
 Vaccine Adjuvants Market | 2026-2036
Vaccine Adjuvants Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Adjuvants Market Intelligence
Project finance for pandemic preparedness infrastructure is reconfiguring competitive entry barriers in vaccine adjuvants. Dynavax Technologies Corporation leverages its toll-like receptor agonist portfolio to anchor biodefense contracts. Croda International Plc sustains lipid adjuvant supply through backward integration into raw material production. GlaxoSmithKline plc dominates the AS01 and AS04 adjuvant platforms through decades of regulatory-validated clinical data.
Vaccine adjuvants are immunological enhancers—typically comprising aluminum salts, oil-in-water emulsions, or saponin derivatives—that amplify antigen-specific immune responses and reduce required antigen doses. The aluminum hydroxide and phosphate formulations remain the most widely administered adjuvant class, though oil emulsions such as MF59 and AS03 deliver superior immunogenicity for influenza and pandemic vaccines. Among mechanism-of-action categories, toll-like receptor agonists represent the fastest-expanding segment as developers target dendritic cell activation for cancer and infectious disease applications. Intramuscular administration occupies the largest volume share, while intranasal delivery is gaining traction for mucosal immunity indications.
FDA's Vaccines and Related Biological Products Advisory Committee shapes adjuvant approval standards through rigorous safety-efficacy balancing, while EMA's Committee for Medicinal Products for Human Use enforces European post-authorization pharmacovigilance for novel immunostimulants. The WHO's prequalification program determines access eligibility for low-income country procurement, directly influencing manufacturer formulation strategies. Stakeholders must monitor how evolving regulatory divergence between FDA and EMA immunogenicity endpoints affects cross-territory development economics.
Market Dynamics
BARDA's pandemic preparedness funding is compressing adjuvant development timelines while concentrating manufacturing capacity in federally supported domestic facilities. This dual pressure of accelerated regulatory pathways and supply security mandates is restructuring competitive entry economics.
Growth Catalysts
- Accelerated Approval Pathways:FDA's Emergency Use Authorization framework for adjuvanted pandemic vaccines reduces clinical trial duration from standard 24-36 month cycles. Developers leverage this compressed timeline for seasonal influenza and emerging pathogen candidates.
- Toll-Like Receptor Agonists:Dendritic cell activation mechanisms expand adjuvant efficacy against intracellular pathogens and tumor antigens. Cancer vaccine developers prioritize these immunostimulants for therapeutic indications.
- Oil-in-Water Emulsion Demand:MF59 and AS03 formulations deliver superior antibody titers for influenza and pandemic preparedness stockpiles. National immunization programs specify these platforms for high-risk population coverage.
Market Restraints
- Squalene Supply Concentration:Shark liver oil and plant-derived squalene sources concentrate extraction capacity in limited coastal processing facilities. Marine conservation restrictions constrain raw material scalability.
- Aluminum Salt Manufacturing Bottlenecks:GMP-compliant aluminum hydroxide and phosphate production requires dedicated precipitation and sterile filtration infrastructure. Qualified supplier bases remain narrow across North America and Europe.
- Immunogenicity-Safety Balancing:EMA's Committee for Medicinal Products for Human Use enforces extended pharmacovigilance periods for novel immunostimulants. Post-authorization safety monitoring extends development cost recovery timelines.
Strategic Opportunities
- Intranasal Delivery Platforms:Mucosal immunity indications for respiratory pathogens create formulation white space beyond intramuscular administration. Developers target IgA-mediated protection for influenza and tuberculosis candidates.
- NIH Partnership Structures:National Institute of Allergy and Infectious Diseases collaborative agreements de-risk early-stage adjuvant characterization. Academic-industry consortia access shared preclinical evaluation infrastructure.
- Lipid Nanoparticle Convergence:mRNA vaccine manufacturing expertise transfers to self-amplifying RNA and protein subunit adjuvant systems. Formulation scientists integrate ionizable lipids with pattern recognition receptor agonists.
Industry Challenges
- Immunological Assay Standardization:Correlates of protection remain undefined for many adjuvant-antigen combinations. Developers face reproducibility gaps between animal models and human immune response prediction.
- Multi-Antigen Formulation Complexity:Combination vaccines require adjuvant compatibility across diverse antigen physicochemical properties. Stability and potency interactions complicate regulatory filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Adjuvants Market |
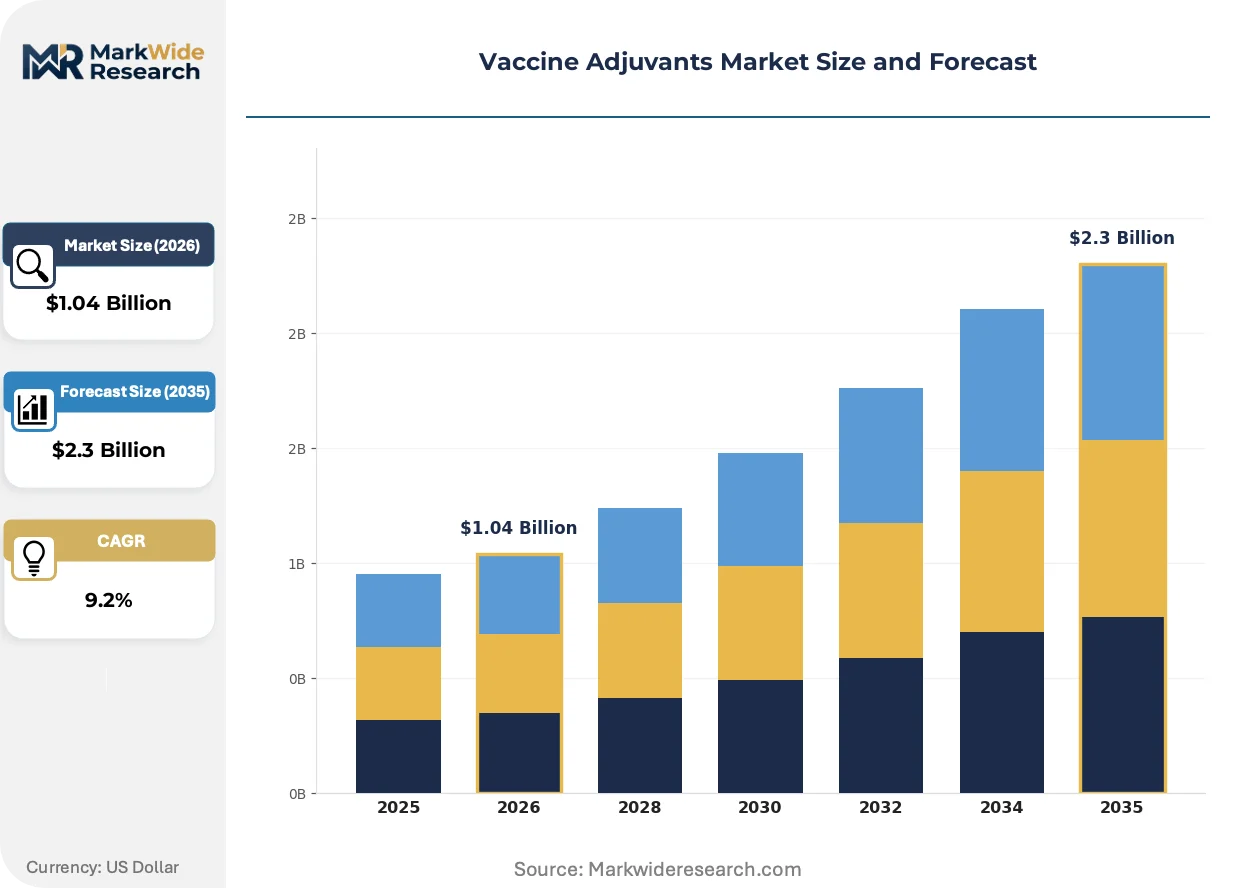
| Market Size in 2026 | $1.04 Billion |
| Market Size in 2035 | $2.3 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alum, Oil Emulsions, MPL, Virosomes Mechanism of Action: Immunostimulatory, Antigen Delivery, Toll-Like Receptor Agonists, Cytokine Modulators Route of Administration: Intramuscular, Subcutaneous, Intralymphatic, Intranasal End User: Pharmaceutical Companies, Research Institutions, Government Agencies, Contract Manufacturing Organizations |
| Companies Covered | GlaxoSmithKline plc, Novavax, Inc., SPI Pharma, Agenus, Inc., CSL Limited, SEPPIC, Dynavax Technologies Corporation, Croda International Plc, Adjuvance Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Adjuvants Market Strategic Shifts & Innovations
Adjuvant platforms are converging with nucleic acid delivery systems and precision immunology, collapsing traditional boundaries between prophylactic and therapeutic applications. This technological fusion demands new manufacturing competencies and regulatory frameworks.
Saponin-based Matrix-M and QS-21 formulations are hybridizing with synthetic lipid bilayers to enhance lymph node targeting while reducing hemolytic toxicity. Cancer immunotherapy developers adopt these hybrid structures for personalized neoantigen vaccines. The structural integration is compressing dose requirements and enabling subunit vaccine efficacy previously achievable only with live-attenuated platforms.
EMA's Clinical Trials Information System mandate for centralized protocol submission is standardizing adjuvant safety documentation across European member states. Manufacturers must harmonize immunogenicity endpoint definitions with FDA guidance to avoid duplicative clinical development. Small and mid-cap developers lacking regulatory affairs scale are consolidating through platform licensing rather than independent filing.
Procurement officers at national immunization programs now require adjuvanted vaccine suppliers to demonstrate pandemic surge capacity through dedicated manufacturing line commitments. Long-term offtake agreements with volume guarantees are displacing spot-market purchasing for seasonal influenza. This contractual shift is most pronounced in United States BARDA-funded stockpile acquisitions and United Kingdom pandemic preparedness frameworks.
Vaccine Adjuvants Market Segmentation
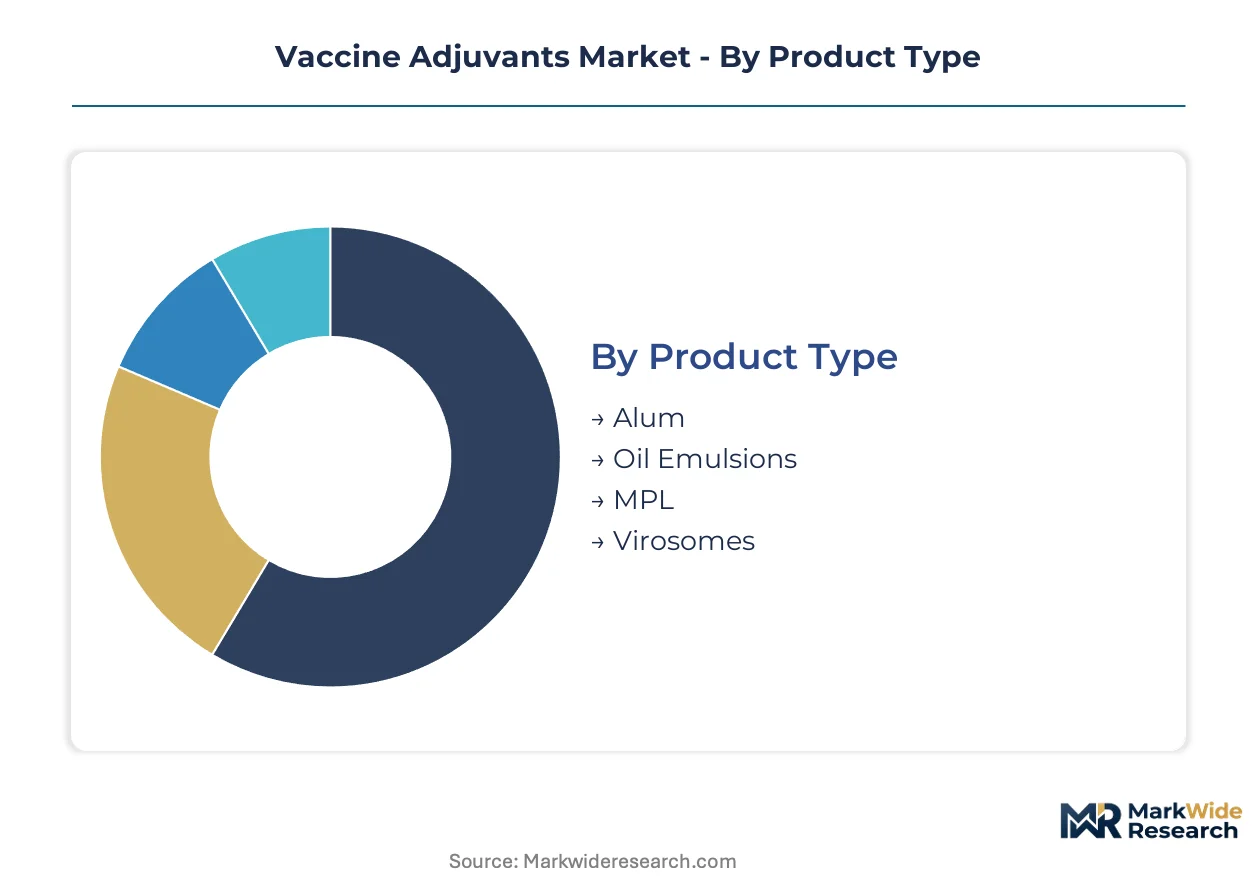
Vaccine adjuvant selection determines immunogenicity profiles, manufacturing scalability, and regulatory pathway complexity. Formulation scientists balance mechanism-of-action specificity against supply chain security when matching adjuvant platforms to target disease indications.
Product Type:
Alum-based formulations anchor high-volume pediatric and seasonal influenza programs, while oil emulsions command premium positioning in pandemic preparedness stockpiles.
- Alum:Aluminum hydroxide and phosphate salts constitute the most administered adjuvant class worldwide. Pediatric immunization programs across the United States, India, and Brazil specify alum-adjuvanted diphtheria-tetanus-pertussis combinations for their cost efficiency and decades of safety documentation. Manufacturing bottlenecks in GMP-compliant precipitation facilities constrain supplier expansion.
- Oil Emulsions:MF59 and AS03 formulations deliver superior antibody titers through squalene-based nanoemulsion structures. BARDA-funded pandemic influenza stockpiles in the United States and United Kingdom procurement frameworks specify these platforms for high-risk population coverage. Squalene extraction from shark liver oil and plant sources concentrates in limited coastal processing facilities.
- MPL:Monophosphoryl lipid A, a detoxified lipopolysaccharide derivative, integrates into combination adjuvants such as AS04 for enhanced TLR4 activation.
- Virosomes:Lipid bilayer vesicles incorporating viral envelope proteins enable targeted antigen presentation and membrane fusion capabilities.
Established volume favors Alum; emerging adoption favors Oil Emulsions.
Mechanism of Action:
Cost tier differentiation separates commodity aluminum salts from precision immunostimulants commanding development-stage premiums.
- Immunostimulatory:Non-specific immune activation through pattern recognition engages complement pathways and inflammatory cascades. Low-cost manufacturing positions these adjuvants for high-volume infectious disease programs in India and Brazil.
- Antigen Delivery:Depot formation and sustained release kinetics concentrate antigen at injection sites for extended dendritic cell sampling. Subunit vaccine developers leverage this mechanism for protein-based candidates requiring prolonged immune exposure.
- Toll-Like Receptor Agonists:Synthetic and natural ligands for TLR3, TLR4, TLR7/8, and TLR9 receptors activate innate immunity with specificity for intracellular pathogens and tumor antigens. Cancer immunotherapy pipelines and biodefense contracts in the United States prioritize these mechanisms.
- Cytokine Modulators:Granulocyte-macrophage colony-stimulating factor and interleukin-12 formulations direct T-cell differentiation and memory formation.
Immunostimulatory platforms dominate current volume; Toll-Like Receptor Agonists are climbing the fastest through oncology and biodefense applications.
Route of Administration:
Application requirements dictate formulation viscosity, particle size distribution, and mucosal adhesion properties across delivery modalities.
- Intramuscular:Deltoid and vastus lateralis injection sites accommodate standard needle lengths and adjuvant volumes up to 1.0 mL. Seasonal influenza and COVID-19 booster campaigns in the United States, United Kingdom, and Japan deploy this route for rapid population coverage.
- Subcutaneous:Reduced vascularity at injection sites prolongs antigen residence time for certain live-attenuated and subunit formulations.
- Intralymphatic:Direct lymph node targeting concentrates adjuvant activity in primary immune induction sites, enabling dose sparing for personalized cancer vaccines.
- Intranasal:Mucosal delivery induces IgA-mediated protection at respiratory pathogen entry points. Developers target this route for influenza and tuberculosis candidates requiring barrier immunity.
Intramuscular administration commands installed infrastructure investment; intranasal platforms gain share fastest through mucosal immunity differentiation.
End User:
Customer type determines procurement scale, regulatory sophistication, and formulation customization requirements.
- Pharmaceutical Companies:GlaxoSmithKline, Sanofi, and Pfizer integrate proprietary adjuvant platforms into vertically controlled vaccine pipelines. These developers maintain dedicated formulation science teams and regulatory affairs infrastructure for multi-territory filings.
- Research Institutions:NIH-funded academic consortia access shared preclinical evaluation infrastructure through National Institute of Allergy and Infectious Diseases partnerships.
- Government Agencies:BARDA, the United Kingdom Vaccine Taskforce, and CEPI fund adjuvant characterization for pandemic preparedness stockpiles.
- Contract Manufacturing Organizations:Lonza, Catalent, and Emergent BioSolutions provide toll formulation and fill-finish services for developers lacking captive adjuvant production.
Pharmaceutical companies concentrate proprietary platform investment; government agencies are expanding fastest through pandemic preparedness funding mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pandemic preparedness agencies and national immunization programs concentrate procurement power across North America, Europe, and Asia-Pacific, with funding flows dictating regional manufacturing capacity distribution.
United States
BARDA stockpile acquisitions and NIH partnership structures anchor adjuvant demand for biodefense and seasonal influenza programs. The FDA's Emergency Use Authorization framework compresses development timelines for pandemic candidates. Manufacturing clusters in Maryland and North Carolina house federally supported formulation facilities serving domestic surge requirements.
Germany
EMA centralized protocol submissions through the Clinical Trials Information System standardize adjuvant safety documentation across member states. The Paul-Ehrlich-Institut enforces batch release testing for novel immunostimulants entering European distribution. Bavaria-based CMO networks provide toll formulation capacity for developers lacking captive production.
United Kingdom
The UK Vaccine Taskforce mandates pandemic surge capacity commitments in long-term offtake agreements with adjuvant suppliers. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for emergency vaccines. Oxfordshire and Cambridge clusters concentrate academic-industry consortia accessing shared preclinical infrastructure.
India
Universal immunization program scale drives alum-based adjuvant consumption for pediatric diphtheria-tetanus-pertussis combinations. CDSCO manufacturing licensing requirements for GMP-compliant precipitation facilities constrain supplier expansion. Hyderabad and Pune house formulation science operations serving domestic vaccine producers and export markets.
Japan
PMDA seasonal influenza strain selection timelines synchronize with oil emulsion adjuvant procurement cycles for high-risk population coverage. METI funding for domestic vaccine self-sufficiency targets lipid adjuvant manufacturing capabilities. Kanto region bioclusters integrate adjuvant characterization with mRNA platform development.
Vaccine Adjuvants Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated pharmaceutical conglomerates dominate proprietary platform pipelines through decades of regulatory-validated clinical data. Mid-cap technology licensors anchor biodefense and oncology applications through mechanism-specific intellectual property. Contract manufacturing organizations capture toll formulation volume from developers lacking captive adjuvant production. Competitive moves concentrate on strategic partnerships for pandemic surge capacity and technology licensing for combination vaccine compatibility.
Within the platform-dominant tier, GlaxoSmithKline plc occupies a position exemplifying regulatory-validated adjuvant system ownership. Among mechanism-focused developers, Dynavax Technologies Corporation and Agenus, Inc. represent archetypes of toll-like receptor agonist specialization for therapeutic and biodefense indications. Croda International Plc anchors supply security through backward integration into lipid raw material production.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novavax, Inc. |
| SPI Pharma |
| Agenus, Inc. |
| CSL Limited |
| SEPPIC |
| Dynavax Technologies Corporation |
| Croda International Plc |
| Adjuvance Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors for squalene and lipid feedstocks transmit cost volatility from marine extraction sites to formulation facilities, concentrating pricing power among backward-integrated suppliers while forcing three-tier price stratification across premium oil emulsions, standard aluminum salts, and economy-grade immunostimulants.
Pricing Analysis
Cost-plus contracts with squalene indexation anchor long-term offtake agreements between BARDA-funded stockpile programs and oil emulsion suppliers. Price differentiation rests on GMP certification tier and volume scale, with pandemic surge commitments commanding premiums over spot-market seasonal orders. Pricing pressure stems from EMA-mandated extended pharmacovigilance periods that elongate cost recovery timelines. Government procurement agencies exhibit highest price sensitivity, while oncology therapeutic developers prioritize mechanism specificity over unit economics.
Supply Chain Analysis
Upstream feedstock concentration for shark liver oil and plant-derived squalene centers on coastal processing facilities in Spain, Japan, and Chile. Aluminum hydroxide precipitation draws from bauxite refining networks in Australia, China, and Brazil. Single-source vulnerability pervades GMP-compliant sterile filtration infrastructure for lipid nanoemulsions. Distribution runs through pharmaceutical company captive networks and toll-manufacturing agreements with CMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BARDA funding cycles and pandemic preparedness stockpile replenishment programs signal a cyclical recovery phase for adjuvant demand, with NIH partnership structures providing countercyclical R&D support.
For Market Incumbents: Build regulatory data moats through decades of FDA-validated immunogenicity endpoints. Anchor pandemic surge capacity commitments in long-term BARDA contracts to forestall CMO competition. Deepen backward integration into squalene extraction to neutralize marine conservation supply risks.
For New Entrants and Emerging Players: Build out intranasal mucosal delivery platforms where formulation white space exceeds incumbent patent density. Target tuberculosis and influenza candidates requiring IgA-mediated protection. Pursue NIH NIAID collaborative agreements to access shared preclinical infrastructure without captive facility investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core adjuvant platform assets. Long-term viability hinges on mechanism-specific intellectual property in toll-like receptor agonists and lipid nanoparticle convergence. Watch FDA Emergency Use Authorization pathway expansion as inflection signal for pandemic preparedness valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | BARDA-funded surge capacity commitments lock in multi-year offtake with domestic facilities. |
| Regulatory Approval Pathway | FDA Emergency Use Authorization compresses development timelines for pandemic candidates. |
| Licensing Agreement | Platform technology access enables combination vaccine compatibility without captive R&D. |
| Backward Integration | In-house squalene extraction secures supply against marine conservation restrictions. |
| Clinical Trial Advancement | NIH NIAID partnerships de-risk early-stage adjuvant characterization through shared infrastructure. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with formulation science directors, regulatory affairs leads at EMA and FDA, BARDA procurement officers, and CMO operations heads informed mechanism-of-action prioritization. Secondary sources include FDA biologics license applications, EMA scientific advice letters, ClinicalTrials.gov adjuvant-arm protocols, and WHO prequalification assessments. Bottom-up segment sizing and top-down macro validation triangulate market estimates.
Calibration against historical BARDA stockpile acquisition data and NIH grant disbursement patterns refines projection accuracy across the analysis window. Segmentation dimensions encompass product type, mechanism of action, route of administration, and end-user archetype. CAGRs derive from spline interpolation between documented contract values and announced capacity expansions. Forecast inputs incorporate pandemic preparedness funding authorization trajectories and EMA-FDA regulatory divergence indices.
Stress conditions across squalene supply disruption, aluminum salt manufacturing bottlenecks, and immunogenicity-safety balancing failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding BARDA funding continuity and EMA pharmacovigilance stability. Cross-checking against WHO prequalification approval rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Progesterone Market