
 Lateral Flow Immunoassay (LFIA) Based Rapid Test Market | 2026-2036
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market Size, Share, and Industry Trends Forecast 2026-2036
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market Foresight
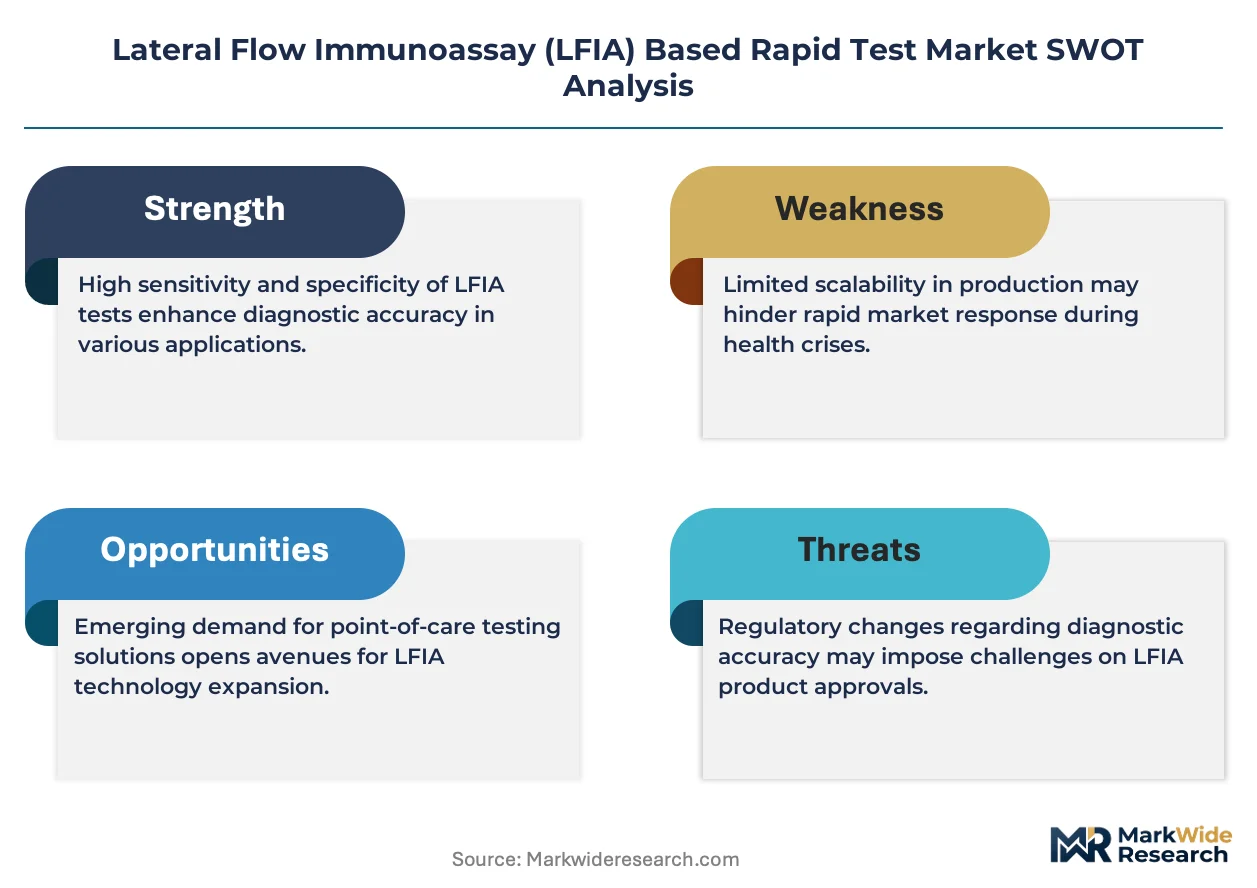
CE marking under the EU In Vitro Diagnostic Regulation is collapsing the window for uncertified manufacturers seeking European market access. Abbott Laboratories leverages its vertically integrated manufacturing footprint to sustain large-scale production of multiplex test strips. bioMérieux S.A. competes through specialized pathogen detection panels that target hospital-acquired infection protocols.
Lateral Flow Immunoassay (LFIA) based rapid tests employ nitrocellulose membranes with antibody-coated nanoparticle conjugates, typically colloidal gold or fluorescent latex, to produce visible signals within 10-20 minutes without instrumentation. These devices serve primary diagnostic screening in decentralized settings where laboratory infrastructure remains limited or turnaround time governs clinical decisions. Qualitative test formats dominate current volume owing to their lower manufacturing complexity and broader regulatory clearances for infectious disease screening. Multiplex configurations represent the fastest-expanding segment as clinicians seek simultaneous detection of multiple analytes from single patient samples.
The FDA governs premarket notification pathways for over-the-counter LFIA devices in the United States, while the EU IVDR imposes stricter clinical evidence requirements for Class C and D diagnostic products. Health Canada and the PMDA in Japan maintain parallel but distinct performance validation standards that shape regional product registration strategies. Stakeholders must monitor evolving post-market surveillance obligations as regulators tighten traceability requirements for point-of-care diagnostics.
Market Dynamics
Point-of-care testing expansion is compressing turnaround requirements and forcing manufacturers to eliminate instrument dependencies from diagnostic workflows. This structural shift privileges nitrocellulose membrane platforms that deliver visual results without laboratory infrastructure.
Growth Catalysts
- FDA OTC Pathway Acceleration:The FDA's streamlined premarket notification framework for over-the-counter diagnostic devices shortens commercialization timelines for instrument-free assay formats targeting decentralized health delivery networks.
- Multiplex Configuration Demand:Hospital-acquired infection protocols are driving simultaneous detection of multiple analytes from single patient samples, expanding panel complexity beyond traditional qualitative screening.
- Colloidal Gold Conjugate Optimization:Advances in nanoparticle surface chemistry are improving signal intensity and stability, reducing manufacturing variability for antibody-coated detection systems.
Market Restraints
- EU IVDR Clinical Evidence Burden:The European Union's In Vitro Diagnostic Regulation imposes stringent performance validation requirements for Class C and D products, collapsing market access windows for uncertified manufacturers.
- Nitrocellulose Membrane Supply Concentration:A limited supplier base for high-purity membrane substrates creates input vulnerability, with production concentrated among specialized chemical manufacturers.
- Fluorescent Latex Substitution Pressure:Quantum dot and upconverting phosphor technologies threaten colloidal gold dominance in high-sensitivity applications requiring quantitative readout capabilities.
Strategic Opportunities
- Home-Based Infectious Disease Monitoring:United States consumers are adopting self-testing for respiratory and sexually transmitted infections, creating direct-to-consumer distribution channels bypassing traditional hospital procurement.
- Digital Reader Convergence:Smartphone camera-based quantification algorithms are enabling semi-quantitative lateral flow results without dedicated instrumentation, bridging visual screening and laboratory precision.
- Japanese PMDA Streamlined Review:Japan's Pharmaceuticals and Medical Devices Agency offers accelerated pathways for designated orphan diagnostics, reducing registration friction for novel pathogen panels.
Industry Challenges
- Bioanalytical Talent Scarcity:Antibody conjugation chemistry and lateral flow assay development require specialized immunochemistry expertise that outpaces current training pipeline output.
- Post-Market Surveillance Traceability:Regulators are tightening lot-tracking requirements for point-of-care diagnostics, forcing manufacturers to rebuild quality management systems around unique device identification standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lateral Flow Immunoassay (LFIA) Based Rapid Test Market |
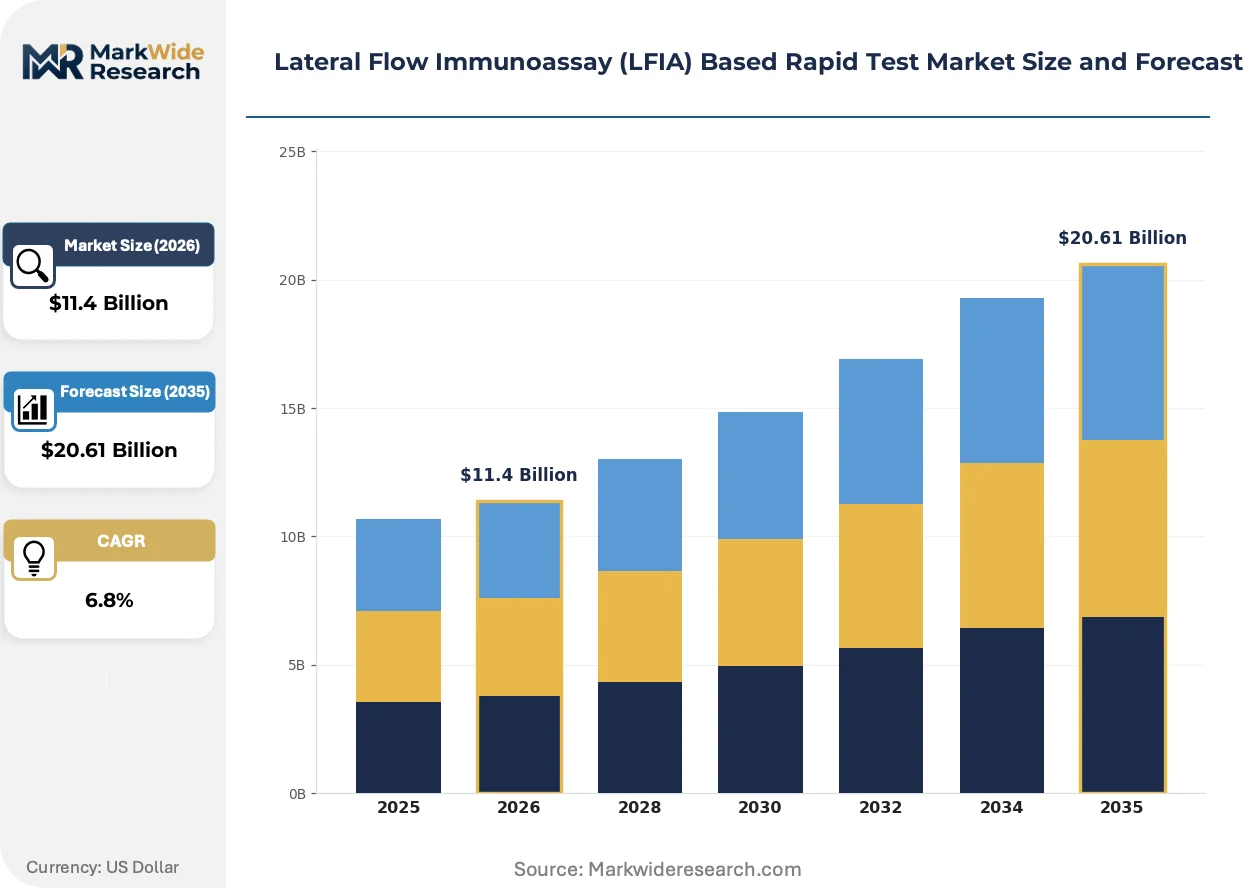
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Qualitative, Quantitative, Semi-Quantitative, Multiplex End User: Laboratories, Hospitals, Clinics, Home Care Application: Disease Diagnosis, Pregnancy Testing, Drug Screening, Food Safety Technology: Colloidal Gold, Lateral Flow, Magnetic Nanoparticles, Silica Nanoparticles |
| Companies Covered | Abbott Laboratories, F Hoffmann-La Roche AG, Danaher Corporation, Thermo Fisher Scientific, Siemens Healthineers AG, Hologic, Inc, QIAGEN N.V., bioMérieux S.A., QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market Shifts & Advancements
Digital integration and multiplexing capabilities are redefining performance expectations for rapid diagnostic platforms. Manufacturers must now engineer connectivity and panel density into membrane-based formats originally designed for single-analyte visual screening.
Fluorescent latex microspheres with europium chelate labels are fragmenting the high-sensitivity segment previously reserved for laboratory analyzers. Emergency departments in tertiary care centers are adopting these substrates for quantitative cardiac marker detection. The technology is fragmenting competitive positioning by enabling time-resolved fluorescence on instrument-free platforms, compressing the performance gap between rapid tests and central laboratory immunoassays.
REACH substance restrictions are forcing reformulation of plastic housing materials and adhesive components used in cassette manufacturing. European manufacturers face supply chain reconfiguration as phthalate and brominated flame retardant limits tighten. Class C infectious disease panels are experiencing delayed CE marking renewals as notified bodies apply enhanced scrutiny to chemical safety documentation under the EU Green Deal implementation timeline.
Hospital procurement consortia are consolidating purchasing authority for point-of-care diagnostics into centralized formulary committees. Individual clinic autonomy is yielding to system-wide standardization mandates that favor large-volume contract holders. This concentration is most visible in United States integrated delivery networks, where standardized test menus are displacing site-specific preference decisions across multi-hospital systems.
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market Segmentation
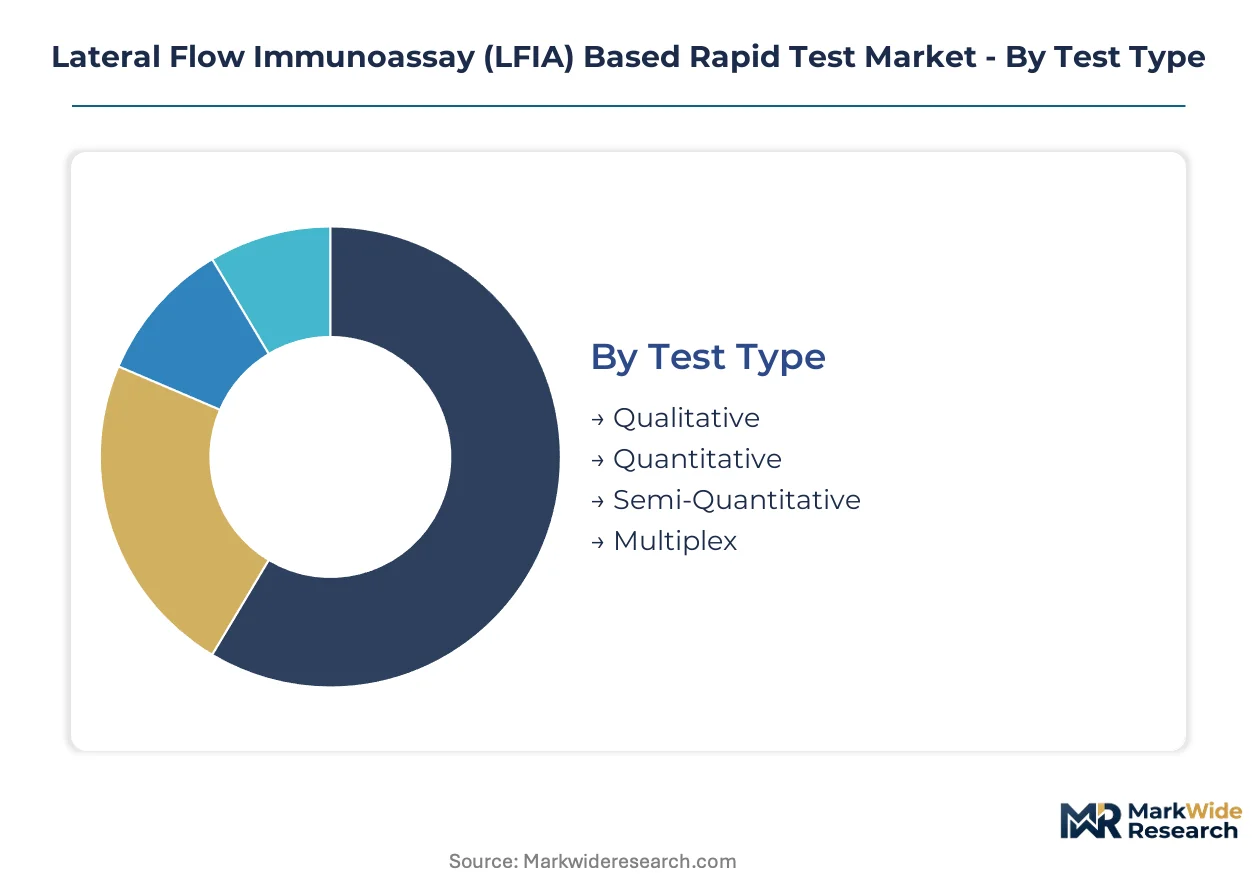
Segmentation in the LFIA rapid test market reveals divergent commercial strategies across test complexity, care setting, and detection chemistry. Manufacturers must align product portfolios with specific regulatory pathways and procurement structures that vary sharply by segment.
Test Type:
Qualitative formats dominate domestic production in the United States and European Union, while quantitative and multiplex platforms drive export-led revenue from specialized manufacturers in Japan and South Korea.
- Qualitative:These binary yes/no detection formats employ colloidal gold conjugates on nitrocellulose membranes to deliver visual results within 10-15 minutes. Demand concentrates in United States retail pharmacy chains and developing country public health programs where instrument-free operation remains mandatory. FDA OTC clearances for infectious disease screening sustain volume leadership despite margin compression.
- Multiplex:Simultaneous multi-analyte detection from single patient samples requires sophisticated membrane patterning and antibody spotting precision. Hospital-acquired infection protocols in German and French tertiary centers are driving adoption, with procurement committees favoring panels detecting 3-5 pathogens simultaneously. The steepest expansion trajectory runs through respiratory and sexually transmitted infection combinations.
- Quantitative:Numeric readout capabilities using fluorescent or colorimetric intensity measurement serve cardiac marker and hormone monitoring applications.
- Semi-Quantitative:Threshold-based result bands provide approximate concentration ranges without full quantification, bridging visual screening and laboratory precision.
Qualitative tests command the established base. The steepest expansion runs through Multiplex configurations.
End User:
Cost tier stratification separates premium laboratory systems from economy home-care formats, with mid-tier hospital and clinic procurement representing the contested middle ground.
- Hospitals:Point-of-care testing expansion in United States integrated delivery networks is consolidating purchasing authority into centralized formulary committees. Emergency departments and intensive care units demand rapid turnaround for sepsis and cardiac marker protocols, with procurement favoring vendors offering standardized test menus across multi-hospital systems.
- Home Care:Direct-to-consumer distribution bypasses traditional healthcare procurement entirely, with United States consumers adopting self-testing for respiratory infections and fertility monitoring. Amazon and pharmacy retail channels are displacing clinical laboratory intermediaries, though FDA OTC authorization remains the gatekeeping hurdle.
- Laboratories:Centralized testing facilities with full analyzer infrastructure represent declining share as specimen transport delays lose competitive standing.
- Clinics:Physician office laboratories balance rapid turnaround requirements against capital constraints, favoring visual-read formats over instrument-dependent systems.
Hospitals anchor the premium tier. Home Care is gaining share fastest through channel disintermediation.
Application:
Application segmentation tracks divergent regulatory maturity, with pregnancy and infectious disease testing holding established clearances while food safety applications face evolving validation requirements.
- Disease Diagnosis:Respiratory pathogen panels, sexually transmitted infection screens, and tropical disease detection for malaria and dengue constitute the core revenue base. United States hospital procurement and PEPFAR-funded programs in sub-Saharan Africa represent dual demand poles with contrasting price sensitivity.
- Food Safety:Pathogen detection for Salmonella, Listeria, and E. coli in agricultural and processing environments requires environmental sampling protocols distinct from clinical matrices. European Union regulatory enforcement under RASFF (Rapid Alert System for Food and Feed) is accelerating industrial adoption, though method validation against ISO standards prolongs commercialization timelines.
- Pregnancy Testing:Mature commodity segment with consolidated manufacturing and minimal technology differentiation.
- Drug Screening:Workplace and forensic applications face stringent chain-of-custody requirements that limit format flexibility.
Disease Diagnosis commands the established base. Food Safety is climbing the fastest through regulatory enforcement expansion.
Technology:
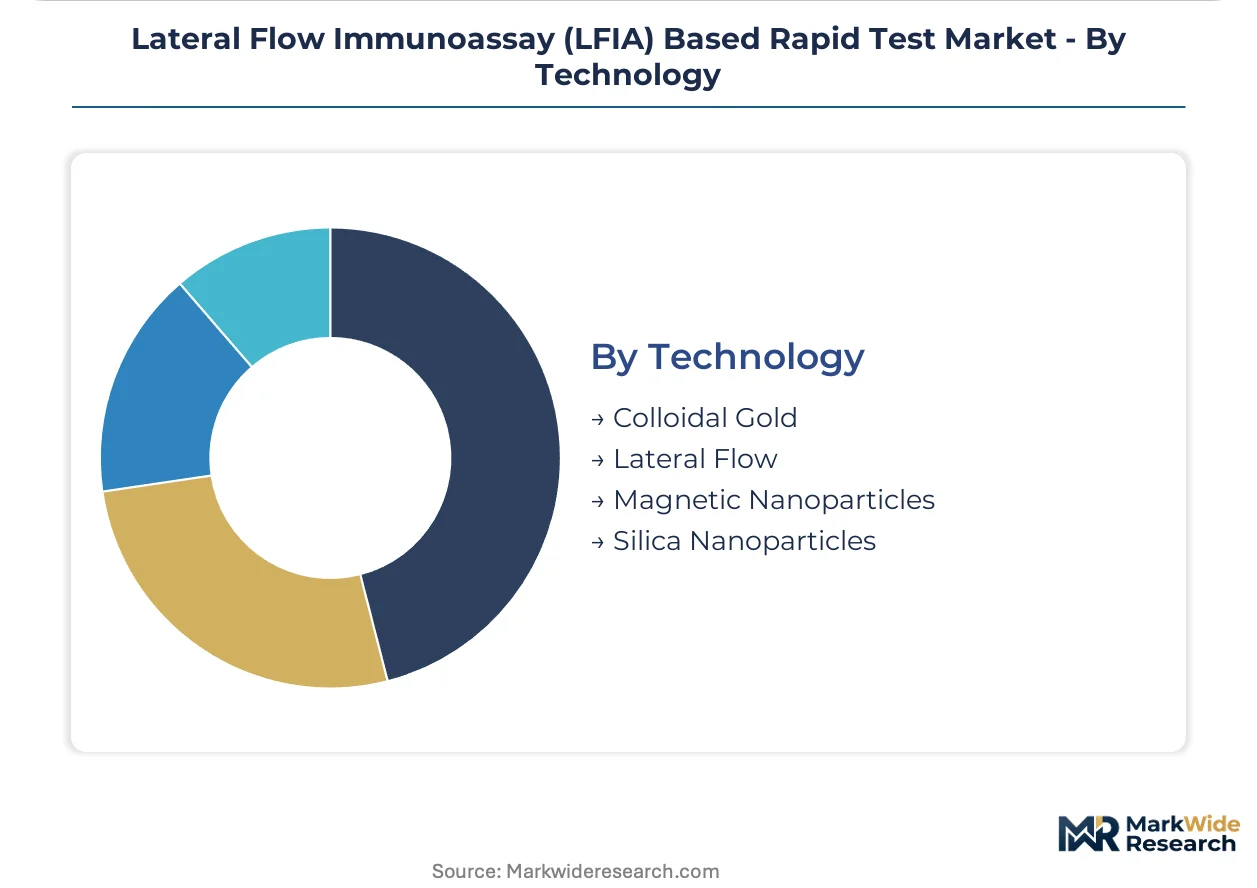
Technology segmentation reflects supply concentration in nanoparticle manufacturing, with colloidal gold production dominated by specialized chemical suppliers while alternative substrates remain niche.
- Colloidal Gold:Antibody-coated gold nanoparticles remain the standard detection conjugate for visual-read assays, with surface chemistry advances improving signal stability and reducing lot-to-lot variability. Manufacturing scale and regulatory familiarity sustain dominance across United States and European volume applications despite sensitivity limitations.
- Magnetic Nanoparticles:Iron oxide cores with functionalized surfaces enable separation-based detection formats with reduced matrix interference. Japanese and South Korean manufacturers are pioneering integration with smartphone reader systems for quantitative applications, targeting cardiac marker and hormone monitoring where precision requirements exceed colloidal gold capabilities.
- Lateral Flow:The foundational membrane-based platform architecture itself, distinct from specific detection chemistry.
- Silica Nanoparticles:Emerging substrate for fluorescent and Raman signal enhancement in research-stage applications.
Colloidal Gold commands the established base. Magnetic Nanoparticles are gaining share fastest through digital reader convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia in the United States command premium pricing for instrument-free assay formats, while European notified bodies under IVDR extend review timelines for Class C infectious disease panels. Japanese regulators accelerate orphan diagnostic pathways, and Chinese domestic manufacturers scale colloidal gold production for tropical disease export programs.
United States
FDA OTC authorization for respiratory and sexually transmitted infection self-tests drives direct-to-consumer channel expansion through Amazon and retail pharmacy networks. The agency's streamlined premarket notification framework compresses commercialization timelines for decentralized health delivery networks. Boston and San Diego biotech clusters concentrate multiplex assay development for hospital-acquired infection protocols.
Germany
Hospital formulary committees in tertiary care centers standardize procurement for sepsis and cardiac marker rapid testing across multi-hospital systems. ECHA REACH substance restrictions force reformulation of plastic housing materials and adhesive components in cassette manufacturing. The Rhine-Ruhr industrial corridor hosts specialized chemical suppliers for high-purity nitrocellulose membrane substrates.
Japan
PMDA accelerated review pathways for designated orphan diagnostics reduce registration friction for novel pathogen panels targeting emerging infectious diseases. METI industrial policy supports smartphone camera-based quantification algorithm development for semi-quantitative lateral flow results. The Kansai region around Osaka anchors magnetic nanoparticle manufacturing for digital reader convergence applications.
China
NMPA domestic device approval prioritizes malaria and dengue rapid tests for Belt and Road Initiative export programs to sub-Saharan Africa and Southeast Asia. SAMR quality system inspections tighten traceability requirements for point-of-care diagnostic manufacturers. The Yangtze River Delta manufacturing belt concentrates colloidal gold nanoparticle production and antibody conjugation chemistry capacity.
India
CDSCO streamlined medical device registration under the 2017 Rules attracts multinational contract manufacturing for tropical disease and fertility rapid tests. The PLI scheme for pharmaceuticals and medical devices incentivizes domestic production of nitrocellulose membranes and diagnostic components. Hyderabad and Bengaluru clusters specialize in bioanalytical talent pools for lateral flow assay development and regulatory consulting services.
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market Competitive Landscape
Player mix skews toward diversified diagnostic conglomerates with vertically integrated manufacturing footprints and specialized mid-cap assay developers with pathogen-specific expertise. Market structure concentrates procurement authority among hospital systems and integrated delivery networks that favor standardized test menus. Two strategic archetypes dominate: scale-driven manufacturers with global distribution infrastructure and technology specialists with proprietary nanoparticle surface chemistry. Competitive moves center on multiplex panel expansion and regulatory pathway optimization for OTC authorization.
Among diversified diagnostic conglomerates, Abbott Laboratories and Danaher Corporation occupy positions exemplifying scale-driven manufacturing and life sciences platform integration. F Hoffmann-La Roche AG represents the premium-tier archetype with specialized clinical chemistry and molecular diagnostic capabilities. bioMérieux S.A. sits within the hospital-acquired infection specialization vector, anchoring expertise in pathogen detection panels for European tertiary care protocols.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F Hoffmann-La Roche AG |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Siemens Healthineers AG |
| Hologic, Inc |
| QIAGEN N.V. |
| bioMérieux S.A. |
| QuidelOrtho Corporation |
| Others |
Supply & Pricing Matrix
Colloidal gold nanoparticle substitution by fluorescent latex microspheres is simultaneously shifting supply geography toward Japanese and South Korean specialty chemical manufacturers and compressing pricing premiums for high-sensitivity cardiac marker applications. This chemistry transition fragments established procurement patterns as hospitals demand quantitative readouts without accepting laboratory analyzer cost structures.
Pricing Analysis
Cost-plus contracts with nitrocellulose membrane suppliers indexed to cellulose pulp futures dominate raw material procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from CE-marked qualitative strips and uncertified developing-market formats. Cost compression in economy tiers is intensifying because Chinese manufacturers are scaling colloidal gold production for Belt and Road export programs. Public health procurement in sub-Saharan Africa exhibits the highest price sensitivity, while United States integrated delivery networks absorb premium pricing for standardized test menus.
Supply Chain Analysis
Inventory lead times for high-purity nitrocellulose membranes have extended from specialized chemical manufacturers in Germany and the United States, creating production scheduling vulnerability for assay developers. The supply chain draws from antibody conjugation chemistry capacity concentrated in China, Japan, and India, with magnetic nanoparticle manufacturing clustering around Osaka. Single-source vulnerability concentrates in membrane substrate supply, where three specialized producers serve the global market. Distribution runs through hospital procurement consortia and direct-to-consumer pharmacy retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LFIA rapid test market sits in a post-pandemic normalization cycle where inventory destocking is giving way to reordering as hospital point-of-care testing programs expand. This cyclical recovery favors manufacturers with established regulatory clearances and membrane supply security.
For Market Incumbents: Compound defensive positioning through backward integration into nitrocellulose membrane manufacturing and accelerated multiplex panel FDA submissions before IVDR compliance windows narrow. Quantum dot substitution threats from South Korean entrants demand investment in fluorescent latex surface chemistry R&D. Captive supply of membrane substrates represents the critical lever for margin defense against commodity strip producers.
For New Entrants and Emerging Players: Digital reader algorithm development for smartphone-based semi-quantification offers entry where incumbents under-serve home-care fertility and cardiac monitoring segments. Japan's orphan diagnostic pathway provides the most penetrable regulatory geography for novel pathogen panels. Go-to-market execution should prioritize Amazon direct-to-consumer distribution bypassing hospital procurement gatekeepers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-caps with proprietary nanoparticle chemistry over pure-play distributors. Long-term viability hinges on regulatory clearance depth rather than manufacturing scale alone. Acquisition targets should demonstrate CE marking progress under IVDR and FDA 510(k) submission timelines. The signal to watch is notified body appointment delays for Class C infectious disease panels.
| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Class C Certification | CE marking under stricter clinical evidence requirements secures European hospital procurement access. |
| FDA OTC Pathway Submission | Over-the-counter authorization unlocks direct-to-consumer respiratory and STI test distribution. |
| Multiplex Panel Expansion | Simultaneous pathogen detection addresses hospital-acquired infection protocol requirements. |
| Digital Reader Integration | Smartphone camera quantification bridges visual screening and laboratory precision. |
| Membrane Supply Security | Backward integration into nitrocellulose manufacturing mitigates single-source raw material risk. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads at diagnostic manufacturers and secondary analysis of FDA 510(k) filings and EMA IVDR notified body guidance anchors the qualitative findings. The research incorporated perspectives from hospital procurement managers, GPO contracts directors, biomedical engineers in point-of-care settings, and nitrocellulose membrane suppliers. Secondary sources included CDSCO device registration databases, PMDA orphan diagnostic designation records, SAMR quality system inspection reports, and customs trade data for diagnostic component flows. Bottom-up test volume modeling triangulated against top-down market value estimates.
Sensitivity analysis around membrane substrate pricing and regulatory approval timeline assumptions tested forecast robustness across the projection horizon. The analytical framework modeled segmentation dimensions including test type complexity, end-user procurement structure, detection chemistry platform, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating infectious disease surveillance data and hospital point-of-care expansion rates as industry-specific inputs.
Underlying assumptions cover stable nitrocellulose supply availability and FDA OTC pathway continuity, with deviation risk concentrated in EU IVDR notified body capacity constraints and REACH substance restriction enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Imaging Biomarkers Market