
 Mammalian Transient Protein Expression Market | 2026-2036
Mammalian Transient Protein Expression Market Size, Share, and Industry Trends Forecast 2026-2036
Mammalian Transient Protein Expression Market Foresight
The EU Green Deal's biomanufacturing sustainability targets is realigning procurement criteria for mammalian expression systems across European pharmaceutical buyers. Thermo Fisher Scientific leverages its integrated reagent-to-bioreactor portfolio to sustain service contracts with top-ten biopharma accounts. Lonza Group anchors high-complexity custom cell-line projects through its Portsmouth, UK facility. Merck KGaA competes on synthetic media formulations that reduce fetal bovine serum dependence in transient workflows.
Mammalian transient protein expression deploys plasmid DNA vectors transfected into suspension-adapted CHO or HEK293 cells to produce recombinant proteins within days rather than weeks required for stable pools. Typical yields reach milligram-to-gram quantities per liter depending on vector design, transfection reagent chemistry, and harvest timing, serving accelerated antibody discovery and preclinical material supply. Cell lines and transfection reagents capture divergent margin structures, with engineered CHO variants commanding premium positioning while reagent volumes scale faster across contract manufacturing organizations. Antibody production and vaccine development applications dominate current throughput, though biotherapeutics represents the deepest value pool as developers advance transient-derived candidates into regulated toxicology studies.
FDA's Chemistry, Manufacturing, and Controls guidance and EMA's Good Manufacturing Practice Annex 2 revisions on biological active substances both elevate documentation burdens for transient-derived clinical materials. ISO 10993 biocompatibility testing standards and ICH Q5D quality guidelines on cell substrates further constrain supplier qualification timelines. Stakeholders must weigh platform standardization against bespoke vector engineering as regulatory agencies tighten traceability requirements for gene-of-origin documentation.
Market Dynamics
Biotherapeutics developers compress antibody discovery timelines by deploying transient expression platforms that bypass stable cell-line generation, creating procurement pressure on contract manufacturing organizations to standardize vector-to-harvest workflows.
Growth Catalysts
- FDA Chemistry, Manufacturing, and Controls guidance:Elevated documentation requirements for clinical-grade transient materials push developers toward validated platform providers with established regulatory files.
- CHO suspension adaptation protocols:Engineered variants achieving gram-per-liter yields for complex glycoproteins expand addressable therapeutic classes beyond standard immunoglobulins.
- German pharmaceutical clusters:Dense contract research networks around Munich and Heidelberg concentrate demand for rapid-turnaround preclinical material supply.
Market Restraints
- Fetal bovine serum price volatility:Synthetic media formulations reduce but do not eliminate serum dependence, exposing cost structures to agricultural commodity swings.
- Plasmid DNA supply concentration:Specialized GMP-grade plasmid manufacturing concentrates among North American and European suppliers, creating single-source vulnerabilities for vector backbones.
- Transfection efficiency ceilings:Physical and chemical delivery methods face hard limits scaling beyond 10^7 cells per batch without electroporation infrastructure investments.
Strategic Opportunities
- Indian biosimilar developers:CDSCO accelerated approval pathways for reference biologics create demand for rapid transient-derived toxicology batches ahead of stable pool establishment.
- Cell-free protein synthesis convergence:Hybrid workflows combining CHO lysates with purified translation machinery address applications requiring non-natural amino acid incorporation.
- EU Green Deal biomanufacturing targets:Sustainability procurement criteria favor expression systems with reduced water and energy footprints per gram of protein output.
Industry Challenges
- Vector engineering talent scarcity:Synthetic biology expertise for codon-optimized, epigenetically silencing-resistant construct design outpaces academic training pipeline output.
- ICH Q5D cell substrate qualification:Documentation of gene-of-origin traceability for transient-derived clinical materials extends supplier qualification timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mammalian Transient Protein Expression Market |
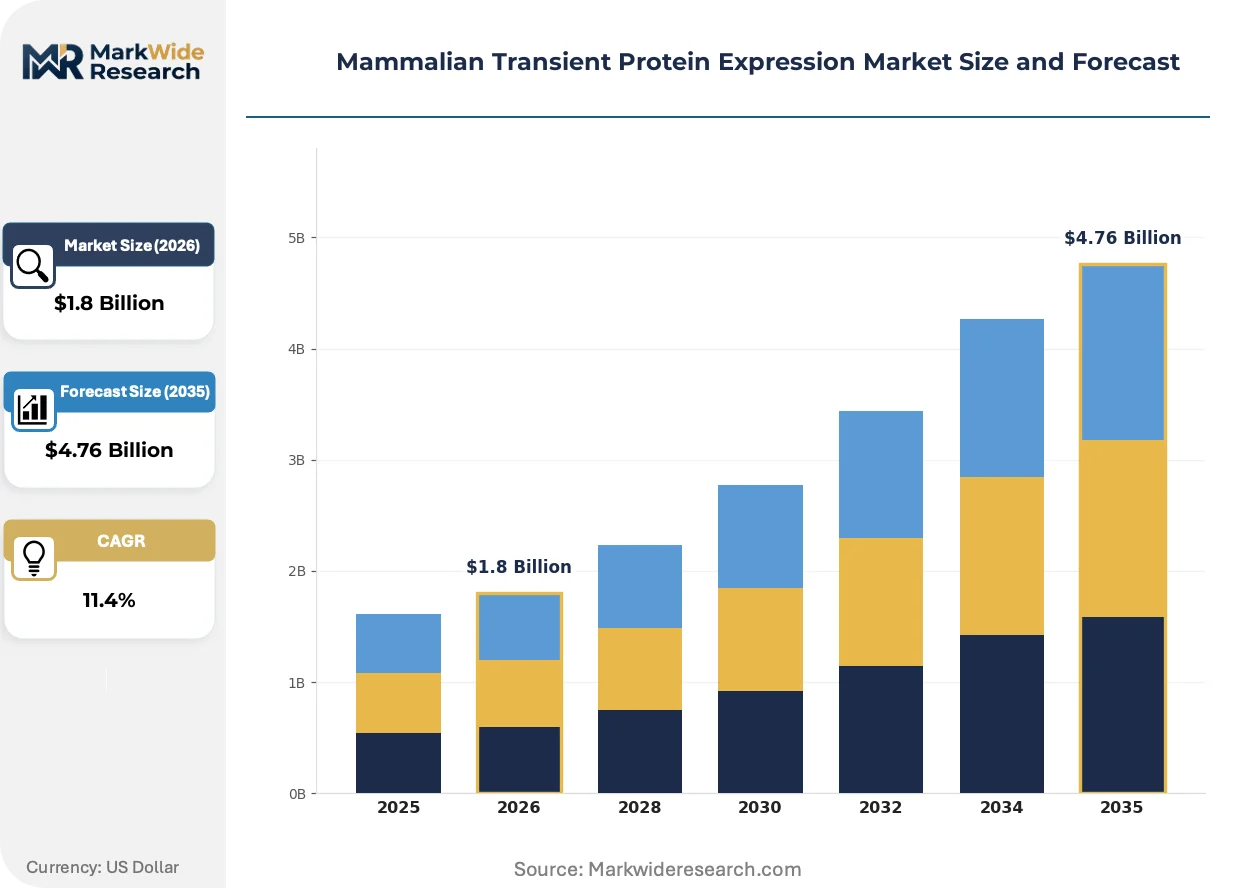
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmids, Vectors, Cell Lines, Transfection Reagents Application: Biotherapeutics, Antibody Production, Vaccine Development, Protein Characterization End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Delivery Mode: Transient Transfection, Viral Transduction, Electroporation, Magnetofection |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Lonza Group, Promega Corporation, Agilent Technologies, Bio-Rad Laboratories, QIAGEN, Takara Bio, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mammalian Transient Protein Expression Market Shifts & Advancements
Expression platform providers reconfigure hardware-software bundles to capture value from automated bioreactor control systems rather than commoditized transfection reagents alone.
Machine learning-guided vector design is converging with high-throughput transient screening workflows. Biotherapeutics developers at mid-sized biotechnology firms deploy generative models predicting untranslated region configurations that boost mRNA stability. This compression of design-test cycles is converging with traditional empirical screening to reduce lead optimization timelines from months to weeks.
EMA Good Manufacturing Practice Annex 2 revisions on biological active substances impose batch-record granularity requirements previously reserved for stable cell-line processes. Contract development and manufacturing organizations revalidate transient platforms under these tightened standards. European biopharma sponsors absorb 15-20% higher documentation costs for toxicology-enabling batches.
Biopharma procurement teams unbundle after-sales technical support from reagent supply contracts, purchasing platform expertise through separate consulting engagements. Large biotechnology firms in the United States negotiate service-level agreements distinct from consumable pricing. This disaggregation pressures reagent suppliers to demonstrate standalone value through analytical method transfer capabilities.
Mammalian Transient Protein Expression Market Segmentation
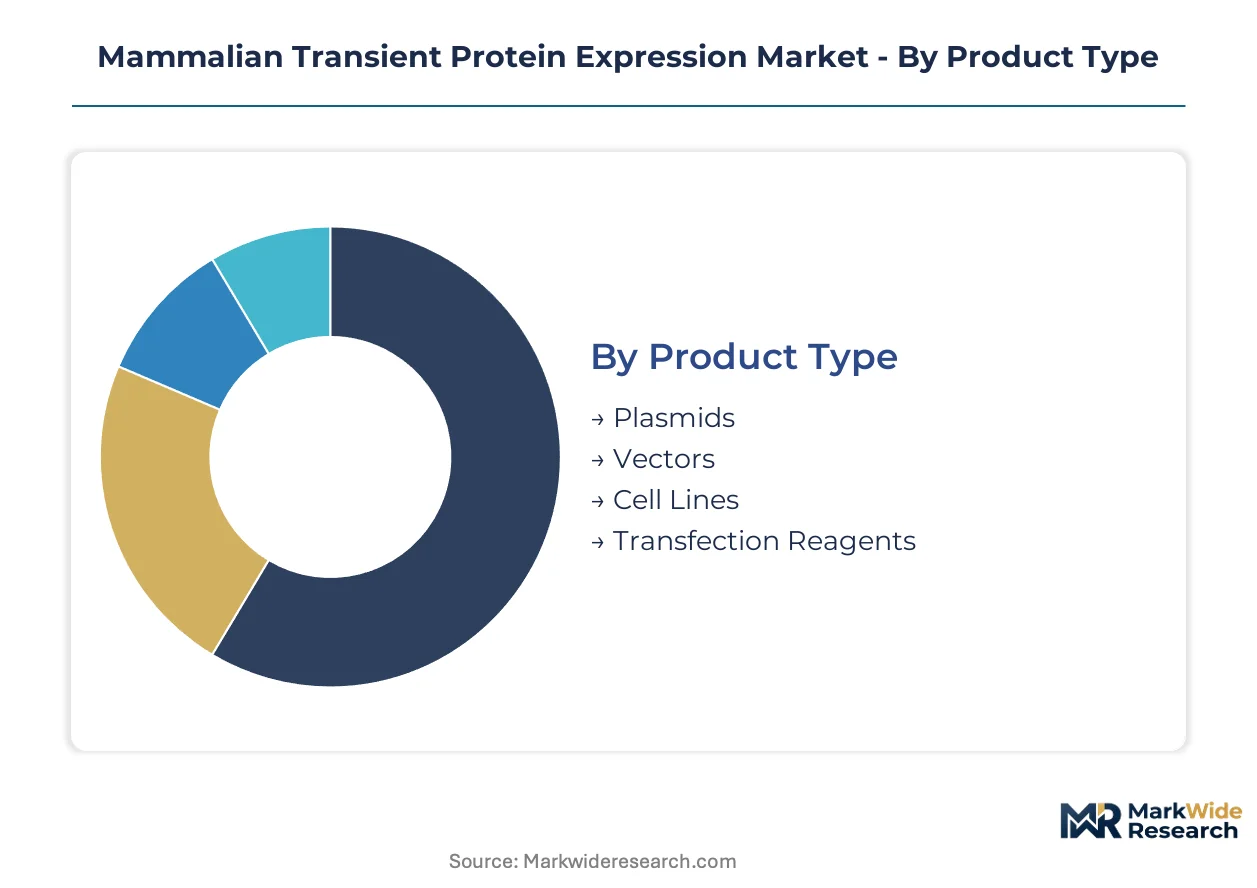
Segmentation in mammalian transient protein expression reveals divergent margin structures and procurement patterns across technology tiers. Product architecture and delivery modality determine workflow standardization versus bespoke engineering trade-offs.
Product Type:
Engineered biological components and chemical reagents constitute distinct technology layers with asymmetric scalability profiles.
- Cell Lines:Suspension-adapted CHO and HEK293 variants enable gram-per-liter yields for complex glycoproteins. Pharmaceutical sponsors in the United States and Germany pay premium positioning fees for epigenetically stabilized lineages with documented traceability files.
- Transfection Reagents:Lipid nanoparticle and polyethylenimine formulations dominate high-throughput screening workflows. Contract manufacturing organizations scale reagent volumes fastest across multi-site antibody discovery programs, though margin compression intensifies above 10^7 cell batch thresholds.
- Plasmids:GMP-grade vector backbones with codon-optimized gene cassettes serve toxicology-enabling production runs.
- Vectors:Episomal and integrating designs accommodate transient versus stable workflow transitions.
Cell lines lead on scale; transfection reagents lead on momentum.
Application:
Therapeutic class requirements reshape platform configuration priorities across development stages.
- Biotherapeutics:Regulated toxicology studies demand ICH Q5D-compliant cell substrate documentation. FDA Chemistry, Manufacturing, and Controls guidance elevates batch-record granularity, extending supplier qualification timelines by 6-12 months for clinical-grade materials.
- Antibody Production:Discovery-stage screening compresses vector-to-harvest cycles to days rather than weeks. Biotechnology firms in German pharmaceutical clusters around Munich and Heidelberg concentrate procurement for rapid-turnaround preclinical supply.
- Vaccine Development:Pandemic response infrastructure investments accelerated platform validation for antigen expression.
- Protein Characterization:Structural biology applications prioritize yield consistency over absolute titer.
Antibody production leads on scale; biotherapeutics leads on momentum.
End User:
Organizational scale and regulatory exposure create divergent sourcing strategies for platform components.
- Pharmaceutical Companies:Top-ten biopharma accounts negotiate integrated reagent-to-bioreactor service contracts with platform providers. Unbundling of technical support into separate consulting engagements pressures standalone reagent suppliers to demonstrate analytical method transfer capabilities.
- Contract Manufacturing Organizations:CDMOs absorb 15-20% higher documentation costs under EMA Good Manufacturing Practice Annex 2 revisions. European biopharma sponsors drive revalidation of transient platforms under tightened batch-record standards.
- Biotechnology Firms:Mid-sized developers deploy machine learning-guided vector design to compress lead optimization timelines.
- Research Institutions:Academic users prioritize cost efficiency over regulatory-grade documentation.
Contract manufacturing organizations lead on scale; biotechnology firms lead on momentum.
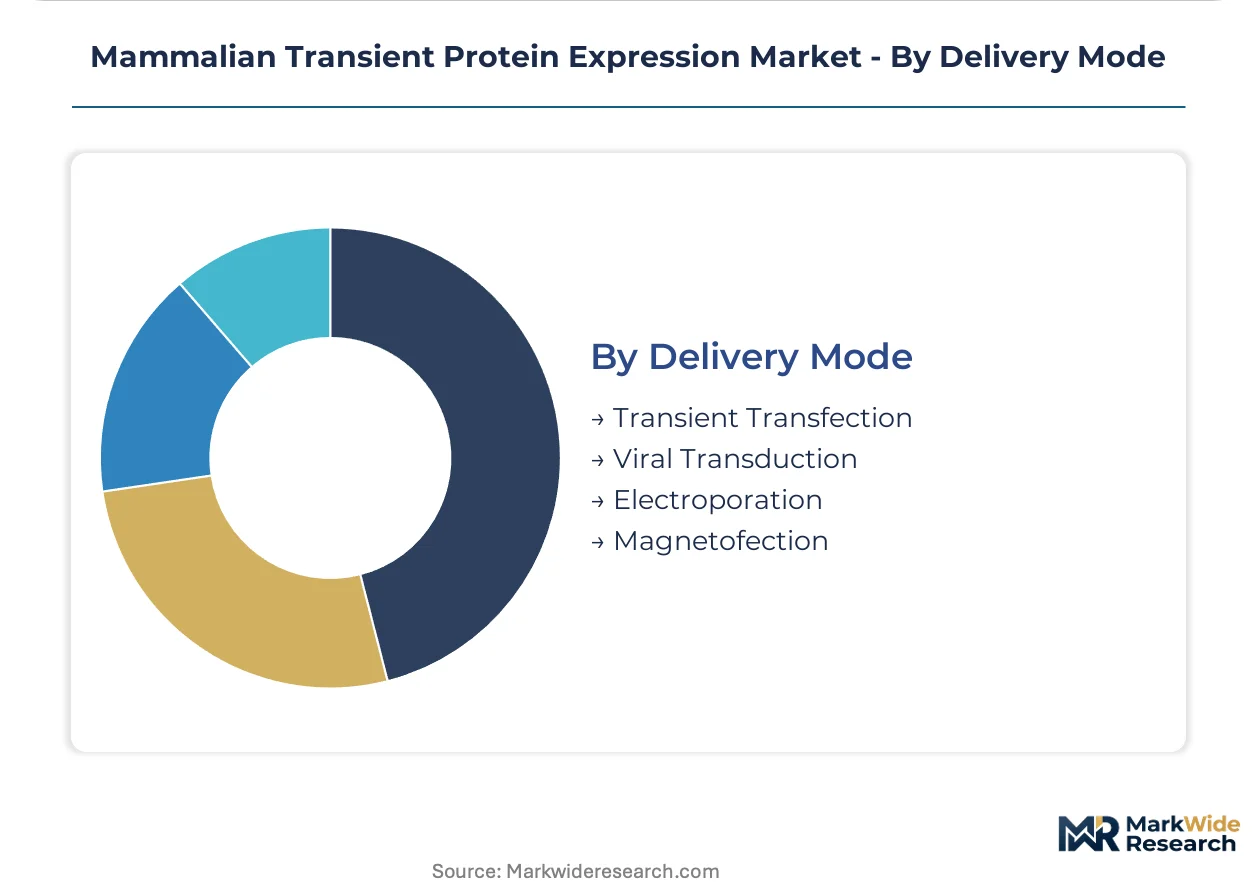
Delivery Mode:
Physical and chemical transfection methods face hard scalability ceilings that reshape infrastructure investment decisions.
- Transient Transfection:Plasmid DNA delivery into suspension cultures remains the workhorse for milligram-to-gram production. Chemical methods face efficiency limits beyond 10^7 cells per batch without electroporation infrastructure investments.
- Electroporation:High-voltage pulse delivery achieves superior transfection efficiency for difficult-to-transfect lineages. Capital intensity restricts deployment to central facilities serving multiple discovery programs.
- Viral Transduction:Lentiviral and adenoviral vectors enable stable integration for extended expression windows.
- Magnetofection:Magnetic particle-assisted delivery addresses specific niche applications requiring spatial targeting.
Transient transfection leads on scale; electroporation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vector engineering talent concentrates in the United States and Germany, anchoring platform development and contract manufacturing capacity for mammalian transient protein expression systems.
United States
Top-ten biopharma accounts drive integrated reagent-to-bioreactor procurement through service-level agreements negotiated separately from consumable pricing. FDA Chemistry, Manufacturing, and Controls guidance elevates documentation burdens for clinical-grade transient materials, pushing sponsors toward validated platform providers. Greater Boston and San Francisco Bay Area clusters concentrate machine learning-guided vector design capabilities at mid-sized biotechnology firms.
Germany
Pharmaceutical sponsors in Munich and Heidelberg pharmaceutical clusters concentrate demand for rapid-turnaround preclinical material supply. EMA Good Manufacturing Practice Annex 2 revisions impose batch-record granularity requirements previously reserved for stable cell-line processes, extending supplier qualification timelines. The Portsmouth facility anchors high-complexity custom cell-line projects serving European biotherapeutics developers.
United Kingdom
Contract development and manufacturing organizations absorb elevated documentation costs under tightened EMA standards, revalidating transient platforms for toxicology-enabling batches. The country's national pharmaceutical regulator aligns with ICH Q5D quality guidelines on cell substrates, constraining gene-of-origin traceability documentation. Oxford and Cambridge biotech corridors sustain demand for suspension-adapted CHO variants.
India
CDSCO accelerated approval pathways for reference biologics create procurement pressure for rapid transient-derived toxicology batches ahead of stable pool establishment. The national pharmaceutical regulator's biosimilar quality frameworks tighten validation requirements for expression systems used in regulated studies. Hyderabad and Bangalore contract research networks expand adoption of transient expression platforms for antibody screening.
Switzerland
Swissmedic oversight of biological active substances elevates supplier qualification standards for clinical-grade transient materials. Basel pharmaceutical clusters maintain dense contract research networks supporting preclinical biotherapeutics development. Swiss sponsors prioritize synthetic media formulations reducing fetal bovine serum dependence in transient workflows.
Mammalian Transient Protein Expression Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the mammalian transient protein expression landscape. The vendor base stratifies between integrated platform providers with captive bioreactor hardware and specialized reagent suppliers scaling through multi-site contract manufacturing relationships. Three archetypes dominate: diversified life science conglomerates with end-to-end portfolios, focused cell-line engineering specialists, and transfection reagent pure-plays facing margin compression at scale. Competitive moves center on strategic partnerships for vector-to-harvest workflow standardization and geographic expansion into Indian biosimilar development clusters.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA represent integrated platform providers leveraging synthetic media and reagent portfolios to sustain service contracts. Lonza Group occupies a position exemplifying the high-complexity custom cell-line specialist archetype, anchoring premium projects through dedicated facility infrastructure. These three companies illustrate the competitive tension between standardization and bespoke engineering as regulatory agencies tighten traceability requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Lonza Group |
| Promega Corporation |
| Agilent Technologies |
| Bio-Rad Laboratories |
| QIAGEN |
| Takara Bio |
| Sartorius AG |
| Others |
Supply & Pricing Matrix
Fetal bovine serum price volatility cascades through synthetic media formulations into tiered service contracts, with agricultural commodity swings compressing margins on standard-grade reagents while premium cell-line engineering retains pricing power through documented traceability files.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes platform providers from standalone reagent suppliers. Three-tier pricing structure across premium, standard, and economy levels separates validated GMP-grade cell lines with ICH Q5D documentation from research-use reagents and generic transfection kits. Price differentiation rests on certification tier and after-sales technical support depth. Cost compression in high-volume transfection reagents is intensifying because contract manufacturing organizations scale batches beyond 10^7 cells. Biotechnology firms show highest price sensitivity for discovery-stage screening, while top-ten biopharma accounts absorb premium positioning fees for integrated reagent-to-bioreactor service contracts.
Supply Chain Analysis
Direct-to-biopharma channels handle top-ten account demand, while contract manufacturing organizations aggregate multi-site reagent procurement through distribution partners. GMP-grade plasmid manufacturing concentrates in the United States, Germany, and Switzerland, creating single-source vulnerabilities for vector backbones. Supply chains draw from specialized fetal bovine serum suppliers in Australia and New Zealand, synthetic media chemical precursors from German specialty chemical producers, and engineered CHO cell banks from UK and US repository facilities. Tariff exposure on agricultural-derived serum components threatens cost structures for serum-dependent workflows. Distribution runs through validated cold-chain logistics networks serving pharmaceutical clusters in Greater Boston, San Francisco Bay Area, Munich, and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with CDSCO accelerated approval pathways in India offering 6-12 month timeline advantages over FDA Chemistry, Manufacturing, and Controls documentation burdens for clinical-grade transient materials.
For Market Incumbents: Acquire synthetic media formulation capabilities to reduce fetal bovine serum dependence and defend against commodity price volatility. Secure backward integration into GMP-grade plasmid manufacturing to eliminate single-source vulnerabilities for vector backbones. Invest in electroporation infrastructure at central facilities serving multiple discovery programs to bypass chemical transfection efficiency ceilings. For New Entrants and Emerging Players: Launch via hybrid cell-free protein synthesis workflows targeting non-natural amino acid incorporation applications underserved by traditional CHO platforms. Penetrate Indian biosimilar developer clusters in Hyderabad and Bangalore where CDSCO pathways create demand for rapid toxicology-enabling batches. Position around machine learning-guided vector design services to capture value from compressed lead optimization timelines at mid-sized biotechnology firms. For Investors and Strategic Acquirers: Consolidation pressure builds where vector engineering talent scarcity outpaces academic training pipeline output and regulatory documentation burdens extend supplier qualification timelines. Long-term viability favors platform providers with captive bioreactor hardware and established regulatory files over pure-play reagent suppliers facing margin compression. Target acquisition archetypes include electroporation infrastructure operators and synthetic media specialists with reduced serum formulations. Watch for FDA guidance revisions on gene-of-origin traceability as inflection indicators for documentation cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory File Expansion | ICH Q5D-compliant cell substrate documentation extends supplier lock-in with top-ten biopharma accounts. |
| Synthetic Media Transition | Reduced fetal bovine serum formulations align procurement with EU Green Deal biomanufacturing sustainability targets. |
| Electroporation Infrastructure Buildout | High-voltage pulse delivery capabilities bypass chemical transfection efficiency limits for difficult-to-transfect lineages. |
| Machine Learning Platform Integration | Generative vector design capabilities compress antibody discovery timelines from months to weeks at biotechnology firms. |
| Indian Biosimilar Market Entry | CDSCO accelerated approval pathways create procurement pull for rapid toxicology-enabling transient batches. |
Research Methodology
Bottom-up biotherapeutics developer modeling reconciled against top-down reagent supplier tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, contract manufacturing organization procurement managers, and academic vector engineering specialists combined with secondary validation against FDA Chemistry, Manufacturing, and Controls guidance documents, EMA Good Manufacturing Practice Annex 2 revisions, ClinicalTrials.gov antibody candidate filings, and SEC 10-K disclosures from diversified life science conglomerates. Triangulation across stakeholder perspectives and documentary sources ensures coverage of both demand-side procurement patterns and supply-side capacity investments.
Input-output matrices map vector design, transfection reagent chemistry, and bioreactor control system investments to gram-per-liter yield outputs across the projection horizon. Segmentation dimensions modeled include product architecture tiers, therapeutic application classes, organizational scale of end users, and physical versus chemical delivery modalities. CAGRs derive from regression analysis of historical adoption curves for transient expression platforms adjusted for regulatory documentation burden escalation and sustainability procurement criteria adoption. Industry-specific forecast inputs incorporate CDSCO approval pathway utilization rates and EU Green Deal biomanufacturing target compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden fetal bovine serum supply disruptions or abrupt FDA guidance revisions on gene-of-origin traceability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Exosomes Market