
 Global Synthetic Biosensors Market | 2026-2036
Global Synthetic Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Biosensors Market Foresight
Hospital procurement channels for point-of-care diagnostics is reconfiguring as integrated health networks consolidate vendor relationships. Abbott Laboratories leverages its vertical manufacturing footprint to secure long-term supply agreements with major hospital systems. F. Hoffmann-La Roche Ltd anchors its position through sustained R&D investment in fluorescence-based detection platforms. Siemens Healthineers competes by extending its digital health ecosystem to embed biosensor data directly into clinical workflows.
Synthetic biosensors are engineered devices that combine biological recognition elements with synthetic transduction systems to detect specific analytes, typically operating through electrochemical, optical, or piezoelectric signal conversion with detection limits reaching picomolar concentrations. These instruments serve pharmaceutical analysis and environmental monitoring by enabling real-time, label-free quantification of biomolecules without extensive sample preparation. Electrochemical platforms dominate current revenue pools due to their cost efficiency and compatibility with portable form factors, while nanotechnology-enhanced designs represent the fastest-expanding technology segment as quantum dot and carbon nanotube integrations improve sensitivity thresholds. Genetic circuits within microfluidic architectures are capturing margin concentration from research institutes seeking programmable cell-free detection systems.
FDA quality system regulations and EU MDR conformity requirements shape product development timelines by mandating extensive clinical validation for diagnostic-grade synthetic biosensors, while ISO 13485 certification has become a baseline threshold for supplier qualification across European and North American procurement frameworks. China's NMPA has accelerated review pathways for innovative biosensor categories, creating divergent regulatory friction for multinationals pursuing simultaneous multi-region market entry. Stakeholders must monitor evolving premarket submission requirements as regulators harmonize performance standards for synthetic biology-derived devices.
Market Dynamics
Pharmaceutical manufacturers are consolidating real-time bioprocess monitoring around synthetic biosensors, compressing validation timelines and forcing component suppliers to integrate upstream with foundry partners to meet FDA and EU MDR performance benchmarks.
Growth Catalysts
- EU MDR Clinical Validation Mandate:Diagnostic-grade synthetic biosensors must demonstrate picomolar detection limits under ISO 13485 frameworks, accelerating replacement of legacy analytical instruments in German and Japanese precision manufacturing clusters.
- Cell-Free Genetic Circuit Platforms:Research institutes are deploying programmable microfluidic architectures for label-free biomolecule quantification, displacing enzyme-linked assays in pharmaceutical quality control workflows.
- Nanotechnology Integration:Quantum dot and carbon nanotube enhancements are lowering sensitivity thresholds in electrochemical platforms, expanding addressable applications in environmental monitoring across United States industrial corridors.
Market Restraints
- Specialized Foundry Concentration:Microfluidic chip fabrication depends on a narrow base of German and Japanese precision manufacturers, creating supply vulnerability for multinationals pursuing simultaneous FDA and NMPA submissions.
- Extended Regulatory Timelines:EU MDR conformity assessment procedures for synthetic biology-derived devices now average 18-24 months, compressing commercialization windows relative to traditional diagnostics.
- Optical Platform Cost Structure:Fluorescence-based detection systems require rare-earth phosphors and precision optics, exposing margins to raw material volatility in Chinese and Australian supply chains.
Strategic Opportunities
- China NMPA Accelerated Pathways:Innovative biosensor categories now qualify for priority review, creating first-mover advantage for multinationals with localized clinical validation capabilities in Shanghai and Suzhou biotech zones.
- Wearable Form Factor Convergence:Integration of electrochemical transducers with flexible electronics is opening continuous monitoring applications in diabetes management and athletic performance optimization.
- Digital Health Ecosystem Embedding:Hospital procurement committees are prioritizing biosensors with native HL7 FHIR connectivity, rewarding vendors with pre-integrated clinical workflow architectures.
Industry Challenges
- Synthetic Biology Talent Scarcity:Genetic circuit design and cell-free system engineering require interdisciplinary expertise spanning molecular biology and microfabrication, with limited training pipelines in United States and European universities.
- Multi-Region Certification Complexity:Simultaneous FDA 510(k), EU MDR, and NMPA submissions demand divergent clinical evidence packages, straining regulatory affairs capacity at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Biosensors Market |
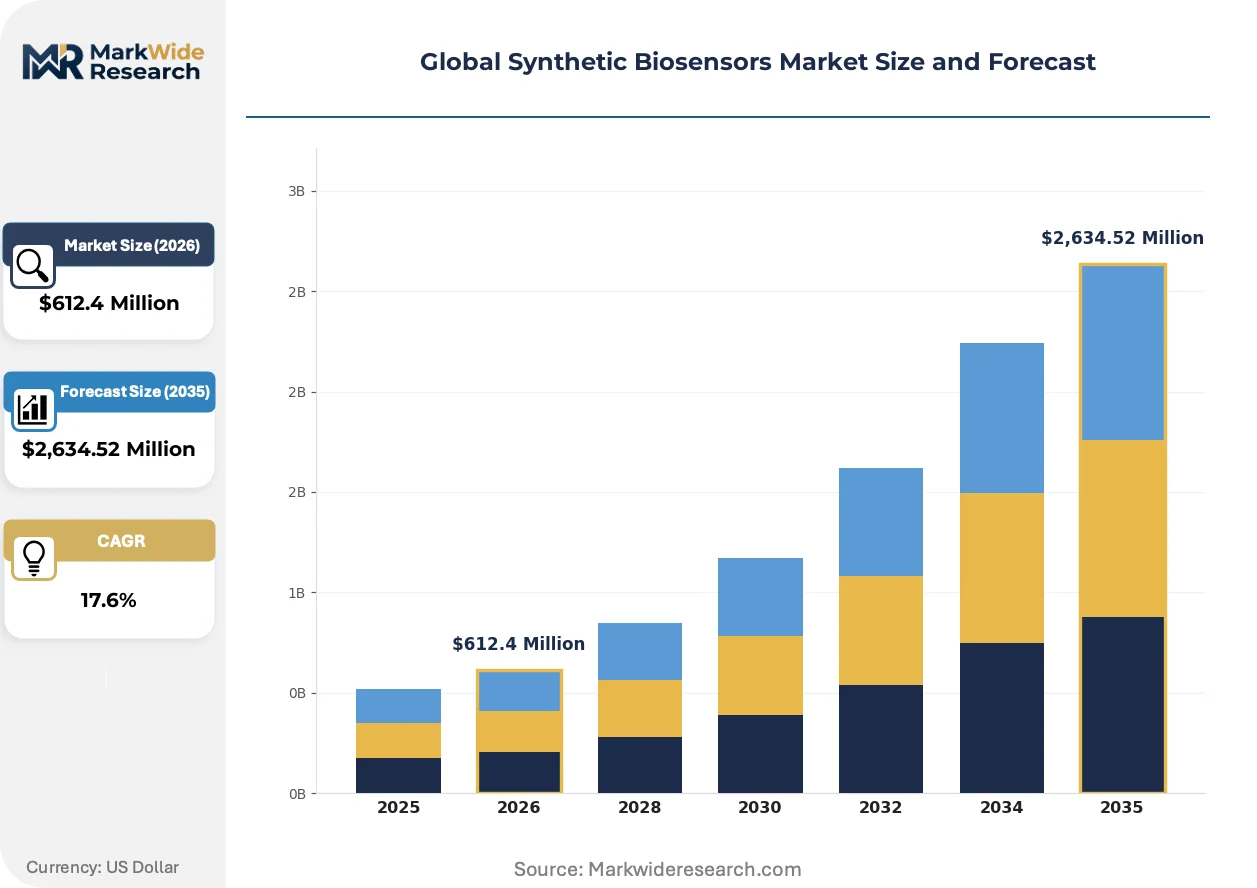
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,634.52 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Optical, Piezoelectric, Thermal, Acoustic, Magnetoresistive Technology: Nanotechnology, Microfluidics, Genetic Circuits, Fluorescence, Surface Plasmon Resonance, Isothermal Amplification Application: Environmental Monitoring, Food Safety, Bioprocess Control, Pharmaceutical Analysis, Agricultural Testing, Biodefense End User: Research Institutes, Diagnostic Laboratories, Biotechnology Firms, Chemical Manufacturers, Academic Centers, Quality Control Units |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Medtronic, Siemens Healthineers, Dexcom, Bio-Rad Laboratories, DuPont, Biosensors International Group, Masimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Biosensors Market Shifts & Advancements
Digital integration is compressing the gap between biosensor raw output and clinical decision support, while regulatory harmonization efforts and procurement centralization are restructuring how vendors access hospital and pharmaceutical buyers.
CRISPR-based nucleic acid detection is digitizing diagnostic workflows by enabling programmable target recognition without thermal cycling infrastructure. Pharmaceutical quality control departments in Germany and Switzerland are adopting these platforms for rapid contaminant screening. The technology is digitizing compliance documentation by generating machine-readable amplification curves that integrate directly with batch release systems.
EU MDR Annex VIII classification rules are redefining which synthetic biosensor configurations require notified body intervention, forcing manufacturers to redesign product architectures to avoid higher-risk device categories. Fluorescence-based detection platforms with quantitative readouts now face stricter clinical evidence requirements than qualitative electrochemical alternatives. German and French manufacturers are responding by bifurcating product portfolios between research-use-only and clinical-grade variants with divergent validation documentation.
Integrated health networks are consolidating vendor relationships around single-source agreements for point-of-care diagnostics, displacing fragmented procurement by individual hospital laboratories. Abbott Laboratories and Roche have secured multi-year supply contracts with major United States health systems by bundling biosensor hardware with reagent subscription models. This concentration is most visible in California and Texas, where Kaiser Permanente and HCA Healthcare have centralized diagnostic device purchasing under value-based care frameworks.
Global Synthetic Biosensors Market Segmentation
Synthetic biosensor architectures fragment across signal transduction physics, manufacturing precision, and regulatory burden. Each segment carries distinct validation timelines and foundry dependencies that reshape vendor economics. Procurement committees weight these trade-offs differently across pharmaceutical, environmental, and clinical use cases.
Product Type:
Cycle times diverge sharply: electrochemical platforms refresh every 18-24 months with firmware upgrades, while optical systems face 5-7 year replacement cycles tied to precision optics depreciation. Thermal and acoustic variants occupy intermediate positions determined by transducer calibration protocols.
- Electrochemical:Potentiometric and amperometric transducers leverage screen-printed electrodes and redox-active probes for label-free detection. Pharmaceutical manufacturers in Germany and the United States deploy these for real-time bioprocess monitoring where picomolar sensitivity meets disposable cost targets. FDA 510(k) pathways favor electrochemical architectures due to established predicate devices.
- Optical:Fluorescence and absorbance-based systems integrate photodiode arrays with waveguide couplers for multi-analyte parallel detection. Swiss and Japanese precision manufacturing clusters concentrate demand for these platforms in pharmaceutical quality control workflows. EU MDR Annex VIII classification rules impose heavier clinical evidence burdens on quantitative optical readouts.
- Piezoelectric:Quartz crystal microbalance transducers detect mass loading through resonant frequency shifts.
- Thermal:Calorimetric biosensors measure enthalpy changes from enzymatic reactions with minimal sample preparation.
- Acoustic:Surface acoustic wave devices exploit piezoelectric substrate deformation for real-time binding kinetics.
- Magnetoresistive:Giant magnetoresistance sensors enable magnetic bead-based sandwich assays with electrical readout.
Electrochemical platforms dominate installed base across diagnostic and environmental monitoring deployments. Optical systems are where expansion concentrates as fluorescence-based detection penetrates pharmaceutical release testing protocols.
Technology:
Cost tiers separate commodity electrochemical strips from premium nanotechnology-enhanced systems. Genetic circuits and microfluidic architectures command 3-5x manufacturing overhead but unlock programmable detection capabilities that research institutes prioritize.
- Nanotechnology:Quantum dot and carbon nanotube integrations amplify signal-to-noise ratios through enhanced electron transfer kinetics. United States environmental monitoring contractors deploy these for heavy metal and pesticide detection in industrial corridor watersheds. Raw material volatility in Chinese rare-earth supply chains compresses margins for phosphor-dependent formulations.
- Microfluidics:Laminated polymer or glass-silicon hybrid chips integrate sample preparation, reaction, and detection in sub-milliliter volumes. German research institutes and biotechnology firms drive adoption for point-of-care infectious disease diagnostics. Specialized foundry concentration in Baden-Württemberg and Tokyo creates supply vulnerability for multinationals.
- Genetic Circuits:Cell-free transcription-translation systems enable programmable biomolecule sensing without intact cells.
- Fluorescence:Förster resonance energy transfer architectures dominate nucleic acid quantification workflows.
- Surface Plasmon Resonance:Gold thin-film biosensors provide label-free binding kinetics for pharmaceutical development.
- Isothermal Amplification:Loop-mediated amplification and recombinase polymerase amplification eliminate thermal cycling infrastructure requirements.
Microfluidics captures the steepest expansion trajectory as programmable architectures displace enzyme-linked assays. Nanotechnology retains premium pricing power in environmental and biodefense applications.
Application:
Volume concentrates in bioprocess control where pharmaceutical manufacturers instrument upstream and downstream unit operations. Food safety and agricultural testing present fragmented demand with divergent regulatory harmonization across jurisdictions.
- Bioprocess Control:Real-time monitoring of cell culture metabolites and product titer accelerates batch release decisions. United States and German pharmaceutical manufacturers consolidate validation protocols around synthetic biosensors to compress FDA and EU MDR submission timelines. Single-use sensor integration with distributed control systems dominates capital planning.
- Pharmaceutical Analysis:Quality control departments deploy biosensors for contaminant screening and potency verification. Swiss and Japanese regulatory agencies have harmonized pharmacopeial chapters to enable mutual recognition of biosensor-based release testing.
- Environmental Monitoring:Industrial corridor wastewater and air quality surveillance drives demand for field-deployable platforms.
- Food Safety:Pathogen and allergen detection in processing facilities faces cost pressure from rapid immunoassay alternatives.
- Agricultural Testing:Soil nutrient and pesticide residue analysis remains fragmented across regional extension services.
- Biodefense:Select agent detection programs in the United States and United Kingdom sustain classified procurement channels.
Bioprocess control anchors revenue concentration through multi-year supply agreements. Pharmaceutical analysis is where margin expansion concentrates as quantitative readouts command premium pricing over qualitative alternatives.
End User:
Customer type determines procurement velocity: diagnostic laboratories consolidate through integrated health networks while research institutes fragment across individual principal investigator budgets. Quality control units operate under capital expenditure cycles tied to facility commissioning.
- Diagnostic Laboratories:Hospital-affiliated and independent testing facilities standardize on biosensor platforms with native laboratory information system connectivity. Kaiser Permanente and HCA Healthcare in California and Texas have centralized purchasing around value-based care frameworks. HL7 FHIR interoperability now gates vendor qualification.
- Research Institutes:Academic and government laboratories prioritize programmable architectures for method development and grant-funded innovation. Max Planck Institutes and RIKEN centers in Germany and Japan concentrate demand for genetic circuit and microfluidic platforms.
- Biotechnology Firms:Cell therapy and gene therapy developers instrument process analytical technology initiatives.
- Chemical Manufacturers:Specialty chemical producers deploy biosensors for biocatalytic process monitoring.
- Academic Centers:Undergraduate teaching laboratories drive demand for low-cost electrochemical educational kits.
- Quality Control Units:Pharmaceutical and food industry release testing departments prioritize ISO 17025-compliant platforms.
Diagnostic laboratories concentrate procurement volume through consolidated vendor relationships. Research institutes are where technology adoption concentrates as early validation creates reference architectures for downstream clinical translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland outstrips United States benchmarks by 15-20 percent for clinical-grade electrochemical platforms, while Chinese manufacturers undercut both markets on nanotechnology-enhanced environmental sensors. This asymmetry fragments procurement strategies across pharmaceutical, diagnostic, and industrial monitoring verticals.
United States
Pharmaceutical manufacturers in Massachusetts and North Carolina deploy synthetic biosensors for real-time bioprocess monitoring to compress FDA 510(k) validation timelines. The FDA quality system regulations mandate ISO 13485 certification as a baseline supplier qualification threshold. Boston-Cambridge biotechnology clusters concentrate demand for programmable genetic circuit platforms in cell therapy process analytical technology.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria anchor EU MDR-compliant electrochemical sensor production for pharmaceutical quality control workflows. EU MDR Annex VIII classification rules impose stricter clinical evidence requirements on quantitative optical readouts than qualitative alternatives. Stuttgart-based foundries supply microfluidic chips to multinationals pursuing simultaneous FDA and NMPA submissions.
China
NMPA accelerated review pathways for innovative biosensor categories attract multinationals establishing localized clinical validation capabilities in Shanghai and Suzhou biotech zones. The National Medical Products Administration prioritizes submissions with domestic multi-center trial data. Yangtze River Delta industrial corridors drive demand for nanotechnology-enhanced environmental monitoring platforms in watershed surveillance contracts.
Japan
PMDA harmonization with ICH guidelines streamlines biosensor approval pathways for pharmaceutical analysis applications. The Pharmaceuticals and Medical Devices Agency maintains stringent post-market surveillance requirements for diagnostic-grade devices. Tokyo-Yokohama precision manufacturing clusters concentrate quartz crystal microbalance transducer fabrication for piezoelectric biosensor architectures.
Switzerland
Swissmedic mutual recognition agreements with EU MDR enable seamless market access for fluorescence-based detection platforms. Swiss pharmacopeial harmonization with German and Japanese standards supports biosensor-based release testing adoption. Basel-Zurich pharmaceutical quality control hubs command premium pricing for quantitative optical systems in contaminant screening workflows.
Global Synthetic Biosensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electrochemical electrode and microfluidic chip fabrication. The vendor base stratifies across three tiers: multinational conglomerates with vertical manufacturing footprints, mid-scale specialists in nanotechnology-enhanced transduction, and regional foundries supplying precision microfluidic substrates. Dominant competitive moves include backward integration into foundry partnerships and technology licensing for cell-free genetic circuit architectures.
Within the multinational conglomerate tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd occupy positions as anchors for integrated health network procurement consolidation. Siemens Healthineers exemplifies the digital health ecosystem embedding strategy. These three entities represent divergent archetypes: Abbott leverages supply agreement bundling, Roche anchors through sustained R&D positioning in fluorescence-based platforms, and Siemens competes via clinical workflow integration rather than hardware specialization alone.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Medtronic |
| Siemens Healthineers |
| Dexcom |
| Bio-Rad Laboratories |
| DuPont |
| Biosensors International Group |
| Masimo |
| Others |
Supply & Pricing Matrix
Baden-Württemberg precision foundries concentrate microfluidic chip fabrication for electrochemical and optical transducers, anchoring margin capture downstream with pharmaceutical manufacturers and integrated health networks that demand EU MDR-compliant validation documentation. This geographic concentration of specialized manufacturing capacity shapes pricing power across the synthetic biosensor value chain.
Pricing Analysis
Configured-to-order genetic circuit platforms command 3-5x premiums over standard electrochemical strips due to programmable detection capabilities and cell-free architecture complexity. Pricing stratifies across clinical-grade, research-use-only, and educational tiers, with ISO 13485 certification and FDA 510(k) predicate status driving the steepest differentiation. Cost compression in commodity electrochemical segments is intensifying as Chinese manufacturers expand nanotechnology-enhanced environmental sensor output. Diagnostic laboratories within consolidated United States health networks exhibit lowest price sensitivity due to value-based care framework incentives, while academic centers face severe budget constraints.
Supply Chain Analysis
Upstream rare-earth phosphor and precision optics feedstock draws from Chinese and Australian mining operations, with quartz crystal substrates sourced from Japanese and German specialty material suppliers. Carbon nanotube and quantum dot inputs hinge on United States and South Korean chemical synthesis capacity. Single-source vulnerability concentrates in Stuttgart-based microfluidic foundries serving simultaneous FDA and NMPA submission timelines. Distribution runs through authorized distributor networks for clinical-grade devices, while research-use platforms move via direct manufacturer-to-institution contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from programmable cell-free genetic circuit platforms that displace enzyme-linked assays in pharmaceutical quality control workflows. Defensive positioning requires building durable moats before these architectures achieve clinical-grade validation.
For Market Incumbents: Build regulatory data moats by accelerating EU MDR clinical validation submissions for quantitative optical readouts ahead of emerging CRISPR-based nucleic acid detection platforms. Anchor backward integration into Baden-Württemberg and Tokyo precision foundries to secure microfluidic chip supply for simultaneous FDA and NMPA filings. Prioritize HL7 FHIR connectivity development to gate hospital procurement committee qualification.
For New Entrants and Emerging Players: Establish a beachhead in wearable electrochemical form factors for diabetes management and athletic performance optimization, where flexible electronics integration creates white-space outside incumbent fluorescence-based strongholds. Target China NMPA accelerated review pathways by building localized clinical validation capabilities in Shanghai and Suzhou biotech zones. Pursue reagent subscription bundling to mirror Abbott and Roche supply agreement structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed nanotechnology-enhanced transduction specialists holding carbon nanotube and quantum dot integration patents but lacking clinical-grade certification infrastructure. Five-to-ten year viability hinges on successful navigation of multi-region FDA, EU MDR, and NMPA submission complexity. Monitor synthetic biology talent pipeline expansion at Max Planck Institutes and RIKEN centers as inflection indicator for programmable architecture maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Completion | Unlocks German and Swiss pharmaceutical quality control procurement channels under Annex VIII classification rules. |
| Cell-Free Genetic Circuit Platform Launch | Displaces enzyme-linked assays in RIKEN and Max Planck Institute method development workflows. |
| Precision Foundry Partnership | Secures microfluidic chip supply from Stuttgart and Tokyo manufacturers for dual regulatory submissions. |
| HL7 FHIR Native Integration | Gates vendor qualification with Kaiser Permanente and HCA Healthcare centralized purchasing committees. |
| China NMPA Localized Trial Investment | Qualifies for accelerated review pathways in Shanghai and Suzhou biotech zones. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical bioprocess engineers, regulatory affairs specialists at FDA and EMA, hospital procurement committee chairs, and microfluidic foundry operations managers, then refined against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, ClinicalTrials.gov biosensor study records, and pharmacopeial harmonization chapters. Bottom-up demand modeling across electrochemical, optical, and piezoelectric transduction platforms was triangulated with top-down pharmaceutical and diagnostic market sizing.
Demand-supply-balance dynamics across the analysis window incorporated real-time bioprocess monitoring adoption curves, cell-free genetic circuit research funding trajectories, and nanotechnology-enhanced environmental monitoring contract awards. Segmentation dimensions included signal transduction physics, manufacturing precision tier, regulatory burden classification, and end-user procurement velocity. CAGRs were derived from installed base replacement cycles, validation timeline compression effects, and programmable architecture penetration rates in pharmaceutical quality control workflows.
Stress conditions across EU MDR Annex VIII reclassification risk, rare-earth phosphor supply disruption, and synthetic biology talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and hospital network consolidation velocity. Cross-checking against ISO 13485 certification database growth and NMPA priority review queue depth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Cell Cycle Analysis Market