
 Global Biological Stains Market | 2026-2036
Global Biological Stains Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biological Stains Market Foresight
Diagnostic laboratory demand is pivoting toward ready-to-use staining kits as staffing shortages pressure workflow efficiency across high-throughput settings. Thermo Fisher Scientific leverages its clinical distribution network to sustain kit penetration in hospital-affiliated labs across North America and Western Europe. Merck KGaA anchors its position through deep catalog breadth in histochemical and fluorescent stains for academic research consortia. Becton, Dickinson and Company competes by integrating stain portfolios with its automated tissue processing hardware, creating bundled procurement appeal for integrated health systems.
Biological stains comprise synthetic or natural dye compounds formulated to selectively bind cellular structures, proteins, or nucleic acids for microscopic visualization, with purity grades typically exceeding 90 percent dye content and specified spectral absorbance ranges. These reagents serve fundamental roles in disease diagnosis, drug safety assessment, and basic research by enabling contrast differentiation in tissue sections, blood smears, and cell cultures. Fluorescent stains command premium positioning due to their indispensability in confocal microscopy and flow cytometry workflows, while immunohistochemical stains represent the fastest-expanding category as companion diagnostic requirements multiply across oncology drug development. Ready-to-use liquid formulations capture growing share from powder formats as laboratories prioritize reproducibility and reduced preparation time.
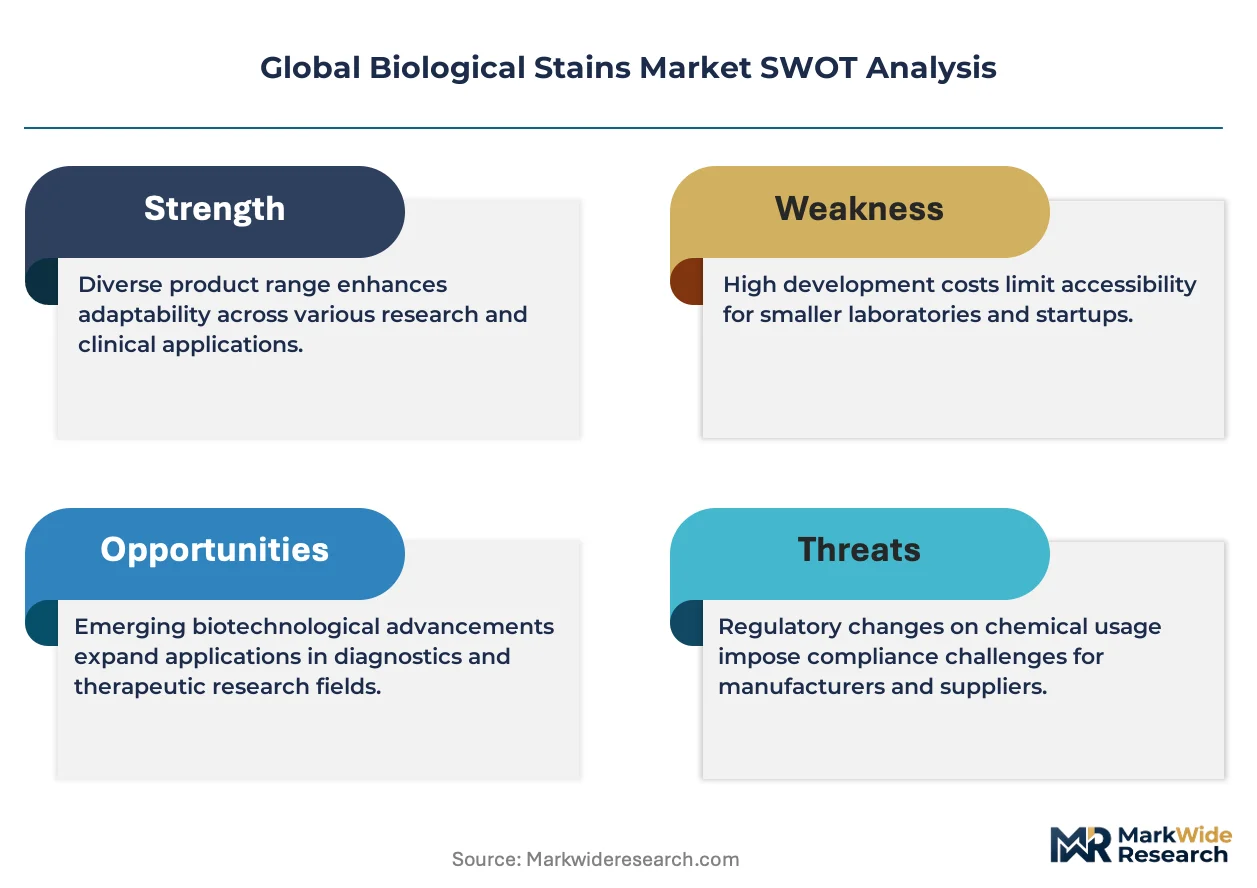
FDA oversight of clinical laboratory reagents through its in vitro diagnostic framework shapes product registration pathways and quality system requirements for stains used in patient diagnosis. EMA and EU MDR standards enforce batch consistency documentation and biological safety testing that manufacturers must satisfy for CE-marked distribution across European member states. ISO 13485 certification has become a baseline expectation for suppliers serving regulated clinical environments rather than research-only accounts. Stakeholders must monitor evolving companion diagnostic co-development partnerships between stain vendors and pharmaceutical sponsors, as these alliances increasingly determine which chromogen and fluorophore platforms achieve preferred status in pivotal clinical trials.
Market Dynamics
Companion diagnostic co-development partnerships between stain vendors and pharmaceutical sponsors are restructuring competitive positioning, as preferred chromogen and fluorophore platforms in pivotal oncology trials determine long-term procurement relationships across hospital-affiliated laboratories.
Growth Catalysts
- EU MDR compliance mandates:Elevated purity standards and documentation requirements in Europe are forcing stain manufacturers to upgrade quality systems, creating competitive separation between certified and non-certified suppliers in clinical markets.
- Immunohistochemical biomarker validation:Pharmaceutical oncology pipelines are expanding their use of IHC stains for companion diagnostic development, pulling specialized reagent demand from centralized pathology networks in Germany and the United States.
- Fluorescent microscopy workflow integration:Confocal and flow cytometry applications in academic research clusters are concentrating procurement of high-performance fluorophores in multi-institutional consortia with standardized staining protocols.
Market Restraints
- Natural dye feedstock volatility:Hematoxylin supply depends on logwood tree cultivation concentrated in Central America, exposing histochemical stain producers to climate-driven harvest fluctuations and price instability.
- REACH registration burdens:European chemical safety documentation requirements for synthetic dye intermediates are extending product development timelines and elevating compliance costs for mid-scale manufacturers without dedicated regulatory teams.
- Digital pathology substitution:AI-assisted whole-slide imaging systems in high-throughput diagnostic settings are reducing per-slide stain consumption intensity as laboratories prioritize computational analysis over multiple sequential staining rounds.
Strategic Opportunities
- India research infrastructure expansion:CDSCO-aligned clinical trial growth and BIS standardization initiatives are opening procurement channels for CE-marked and ISO-certified stain suppliers serving contract research organizations in Hyderabad and Bangalore clusters.
- Ready-to-use kit penetration:Liquid formulation stains with validated stability claims are displacing powder reagents in staffing-constrained hospital laboratories seeking reproducible turnaround times without technical specialist preparation.
- CRISPR-based spatial transcriptomics:Convergence of gene editing visualization and multiplexed fluorescent staining is creating demand for novel nucleic acid-binding fluorophores in spatial biology instrument ecosystems.
Industry Challenges
- ISO 13485 certification timeline compression:Clinical laboratory customers are demanding quality system documentation within compressed procurement cycles, straining smaller manufacturers' regulatory affairs capacity.
- Spectral signature standardization:Inconsistent absorbance range specifications across supplier certificates of analysis are forcing end-users to perform in-house validation, delaying assay transfer between research and diagnostic settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biological Stains Market |
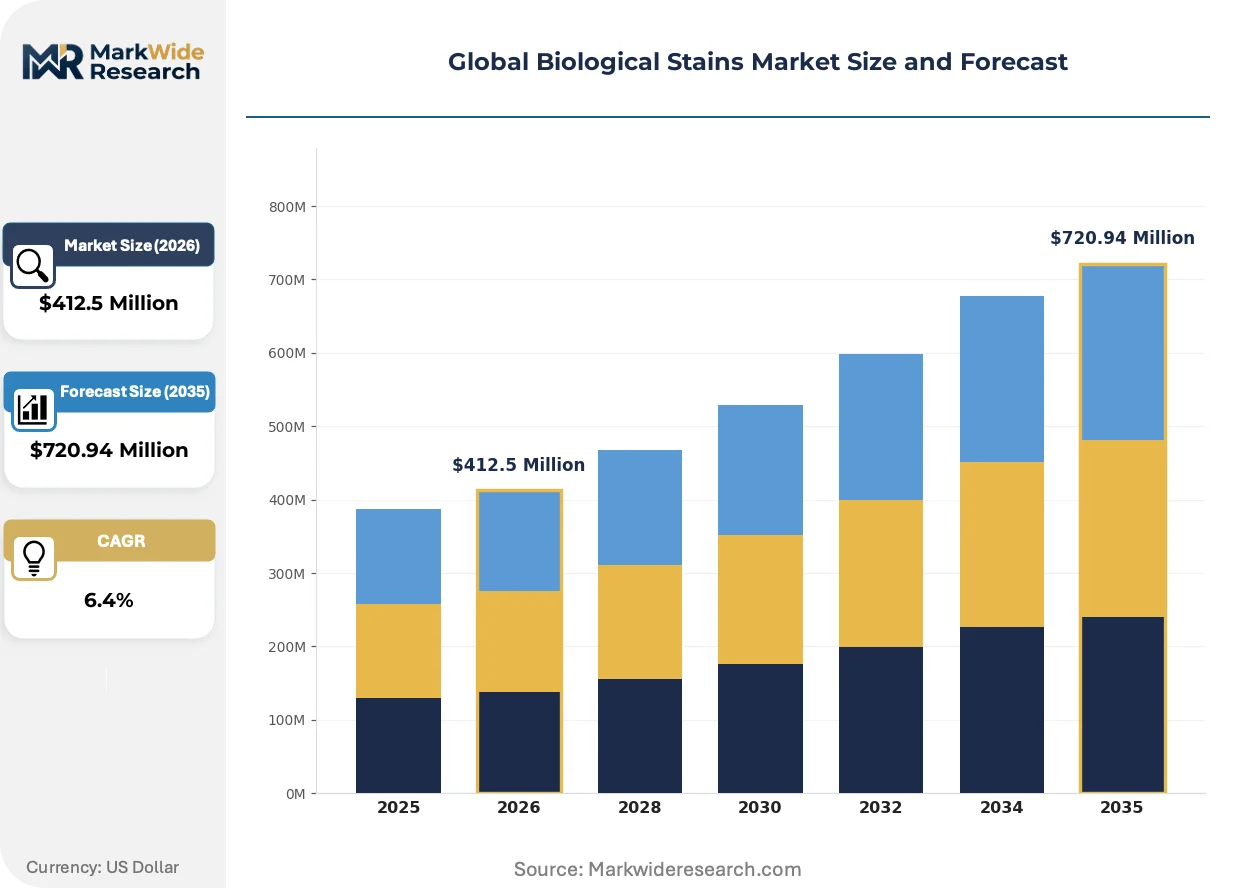
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vital Stains, Fluorescent Stains, Histochemical Stains, Immunohistochemical Stains, Enzyme Stains Application: Cell Biology, Microbiology, Cytology, Pathology, Hematology End User: Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Academic Institutions, Biotechnology Firms Form: Liquid, Powder, Tablets, Dyes, Ready-to-use Kits |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Becton, Dickinson and Company, Avantor, Macsen Laboratories, Abbey Color, Epredia Inc., Sigma-Aldrich, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biological Stains Market Shifts & Advancements
Workflow automation and reagent integration are compressing the traditional separation between stain chemistry and analytical instrumentation, with vendors restructuring product architectures around complete system compatibility rather than standalone dye performance.
Quantum dot nanocrystal stains are absorbing spectral multiplexing demand from conventional organic fluorophores in high-parameter flow cytometry panels. Academic medical centers with specialized cytometry cores are adopting these semiconductor nanocrystals for their photostability and narrow emission profiles. The technology is absorbing premium positioning in lymphoma immunophenotyping workflows where ten-color panels exceed conventional dye limitations.
REACH authorization requirements for aromatic amine intermediates are forcing reformulation of classic histochemical stains across European supply chains. Manufacturers are substituting alternative coupling chemistry to maintain batch-to-batch consistency while satisfying ECHA substance restrictions. Azo dye-based chromogens in routine H&E alternatives face the steepest substitution pressure in Germany's centralized pathology procurement networks.
Consolidated procurement through group purchasing organizations is compressing supplier negotiation leverage in North American health systems. Integrated delivery networks are unbundling stain purchases from tissue processor maintenance contracts, forcing standalone reagent pricing transparency. This pattern is most visible in United States hospital-affiliated laboratories where supply chain standardization initiatives span multiple affiliated sites.
Global Biological Stains Market Segmentation
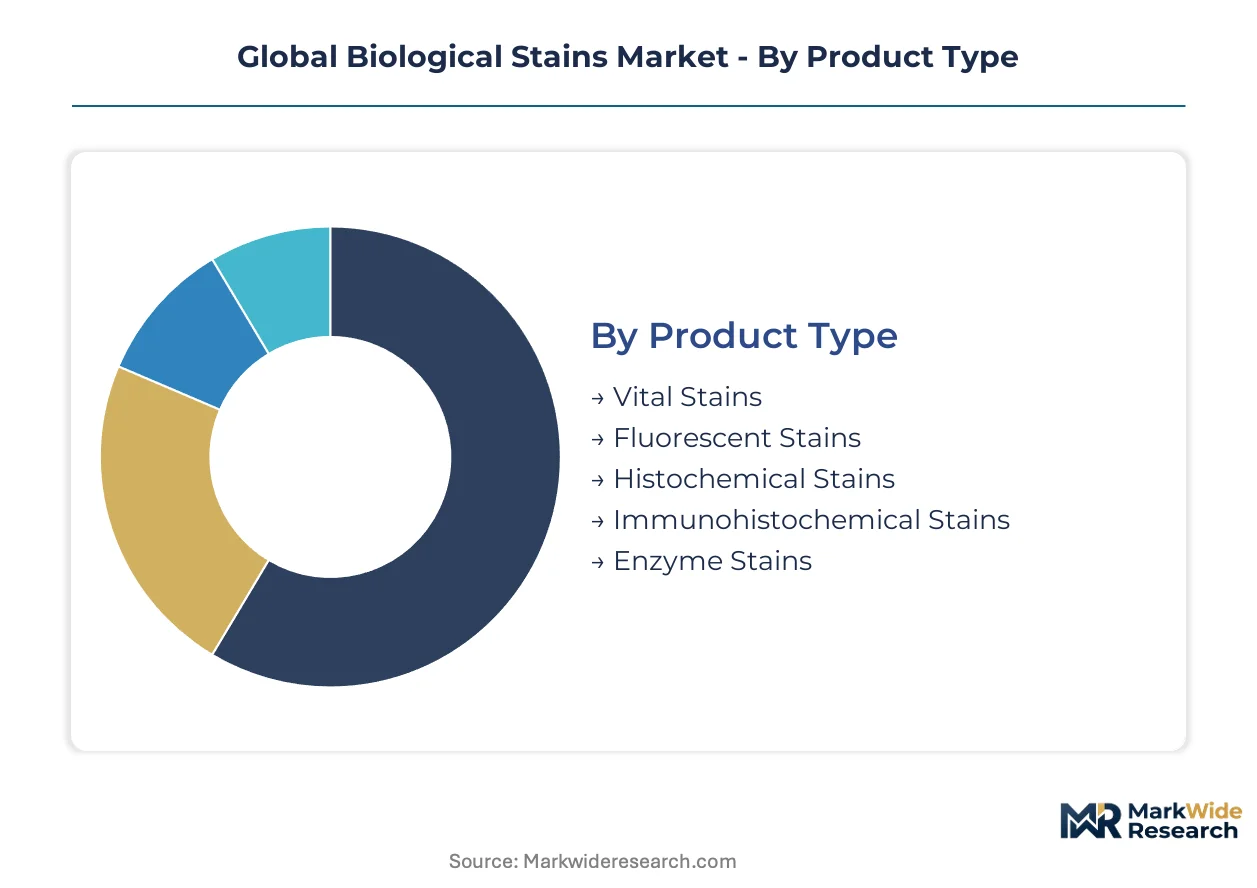
Biological stains serve fundamentally different purposes across research, diagnostic, and pharmaceutical workflows, with each segment demanding distinct purity grades, regulatory documentation, and formulation stability. Understanding how procurement criteria diverge across these dimensions reveals where manufacturers must align product architectures with specific customer validation requirements.
Product Type:
Buyers in this category differentiate primarily by optical detection modality and the complexity of target biomolecule binding required for their analytical workflows.
- Immunohistochemical Stains:Antibody-conjugated chromogens enabling protein-specific detection in formalin-fixed tissue sections, with horseradish peroxidase and alkaline phosphatase reporter systems dominating clinical diagnostics. Pharmaceutical oncology pipelines in Germany and the United States are pulling specialized reagent demand for companion diagnostic validation, forcing suppliers to maintain master file documentation with FDA and EMA.
- Fluorescent Stains:Organic fluorophores and quantum dot nanocrystals engineered for precise excitation-emission profiles in confocal microscopy and flow cytometry. Academic medical centers with specialized cytometry cores in multi-institutional consortia concentrate procurement of high-parameter panels where photostability and narrow emission bandwidths command premium positioning.
- Vital Stains:Membrane-permeable dyes distinguishing living from dead cells through metabolic activity or membrane integrity assays.
- Histochemical Stains:Classic dye mixtures including hematoxylin-eosin formulations for general tissue morphology visualization.
- Enzyme Stains:Substrate-chromogen systems detecting enzymatic activity in tissue sections or cell preparations.
Histochemical stains lead volumes today; immunohistochemical stains are gaining share fastest.
Application:
Workflow throughput and regulatory scrutiny intensity separate these segments, with diagnostic applications demanding ISO 13485-certified supply chains that research settings often bypass.
- Pathology:Tissue-based diagnostic staining in hospital-affiliated laboratories and centralized networks, where turnaround time pressures and companion diagnostic requirements drive preference for ready-to-use formulations with validated stability claims. Germany's centralized pathology procurement networks exemplify this concentration, bundling high-volume chromogen purchases with automated platform compatibility requirements.
- Cell Biology:Live-cell imaging and subcellular localization studies in academic and biotechnology research settings, where multiplexed fluorescent staining protocols require precise spectral separation. Spatial transcriptomics convergence with CRISPR visualization is creating demand for novel nucleic acid-binding fluorophores in instrument ecosystems centered on Boston and San Diego research clusters.
- Microbiology:Bacterial and fungal identification through differential staining techniques.
- Cytology:Individual cell analysis for cancer screening and infectious disease detection.
- Hematology:Blood cell differentiation and bone marrow examination protocols.
Pathology commands the largest revenue pool; cell biology applications are climbing the fastest.
End User:
Budget authority and technical staffing levels determine formulation preferences, with resource-constrained settings prioritizing preparation simplicity over per-unit cost optimization.
- Diagnostic Laboratories:High-throughput clinical testing facilities facing staffing shortages and workflow efficiency pressures, where ready-to-use liquid kits displace powder reagents to reduce technical specialist preparation time. Hospital-affiliated laboratories across North America and Western Europe concentrate procurement through group purchasing organizations that demand standalone reagent pricing transparency.
- Research Institutes:Multi-investigator facilities with specialized cores standardizing protocols across consortia, where deep catalog breadth in histochemical and fluorescent stains supports diverse project requirements. Academic research clusters in Germany drive bulk procurement through centralized purchasing offices with stringent batch consistency documentation requirements.
- Pharmaceutical Companies:Drug developers requiring biomarker validation for regulatory submission.
- Academic Institutions:University laboratories with variable funding cycles and project-specific staining needs.
- Biotechnology Firms:Emerging companies prioritizing rapid assay development and technology transfer.
Diagnostic laboratories generate the highest absolute demand; research institutes are expanding most quickly.
Form:
Preparation labor and reproducibility requirements shape selection, with staffing constraints accelerating displacement of traditional formats.
- Ready-to-use Kits:Pre-formulated liquid stains with validated stability claims and standardized protocols, capturing share from traditional formats as laboratories prioritize reproducible turnaround times. Thermo Fisher Scientific leverages its clinical distribution network to sustain penetration in hospital-affiliated labs where technical specialist availability constrains powder preparation workflows.
- Liquid:Concentrated solutions requiring dilution but offering longer shelf stability than pre-diluted kits, positioned for high-volume users with established quality control procedures.
- Powder:Lyophilized or crystalline dyes requiring dissolution and filtration, facing displacement except in specialized applications demanding custom concentration optimization.
- Tablets:Pre-measured solid units dissolving to specific volumes, serving mid-scale laboratories seeking preparation standardization without full kit premium pricing.
- Dyes:Raw colorant materials for in-house formulation by manufacturers and specialized research facilities.
Powder formulations retain volume leadership; ready-to-use kits are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stain manufacturers are relocating production to jurisdictions with streamlined chemical safety documentation, creating compliance arbitrage between REACH-heavy European operations and lighter regulatory environments in Asia-Pacific manufacturing zones.
United States
FDA in vitro diagnostic oversight shapes quality system requirements for clinical-grade stains, while companion diagnostic partnerships between pharmaceutical sponsors and reagent vendors concentrate in Boston and San Diego research clusters. Hospital-affiliated laboratories across the Midwest and Southeast drive ready-to-use kit procurement through group purchasing organizations demanding standalone pricing transparency.
Germany
Centralized pathology networks in Baden-Württemberg and North Rhine-Westphalia bundle high-volume chromogen purchases with automated platform compatibility requirements. EU MDR batch consistency documentation and ECHA REACH authorization for aromatic amine intermediates force reformulation of classic histochemical stains, elevating compliance costs for mid-scale suppliers without dedicated regulatory teams.
China
NMPA medical device classification for diagnostic reagents is tightening registration pathways for imported stains, while domestic manufacturers in the Yangtze River Delta expand capacity for histochemical and fluorescent dye production. Academic research consortia in Beijing and Shanghai concentrate procurement of quantum dot nanocrystals for high-parameter flow cytometry applications.
India
CDSCO-aligned clinical trial growth and BIS standardization initiatives in Hyderabad and Bangalore clusters are opening procurement channels for CE-marked and ISO-certified stain suppliers serving contract research organizations. Research infrastructure expansion is pulling demand for immunohistochemical reagents in biomarker validation workflows.
Japan
PMDA quality system requirements for in vitro diagnostics enforce batch consistency documentation that favors established suppliers with ISO 13485 certification. Academic medical centers in the Kanto region around Tokyo concentrate procurement of fluorescent stains for confocal microscopy and spatial transcriptomics applications.
Global Biological Stains Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement through health system group purchasing organizations compressing supplier negotiation leverage in North America. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with clinical distribution networks, mid-scale manufacturers with deep catalog breadth in research reagents, and automated platform integrators bundling stains with tissue processing hardware. Competitive moves center on companion diagnostic co-development partnerships with pharmaceutical sponsors and vertical integration into dye intermediate production to secure supply chain stability.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions shaped by their clinical distribution infrastructure and catalog depth respectively. Becton, Dickinson and Company exemplifies the platform-integrated archetype, with its automated tissue processing systems creating bundled procurement appeal for integrated health systems. These three entities represent distinct competitive vectors: clinical scale, research breadth, and hardware-software integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Becton, Dickinson and Company |
| Avantor |
| Macsen Laboratories |
| Abbey Color |
| Epredia Inc. |
| Sigma-Aldrich |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Centralized pathology networks in Germany and group purchasing organizations across United States hospital systems compress supplier negotiation leverage into transparent contract structures. This buyer concentration forces tiered pricing stratification across ISO 13485-certified premium grades, research-grade intermediates, and economy powder formulations without full regulatory documentation.
Pricing Analysis
Distributor margins absorb 15-25 points of end-user price in clinical reagent channels, while direct procurement by pharmaceutical sponsors for companion diagnostic co-development commands volume discounts off list. Pricing stratifies across premium, standard, and economy tiers based on certification level and batch documentation depth. Cost compression in mid-scale manufacturer tiers intensifies as REACH registration burdens and EU MDR compliance investments accumulate without offsetting volume scale. Diagnostic laboratories facing staffing shortages exhibit lowest price sensitivity for ready-to-use liquid kits, while academic research clusters with variable funding cycles prioritize per-unit cost optimization over preparation labor.
Supply Chain Analysis
ISO 13485 certification gating restricts qualified supplier pools to established manufacturers with dedicated quality systems, fragmenting procurement options for clinical-grade stains. Manufacturing concentrates in Germany, United States, and China, with dye intermediate production anchored in Chinese chemical parks and formulation finishing distributed across regional regulatory jurisdictions. Hematoxylin feedstock draws from logwood cultivation in Central America, exposing histochemical stain producers to climate-driven harvest volatility. Single-source vulnerability in natural dye supply chains elevates reformulation risk for classic H&E alternatives. Distribution runs through clinical laboratory distributors in North America, direct hospital contracts in Germany, and academic purchasing consortia in multi-institutional research clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where companion diagnostic validation requirements and EU MDR compliance burdens concentrate procurement with certified suppliers holding master file documentation with FDA and EMA. The demand shift toward ready-to-use liquid formulations with validated stability claims rewards manufacturers with integrated quality systems over commodity powder suppliers.
For Market Incumbents: Lock in companion diagnostic co-development partnerships with pharmaceutical sponsors before pivotal trial chromogen selection freezes procurement relationships across hospital-affiliated laboratories. Defend margin position by securing captive supply of aromatic amine intermediates facing REACH authorization pressure, or accelerate reformulation investments to maintain batch consistency under ECHA substance restrictions. Prioritize ISO 13485 certification maintenance as clinical customers compress procurement cycles with compressed quality system documentation demands. For New Entrants and Emerging Players: Launch via contract research organization procurement channels in Hyderabad and Bangalore clusters where CDSCO-aligned clinical trial growth outpaces domestic certified supplier capacity. Target research-grade fluorescent stains for spatial transcriptomics instrument ecosystems in Boston and San Diego academic medical centers, where novel nucleic acid-binding fluorophores command premium positioning without immediate diagnostic regulatory burden. Penetrate through multi-institutional consortia standardization initiatives rather than fragmented individual laboratory sales. For Investors and Strategic Acquirers: Platform-integrated diagnostic hardware manufacturers are the most active acquirers in this space, seeking stain portfolio tuck-ins to complete bundled procurement offerings for integrated health systems. Mid-scale manufacturers with deep catalog breadth in histochemical and fluorescent stains but lacking dedicated regulatory affairs capacity present consolidation targets over a five-to-ten year quality-system investment horizon. Watch for inflection in companion diagnostic co-development announcement velocity as signal of which chromogen and fluorophore platforms achieve preferred status in pivotal oncology trials.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Pharmaceutical sponsors in Germany and United States freeze long-term chromogen procurement through pivotal trial platform selection. |
| REACH-Compliant Reformulation Investment | ECHA aromatic amine restrictions force substitution chemistry to maintain batch consistency in European supply chains. |
| Ready-to-Use Liquid Kit Expansion | Thermo Fisher Scientific leverages clinical distribution networks to displace powder reagents in staffing-constrained hospital laboratories. |
| Quantum Dot Nanocrystal Scale-Up | Academic medical centers adopt semiconductor fluorophores for photostability in ten-color lymphoma immunophenotyping panels. |
| Backward Integration into Dye Intermediates | Manufacturers secure supply chain stability against logwood harvest volatility and REACH authorization bottlenecks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pathology laboratory directors, pharmaceutical biomarker validation leads, regulatory affairs managers at stain manufacturers, and group purchasing organization contract specialists with secondary validation against FDA in vitro diagnostic filings, EMA master file documentation, EU MDR technical file submissions, and ISO 13485 certification registry data. Bottom-up demand modeling from diagnostic laboratory procurement volumes and top-down supply assessment from manufacturer capacity disclosures were triangulated for convergence.
Segment-weighting approaches distributed value across immunohistochemical, fluorescent, histochemical, and vital stain categories by application in pathology, cell biology, and pharmaceutical workflows, with further stratification by end-user type and formulation format. CAGRs were derived from trend extrapolation of procurement pattern shifts and regulatory compliance cost trajectories across the analysis window. Forecast inputs incorporated companion diagnostic pipeline progression, digital pathology adoption curves, and spatial transcriptomics instrument ecosystem expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH authorization delays or accelerated digital pathology substitution in high-throughput diagnostic settings. A model refresh is warranted upon material change in pharmaceutical oncology pipeline structure or EU MDR enforcement intensity affecting mid-scale manufacturer exit rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Global Cell Signaling Market