
 Global MRSA Testing Market | 2026-2036
Global MRSA Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global MRSA Testing Market Foresight
Market Context
Modular assay menus is shifting how hospital laboratories configure their MRSA testing workflows, unbundling traditional culture-based panels into discrete molecular and rapid POC options. Roche Diagnostics leverages its installed base of automated platforms to sustain recurring reagent revenue across large health systems. bioMérieux SA anchors its position through specialized chromogenic media and complementary molecular confirmation assays. Cepheid competes aggressively on cartridge-based random-access systems that reduce batch dependency in mid-volume settings.
Technical Definition and Structural Segments
MRSA testing encompasses laboratory and point-of-care methods that detect methicillin-resistant Staphylococcus aureus colonization or active infection, typically targeting the mecA or mecC gene variants and their regulatory elements through phenotypic culture, nucleic acid amplification, or immunochromatographic techniques. Molecular diagnostics leads absolute revenue contribution due to superior turnaround time and sensitivity in pre-surgical clearance protocols, while rapid POC tests represent the fastest-expanding configuration as nursing units seek bedside admission screening without central lab dependency. Immunoassays occupy a narrowing but defensible niche in blood bank and seroprevalence applications where antigen detection suffices.
Regulatory Frame and Outlook
The FDA governs in vitro diagnostic platform approvals and clinical trial design requirements for novel resistance-gene targets, while the Clinical Laboratory Improvement Amendments set personnel and quality standards that shape test complexity tiers and site-of-care eligibility. WHO antimicrobial resistance surveillance guidelines and EU MDR conformity requirements for IVD manufacturers create additional compliance layers that influence product development roadmaps and market access timelines. Stakeholders must monitor how decentralized regulatory pathways for POC molecular devices reshape competitive boundaries between central laboratory and near-patient testing models.
Market Dynamics
Platform consolidation among clinical laboratories is compressing vendor margins while molecular diagnostic workflows displace slower culture-based protocols in pre-surgical screening programs.
Growth Catalysts
- CMS bundled payment models:United States surgical site infection penalties create direct financial accountability for hospitals, forcing investment in preemptive MRSA colonization screening before orthopedic and cardiac procedures.
- WHO antimicrobial resistance surveillance frameworks:Mandatory reporting requirements across member states expand testing infrastructure in secondary and tertiary hospitals previously lacking molecular capacity.
- Random-access molecular platforms:Cartridge-based systems eliminate batch processing delays, allowing mid-volume laboratories to match turnaround times of high-throughput reference centers.
Market Restraints
- Reagent rental lock-in:Automated platform contracts bind laboratories to proprietary consumable ecosystems, raising switching costs and suppressing price competition among alternative assay suppliers.
- CLIA complexity tier restrictions:Moderate and high-complexity molecular tests face personnel certification barriers that limit deployment to centralized laboratory sites, constraining point-of-care expansion.
- Chromogenic media substitution:Conventional culture methods retain cost advantages in low-resource settings where capital equipment procurement remains prohibitive.
Strategic Opportunities
- Decentralized regulatory pathways:FDA's evolving guidance on waived molecular complexity creates openings for nursing-unit deployment without laboratory infrastructure dependency.
- EU MDR conformity acceleration:Streamlined IVD technical documentation requirements shorten market access timelines for novel resistance-gene target panels.
- Long-term care facility penetration:Skilled nursing facilities in the United States represent an under-screened admission population where rapid antigen detection can substitute for central lab referral.
Industry Challenges
- Molecular diagnostics specialist shortage:Clinical laboratory science programs produce insufficient nucleic acid amplification technologists to staff expanded testing volumes.
- Legacy LIS integration friction:Hospital information systems require custom middleware development to ingest results from heterogeneous POC device fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MRSA Testing Market |
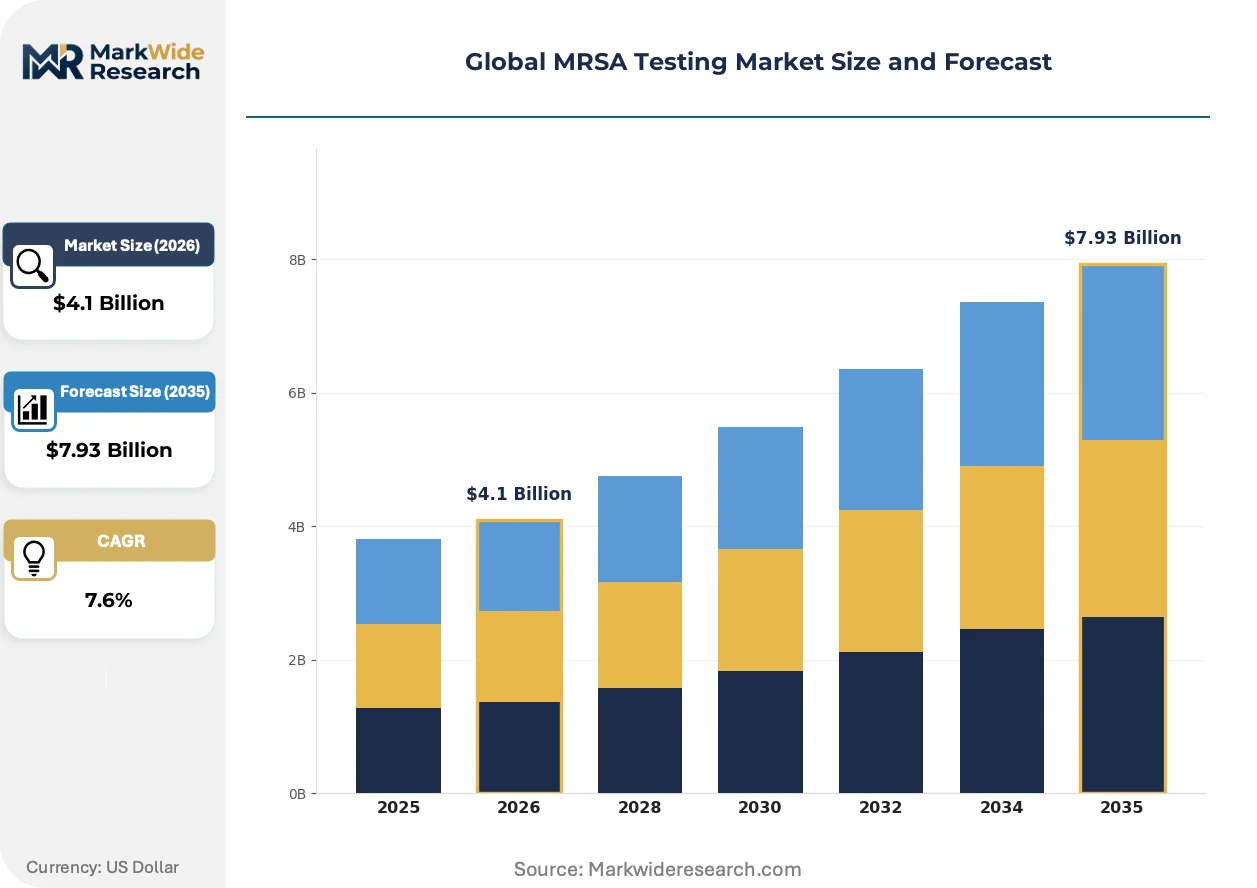
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.93 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Tests, Molecular Diagnostics, Immunoassays, Rapid POC Tests Application: Hospital Infection Control, Community Screening, Surgical Site Monitoring, Long-term Care Surveillance End User: Diagnostic Laboratories, Blood Banks, Academic Research Centers, Clinical Pathology Labs Testing Technology: PCR, DNA Hybridization, Enzyme Immunoassays, Lateral Flow Assays |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, bioMérieux SA, Becton Dickinson and Company, Thermo Fisher Scientific, Cepheid, Hain Lifescience GmbH, 3M, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MRSA Testing Market Shifts & Advancements
Workflow unification across detection modalities is collapsing the traditional separation between phenotypic culture and molecular confirmation, compressing diagnostic pathways into single-platform protocols.
Multiplex PCR panels are unifying mecA/mecC detection with Panton-Valentine leukocidin virulence screening in single-reaction formats. Academic medical centers in Germany and the Netherlands are adopting these consolidated workflows for high-risk admission screening. This convergence is eliminating the need for sequential culture-based confirmation, reducing total laboratory process time by compressing two discrete testing phases into one automated run.
EU MDR technical documentation requirements for IVD manufacturers are forcing earlier engagement with notified bodies during product development. The regulation's enhanced clinical evidence standards extend market access timelines for novel resistance markers. Smaller assay developers are responding by prioritizing CE-marked platforms for well-characterized gene targets over exploratory diagnostic innovations.
Hospital procurement committees are consolidating vendor relationships around integrated platform-service bundles rather than discrete reagent purchasing. This shift disfavors standalone assay suppliers lacking automated instrumentation ecosystems. The United Kingdom's National Health Service procurement frameworks exemplify this concentration, favoring multi-year managed service agreements over transactional consumable contracts.
Global MRSA Testing Market Segmentation
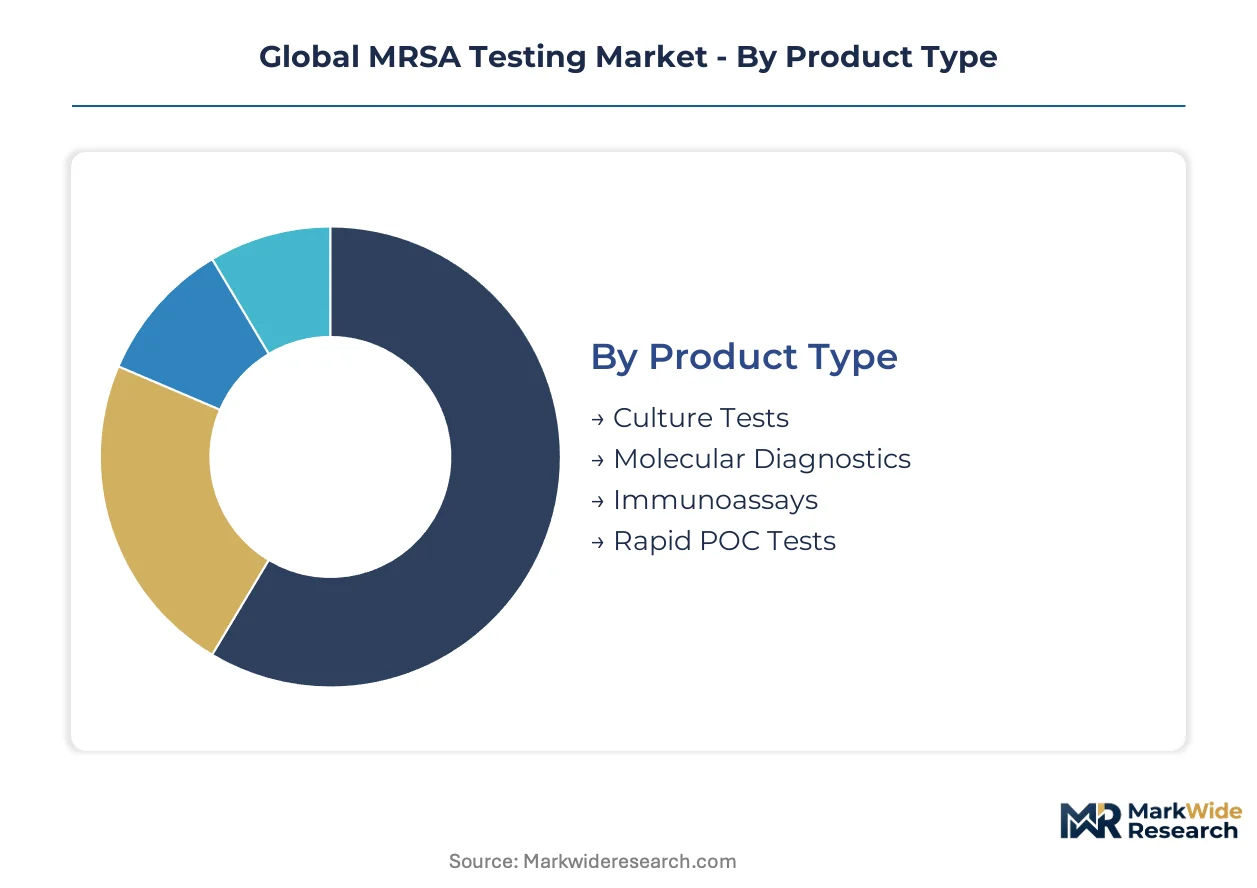
MRSA testing configurations diverge sharply by clinical setting and workflow constraints. Laboratories prioritize throughput and sensitivity while point-of-care deployments trade analytical performance for speed and operator independence.
Product Type:
Customization intensity varies from fully standardized cartridge formats to laboratory-developed protocols requiring significant validation investment.
- Molecular Diagnostics:Nucleic acid amplification platforms detect mecA/mecC gene variants with turnaround times under two hours. Demand concentrates in United States academic medical centers where CMS bundled payment penalties for surgical site infections mandate pre-operative colonization screening. FDA complexity classifications currently restrict these systems to moderate-complexity laboratory sites.
- Rapid POC Tests:Immunochromatographic and molecular cartridge systems deliver results at the bedside without central laboratory infrastructure. Expansion is steepest in German and Dutch hospital networks adopting decentralized admission screening protocols. CLIA waiver pathways are unlocking nursing-unit deployment in United States skilled nursing facilities.
- Culture Tests:Chromogenic and selective media methods retain cost advantages in resource-constrained settings.
- Immunoassays:Antigen detection formats serve blood bank screening and seroprevalence monitoring applications.
Most installed capacity flows through Molecular Diagnostics. Expansion is steepest in Rapid POC Tests.
Application:
Volume distribution tracks infection control liability exposure across care settings.
- Hospital Infection Control:High-risk admission screening and outbreak investigation protocols drive the majority of test volume. United States health systems under CMS Hospital-Acquired Condition Reduction Program penalties deploy molecular panels for orthopedic and cardiac surgery clearance. WHO antimicrobial resistance surveillance mandates are expanding comparable infrastructure in Indian and Brazilian tertiary hospitals.
- Surgical Site Monitoring:Pre-operative nasal swab screening targets methicillin-resistant Staphylococcus aureus decolonization before implant procedures. Demand clusters in German statutory health insurance networks where procedure-specific infection rates determine reimbursement levels. EU MDR technical documentation requirements are lengthening approval timelines for novel resistance-gene target panels in this segment.
- Community Screening:Outpatient and emergency department protocols identify colonized individuals prior to high-risk interventions.
- Long-term Care Surveillance:Skilled nursing facility admission testing represents underpenetrated volume with significant expansion potential.
Hospital Infection Control commands the largest share of current volume. Long-term Care Surveillance is climbing the fastest as regulatory scrutiny intensifies.
End User:
Capital availability and technical staffing determine platform selection across customer types.
- Diagnostic Laboratories:High-throughput reference centers and hospital core laboratories process batch molecular runs for multiple facilities. United States commercial laboratory networks leverage automated platform economies to serve distributed health system clients. FDA platform approval pathways favor established vendors with extensive clinical trial data packages.
- Clinical Pathology Labs:Mid-volume hospital laboratories balance turnaround time requirements against capital constraints. German hospital-based pathology departments are consolidating vendor relationships around multi-year managed service agreements rather than transactional reagent purchasing.
- Blood Banks:Donor screening protocols require high-sensitivity detection with documented seroconversion windows.
- Academic Research Centers:Surveillance studies and resistance mechanism characterization generate demand for research-use-only molecular panels.
Diagnostic Laboratories process the highest absolute test volumes. Clinical Pathology Labs are gaining share fastest as platform consolidation accelerates.
Testing Technology:
Technical maturity and regulatory clearance status create distinct deployment corridors.
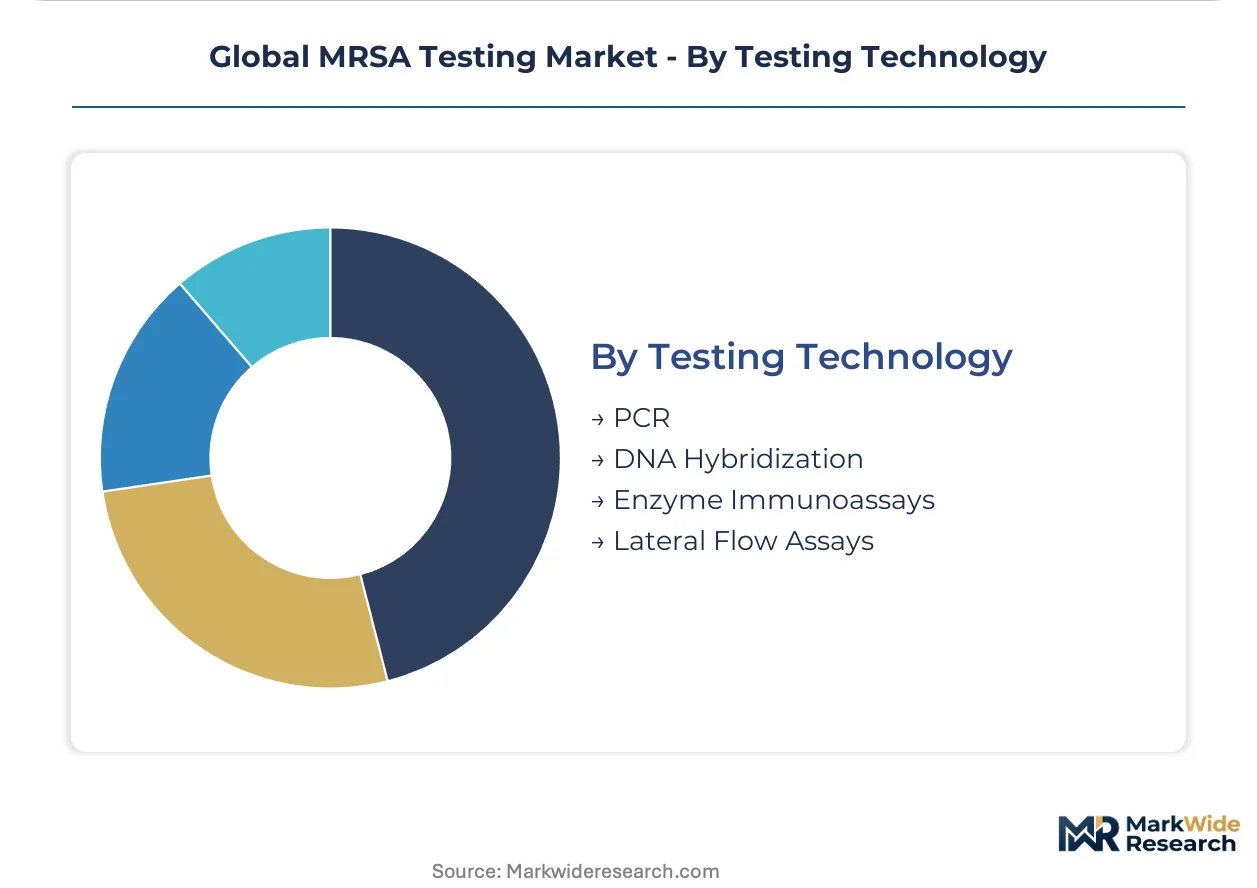
- PCR:Real-time amplification delivers quantitative mecA/mecC detection with internal controls for inhibition monitoring. United States clinical laboratories favor FDA-cleared platforms with established performance in pre-surgical screening indications. Random-access cartridge configurations are displacing batch-based systems in mid-volume settings.
- Lateral Flow Assays:Visual readout immunochromatographic strips require no instrumentation and minimal training. Demand is expanding most quickly in Indian primary health centers and United States long-term care facilities where laboratory infrastructure is limited. WHO prequalification pathways facilitate procurement in low-resource settings.
- DNA Hybridization:Probe-based detection methods serve specialized resistance gene confirmation applications.
- Enzyme Immunoassays:Microplate and automated analyzer formats persist in blood bank and high-volume screening environments.
PCR platforms anchor the installed base. Lateral Flow Assays are expanding most quickly as waived complexity pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MRSA testing infrastructure originated in Northern European hospital networks during the 1990s methicillin resistance surveillance initiatives, then scaled through United States academic medical centers responding to CMS infection control mandates. Platform deployment patterns now diverge sharply by reimbursement structure and regulatory complexity tiering.
United States
CMS Hospital-Acquired Condition Reduction Program penalties drive pre-surgical molecular screening volumes in orthopedic and cardiac service lines. FDA moderate-complexity classifications restrict nucleic acid amplification platforms to centralized laboratory sites. The Boston-Cambridge corridor hosts dense clusters of molecular diagnostic developers supplying cartridge-based systems to multi-hospital networks.
Germany
Statutory health insurance procedure-specific infection rate benchmarks mandate aggressive admission screening in tertiary care facilities. BfArM post-market surveillance requirements extend validation timelines for novel resistance-gene target panels. The Rhine-Ruhr metropolitan region concentrates hospital laboratory networks consolidating vendor relationships around multi-year managed service agreements.
Netherlands
RIVM national antimicrobial resistance surveillance protocols generate standardized testing demand across university medical centers. EU MDR technical documentation requirements for IVD manufacturers lengthen approval pathways for exploratory diagnostic innovations. The Utrecht-Eindhoven corridor anchors implementation of multiplex PCR panels unifying mecA detection with virulence screening.
India
WHO antimicrobial resistance surveillance frameworks expand molecular capacity in secondary and tertiary hospitals previously dependent on chromogenic culture methods. CDSCO import licensing requirements shape platform selection for distributed hospital networks. Mumbai and Delhi metropolitan clusters drive adoption of random-access cartridge systems eliminating batch processing delays.
Brazil
ANVISA IVD registration pathways influence market access timelines for imported molecular diagnostic platforms. Public health system procurement concentrates testing capacity in São Paulo and Rio de Janeiro state hospital networks. Private laboratory chains in the Southeast region deploy automated platform economies to serve distributed health system clients.
Global MRSA Testing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across platform automation and reagent ecosystem depth. The vendor base stratifies into three tiers: integrated diagnostics conglomerates with automated instrumentation ecosystems, specialized molecular assay developers with cartridge-based random-access systems, and standalone media suppliers defending chromogenic culture positions. Consolidation pressure favors multi-year managed service agreements over transactional consumable contracts. Technology licensing and backward integration into proprietary reagent manufacturing represent dominant competitive vectors.
Among Swiss-German diagnostics conglomerates, Roche Diagnostics anchors the integrated platform tier through automated system installed bases sustaining recurring reagent revenue. French specialist bioMérieux SA occupies a position exemplifying chromogenic media anchoring complemented by molecular confirmation assay portfolios. Cepheid represents the cartridge-based random-access archetype competing on reduced batch dependency in mid-volume laboratory settings.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| bioMérieux SA |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| Cepheid |
| Hain Lifescience GmbH |
| 3M |
| QIAGEN |
| Others |
Supply & Pricing Matrix
Polymerase chain reaction reagent raw material indices cascade through three distinct pricing tiers as automated platform contracts lock laboratories into proprietary consumable ecosystems. This input-cost transmission creates widening spreads between cartridge-based molecular systems and commodity chromogenic media.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated platforms from CE-marked cartridge systems and conventional culture methods. Price differentiation hinges on turnaround time performance and regulatory complexity tier, with CLIA-waived rapid tests commanding premiums in nursing-unit deployments. Pricing pressure stems from hospital procurement committees consolidating vendor relationships around multi-year managed service agreements. Long-term care facilities exhibit highest price sensitivity due to capital constraints, while academic medical centers under CMS bundled payment penalties prioritize sensitivity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch precision optics suppliers providing fluorescence detection modules for real-time PCR platforms. Manufacturing concentration clusters in the United States, Germany, and China, with thermal cycler components drawing from Taiwanese semiconductor foundries and Swiss precision machining houses. Supply chain risk centers on EU MDR technical documentation delays extending approval timelines for novel resistance-gene target panels. Distribution runs through hospital procurement frameworks and group purchasing organizations consolidating multi-facility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA moderate-complexity classifications in the United States delay point-of-care deployment that EU MDR streamlined pathways already permit in German hospital networks.
For Market Incumbents: Hedge against cartridge-based random-access displacement by deepening backward integration into proprietary reagent manufacturing. Consolidate hospital laboratory vendor relationships through multi-year managed service agreements before CLIA waiver pathways unlock nursing-unit competition. Anchor position in United States academic medical centers where CMS surgical site infection penalties sustain molecular screening volumes. For New Entrants and Emerging Players: Capture underpenetrated long-term care surveillance volume in United States skilled nursing facilities where rapid antigen detection substitutes for central lab referral. Target Indian secondary hospitals expanding molecular capacity under WHO antimicrobial resistance surveillance frameworks. Lead with lateral flow immunoassay formats requiring minimal capital investment and WHO prequalification procurement eligibility. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized molecular assay developers possessing CE-marked platforms for well-characterized gene targets. Long-term viability over a multi-year horizon favors cartridge-based random-access specialists over chromogenic media suppliers facing substitution pressure. Watch FDA guidance evolution on waived molecular complexity as the inflection signal for point-of-care expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Pursuit | Unlocks nursing-unit deployment without laboratory infrastructure dependency in United States skilled nursing facilities. |
| EU MDR Technical Documentation Acceleration | Shortens market access timelines for novel resistance-gene target panels through notified body pre-submission engagement. |
| Hospital System Partnership | Secures multi-year managed service agreements consolidating vendor relationships around integrated platform-service bundles. |
| Reimbursement Strategy Development | Aligns test menu configuration with CMS bundled payment penalties for surgical site infections in orthopedic service lines. |
| Multiplex PCR Panel Expansion | Unifies mecA/mecC detection with Panton-Valentine leukocidin screening in single-reaction formats for German academic medical centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital laboratory directors, molecular diagnostics specialists, GPO contracts managers, and biomedical engineers with secondary validation against FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and EU MDR technical documentation repositories. Bottom-up test volume modeling and top-down market sizing triangulated across segmentation dimensions.
Historical reference periods anchored projections across the analysis window, with CAGR derivation reflecting instrument placement cycles, reagent consumption curves, and regulatory approval timelines. Segmentation modeling incorporated product type, application, end user, testing technology, and regional reimbursement structure. Industry-specific inputs included CLIA complexity tier migration rates and WHO surveillance framework adoption trajectories.
Regulatory pathway delays, platform consolidation velocity, and antimicrobial resistance surveillance mandate expansion are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about laboratory infrastructure investment and point-of-care complexity reclassification. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market