
 Middle East and Africa Cell Counting Market | 2026-2036
Middle East and Africa Cell Counting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cell Counting Market Analytics
South African laboratory instrument distributors is consolidating around automated cell counting platforms as public health programs scale molecular diagnostics capacity. Danaher Corporation leverages its Beckman Coulter life sciences division to sustain strong service infrastructure across Johannesburg and Cape Town. Bio-Rad Laboratories, Inc. competes on flow cytometry-based counting systems optimized for CD4 T-cell enumeration in HIV patient monitoring. Sysmex Corp dominates hematology analyzer placements in South Africa's National Health Laboratory Service network.
Cell counting encompasses quantitative methods for enumerating viable and non-viable cells in biological samples, with modern automated systems achieving throughput exceeding 10,000 cells per second using electrical impedance or digital imaging principles. These instruments serve critical quality control functions in bioprocessing, clinical diagnostics, and regenerative medicine workflows across the region. Automated Counters command the largest installed base among product types due to throughput advantages in high-volume hospital laboratories. Flow Cytometry technology leads technology segmentation for immunophenotyping applications, while Contract Research Organizations represent the fastest-growing end user category as pharmaceutical outsourcing expands into Egypt and Morocco.
South Africa's SAHPRA and Egypt's Egyptian Drug Authority regulate in-vitro diagnostic instruments under converging technical standards that increasingly reference ISO 15189 laboratory accreditation requirements. These frameworks shape procurement decisions by mandating local calibration support and traceable quality management systems for cell counting devices. Stakeholders must monitor harmonization between national regulatory pathways and the African Medicines Agency's emerging continental prequalification scheme to anticipate market access shifts.
Market Dynamics
Automated cell counting platforms are displacing manual hemocytometry across Middle East and Africa clinical laboratories as SAHPRA and Egypt's national pharmaceutical regulator tighten ISO 15189-aligned quality mandates. This instrument upgrade cycle concentrates purchasing power within South Africa's National Health Laboratory Service and Egypt's centralized procurement frameworks.
Growth Catalysts
- SAHPRA registration harmonization:South Africa's tightened in-vitro diagnostic device requirements push laboratories toward validated automated platforms with traceable calibration chains.
- HIV program scale-up:CD4 T-cell enumeration demand from South Africa's national treatment program drives flow cytometry analyzer placements in Gauteng province academic medical centers.
- Bioprocessing quality control:Contract manufacturing organizations in Egypt and Morocco adopt electrical impedance counters for cell viability monitoring in monoclonal antibody production workflows.
Market Restraints
- Reagent supply concentration:Proprietary consumables for hematology analyzers flow through single-source distribution agreements concentrated in Johannesburg and Cairo, creating vulnerability to foreign exchange volatility.
- Technical skill scarcity:Flow cytometry operation and gating analysis require specialized training unavailable in secondary cities across the region, limiting platform utilization rates.
- Capital intensity barriers:Automated counter procurement costs exceed public health laboratory capital budgets in Ethiopia, Nigeria, and Kenya, constraining addressable market expansion.
Strategic Opportunities
- Morocco pharmaceutical outsourcing:Contract research organizations in Casablanca-Rabat corridor are building GMP-compliant cell therapy manufacturing capacity requiring validated counting systems.
- Digital imaging convergence:Artificial intelligence-enhanced brightfield microscopy is merging with traditional electrical impedance methods, enabling label-free viability assessment.
- East African laboratory networks:Kenya's devolved health system creates procurement nodes in Nairobi, Mombasa, and Kisumu for distributed analyzer placement outside South African supply orbits.
Industry Challenges
- Service engineer scarcity:Field maintenance capacity for complex flow cytometry systems concentrates in Johannesburg and Cape Town, leaving Lagos and Nairobi installations with extended downtime exposure.
- Legacy LIS integration:South Africa's NHLS network operates heterogeneous laboratory information systems that resist standardized data export from newer automated counters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cell Counting Market |
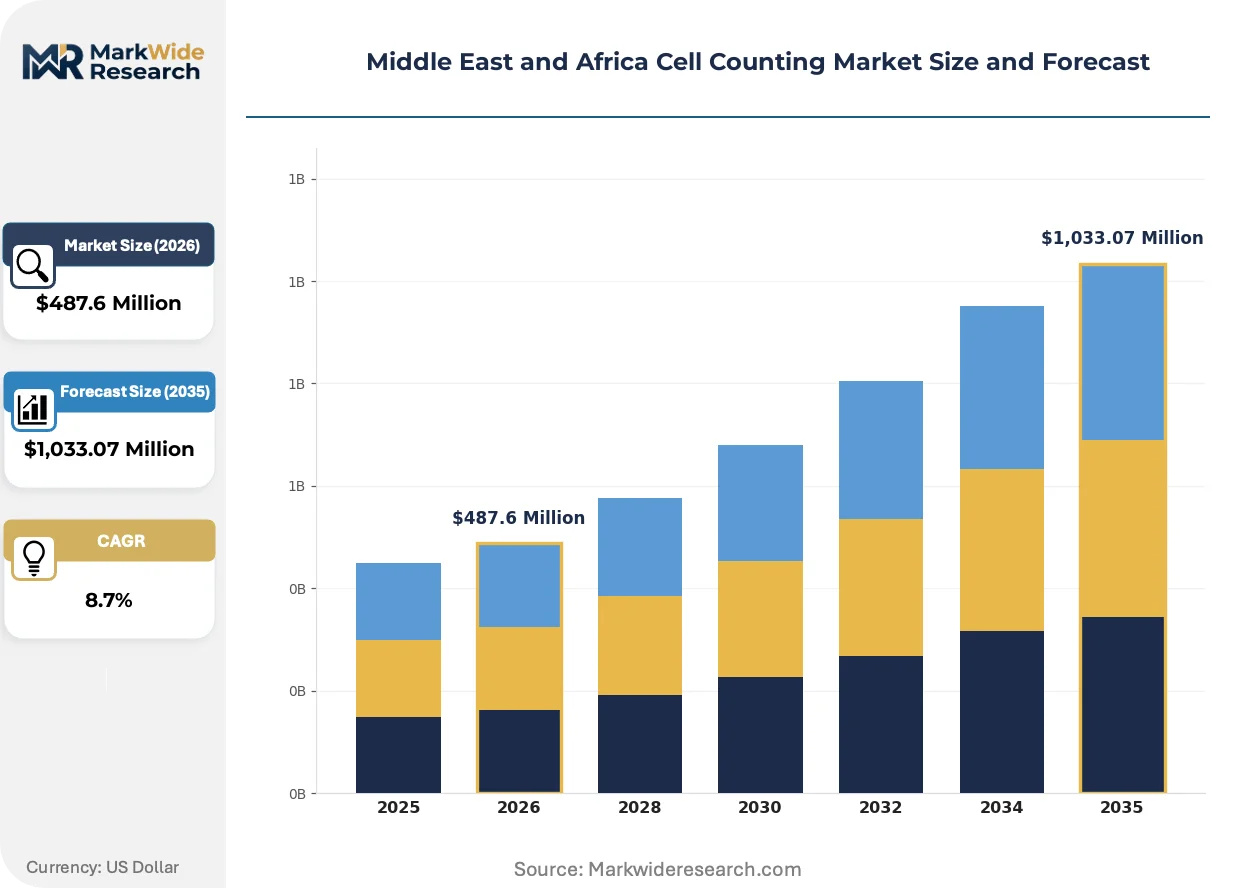
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Counters, Manual Counters, Image-Based Systems, Microfluidic Devices Technology: Flow Cytometry, Hemocytometers, Digital Imaging, Electrical Impedance Application: Clinical Diagnostics, Drug Discovery, Stem Cell Research, Environmental Monitoring End User: Biotechnology Firms, Academic Institutes, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Agilent Technologies, Inc., Shimadzu Corporation, Nikon Corporation, Becton, Dickinson and Company, Corning Incorporated, Danaher Corporation, Bio-Rad Laboratories, Inc., Sysmex Corp, Thermo Fisher Scientific Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cell Counting Market Evolving Landscape
Portable cell counting devices are penetrating point-of-care tuberculosis diagnostics in resource-limited settings, compressing the traditional centralized laboratory model. This shift intersects with regulatory pressure for decentralized quality assurance and procurement fragmentation across national, provincial, and private health system tiers.
Image-based cytometry is decentralizing cell enumeration from core hospital laboratories to district-level clinics in South Africa's KwaZulu-Natal and Eastern Cape provinces. Community health centers are adopting smartphone-connected counting chambers for CD4 monitoring. This technology is compressing sample turnaround times from days to hours while reducing cold-chain transport requirements for peripheral blood draws.
Egypt's national pharmaceutical regulator has aligned in-vitro diagnostic technical standards with ISO 15189 laboratory accreditation requirements, mandating local calibration support and traceable quality management systems. This framework is elevating procurement criteria above price-only evaluation. Multinational manufacturers are responding by establishing Cairo-based service depots and Arabic-language training programs.
After-sales service unbundling is disrupting traditional analyzer purchasing in Saudi Arabia and UAE hospital networks. Buyers are separating instrument acquisition from maintenance contracts, engaging third-party biomedical engineers for routine calibration. This pattern is most visible in Dubai's private healthcare sector, where procurement committees prioritize multi-vendor service flexibility over single-source bundled agreements.
Middle East and Africa Cell Counting Market Segmentation
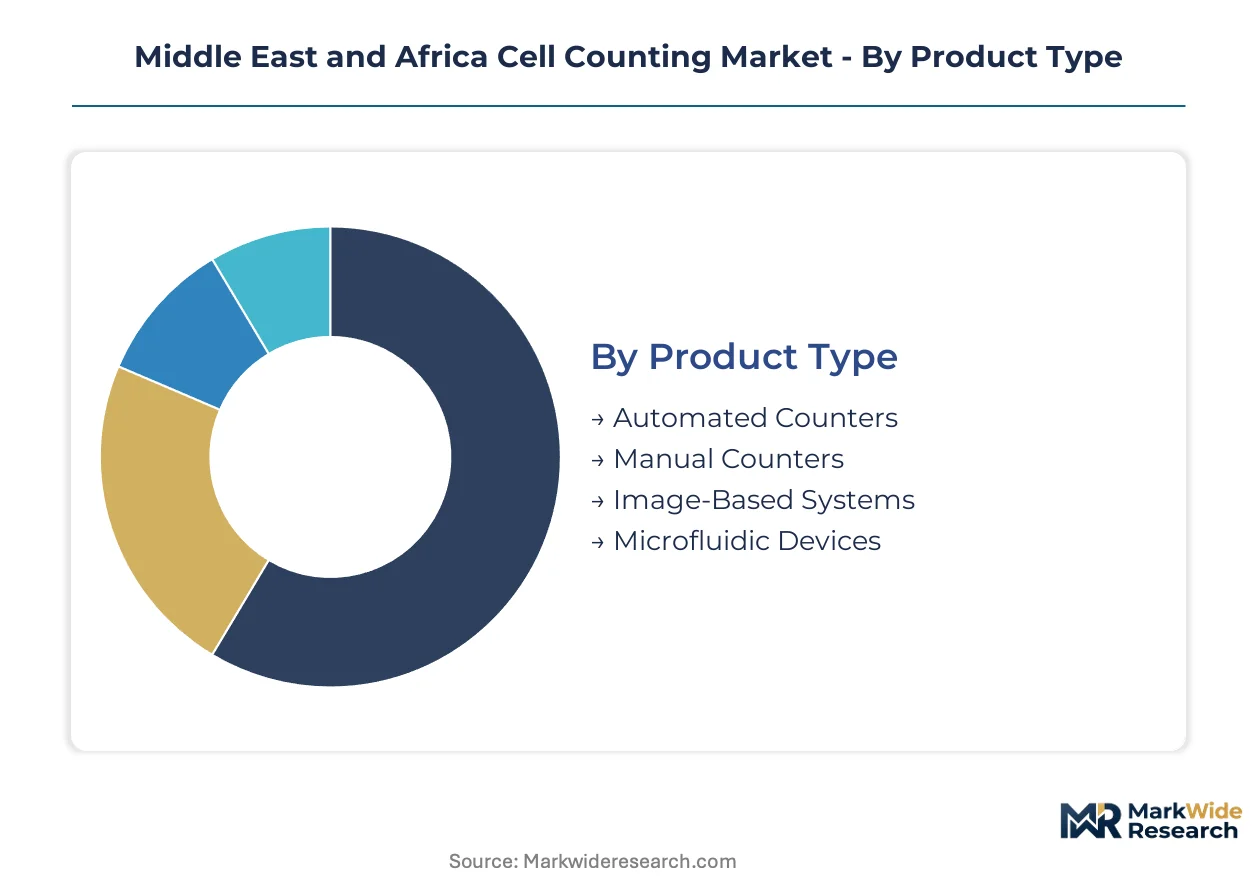
Cell counting market segmentation in the Middle East and Africa reflects divergent procurement priorities across public health systems, academic research networks, and emerging bioprocessing clusters. Each dimension captures distinct technology preferences shaped by capital availability, regulatory compliance requirements, and technical workforce depth.
Product Type:
Instrument upgrade cycles across South African and Egyptian laboratories are accelerating replacement of manual methods with automated platforms that satisfy tightened ISO 15189-aligned quality mandates.
- Automated Counters:Electrical impedance and digital imaging systems process samples at throughputs exceeding 10,000 cells per second. South Africa's National Health Laboratory Service concentrates procurement of these platforms for tuberculosis and HIV monitoring programs in Gauteng province.
- Image-Based Systems:Artificial intelligence-enhanced brightfield microscopy enables label-free viability assessment without fluorescent stains. Demand clusters in Morocco's Casablanca-Rabat pharmaceutical corridor where contract manufacturers require GMP-compliant quality control.
- Manual Counters:Hemocytometers remain prevalent in resource-constrained secondary cities across Ethiopia and Kenya where capital budgets exclude automated alternatives.
- Microfluidic Devices:Smartphone-connected counting chambers are penetrating point-of-care diagnostics in South Africa's KwaZulu-Natal and Eastern Cape provinces.
Automated Counters sits at the top of the volume ranking, with Image-Based Systems climbing the fastest.
Technology:
Technology selection tracks application specificity, with high-complexity methods commanding premium placement in academic medical centers while simpler approaches serve decentralized screening programs.
- Flow Cytometry:Laser-based immunophenotyping systems enable multi-parameter CD4 T-cell enumeration critical to South Africa's national HIV treatment program. Sysmex and Beckman Coulter field service infrastructure concentrates in Johannesburg and Cape Town.
- Electrical Impedance:Coulter principle counters dominate hematology analyzer placements across Egypt's centralized hospital networks. The Egyptian Drug Authority mandates local calibration support that favors established service footprints.
- Digital Imaging:CCD and CMOS sensor-based systems are displacing manual microscopy in Saudi Arabia's university hospital laboratories.
- Hemocytometers:Traditional glass counting chambers persist in Nigeria's private diagnostic chains where reagent cost sensitivity exceeds throughput requirements.
Electrical Impedance holds the broadest installed base, though Flow Cytometry is gaining share fastest among technology categories.
Application:
Application demand correlates with national disease burden profiles and research funding allocations, creating geographic specialization across the region.
- Clinical Diagnostics:Patient sample processing for infectious disease monitoring drives analyzer placements in South Africa's public health laboratory network. SAHPRA registration requirements favor validated automated platforms with traceable calibration chains.
- Drug Discovery:High-content screening workflows in Egypt's pharmaceutical R&D centers require multi-well plate compatible counting systems. The country's national pharmaceutical regulator has aligned technical standards with ISO 15189 requirements.
- Stem Cell Research:Regenerative medicine applications concentrate in UAE academic medical centers with advanced cell therapy manufacturing ambitions.
- Environmental Monitoring:Microbial enumeration for water quality assessment operates across Morocco's expanding public health laboratory infrastructure.
Clinical Diagnostics maintains dominant volume position, while Drug Discovery is expanding most quickly as pharmaceutical outsourcing deepens in North Africa.
End User:
End user procurement behavior diverges sharply between centralized public tenders and decentralized private purchasing, shaping vendor go-to-market strategies.
- Contract Research Organizations:GMP-compliant cell therapy manufacturing capacity in Morocco and Egypt requires validated counting systems with complete IQ/OQ/PQ documentation. These organizations are expanding most quickly among end user categories.
- Pharmaceutical Companies:Monoclonal antibody producers in Egypt adopt electrical impedance counters for bioprocess quality control, with procurement flowing through Cairo-based distribution agreements.
- Academic Institutes:Research funding in South Africa's Johannesburg-Pretoria corridor supports flow cytometry analyzer placements for immunology and oncology studies.
- Biotechnology Firms:Early-stage cell therapy developers in Kenya's Nairobi biotechnology cluster represent emerging demand outside traditional South African supply orbits.
Contract Research Organizations lead expansion velocity, though Pharmaceutical Companies retain the largest committed capital base for high-throughput systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands the region's densest laboratory infrastructure while Egypt's centralized procurement frameworks concentrate purchasing power in Cairo-based hospital networks.
South Africa
Gauteng province drives analyzer demand through Johannesburg and Pretoria's academic medical centers supporting tuberculosis and HIV monitoring programs. SAHPRA tightened in-vitro diagnostic registration requirements, pushing laboratories toward validated automated platforms with traceable calibration chains. The National Health Laboratory Service concentrates hematology analyzer placements in its centralized network.
Egypt
The Egyptian Drug Authority aligned technical standards with ISO 15189 laboratory accreditation requirements, elevating procurement criteria above price-only evaluation. Cairo-based hospital networks dominate electrical impedance counter placements for patient sample processing. Contract research organizations in the city's pharmaceutical corridor build GMP-compliant cell therapy manufacturing capacity requiring validated counting systems.
Morocco
Pharmaceutical outsourcing expansion in the Casablanca-Rabat corridor creates demand for image-based systems enabling label-free viability assessment. The country's national pharmaceutical regulator mandates local calibration support for imported diagnostic instruments. Contract manufacturers in this cluster adopt artificial intelligence-enhanced brightfield microscopy for monoclonal antibody production quality control.
United Arab Emirates
Dubai's private healthcare sector unbundles after-sales service from analyzer purchasing, engaging third-party biomedical engineers for routine calibration. MOHAP oversees multi-vendor procurement committees prioritizing service flexibility over single-source bundled agreements. Academic medical centers in Abu Dhabi develop advanced cell therapy manufacturing ambitions driving stem cell research applications.
Saudi Arabia
SFDA regulates in-vitro diagnostic instruments under converging technical standards with Gulf Cooperation Council harmonization initiatives. Hospital networks in Riyadh and Jeddah separate instrument acquisition from maintenance contracts, compressing traditional vendor relationships. University hospital laboratories adopt digital imaging systems displacing manual microscopy for research applications.
Middle East and Africa Cell Counting Market Competitive Landscape
United States-based conglomerates anchor one tier through life sciences divisions with established service infrastructure; Japanese specialists hold another through hematology analyzer dominance in centralized laboratory networks. Market structure consolidates around multinational instrument manufacturers with regional calibration depots and Arabic-language training programs. Three archetypes prevail: diversified conglomerates with diagnostic portfolios, pure-play hematology specialists, and flow cytometry-focused immunophenotyping vendors. Competitive moves concentrate on Cairo-based service depot establishment and Johannesburg field engineer capacity expansion.
Within the diversified conglomerate tier, Danaher Corporation and Thermo Fisher Scientific Inc. exemplify players leveraging broad life sciences portfolios to sustain maintenance infrastructure across Johannesburg and Cape Town. Sysmex Corp occupies a distinct position as a hematology-focused specialist with deep placements in South Africa's National Health Laboratory Service network. These three companies represent the dominant competitive anchors shaping regional procurement negotiations and service level agreements.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Shimadzu Corporation |
| Nikon Corporation |
| Becton, Dickinson and Company |
| Corning Incorporated |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Sysmex Corp |
| Thermo Fisher Scientific Inc. |
| Others |
Value Network & Pricing Analysis
Field service engineer concentration in Johannesburg and Cape Town creates labor-cost differentials that widen pricing-tier spreads between premium bundled service contracts and unbundled third-party maintenance arrangements.
Pricing Analysis
Capacity additions in Egypt and Morocco are reshaping price floors for electrical impedance counters as Cairo-based service depots reduce premium logistics surcharges. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15189-validated platforms with traceable calibration chains from basic hematology analyzers. Cost compression in the economy tier is intensifying because Ethiopian and Kenyan public health laboratories face capital intensity barriers. Pharmaceutical companies in North Africa demonstrate least price sensitivity due to GMP compliance mandates, while Nigeria's private diagnostic chains exhibit highest reagent cost sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with proprietary consumables for hematology analyzers flowing through Johannesburg and Cairo distribution agreements. Manufacturing concentration centers on Japan, the United States, and Germany for core instrument platforms, while reagent production draws from regional formulation facilities. Laser optics and Coulter principle electrodes represent critical component dependencies with limited secondary sourcing. Tariff exposure runs through foreign exchange volatility in Egyptian pound and South African rand-denominated procurement. Distribution runs through consolidated laboratory instrument distributors with exclusive territorial agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa cell counting market compounds steadily as infectious disease monitoring programs institutionalize automated platform procurement across national health laboratory networks.
For Market Incumbents: Hedge against after-sales service unbundling by establishing Cairo-based Arabic-language training programs and third-party biomedical engineer certification tracks. SAHPRA registration harmonization threatens margin compression for non-validated platforms. Vertical integration into reagent formulation within Johannesburg and Cairo reduces foreign exchange exposure on proprietary consumables. For New Entrants and Emerging Players: Smartphone-connected microfluidic counting chambers offer a technology-first wedge into South Africa's KwaZulu-Natal and Eastern Cape district-level clinics. Kenya's devolved health system represents the most penetrable geography with procurement nodes in Nairobi, Mombasa, and Kisumu outside established supply orbits. Partner with East African laboratory networks for distributed analyzer placement rather than competing head-to-head in Gauteng province. For Investors and Strategic Acquirers: Diversified life sciences conglomerates are the most active acquirer in this space, seeking regional service infrastructure to complement diagnostic portfolios. Target acquisition archetypes include flow cytometry-focused immunophenotyping vendors with Johannesburg field engineer capacity. Watch for African Medicines Agency continental prequalification scheme harmonization as inflection indicator for market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cairo Service Depot Establishment | Egyptian Drug Authority ISO 15189 alignment mandates local calibration support for market access. |
| Arabic-Language Training Program | MOHAP and SFDA procurement committees prioritize service flexibility with native-language technical documentation. |
| Third-Party Biomedical Engineer Certification | Dubai's private healthcare sector unbundling trend compresses traditional single-source bundled agreements. |
| Reagent Formulation Regionalization | Foreign exchange volatility in Johannesburg and Cairo procurement creates cost advantage for localized production. |
| East African Distribution Partnership | Kenya's devolved health system creates procurement nodes outside South African supply concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at SAHPRA and the Egyptian Drug Authority with secondary validation from hospital procurement databases, GPO contracts, ISO 15189 accreditation records, and in-vitro diagnostic registration filings. Bottom-up analyzer placement tracking and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, technology, application, and end user dimensions shaped the analytical framework over the projection horizon. Modeled dimensions included electrical impedance versus flow cytometry technology splits, public health laboratory versus contract research organization end-user clusters, and regional regulatory framework variations. CAGRs derived from instrument replacement cycle analysis and molecular diagnostics capacity expansion trajectories. Infectious disease program scale-up rates and bioprocessing quality control adoption curves served as key forecast inputs.
The model holds under stable regulatory harmonization between national pathways and African Medicines Agency prequalification; deviation in SAHPRA registration timelines or Egyptian Drug Authority technical standard revisions would shift instrument upgrade cycle assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Biochips Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market