
 Subcutaneous Biologics Market | 2026-2036
Subcutaneous Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Subcutaneous Biologics Market Outlook
Buyer concentration among hospital purchasing consortia and specialty clinic networks is expanding as integrated delivery networks negotiate centralized biologics contracts. AbbVie leverages its immunology portfolio depth to sustain formulary positioning across these consolidating buyers. Amgen anchors its presence through manufacturing scale in monoclonal antibody production, while Novo Nordisk dominates diabetes-oriented subcutaneous delivery with in-house production of injectable pens.
Subcutaneous biologics are large-molecule therapeutic proteins formulated for administration into the fatty tissue beneath the skin, typically requiring molecular weights above 10 kDa and optimized viscosity profiles for patient self-injection through 25-31 gauge needles. Monoclonal antibodies occupy the largest revenue pool due to chronic dosing requirements in oncology and autoimmune disorders, while auto-injectors represent the fastest-growing delivery method as manufacturers prioritize patient adherence and reduced healthcare utilization. Prefilled syringes retain significant share in institutional settings where nursing oversight remains standard.
The FDA's biosimilar interchangeability standards and the EMA's MDR requirements for combination drug-device products create divergent compliance burdens that shape market access timelines. The WHO's prequalification pathway for biotherapeutics adds complexity for manufacturers targeting lower-middle-income procurement channels. Stakeholders must monitor evolving FDA guidance on immunogenicity testing for subcutaneous reformulations of intravenous originators, as this technical barrier determines which developers can compete in the largest reimbursement markets.
Market Dynamics
Payer-driven site-of-care migration from infusion centers to home administration is compressing delivery infrastructure requirements and rewiring reimbursement logic across therapeutic categories.
Growth Catalysts
- FDA Biosimilar Interchangeability Pathway:The streamlined approval framework accelerates competitive entry for subcutaneous reformulations of intravenous originators, expanding patient access to self-administered alternatives in immunology and oncology.
- Auto-injector Platform Engineering:Advances in needle-retraction mechanisms and viscosity-tolerant spring systems enable higher-concentration biologic formulations, reducing injection frequency and improving adherence in chronic disease management.
- German Homecare Infrastructure:Dense networks of specialized nursing services and favorable reimbursement for domestic self-injection create a template for outpatient biologics expansion across European markets.
Market Restraints
- High-Purity Excipient Supply Concentration:Limited qualified suppliers of pharmaceutical-grade polysorbates and histidine buffers in Switzerland and Germany create input vulnerability for formulation stability.
- EMA MDR Combination Product Requirements:The expanded technical documentation and clinical evidence standards for drug-device subcutaneous systems extend approval timelines by 18-24 months compared with standalone biologics.
- Intravenous-to-Subcutaneous Immunogenicity Risk:Route-switching studies demonstrating equivalent safety profiles impose additional Phase III burden that filters out development-stage competitors with constrained capital.
Strategic Opportunities
- Japanese Aging Demographics:METI incentives for reducing hospital bed utilization align with subcutaneous self-administration models in rheumatoid arthritis and psoriasis, where patient mobility limitations favor home therapy.
- WHO Prequalification Pathway:The emerging procurement channel for lower-middle-income countries creates volume opportunity for simplified cold-chain formulations of established monoclonal antibodies.
- Connected Device Integration:Convergence of Bluetooth-enabled auto-injectors with electronic health record systems enables real-world adherence data capture that supports value-based contracting with US payers.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Shortage of specialists in high-concentration protein formulation and shear-stress mitigation constrains manufacturing scale-up for subcutaneous-ready drug substances.
- Legacy IV Infrastructure Stranded Costs:Hospital systems face write-down pressures on infusion center investments as outpatient biologics programs shift capital toward home nursing networks and patient training platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subcutaneous Biologics Market |
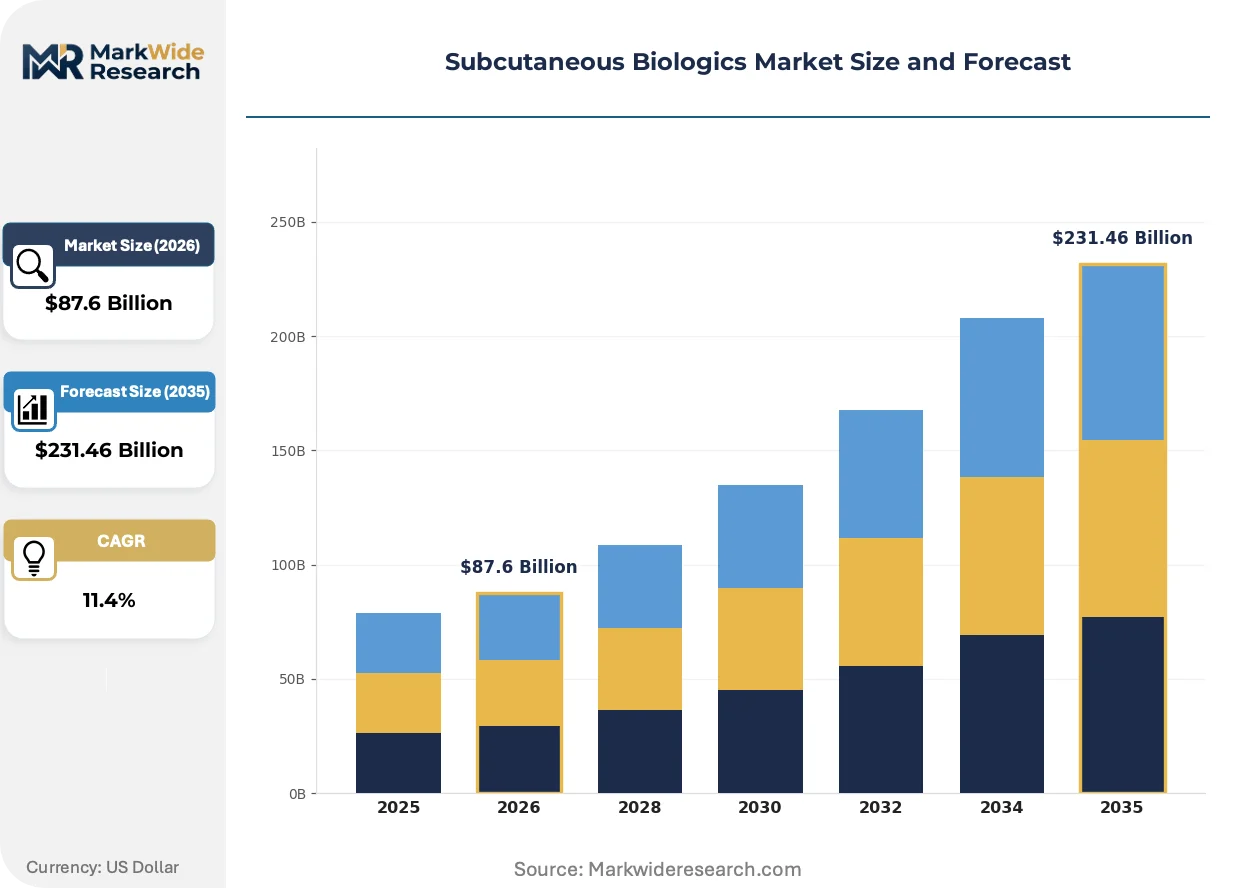
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immunoglobulins, Hormones, Enzymes Delivery Method: Auto-Injectors, Prefilled Syringes, Injectable Pens, Infusion Pumps Therapy Area: Oncology, Autoimmune Disorders, Diabetes, Infectious Diseases End User: Hospitals, Homecare Settings, Specialty Clinics, Research Institutions |
| Companies Covered | AbbVie, Amgen, Roche, Novartis, Pfizer, Novo Nordisk, Biogen, Sanofi, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subcutaneous Biologics Market Strategic Shifts
Delivery technology convergence with digital adherence monitoring is restructuring how manufacturers demonstrate value to consolidated purchasers and differentiate beyond molecular attributes.
Wearable bolus injectors for large-volume subcutaneous administration are decentralizing oncology supportive care from ambulatory infusion suites to patient homes. Community oncology networks in the United States are piloting these patch-pump systems for trastuzumab and rituximab biosimilars, compressing reimbursement site-of-care differentials and shifting nursing labor toward remote monitoring rather than chair time.
The EMA's 2024 MDR guidance on needle-based combination products tightens clinical validation requirements for human factors testing and use-error mitigation. Manufacturers must now submit comprehensive patient handling studies across age and dexterity spectrums, delaying European market entry for device-naive developers while favoring established auto-injector platforms with existing usability dossiers.
Hospital purchasing consortia are consolidating biologics procurement under single-source contracts with adherence-linked rebate structures. Specialty pharmacy networks displace traditional wholesale distribution for subcutaneous therapies in the United States, capturing patient onboarding and training functions that previously resided with clinic nursing staff.
Subcutaneous Biologics Market Segmentation
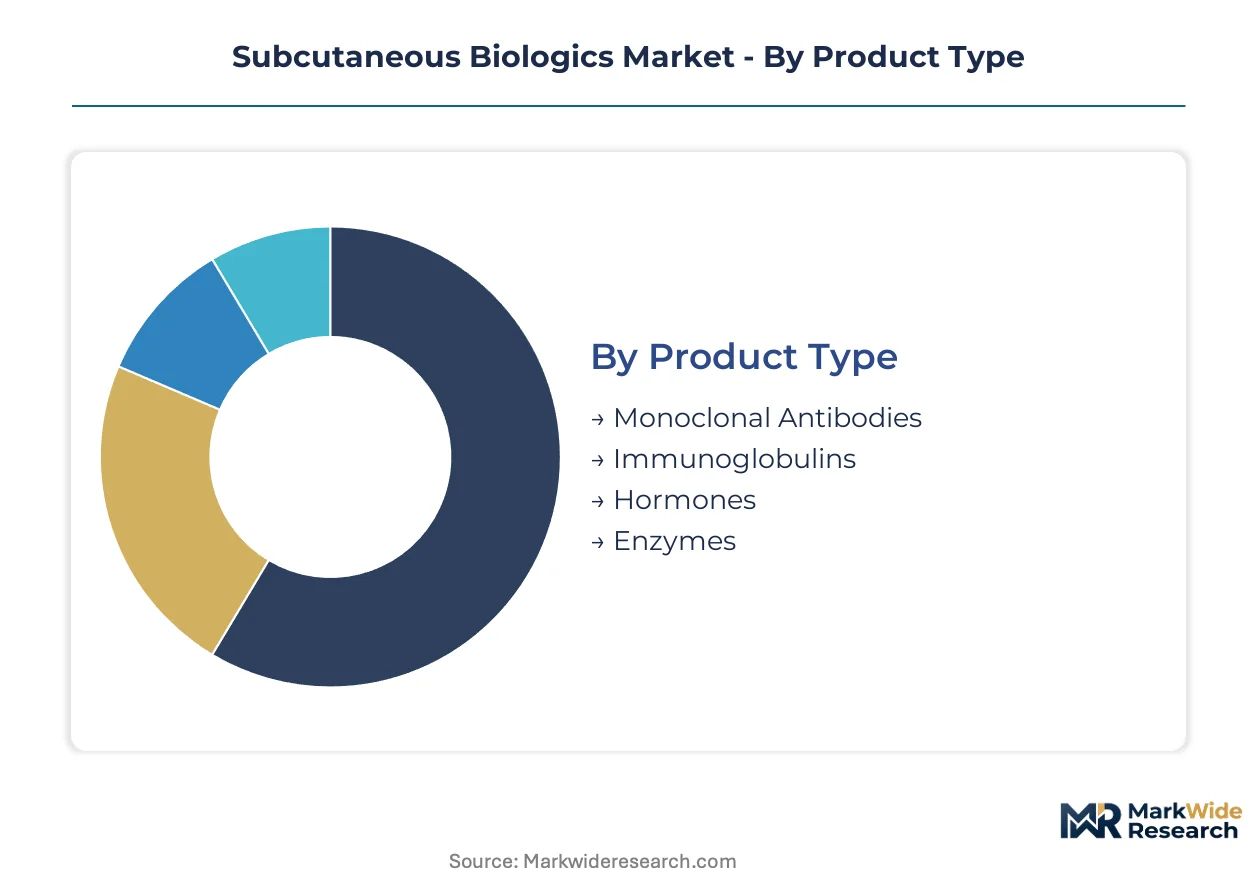
Subcutaneous biologics segmentation reveals how formulation requirements, device complexity, and site-of-care economics fragment procurement patterns across therapeutic categories. Manufacturers must align R&D investment with the compliance burdens and reimbursement logic governing each segment boundary.
Product Type:
FDA biosimilar interchangeability standards and EMA MDR requirements impose divergent clinical evidence demands across molecular classes, with monoclonal antibodies facing the steepest immunogenicity testing thresholds.
- Monoclonal Antibodies:Large-molecule therapeutic proteins engineered for high-affinity target binding, typically exceeding 150 kDa molecular weight. Chronic dosing regimens in oncology and autoimmune disorders concentrate demand in the United States and Germany, where self-administration reimbursement frameworks are mature. EMA stability testing requirements for subcutaneous reformulations extend development timelines compared with intravenous originators.
- Immunoglobulins:Polyclonal antibody preparations derived from pooled human plasma, requiring specialized viral inactivation and viscosity optimization for subcutaneous delivery. Demand clusters in homecare settings for primary immunodeficiency, with Japanese regulatory pathways favoring domestic plasma sourcing over imported alternatives.
- Hormones:Recombinant protein therapies including insulin analogues and growth factors, characterized by lower molecular weights and established cold-chain distribution. Novo Nordisk's captive manufacturing of injectable pens dominates diabetes-oriented delivery.
- Enzymes:Replacement therapies for rare metabolic disorders, requiring ultra-high purity standards and limited-batch production economics. Payer pressure for outcomes-based contracting constrains pricing flexibility in this orphan-disease segment.
Monoclonal antibodies sit at the top of the volume ranking, with immunoglobulins climbing the fastest as plasma fractionation capacity expands across European collection networks.
Delivery Method:
Device selection directly determines patient adherence economics and the intensity of nursing labor required for therapy initiation, creating tiered cost structures across administration settings.
- Auto-Injectors:Spring-powered systems with needle-retraction mechanisms enabling single-handed operation, engineered for viscosity-tolerant delivery of high-concentration formulations. Bluetooth-enabled variants capturing real-world adherence data are gaining share fastest in US value-based contracting environments.
- Prefilled Syringes:Glass-barrel systems with staked needles, retaining institutional preference where nursing oversight remains standard. German hospital purchasing consortia negotiate centralized contracts favoring established suppliers with existing EMA usability dossiers.
- Injectable Pens:Dial-dose systems with cartridge-based drug reservoirs, dominant in diabetes and growth hormone therapy where dose titration flexibility is clinically essential. METI incentives in Japan align pen-based self-administration with bed-reduction targets in aging patient populations.
- Infusion Pumps:Wearable bolus injectors for large-volume subcutaneous administration, decentralizing oncology supportive care from ambulatory suites to patient homes. US community oncology networks pilot these patch-pump systems for trastuzumab biosimilars.
Auto-injectors command the highest patient preference scores, while prefilled syringes retain dominant institutional volume through hospital formulary inertia.
Therapy Area:
Reimbursement site-of-care differentials and chronic versus acute treatment duration reshape competitive intensity and manufacturing scale requirements across therapeutic applications.
- Oncology:Supportive care biologics including granulocyte colony-stimulating factors and anti-emetics, with biosimilar entry compressing originator pricing. Wearable pump adoption is accelerating in US community oncology networks seeking to reduce chair-time costs.
- Autoimmune Disorders:Anti-TNF and anti-IL agents requiring lifelong administration, where FDA interchangeability standards enable pharmacy-level substitution. AbbVie's formulary positioning across integrated delivery networks sustains volume leadership in rheumatoid arthritis and psoriasis.
- Diabetes:Insulin and GLP-1 receptor agonist delivery, where in-house device manufacturing at Novo Nordisk and Eli Lilly creates captive ecosystem lock-in. Japanese aging demographics favor pen-based home administration over clinic-based infusion.
- Infectious Diseases:Prophylactic and therapeutic antibodies, including COVID-19 monoclonals and hepatitis B immunoglobulins. WHO prequalification pathways create procurement access for simplified cold-chain formulations in lower-middle-income markets.
Autoimmune disorders anchor the revenue base through chronic dosing, with oncology delivery method innovation expanding most quickly as site-of-care migration accelerates.
End User:
Capital allocation and staffing models diverge sharply between institutional settings with legacy infusion infrastructure and emerging homecare platforms requiring patient training investments.
- Hospitals:Integrated delivery networks with stranded costs in infusion center real estate, now pivoting capital toward outpatient biologics programs and remote monitoring platforms. Centralized purchasing consortia negotiate adherence-linked rebate structures.
- Homecare Settings:Specialized nursing networks and patient training platforms, densest in Germany where reimbursement favors domestic self-injection support. US specialty pharmacy networks displace wholesale distribution for onboarding functions.
- Specialty Clinics:Rheumatology, dermatology, and endocrinology practices with high biologics prescribing volume, consolidating under hospital system ownership. Amgen's manufacturing scale supports supply security commitments to these consolidating buyers.
- Research Institutions:Academic medical centers conducting route-switching studies and immunogenicity trials, critical for FDA approval of intravenous-to-subcutaneous reformulations. EMA MDR requirements for combination products extend their validation timelines.
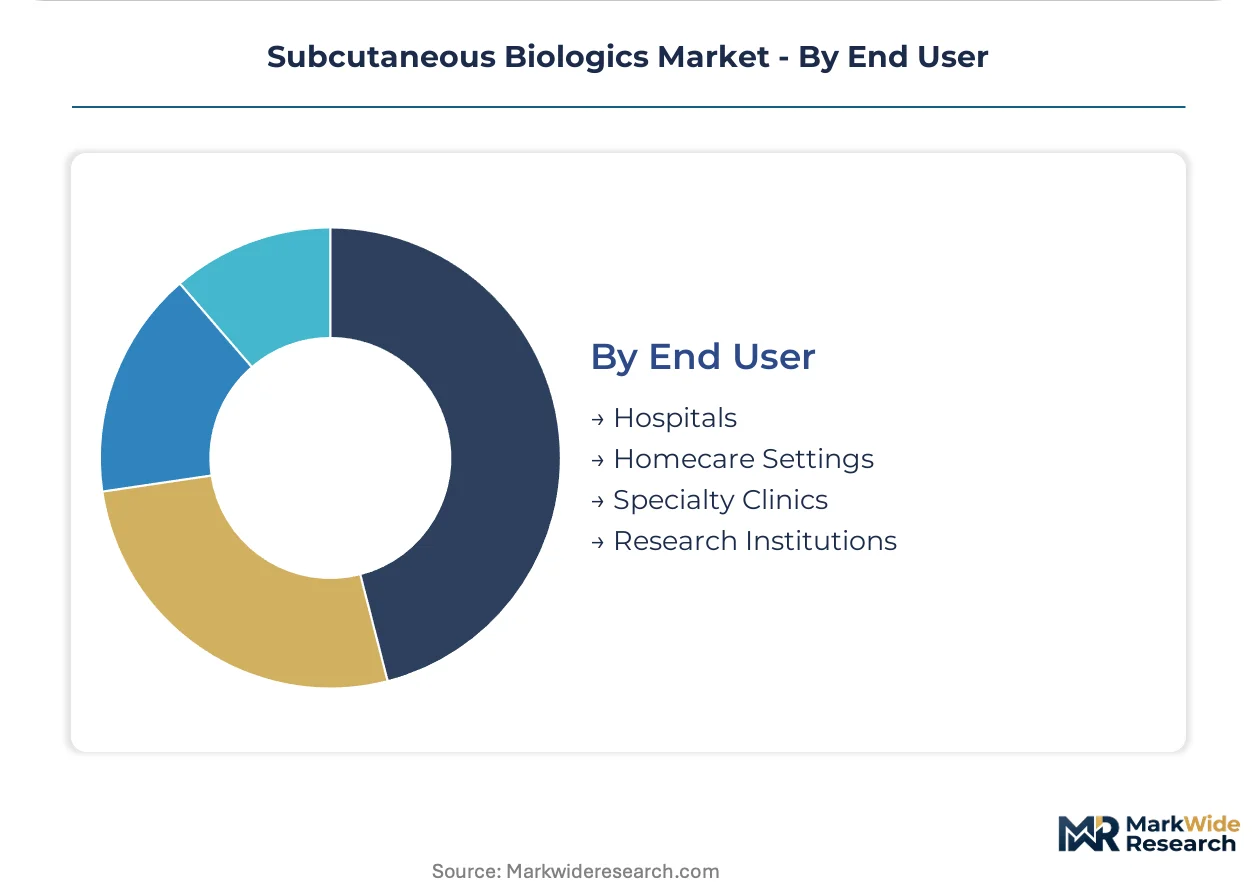
Hospital systems retain the largest procurement volume, with homecare settings gaining share fastest as payer site-of-care migration policies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation scientists and bioprocess engineers concentrate in Basel, Boston, and Osaka, anchoring regional capability clusters that determine where subcutaneous biologic development accelerates.
United States
FDA biosimilar interchangeability standards drive competitive entry timelines for intravenous-to-subcutaneous reformulations. Payer site-of-care migration policies compress reimbursement differentials between infusion centers and home administration. The Greater Boston biotech corridor hosts contract development organizations specializing in high-concentration protein formulation.
Germany
Dense networks of specialized nursing services and favorable reimbursement for domestic self-injection create template conditions for outpatient biologics expansion. EMA MDR requirements for combination drug-device products extend approval timelines compared with standalone biologics. The Rhine-Main cluster around Frankfurt concentrates pharmaceutical-grade excipient suppliers and histidine buffer production.
Japan
METI incentives for reducing hospital bed utilization align subcutaneous self-administration models with aging demographic pressures in rheumatoid arthritis and psoriasis. PMDA streamlined assessments for subcutaneous formulations accelerate market entry relative to intravenous originators. The Kansai region around Osaka anchors domestic plasma sourcing networks for immunoglobulin production.
Switzerland
Concentration of qualified suppliers for pharmaceutical-grade polysorbates creates input advantages for formulation stability. Swissmedic maintains alignment with EMA standards while offering specialized pathways for combination product review. The Basel pharmaceutical cluster houses technical expertise in shear-stress mitigation for high-concentration biologic manufacturing.
United Kingdom
NHS England site-of-care policies accelerate shifts from hospital-based infusion to community and home administration settings. MHRA post-Brexit regulatory autonomy enables divergence from EMA timelines on specific combination product assessments. The Cambridge-London corridor attracts bioprocess engineering talent for viscosity optimization and auto-injector platform development.
Subcutaneous Biologics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across fragmented therapeutic verticals, creating tiered competitive intensity that varies by molecular class and delivery technology. Hospital purchasing consortia and specialty pharmacy networks concentrate procurement power, favoring manufacturers with established EMA usability dossiers and FDA interchangeability designations. Three archetypes dominate: integrated pharmaceutical-device developers with captive manufacturing, biosimilar specialists leveraging abbreviated approval pathways, and contract manufacturing organizations scaling high-concentration formulation capacity. Competitive moves center on manufacturing scale commitments to consolidating buyers and connected device integration for real-world adherence data capture.
Among diversified immunology and oncology developers, AbbVie and Amgen exemplify contrasting strategic positions within the competitive structure. AbbVie represents the portfolio-depth archetype, sustaining formulary positioning across consolidating integrated delivery networks through breadth in autoimmune therapeutics. Amgen anchors the manufacturing-scale archetype, securing supply security commitments to specialty clinic networks through monoclonal antibody production capacity. Novo Nordisk occupies a distinct position as the captive ecosystem developer, with in-house production of injectable pens creating device-drug integration advantages in diabetes-oriented delivery.
| Leading Market Players |
|---|
| AbbVie |
| Amgen |
| Roche |
| Novartis |
| Pfizer |
| Novo Nordisk |
| Biogen |
| Sanofi |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Hospital purchasing consortia and specialty pharmacy networks concentrate procurement power across the United States and Germany, enforcing adherence-linked rebate structures that embed device training and patient onboarding services within drug pricing contracts.
Pricing Analysis
Bundled service contracts dominate in institutional settings, where nursing oversight and cold-chain logistics are priced into per-dose agreements, while unbundled product-only pricing prevails in German homecare networks where reimbursement separates drug from service. Three-tier pricing structure across premium originator, standard biosimilar, and economy unbranded biologics segments stratifies by FDA interchangeability designation and EMA MDR compliance depth. Pricing pressure stems from biosimilar entry in oncology supportive care, compressing originator margins in granulocyte colony-stimulating factors. Community oncology networks exhibit highest price sensitivity due to site-of-care migration economics, while integrated delivery networks with captive specialty pharmacies show lowest sensitivity due to formulary control.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German suppliers of pharmaceutical-grade polysorbates and histidine buffers, where qualified manufacturing sites for high-purity excipients number fewer than five globally. Manufacturing concentration centers on the United States, Switzerland, and Germany for fill-finish capacity, with fill-finish operations drawing from Basel-area formulation science clusters. Cold-chain distribution hinges on specialized logistics networks with 2-8°C validated containers, creating exposure to temperature excursion risks during last-mile delivery to patient homes. Distribution runs through specialty pharmacy networks in the United States and hospital purchasing consortia in Germany, displacing traditional wholesale channels for patient-facing subcutaneous therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through connected device integration, where Bluetooth-enabled auto-injectors capture adherence data that supports value-based contracting premiums with US payers.
For Market Incumbents: Deploy manufacturing scale commitments as the primary lever to secure supply security agreements with consolidating specialty clinic networks. Anchor formulary positioning through backward integration into high-concentration protein formulation capacity in the Greater Boston corridor. Defend against biosimilar entrants by accelerating FDA interchangeability studies for intravenous-to-subcutaneous reformulations, creating technical barriers that filter out capital-constrained competitors. For New Entrants and Emerging Players: Underserved community oncology networks in the United States represent the most penetrable buyer archetype, stranded with legacy infusion center costs and seeking site-of-care migration partners. Penetrate through wearable bolus injector platforms for trastuzumab biosimilars, where pilot programs demonstrate chair-time reduction economics. Lead with remote nursing monitoring services bundled with device training, capturing functions that hospital systems are outsourcing. For Investors and Strategic Acquirers: Diversified pharmaceutical-device developers with captive manufacturing are the most active acquirer in this space, seeking bolt-on formulation capabilities. Long-term viability favors targets with established EMA usability dossiers and FDA interchangeability designations, positioned for the 5-10 year window of site-of-care migration maturation. Watch for FDA guidance finalization on immunogenicity testing for route-switching studies as the signal for competitive entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Device Integration | Bluetooth-enabled auto-injectors capture real-world adherence data for US payer value-based contracting. |
| EMA MDR Compliance Investment | Existing usability dossiers accelerate European market entry against device-naive competitors. |
| High-Concentration Formulation Scale-Up | Shear-stress mitigation expertise in Basel and Boston clusters enables viscosity-tolerant delivery systems. |
| Specialty Pharmacy Network Partnership | Patient onboarding and training functions displace hospital nursing labor in US distribution. |
| WHO Prequalification Pathway Entry | Simplified cold-chain formulations unlock procurement access in lower-middle-income markets. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative findings in operational reality across formulation science and site-of-care economics. Secondary validation drew from FDA biosimilar filings, EMA MDR submission databases, ClinicalTrials.gov route-switching study records, and hospital GPO contract repositories. Bottom-up patient-flow modeling and top-down therapeutic category spend analysis were triangulated against manufacturer capacity disclosures.
Bottom-up volume builds tracked administration frequency by therapy area, molecular class, and delivery method, while top-down checks validated against national health expenditure data and payer site-of-care migration policy filings. Segmentation dimensions spanned product type, delivery technology, therapy area, and end-user setting across the projection horizon. CAGRs were derived from patient population prevalence trends, biosimilar entry assumptions, and reimbursement policy velocity in key markets. Forecast inputs incorporated EMA approval timeline differentials for combination products and FDA interchangeability designation rates.
Underlying measurement precision varies by segment; monoclonal antibodies and auto-injector delivery carry tighter precision than enzyme replacement therapies and infusion pump systems due to data availability. Forecasts reflect documented assumptions on biosimilar uptake curves, site-of-care migration speed, and regulatory guidance evolution, with immunogenicity testing requirement changes and excipient supply disruptions representing specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Biochips Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Proteomics Market
Biomedical Technology
E2 Antibody Market