
 Needle Based Biopsy Guns Market | 2026-2036
Needle Based Biopsy Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Needle Based Biopsy Guns Market Foresight
A capital-intensity divergence between integrated manufacturers and assembly-focused competitors is redrawing tier boundaries in needle-based biopsy guns. BD leverages captive polymer molding and metal fabrication to control cost structures across spring-loaded and vacuum-assisted lines. Cook Group anchors its position through deep specialization in percutaneous access devices, while B. Braun Melsungen AG competes on sterile disposable integration within European hospital supply chains.
Needle-based biopsy guns are spring-actuated or vacuum-driven instruments designed to extract tissue cores through percutaneous insertion, typically operating at gauge ranges from 8G to 20G with adjustable throw lengths between 6mm and 23mm for lesion targeting in radiology-guided procedures. Their primary purpose is obtaining histological samples without open surgery, reducing patient recovery time and complication rates in oncology diagnostics. Vacuum-assisted systems command the strongest margin pools due to larger sample volumes and reduced sampling error, while automated delivery modes represent the fastest-growing configuration as imaging centers seek procedural standardization. Spring-loaded devices retain the largest installed base in hospitals, though fine needle aspiration instruments face margin compression from commoditization in outpatient settings.
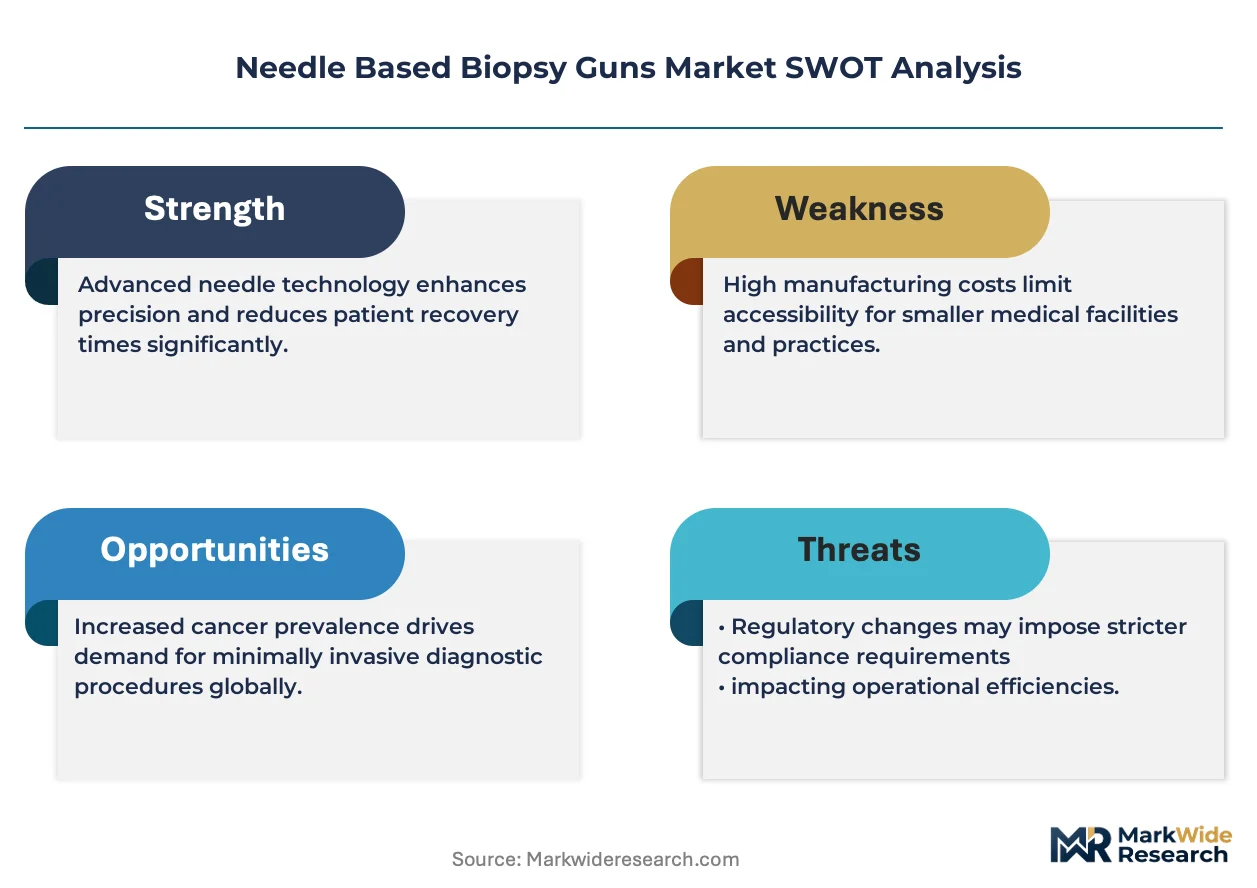
The FDA governs 510(k) clearance pathways for Class II biopsy devices, while the EU MDR imposes strengthened clinical evidence requirements and post-market surveillance obligations on manufacturers selling into European member states. ISO 13485 certification shapes supplier qualification criteria, directly filtering which producers can serve integrated delivery networks and national procurement frameworks. Stakeholders must monitor how FDA digital health guidance and EU MDR economic operator liability rules reshape compliance costs and competitive entry barriers.
Market Dynamics
EU MDR sterilization and traceability mandates are compressing supplier qualification timelines while hospital networks consolidate procurement around certified disposable-integrated systems. This regulatory pressure is redrawing competitive tier boundaries faster than product innovation cycles.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:Strengthened post-market surveillance obligations are filtering out uncertified suppliers and concentrating volume among ISO 13485-compliant manufacturers with validated sterilization protocols.
- Vacuum-Assisted Sample Volume:Imaging centers are standardizing on vacuum-driven instruments for larger tissue cores and reduced sampling error in radiology-guided oncology diagnostics.
- German Hospital Procurement Consolidation:Integrated delivery networks are bundling biopsy device contracts with sterilization service agreements, favoring suppliers with captive polymer molding capabilities.
Market Restraints
- Stainless Steel and Polymer Input Volatility:Gauge-specific needle alloys and medical-grade polymers face price swings that compress margin pools on spring-loaded disposable lines.
- EU MDR Economic Operator Liability:Expanded legal exposure for authorized representatives and importers is extending compliance timelines and raising entry costs for non-European manufacturers.
- Fine Needle Aspiration Commoditization:Outpatient clinics are substituting lower-margin aspiration instruments for core biopsy guns in superficial lesion assessment, eroding premium positioning.
Strategic Opportunities
- US Imaging Center Network Expansion:Minimally invasive diagnostic capacity builds in radiology chains are creating demand for automated delivery modes with procedural standardization features.
- FDA Digital Health Guidance Convergence:Software-integrated biopsy tracking systems are opening pathways for real-time lesion documentation and AI-assisted targeting.
- India CDSCO Localization Incentives:Domestic manufacturing requirements under medical device rules are creating white space for regional assembly partnerships with sterilization validation capabilities.
Industry Challenges
- ISO 13485 Certification Timeline Compression:Supplier qualification for integrated delivery networks requires 12-18 month validation cycles that strain working capital for mid-tier manufacturers.
- Legacy Sterilization Equipment Integration:Hospital central sterile supply departments face friction retrofitting ethylene oxide and gamma sterilization lines for vacuum-assisted disposable volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle Based Biopsy Guns Market |
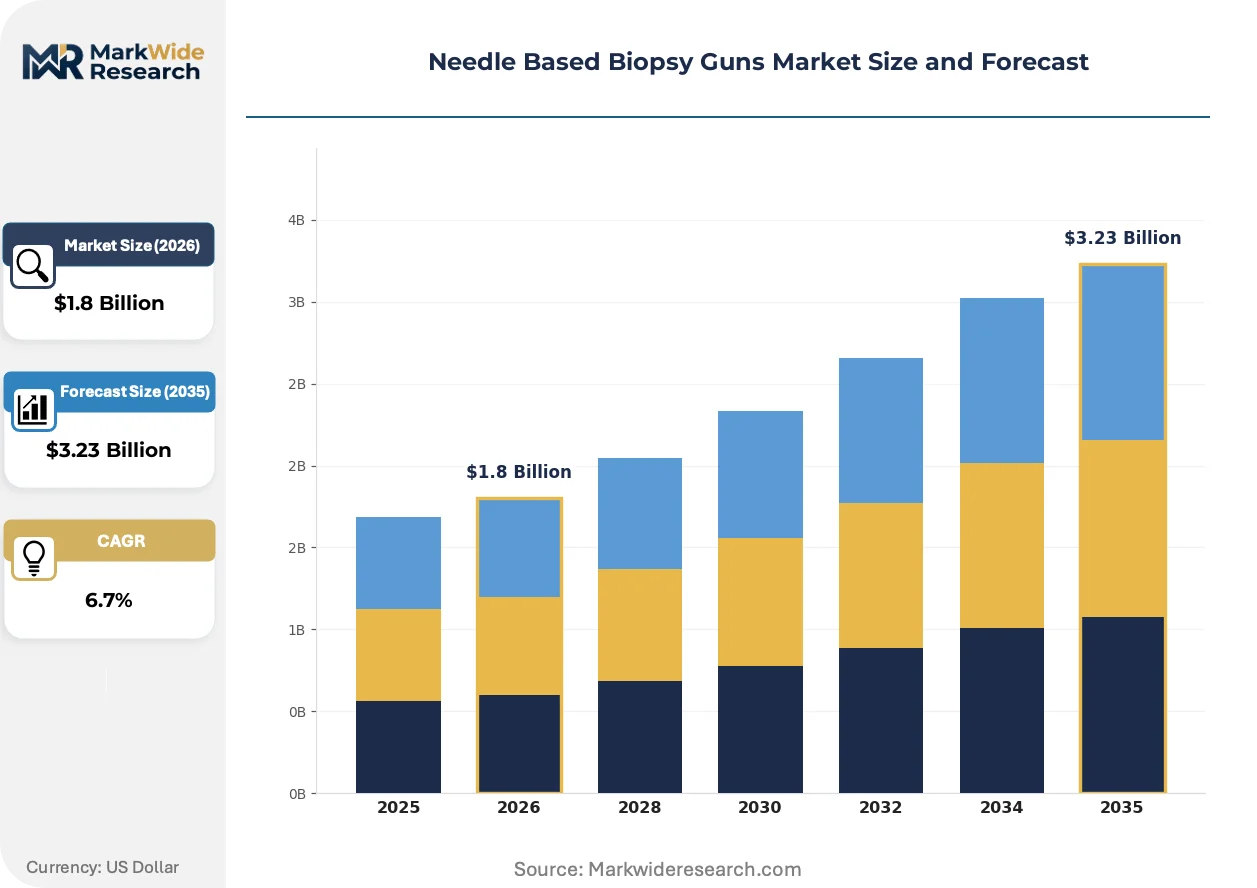
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring-Loaded, Vacuum-Assisted, Fine Needle Aspiration, Automated End User: Hospitals, Diagnostic Labs, Outpatient Centers, Imaging Centers Application: Oncology, Cardiology, Infectious Diseases, Autoimmune Disorders Delivery Mode: Manual, Motorized, Handheld, Robotic |
| Companies Covered | Cardinal Health, Devicor Medical Products, Inc., BD, Cook Group, Leica Biosystems Nussloch GmbH, Argon Medical, B. Braun Melsungen AG, Olympus Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle Based Biopsy Guns Market Shifts & Advancements
Needle-based biopsy instrumentation is converging with digital tracking and automated delivery systems that compress procedural variability. These shifts are redefining how manufacturers defend margin pools across spring-loaded and vacuum-assisted product lines.
Miniaturized vacuum-assisted biopsy needles are miniaturizing gauge profiles while maintaining core sample integrity for superficial and dense tissue applications. Radiology departments in US imaging center networks are adopting 10G-12G instruments for breast and thyroid lesions at replacement cycles of 18-24 months. This downsizing is miniaturizing the addressable market for traditional 14G-16G spring-loaded devices while expanding premium positioning for precision-engineered vacuum systems.
EU MDR post-market surveillance obligations are extending clinical evidence requirements for Class IIa and IIb biopsy devices sold into European member states. Manufacturers must now maintain systematic vigilance data and periodic safety update reports that raise compliance overhead by 15-25% relative to pre-2021 Medical Device Directive standards. German hospital procurement frameworks are responding by pre-qualifying only suppliers with established European authorized representatives and validated sterilization partnerships.
Outcome-based procurement contracts are displacing unit-price purchasing in US integrated delivery networks. Hospital systems are bundling biopsy device supply with procedural training, maintenance, and sample quality guarantees that shift risk to manufacturers. This reconfiguration is most visible in oncology diagnostics networks across the Midwest and Southeast, where multi-year agreements now tie supplier payments to histological adequacy rates and complication reduction metrics.
Needle Based Biopsy Guns Market Segmentation
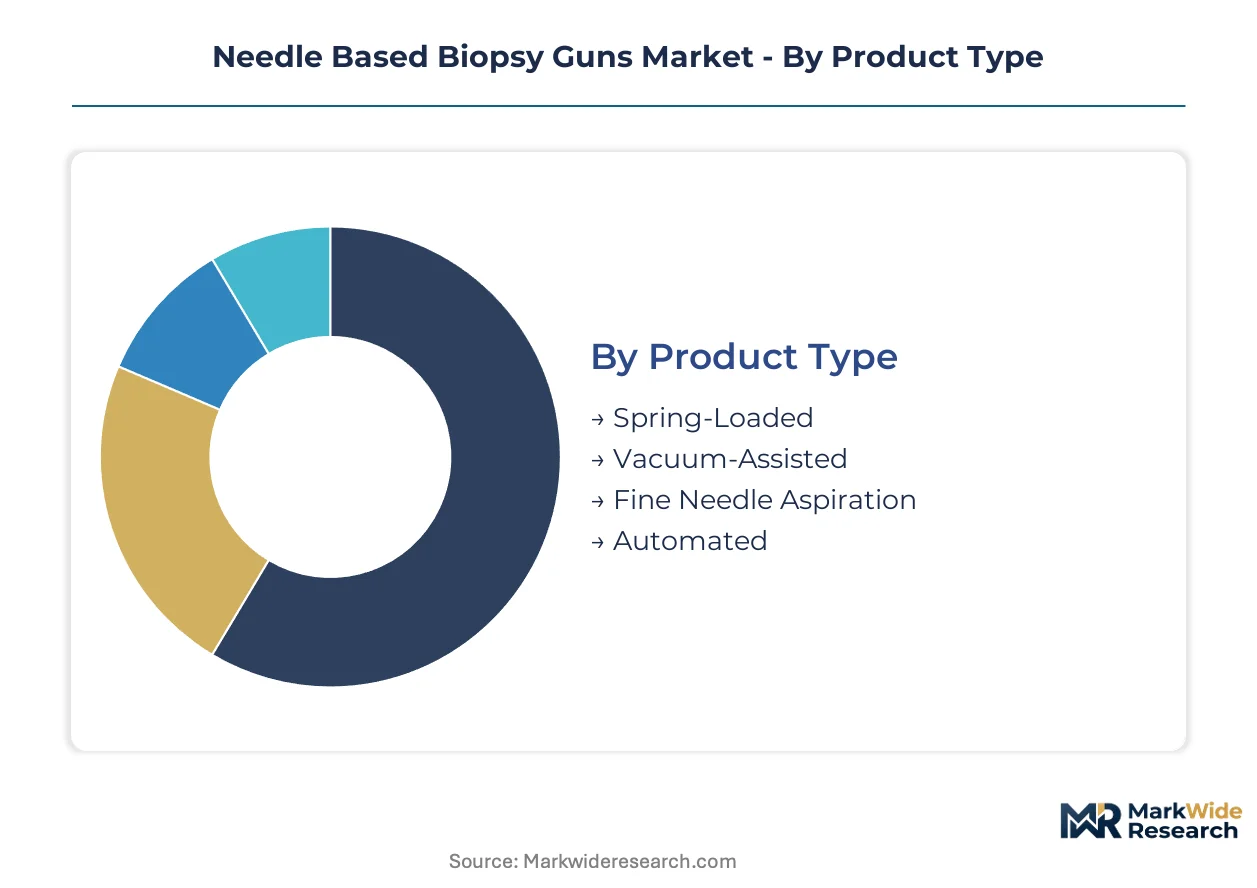
Segmentation in needle-based biopsy guns reveals how procurement channels, clinical settings, and technology configurations fragment demand. Understanding these divides exposes where margin pools concentrate and which specifications govern supplier qualification.
Product Type:
Channel mix varies sharply across mechanism designs, with vacuum-assisted systems flowing through radiology-focused distributors while spring-loaded devices dominate hospital central supply contracts.
- Spring-Loaded:Mechanical firing mechanisms using compressed springs to drive cutting cannulas through coaxial needles. Demand concentrates in US hospital networks where bulk disposable purchasing and established sterilization protocols favor proven designs over capital-intensive alternatives.
- Vacuum-Assisted:Negative-pressure systems that draw tissue into sampling apertures for larger core volumes with fewer passes. Imaging centers in Germany and the United States are standardizing on these instruments to reduce sampling error in breast and prostate diagnostics.
- Fine Needle Aspiration:Lower-gauge instruments for cytology sampling without core extraction.
- Automated:Programmable delivery systems with standardized throw lengths and firing speeds.
Spring-loaded devices dominate installed base. Vacuum-assisted configurations are where expansion concentrates.
End User:
Cost tiers separate these segments, with capital equipment bundling at imaging centers contrasting against price-sensitive disposable purchasing at outpatient clinics.
- Hospitals:Integrated delivery networks with central sterile supply departments and multi-specialty procurement committees. German hospital systems are bundling biopsy device contracts with sterilization service agreements under EU MDR compliance frameworks.
- Imaging Centers:Radiology-focused facilities expanding minimally invasive diagnostic capacity across US metropolitan markets. These operators prioritize procedural standardization and automated delivery modes to compress variability across high-volume lesion assessment protocols.
- Diagnostic Labs:External pathology providers influencing device selection through sample quality specifications.
- Outpatient Centers:Cost-conscious settings where fine needle aspiration substitutes erode premium positioning for core biopsy systems.
Hospitals anchor procurement volume. Imaging centers are climbing the fastest.
Application:
Volume concentration tracks oncology's procedural density, with other applications fragmented across subspecialty practices with divergent reimbursement profiles.
- Oncology:Tumor sampling for histological diagnosis and biomarker profiling. US imaging center networks are expanding dedicated oncology biopsy suites with vacuum-assisted systems for breast, lung, and liver lesion assessment.
- Cardiology:Myocardial and pericardial tissue acquisition for infiltrative disease diagnosis.
- Infectious Diseases:Deep tissue sampling for culture and molecular pathogen identification.
- Autoimmune Disorders:Organ-specific biopsies for inflammatory condition classification.
Oncology commands the deepest specification requirements. Cardiology represents the steepest expansion trajectory among non-oncology applications.
Delivery Mode:
Technology maturity separates manual and motorized systems from emerging robotic configurations, with handheld designs bridging the gap in mobile and point-of-care settings.
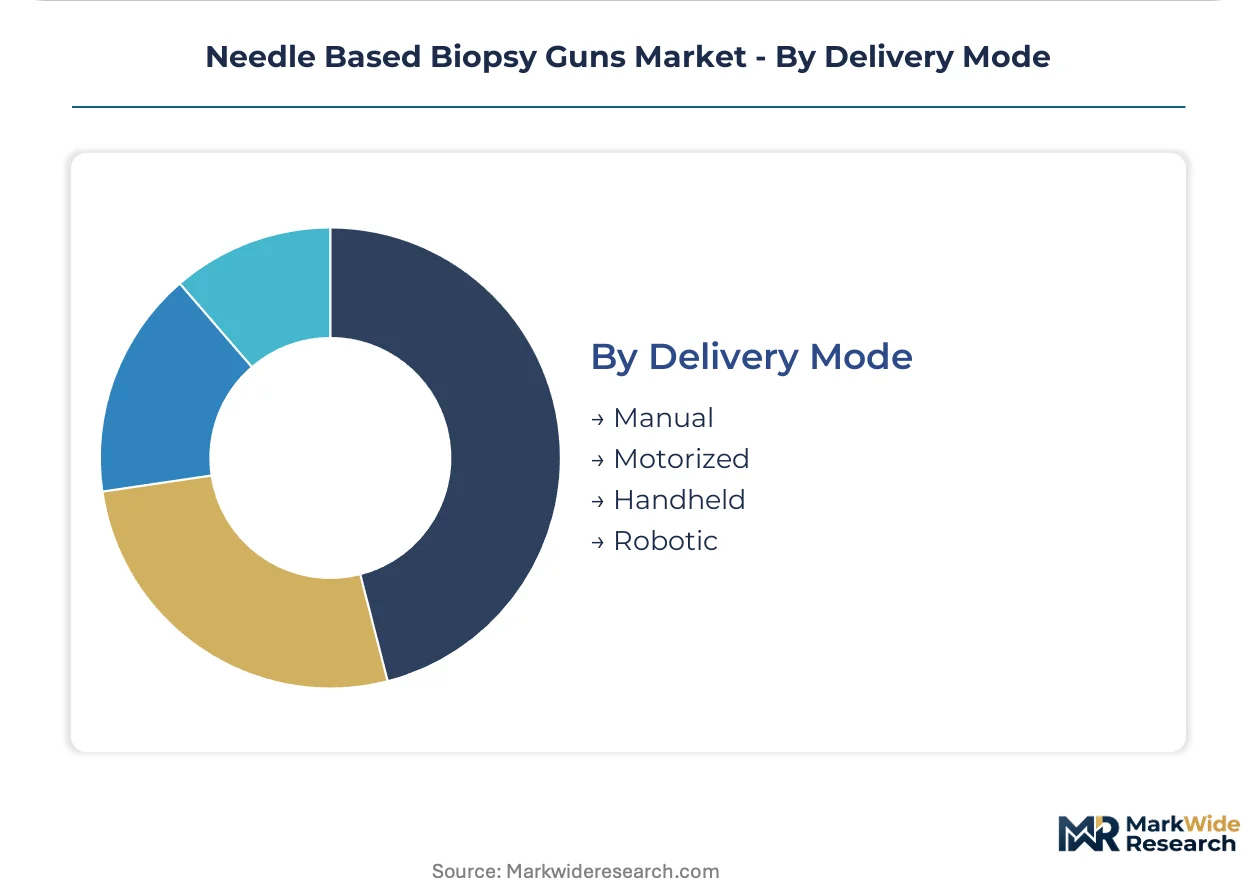
- Manual:Operator-controlled insertion and firing without powered assistance. These instruments retain share in resource-limited settings and procedures requiring tactile feedback for superficial lesion targeting.
- Motorized:Battery or mains-powered firing mechanisms with consistent velocity profiles. German radiology departments are adopting motorized vacuum-assisted systems to standardize sample quality across operator experience levels.
- Handheld:Portable designs optimized for bedside and ambulatory deployment.
- Robotic:Image-guided positioning systems with programmable needle trajectories.
Manual devices retain the broadest geographic reach. Motorized systems are gaining share fastest in regulated markets with reimbursement for procedural standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States imaging centers deploy vacuum-assisted systems for high-volume oncology diagnostics, whereas German hospital networks prioritize sterilization-integrated procurement under stricter regulatory frameworks. This divergence in consumption patterns separates automated delivery adoption in North America from compliance-driven bundling in Europe.
United States
Radiology chains across the Midwest and Southeast are expanding dedicated biopsy suites with motorized vacuum-assisted instruments. FDA 510(k) clearance pathways govern Class II device entry, with digital health guidance now converging on software-integrated tracking systems. The Greater Boston cluster anchors precision-engineered manufacturing for gauge-specific needle alloys serving academic medical centers.
Germany
Integrated delivery networks in North Rhine-Westphalia are bundling biopsy device contracts with ethylene oxide sterilization service agreements. EU MDR post-market surveillance obligations filter supplier qualification toward ISO 13485-compliant manufacturers with validated European authorized representatives. The Baden-Württemberg medical technology corridor concentrates polymer molding capabilities for disposable-integrated system production.
China
Tier-one hospitals in the Yangtze River Delta are upgrading from manual to motorized delivery systems for breast and prostate lesion assessment. NMPA registration requirements under revised medical device rules extend clinical evidence timelines for Class II invasive instruments. The Beijing-Tianjin-Hebei cluster hosts domestic assembly partnerships targeting CDSCO localization incentives for regional sterilization validation.
India
Diagnostic lab chains in Maharashtra and Karnataka are adopting fine needle aspiration instruments for cost-conscious outpatient oncology screening. CDSCO domestic manufacturing mandates under Medical Device Rules 2017 create procurement preferences for regional producers with captive sterilization partnerships. The Delhi-NCR corridor concentrates import-dependent distribution for vacuum-assisted systems serving private hospital networks.
Japan
Academic medical centers in the Kanto region are standardizing on automated biopsy delivery for thyroid and superficial lesion protocols. PMDA quality management system inspections enforce traceability requirements that extend supplier validation cycles. The Osaka-Kobe manufacturing belt anchors precision metal fabrication for spring-actuated mechanisms serving domestic and Southeast Asian markets.
Needle Based Biopsy Guns Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in needle-based biopsy guns, with captive polymer molding and metal fabrication capabilities separating cost-structure defenders from assembly-focused competitors. The upper tier controls sterilization-validated supply chains across spring-loaded and vacuum-assisted lines, while mid-tier players compete on disposable volume contracts within regional hospital frameworks. Strategic archetypes include full-stack manufacturers with in-house needle alloy production, radiology-focused specialists with deep percutaneous access expertise, and sterile disposable integrators serving European procurement networks. Dominant competitive moves encompass backward integration into medical-grade polymer supply and multi-year outcome-based contracting with integrated delivery networks.
Within the integrated manufacturing tier, BD and Cook Group exemplify divergent specialization strategies. BD represents the full-stack archetype with captive control over cost structures spanning mechanism designs, while Cook Group anchors the percutaneous access specialist position. B. Braun Melsungen AG sits within the European sterile disposable integration tier, leveraging supply chain proximity to German hospital procurement frameworks. These three entities illustrate how manufacturing depth, clinical application focus, and geographic supply chain positioning create defensible tier boundaries faster than product innovation cycles alone.
| Leading Market Players |
|---|
| Cardinal Health |
| Devicor Medical Products, Inc. |
| BD |
| Cook Group |
| Leica Biosystems Nussloch GmbH |
| Argon Medical |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Long-term sterilization service contracts in German hospital networks lock in both supply access and price visibility for vacuum-assisted biopsy systems, bundling device procurement with ethylene oxide validation under EU MDR frameworks. This contractual architecture concentrates procurement power among ISO 13485-compliant manufacturers while compressing margin flexibility for assembly-focused competitors lacking captive polymer molding capabilities.
Pricing Analysis
Contract-based long-term offtake dominates German hospital procurement, with pricing stratifying across FDA-cleared premium tiers, CE-marked standard configurations, and economy-grade spring-loaded disposables for outpatient settings. Price differentiation centers on sterilization validation depth and gauge-specific needle alloy sourcing. Cost compression in spring-loaded disposable lines is intensifying because stainless steel and medical-grade polymer input volatility erodes margin pools. Outpatient clinics exhibit highest price sensitivity, substituting fine needle aspiration instruments for core biopsy systems, while US imaging center networks show lowest sensitivity due to bundled outcome-based contracting.
Supply Chain Analysis
Inventory lead times for gauge-specific needle alloys extend supplier qualification cycles to 12-18 months, straining working capital for mid-tier manufacturers seeking integrated delivery network contracts. Supply concentrates in Germany for polymer molding, Japan for precision metal fabrication, and the United States for automated delivery system assembly. Raw material dependencies include medical-grade polymers, stainless steel needle alloys, and gamma-sterilization packaging materials. Single-source vulnerability in European ethylene oxide sterilization capacity poses structural risk. Distribution runs through radiology-focused distributors for vacuum-assisted systems and hospital central supply contracts for spring-loaded devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Needle-based biopsy instrumentation is approaching a platform-economics inflection as software-integrated tracking systems and AI-assisted targeting converge on standardized data exchange protocols, creating interoperability layers that favor manufacturers with companion digital health submissions.
For Market Incumbents: Compound defensive positioning by deepening backward integration into medical-grade polymer supply and securing multi-year outcome-based contracts with US integrated delivery networks that tie payments to histological adequacy rates. Fine needle aspiration commoditization in outpatient settings threatens premium positioning for core biopsy systems, necessitating accelerated investment in motorized vacuum-assisted lines with procedural standardization features.
For New Entrants and Emerging Players: FDA 510(k) clearance fast-tracks for software-integrated biopsy tracking systems open white-space in US imaging center networks seeking real-time lesion documentation. The most penetrable segment lies in automated delivery modes for radiology chains expanding minimally invasive diagnostic capacity. A targeted go-to-market angle pairs sterilization validation partnerships with regional assembly operations under India's CDSCO localization incentives.
For Investors and Strategic Acquirers: Radiology-focused percutaneous access specialists with deep specialization in breast and prostate lesion protocols represent compelling acquisition targets, given their defensible clinical application expertise and established distributor relationships. Long-term viability over the coming decade hinges on convergence between mechanical instrumentation and digital health reimbursement pathways. The critical inflection signal to monitor is FDA digital health guidance finalization for AI-assisted targeting systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Digital Health Submission | Software-integrated tracking systems unlock real-time lesion documentation in US imaging centers. |
| CE Marking Pathway Under EU MDR | Strengthened clinical evidence requirements filter supplier qualification toward ISO 13485-compliant manufacturers. |
| Hospital System Partnership | Bundled sterilization service agreements in Germany concentrate procurement among captive polymer molders. |
| Software Companion Development | AI-assisted targeting convergence creates interoperability layers favoring companion digital health submissions. |
| Reimbursement Strategy | Outcome-based contracting in US Midwest and Southeast oncology networks ties supplier payments to complication reduction metrics. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and radiology department heads; and secondary validation against FDA 510(k) filings, EU MDR vigilance databases, hospital procurement contracts, and CMS Medicare reimbursement schedules. Bottom-up triangulation across mechanism design configurations and top-down validation against sterilization service agreement volumes anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation across product type, end user, application, and delivery mode dimensions. CAGRs derived from weighted average growth trajectories across vacuum-assisted, spring-loaded, and automated system configurations. Forecast inputs incorporated EU MDR compliance cost escalation curves and US imaging center network expansion rates.
Underlying assumptions cover sterilization validation timeline compression and polymer input price stability, with deviation risk concentrated in EU MDR economic operator liability expansion and gamma sterilization capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Organoids Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Cell Isolation Market