
 Live Cell RNA Detection Market | 2026-2036
Live Cell RNA Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Live Cell RNA Detection Market Foresight
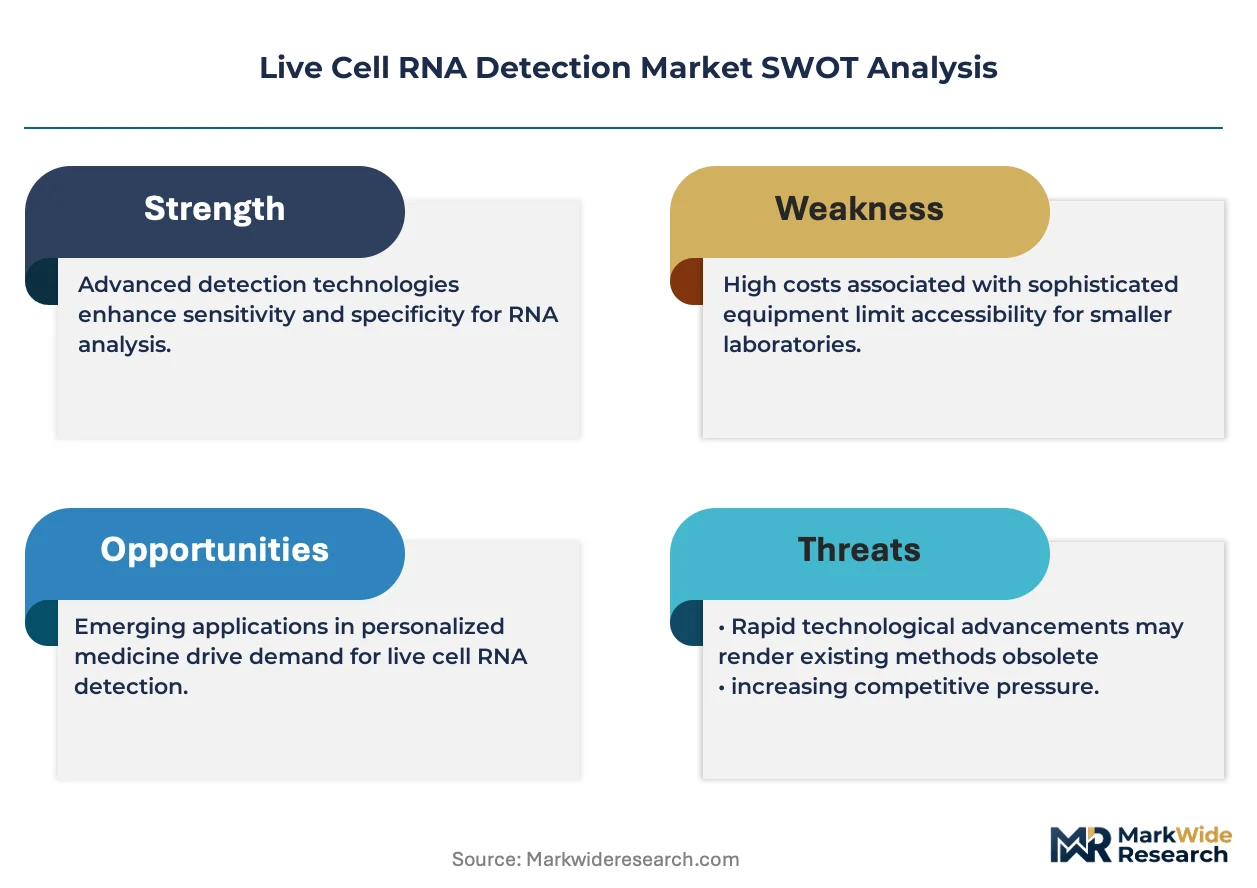
Modular assay panel design is pivoting buyer choice away from monolithic detection kits toward configurable RNA imaging workflows. Thermo Fisher Scientific Inc. leverages its reagent-instrument ecosystem to anchor high-throughput live cell analysis contracts. QIAGEN competes through sample-prep automation that integrates with third-party imaging platforms. Bio-Rad Laboratories Inc. specializes in droplet digital PCR modules that extend into single-cell RNA quantification workflows.
Live cell RNA detection encompasses fluorescent probe-based, hybridization-mediated, and amplification-coupled methods for visualizing and quantifying RNA molecules within intact, viable cells, typically operating at subcellular resolution with temporal resolution spanning minutes to hours. These systems serve pharmaceutical screening, developmental biology, and clinical transcriptomics by preserving cellular context that lysate-based methods destroy. Fluorescent In Situ Hybridization retains dominance in spatial transcriptomics applications where subcellular localization determines therapeutic relevance. CRISPR-based detection methods represent the fastest-expanding technology segment as programmable RNA-binding proteins displace static probe sets. Pharmaceutical Companies constitute the highest-margin end user segment due to regulatory-grade validation requirements and recurring consumable demand.
FDA oversight of companion diagnostic development shapes product validation pathways for U.S.-targeted RNA detection platforms, while EMA's In Vitro Diagnostic Regulation redefines conformity assessment burdens for European market access. ISO 13485 quality management standards and IEC 61010-1 safety specifications govern instrument manufacturing for clinical-adjacent research applications. Stakeholders must monitor evolving cross-border data requirements for cloud-connected imaging systems as genomic data localization laws proliferate.
Market Dynamics
Programmable CRISPR-based RNA imaging systems are compressing development cycles for reagent suppliers while fragmenting procurement authority between core facilities and individual research groups. This structural shift redistributes margin capture from instrument manufacturers toward consumable-anchored workflow providers.
Growth Catalysts
- Precision medicine infrastructure funding:National health research agencies in the United States, Germany, and Japan direct capital toward single-cell transcriptomics platforms that preserve cellular context for therapeutic validation.
- EMA In Vitro Diagnostic Regulation:The 2022 regulatory framework elevates conformity requirements for European market access, creating competitive moats for validated platform suppliers against unvalidated reagent vendors.
- Hybridization-mediated detection:Fluorescent In Situ Hybridization protocols achieve subcellular resolution in spatial transcriptomics applications where lysate-based methods destroy localization information critical to drug target assessment.
Market Restraints
- Specialized fluorophore supply concentration:Synthesis of photostable organic dyes for live cell imaging concentrates among German and Japanese chemical suppliers, exposing reagent manufacturers to input cost volatility and allocation risk.
- CRISPR licensing complexity:Broad Institute and University of California patent estates impose layered royalty obligations on programmable RNA-binding protein systems, elevating total cost of ownership for commercialized detection kits.
- ISO 13485 certification timelines:Quality management system validation for clinical-adjacent instruments extends 18-24 months, delaying revenue recognition for platform developers targeting diagnostic workflow expansion.
Strategic Opportunities
- Cloud-connected imaging data localization:Genomic data sovereignty laws proliferating across European member states create demand for region-housed image analysis infrastructure that complies with GDPR cross-border transfer restrictions.
- Pharmaceutical screening automation:High-content screening departments at large molecule developers seek modular assay panels configurable across therapeutic programs rather than monolithic detection kits.
- Developmental biology application expansion:Embryonic stem cell researchers adopt live cell RNA detection for lineage tracing studies, opening consumable demand from academic segments historically served by lower-margin bulk reagent suppliers.
Industry Challenges
- Multidisciplinary talent scarcity:Integration of molecular biology, optical engineering, and computational image analysis requires hybrid skill sets that outpace graduate program output in core markets.
- Legacy fluorescence microscope incompatibility:Research groups with sunk capital in confocal systems face workflow friction when adopting CRISPR-based methods requiring specialized excitation profiles.
- IEC 61010-1 safety recertification:Instrument modifications to accommodate faster image acquisition trigger exhaustive electrical safety retesting that compresses product update cadence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Cell RNA Detection Market |
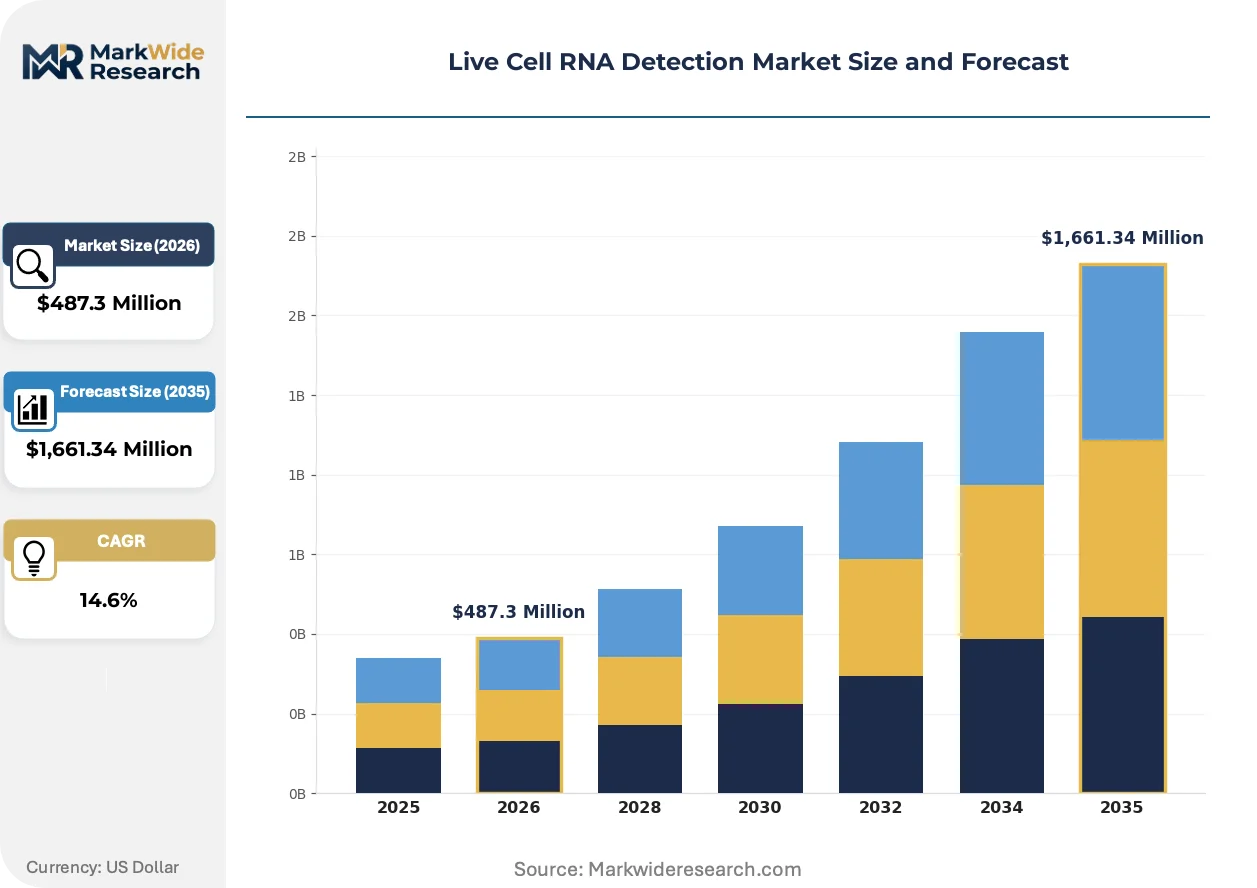
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Detection Method: Flow Cytometry, Fluorescent In Situ Hybridization, qPCR, RNA-Seq Application: Cell Biology Research, Drug Discovery, Genetic Analysis, Disease Diagnostics End User: Academic Institutions, Pharmaceutical Companies, Research Laboratories, Biotechnology Firms Technology: Microarray, Nanotechnology, Optical Imaging, CRISPR |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Agilent Technologies Inc., BioTek Instruments Inc., QIAGEN, Promega Corporation, Bio-Rad Laboratories Inc., Nikon Instruments Inc., Advanced Cell Diagnostics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Cell RNA Detection Market Shifts & Advancements
Automation of sample preparation and image analysis is collapsing the technician-time bottleneck that historically constrained live cell RNA detection throughput. Three convergent developments are reshaping competitive positioning among platform suppliers.
Microfluidic droplet encapsulation is automating single-cell isolation and barcoding for downstream RNA imaging workflows. Pharmaceutical toxicology departments adopt these integrated systems to compress compound screening timelines from weeks to days. The technology is automating labor-intensive steps that previously required manual micromanipulation, shifting value capture toward consumable-anchored platform contracts.
FDA's 2024 guidance on companion diagnostic co-development establishes validation benchmarks for RNA detection platforms targeting therapeutic decision support. The framework elevates documentation burdens for U.S. market entry while creating preference hierarchies among pharmaceutical partners seeking streamlined regulatory pathways. Clinical transcriptomics service providers in Boston and San Diego restructure quality systems to align with the guidance's evidentiary requirements.
Core facility directors are consolidating procurement authority over departmental requisitioning, centralizing instrument service contracts and bulk consumable purchasing. This concentration fragments the historical vendor relationship between sales representatives and individual principal investigators. The shift is most visible in NIH-funded research institutes where shared instrumentation grants mandate standardized platform selection across investigator groups.
Live Cell RNA Detection Market Segmentation
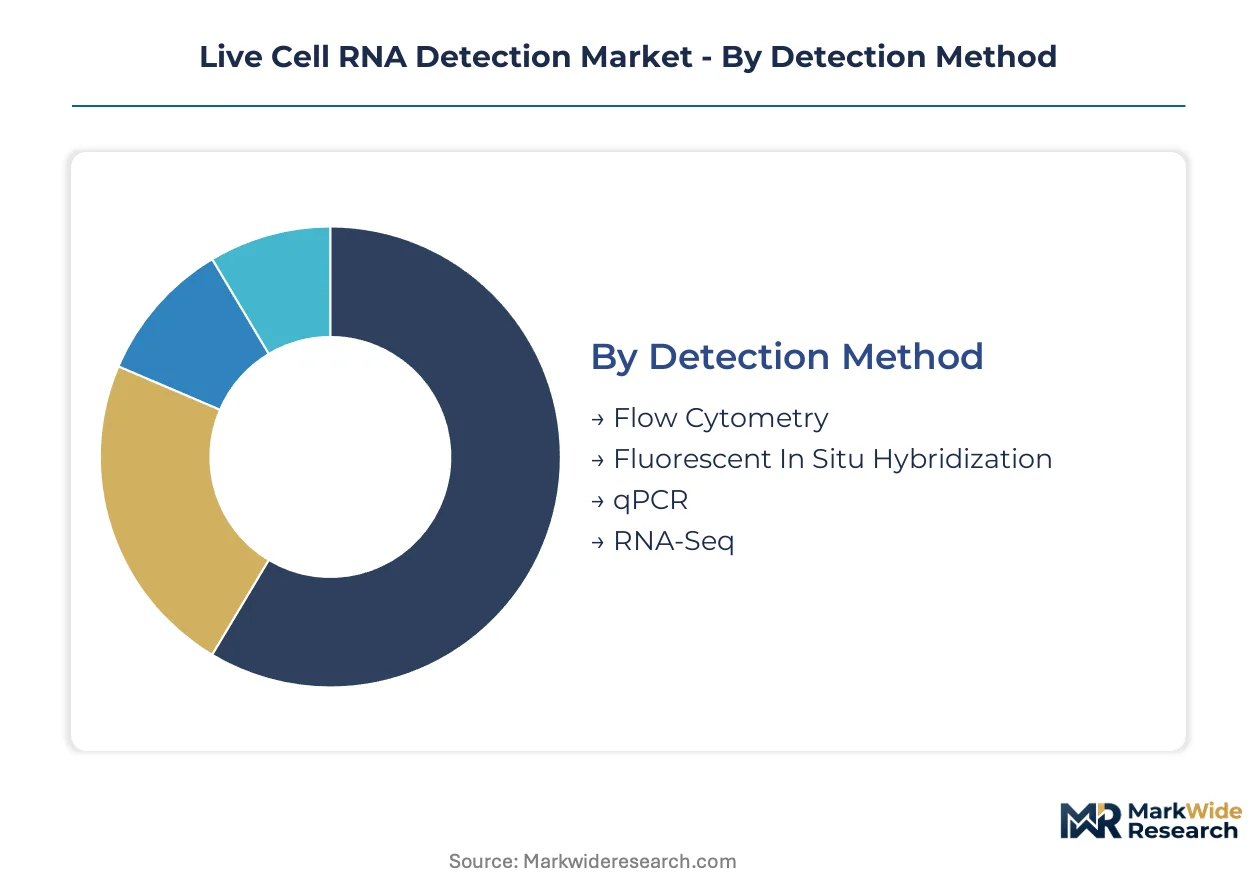
Technology selection in live cell RNA detection hinges on resolution requirements, throughput demands, and compatibility with existing infrastructure. Procurement committees weigh capital expenditure against consumable lock-in when evaluating platform categories. Each segmentation dimension reveals distinct margin structures and competitive dynamics that shape supplier strategy.
Detection Method:
Choice of detection method pivots on the trade-off between spatial precision and temporal throughput that individual research programs require.
- Flow Cytometry:Suspension-based analysis enables rapid quantification of RNA expression across thousands of cells per second. Pharmaceutical toxicology departments in the United States deploy these systems for high-throughput compound screening where population statistics outweigh subcellular detail.
- Fluorescent In Situ Hybridization:Probe hybridization delivers subcellular localization of RNA transcripts within intact cellular architecture. Spatial transcriptomics consortia in Germany prioritize FISH workflows where therapeutic target validation depends on precise intracellular positioning.
- qPCR:Amplification-coupled quantification provides sensitivity for low-abundance transcripts. Academic core facilities favor qPCR modules for cost-effective validation of RNA interference experiments.
- RNA-Seq:Next-generation sequencing of extracted RNA delivers comprehensive transcriptome coverage. Single-cell genomics centers combine RNA-Seq with live cell imaging for multi-modal characterization.
Fluorescent In Situ Hybridization leads on scale; CRISPR-enhanced RNA-Seq methods lead on momentum.
Application:
Application focus determines regulatory exposure and pricing power, with clinical-adjacent workflows commanding premium validation tiers.
- Cell Biology Research:Fundamental investigation of RNA dynamics, localization, and turnover in model organisms and primary cultures. NIH-funded institutes in Maryland and California drive consumable demand for longitudinal imaging studies.
- Drug Discovery:Target identification, mechanism validation, and toxicity screening for therapeutic development. Large molecule developers in Boston and Basel seek automated platforms that compress screening timelines.
- Genetic Analysis:Hereditary disease gene expression profiling and variant functional assessment. Clinical laboratories in Tokyo integrate live cell RNA detection with diagnostic sequencing pipelines.
- Disease Diagnostics:Companion diagnostic development and infectious disease RNA detection. FDA oversight of companion diagnostic co-development elevates documentation burdens for U.S.-targeted platforms.
Cell Biology Research dominates volume; Disease Diagnostics commands the steepest expansion trajectory as regulatory frameworks mature.
End User:
End user type structures procurement authority and service contract terms, with centralized core facilities displacing individual investigator relationships.
- Academic Institutions:University research departments and medical school laboratories conducting investigator-initiated studies. Shared instrumentation grants at German Max Planck Institutes mandate standardized platform selection.
- Pharmaceutical Companies:Large molecule developers and specialty therapeutics firms with regulatory-grade validation requirements. Recurring consumable demand from these accounts anchors supplier revenue stability.
- Research Laboratories:Government research institutes and contract research organizations. Core facility directors consolidate procurement authority over departmental requisitioning.
- Biotechnology Firms:Emerging therapeutics developers and platform technology companies. Venture-backed startups in Cambridge and South San Francisco prioritize modular assay panels configurable across programs.
Pharmaceutical Companies lead on margin capture; Biotechnology Firms gain share fastest as precision medicine infrastructure expands.
Technology:
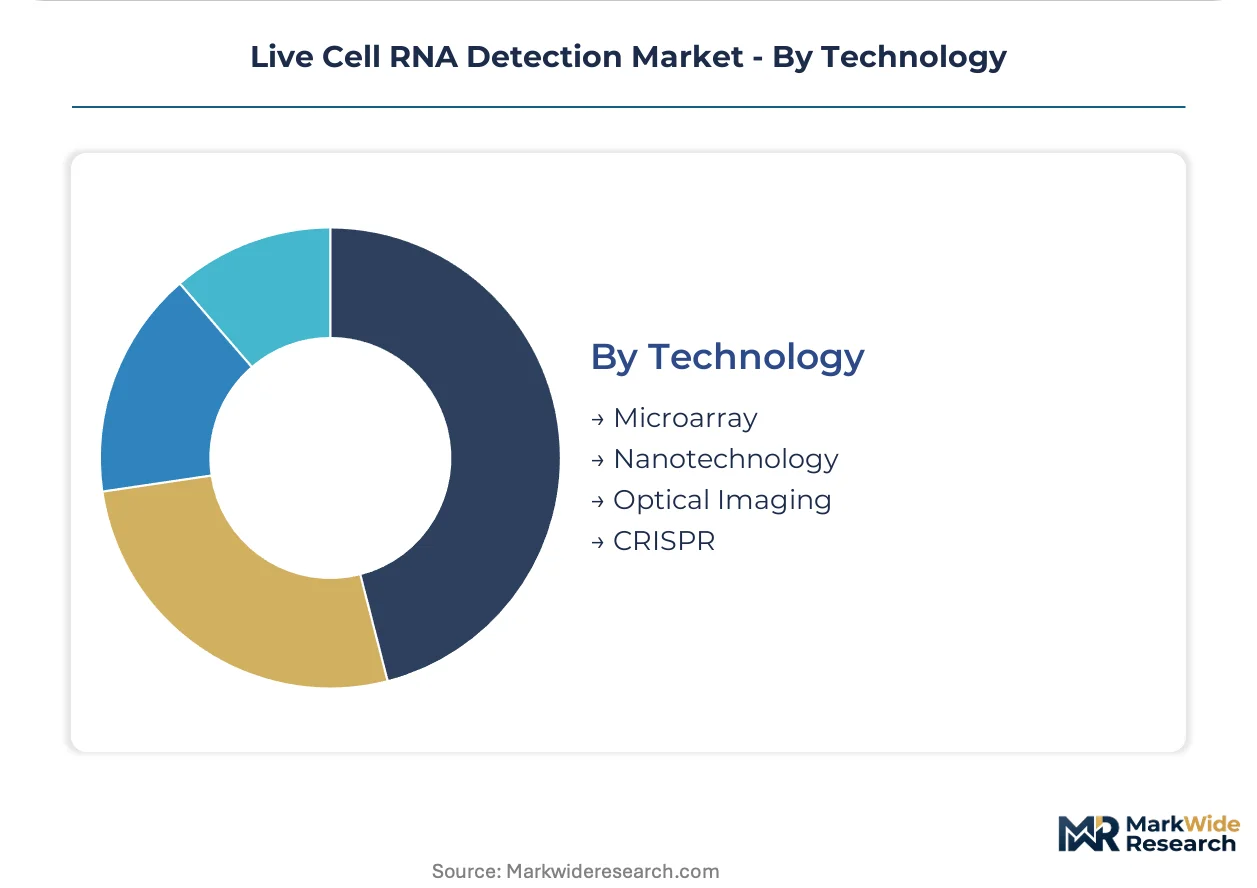
Technology architecture determines competitive moat durability, with programmable systems displacing static probe sets.
- Microarray:Solid-phase nucleic acid hybridization on glass or silicon substrates for parallel expression profiling. Legacy installations persist in agricultural biotechnology applications.
- Nanotechnology:Quantum dot and gold nanoparticle reporters enhancing photostability and multiplexing capacity. Japanese chemical suppliers concentrate synthesis of specialized fluorophores for these systems.
- Optical Imaging:Confocal and super-resolution microscopy enabling real-time RNA visualization. Research groups with sunk capital in confocal systems face workflow friction when adopting newer methods.
- CRISPR:Programmable RNA-binding proteins for dynamic, sequence-specific detection. Broad Institute and University of California patent estates impose layered royalty obligations on commercialized kits.
Optical Imaging retains installed base dominance; CRISPR-based platforms climb the fastest as programmable systems compress development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Live cell RNA detection technologies originated in United States academic medical centers during the early 2000s, with subsequent scaling driven by NIH instrumentation grants and pharmaceutical toxicology automation demands.
United States
FDA's 2024 companion diagnostic guidance and NIH precision medicine funding propel platform adoption across Boston and San Diego biotech clusters. Research institutes in Maryland consolidate procurement authority through shared instrumentation grants that mandate standardized live cell imaging systems. Core facility directors at Stanford and Harvard Medical School anchor multi-year service contracts with reagent-anchored workflow providers.
Germany
Max Planck Institutes and Helmholtz Centers drive demand for subcellular resolution FISH workflows in developmental biology applications. EMA's In Vitro Diagnostic Regulation elevates conformity assessment burdens, creating competitive moats for validated platform suppliers against unvalidated reagent vendors. Heidelberg and Munich research campuses concentrate procurement of automated sample-prep systems that integrate with third-party imaging platforms.
Japan
METI funding for single-cell genomics infrastructure and PMDA oversight of clinical transcriptomics platforms accelerate market development. Japanese chemical suppliers concentrate synthesis of photostable organic dyes, exposing reagent manufacturers to input cost volatility. Tokyo and Osaka medical school laboratories integrate live cell RNA detection with diagnostic sequencing pipelines for hereditary disease profiling.
United Kingdom
Wellcome Trust and UK Research Innovation funding support spatial transcriptomics consortia prioritizing FISH workflows for therapeutic target validation. MHRA alignment with EMA regulatory frameworks shapes validation pathways for diagnostic-adjacent platforms. London and Cambridge biotech clusters restructure quality systems to meet evidentiary requirements for companion diagnostic co-development.
China
NMPA regulatory frameworks for IVD development and national precision medicine initiatives expand domestic platform demand. Chinese academic medical centers in Beijing and Shanghai adopt CRISPR-based detection methods as programmable RNA-binding proteins displace static probe sets. Government research institutes prioritize modular assay panels configurable across therapeutic programs over monolithic detection kits.
Live Cell RNA Detection Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with reagent-instrument ecosystems. Consolidation pressures concentrate margin capture among consumable-anchored workflow providers while fragmenting procurement authority between core facilities and individual research groups. Three archetypes dominate: full-stack platform suppliers integrating hardware, software, and reagents; specialized imaging component manufacturers; and sample-prep automation specialists. Strategic moves center on technology licensing for CRISPR-based methods and geographic expansion through distributor networks in Asia-Pacific markets.
Among United States-based conglomerates, Thermo Fisher Scientific Inc. exemplifies the full-stack archetype through reagent-instrument ecosystem integration. German diversified chemicals player Merck KGaA occupies a position bridging pharmaceutical-grade reagents and precision instrumentation. QIAGEN represents the sample-prep automation specialist archetype, with its modular platforms integrating across third-party imaging systems. These three anchors illustrate how procurement consolidation favors vendors with consumable-anchored recurring revenue models over pure hardware manufacturers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Agilent Technologies Inc. |
| BioTek Instruments Inc. |
| QIAGEN |
| Promega Corporation |
| Bio-Rad Laboratories Inc. |
| Nikon Instruments Inc. |
| Advanced Cell Diagnostics Inc. |
| Others |
Supply & Pricing Matrix
CRISPR-based RNA imaging systems compress reagent development cycles while simultaneously fragmenting procurement authority between core facilities and individual research groups. This technological transition concentrates margin capture among consumable-anchored workflow providers in the United States, Germany, and Japan, where national health research agencies fund precision medicine infrastructure.
Pricing Analysis
Consumable-anchored recurring revenue models dominate the competitive structure, with reagent-instrument ecosystems commanding premium positioning over pure hardware manufacturers. Price differentiation hinges on ISO 13485 certification tier and integration depth with third-party imaging platforms. Pricing pressure stems from CRISPR licensing complexity elevating total cost of ownership for commercialized detection kits. Academic core facilities exhibit highest price sensitivity due to shared instrumentation grant constraints, while pharmaceutical toxicology departments tolerate premium tiers for regulatory-grade validation.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive fluorophores elevates landed costs for reagent manufacturers sourcing from German and Japanese chemical suppliers. Synthesis of photostable organic dyes concentrates among specialized chemical suppliers in Germany and Japan, exposing manufacturers to input cost volatility and allocation risk. Supply chain risk centers on single-source vulnerability for specialized fluorophore precursors. Distribution runs through reagent-instrument ecosystem providers anchoring multi-year service contracts with core facility directors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live cell RNA detection functions as a regulatory compounder where FDA's 2024 companion diagnostic guidance and EMA's In Vitro Diagnostic Regulation create escalating conformity barriers that concentrate demand among validated platform suppliers.
For Market Incumbents: Cement consumable-anchored recurring revenue through reagent-instrument ecosystem integration that locks in core facility service contracts. Defend against CRISPR-based programmable systems by accelerating backward integration into specialized fluorophore synthesis to neutralize German and Japanese supplier concentration risk. Prioritize ISO 13485 certification investment to capture diagnostic-adjacent workflow expansion before unvalidated reagent vendors achieve compliance. For New Entrants and Emerging Players: Academic core facilities in NIH-funded research institutes represent the most penetrable entry point, as shared instrumentation grants mandate standardized platform selection that fragments incumbent relationships. Target developmental biology application expansion for embryonic stem cell lineage tracing studies, where consumable demand from academic segments remains underserved by lower-margin bulk reagent suppliers. Pursue modular assay panel design that pivots buyer choice away from monolithic detection kits toward configurable RNA imaging workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among sample-prep automation specialists with modular platforms integrating across third-party imaging systems, as procurement consolidation favors consumable-anchored recurring revenue models. Long-term viability across the analysis window rests on CRISPR licensing estate navigation and cloud-connected imaging data localization compliance. Watch for inflection in pharmaceutical screening automation contracts as large molecule developers seek configurable assay panels across therapeutic programs.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Licensing Agreement | Broad Institute patent estate access reduces royalty stack burden for programmable RNA-binding protein commercialization. |
| ISO 13485 Certification Investment | Quality management validation creates competitive moats against unvalidated reagent vendors under EMA's 2022 regulatory framework. |
| Cloud-Connected Imaging Infrastructure | Region-housed image analysis platforms comply with GDPR cross-border transfer restrictions proliferating across European member states. |
| Backward Integration into Fluorophore Synthesis | In-house production of photostable organic dyes neutralizes input cost volatility from German and Japanese chemical supplier concentration. |
| Pharmaceutical Core Facility Partnership | Multi-year service contracts with high-content screening departments anchor recurring consumable demand from regulatory-grade validation workflows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with core facility directors, reagent procurement managers, pharmaceutical toxicology leads, regulatory affairs specialists, and biomedical imaging engineers with secondary validation against FDA 510(k) filings, EMA IVD submissions, NIH instrumentation grant databases, and ISO 13485 certification registries. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates across detection method, application, end user, and technology dimensions.
Segment-weighting approaches distributed value estimates across fluorescent probe-based, hybridization-mediated, and amplification-coupled detection methods, with pharmaceutical screening automation and disease diagnostics applications receiving distinct regulatory-grade validation premiums. CAGRs derived from instrument installation base expansion, consumable pull-through rates, and CRISPR-based technology substitution curves. Forecast inputs incorporated precision medicine infrastructure funding trajectories in the United States, Germany, and Japan alongside EMA and FDA regulatory pathway evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CRISPR patent estate litigation resolution, specialized fluorophore supply allocation disruptions, and genomic data sovereignty law proliferation affecting cloud-connected imaging system deployment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Northern Blotting Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market