
 Custom Nucleic Acid Market | 2026-2036
Custom Nucleic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Nucleic Acid Market Analytics
Contract manufacturing revenue is fragmenting as pharmaceutical sponsors internalize oligonucleotide synthesis capabilities. Thermo Fisher Scientific leverages its integrated instrumentation and reagent portfolio to control upstream workflows. Integrated DNA Technologies anchors the high-complexity custom oligo segment with proprietary synthesis chemistries.
Custom nucleic acids comprise sequence-defined DNA, RNA, and synthetic oligonucleotides manufactured through solid-phase phosphoramidite chemistry or enzymatic synthesis, with purity grades spanning research-use to GMP-certified therapeutic grade. These molecules serve as primers, probes, gene constructs, and active pharmaceutical ingredients in precision medicine workflows. Oligonucleotides command the dominant product share as antisense and siRNA therapeutics advance through clinical pipelines. Gene therapy applications attract the fastest investment velocity, while synthetic biology platforms create downstream pull for plasmid DNA at industrial scale.
FDA's Chemistry, Manufacturing, and Controls guidance for oligonucleotide therapeutics shapes product specifications and batch-release protocols in the United States. EMA's Good Manufacturing Practice Annex 2 revisions for biological substances extend compliance burdens for European suppliers. ISO 13485 and ISO 9001 certifications function as baseline market-access credentials across jurisdictions. Stakeholders must monitor regulatory divergence between FDA and EMA purity thresholds as therapeutic oligo pipelines mature.
Market Dynamics
Pharmaceutical sponsors are internalizing oligonucleotide synthesis capabilities to protect intellectual property and compress development timelines, fragmenting contract manufacturing revenue while concentrating high-complexity production among integrated platform providers.
Growth Catalysts
- Gene therapy pipeline expansion:Antisense and siRNA therapeutics advance through clinical stages, pulling demand for GMP-certified oligonucleotides as active pharmaceutical ingredients.
- FDA accelerated approval pathways:Shortened development timelines for nucleic acid therapeutics compress procurement cycles and expand sponsor budgets for custom synthesis.
- CRISPR editing workflows:Guide RNA and donor template demand from academic and commercial gene editing programs scales synthesis volumes for high-purity RNA constructs.
Market Restraints
- Phosphoramidite monomer cost volatility:Specialty chemical feedstocks for solid-phase synthesis face supply concentration among limited specialty chemical manufacturers, squeezing margin predictability.
- GMP facility scarcity:Therapeutic-grade oligonucleotide manufacturing requires dedicated cleanroom infrastructure with limited qualified capacity in the United States and Europe.
- Enzymatic synthesis technical ceiling:Current enzymatic platforms struggle with sequence length and modification density versus phosphoramidite chemistry, constraining substitution potential.
Strategic Opportunities
- Plasmid DNA industrial scale-up:Synthetic biology platforms and viral vector manufacturing create downstream pull for kilogram-scale plasmid production currently supplied by fragmented providers.
- EMA Annex 2 compliance services:European Good Manufacturing Practice revisions for biological substances create advisory and certification revenue streams for quality consulting specialists.
- mRNA manufacturing platform convergence:Lipid nanoparticle formulation and synthetic chemistry integration opportunities emerge as vaccine and therapeutic developers seek end-to-end suppliers.
Industry Challenges
- Phosphoramidite chemist talent scarcity:Solid-phase synthesis expertise concentrates among aging specialists with limited training pipeline replacement, constraining capacity expansion.
- ISO 13485 certification timelines:Medical device-grade quality system implementation for diagnostic oligonucleotides extends 12-18 month market entry delays for new entrants.
- Legacy ERP integration friction:Electronic batch record systems for nucleic acid manufacturing require custom configuration with existing pharmaceutical sponsor procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Nucleic Acid Market |
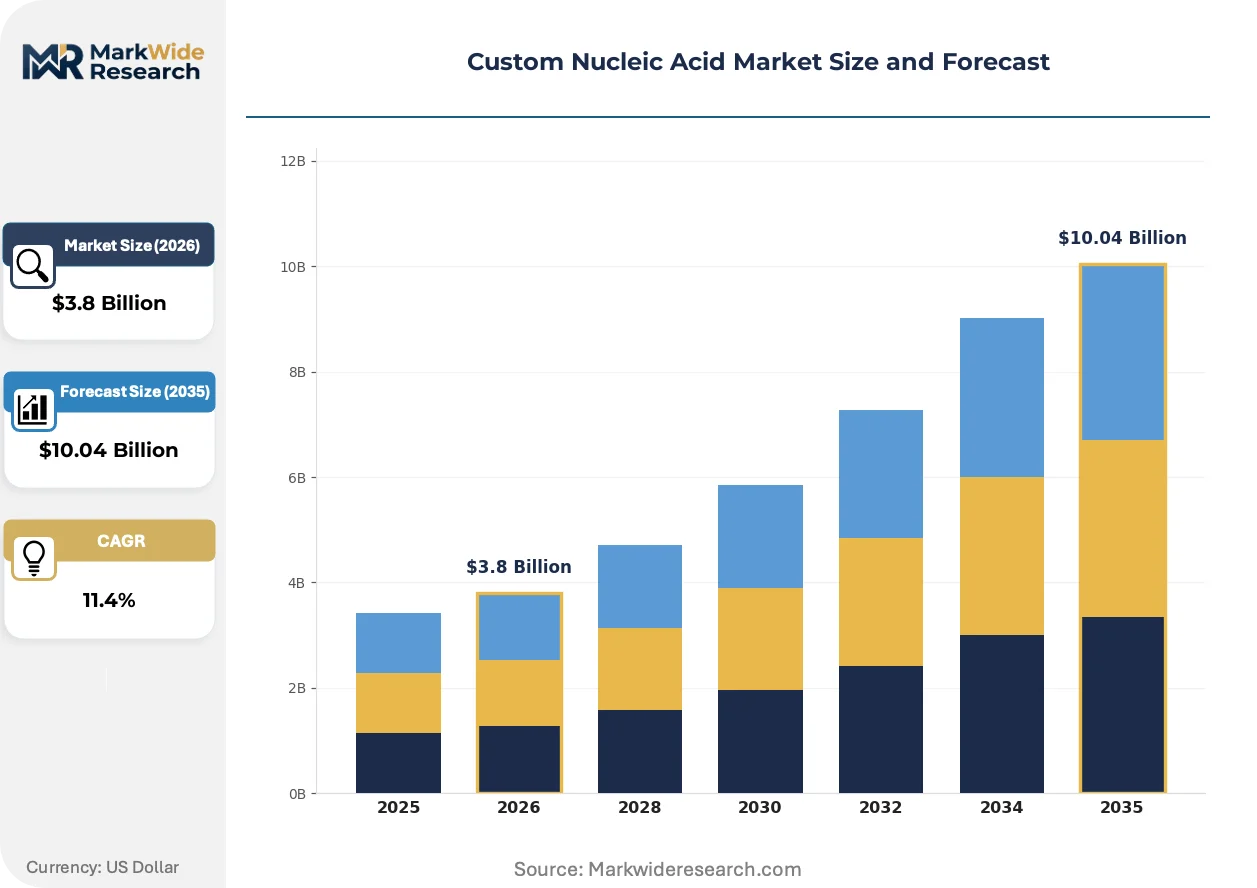
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligonucleotides, Plasmids, RNA, DNA Technology: Sequencing, PCR, Synthesis, Amplification End User: Research Institutions, Pharmaceutical Companies, Biotech Firms, Contract Research Organizations Application: Gene Therapy, Diagnostics, Vaccine Development, Synthetic Biology |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Integrated DNA Technologies, Danaher Corporation, Agilent Technologies, Eurofins Scientific, Lonza, Bachem, LGC Biosearch Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Nucleic Acid Market Evolving Landscape
Enzymatic synthesis platforms are disrupting established phosphoramidite chemistry workflows, while regulatory guidance convergence and buyer consolidation reshape competitive positioning across the value chain.
Enzymatic DNA synthesis using template-independent polymerases is rendering obsolete traditional solid-phase phosphoramidite methods for sequences exceeding 200 bases. Gene synthesis providers and synthetic biology platforms adopt these systems to compress turnaround times from weeks to days. The structural consequence is commoditization pressure on research-grade oligonucleotides while concentrating premium pricing on therapeutic-grade certification.
EMA's Good Manufacturing Practice Annex 2 revisions for biological substances extend impurity profiling and batch-release documentation requirements for European suppliers. Manufacturers must demonstrate endotoxin control and bioburden management beyond prior small-molecule standards. The segment most affected is contract manufacturing organizations serving European pharmaceutical sponsors, which are investing in dedicated quality assurance headcount and analytical instrumentation.
Biopharmaceutical sponsors now consolidate oligonucleotide procurement under single-source agreements with integrated platform providers rather than fragmenting across specialty synthesis houses. This channel concentration displaces mid-tier custom oligo vendors from therapeutic pipelines and redirects their focus toward research-use and diagnostic segments. The geographic concentration of this shift is most visible in the United States, where top-20 pharmaceutical sponsors have reduced qualified supplier lists by 40 percent since 2022.
Custom Nucleic Acid Market Segmentation
Segmentation in the custom nucleic acid market reveals how purity grades, synthesis platforms, and regulatory certifications partition value capture. Each dimension carries distinct margin profiles and competitive barriers that determine supplier positioning.
Product Type:
The use-case spectrum spans research-grade reagents through GMP-certified active pharmaceutical ingredients, with purity thresholds and documentation requirements escalating across tiers.
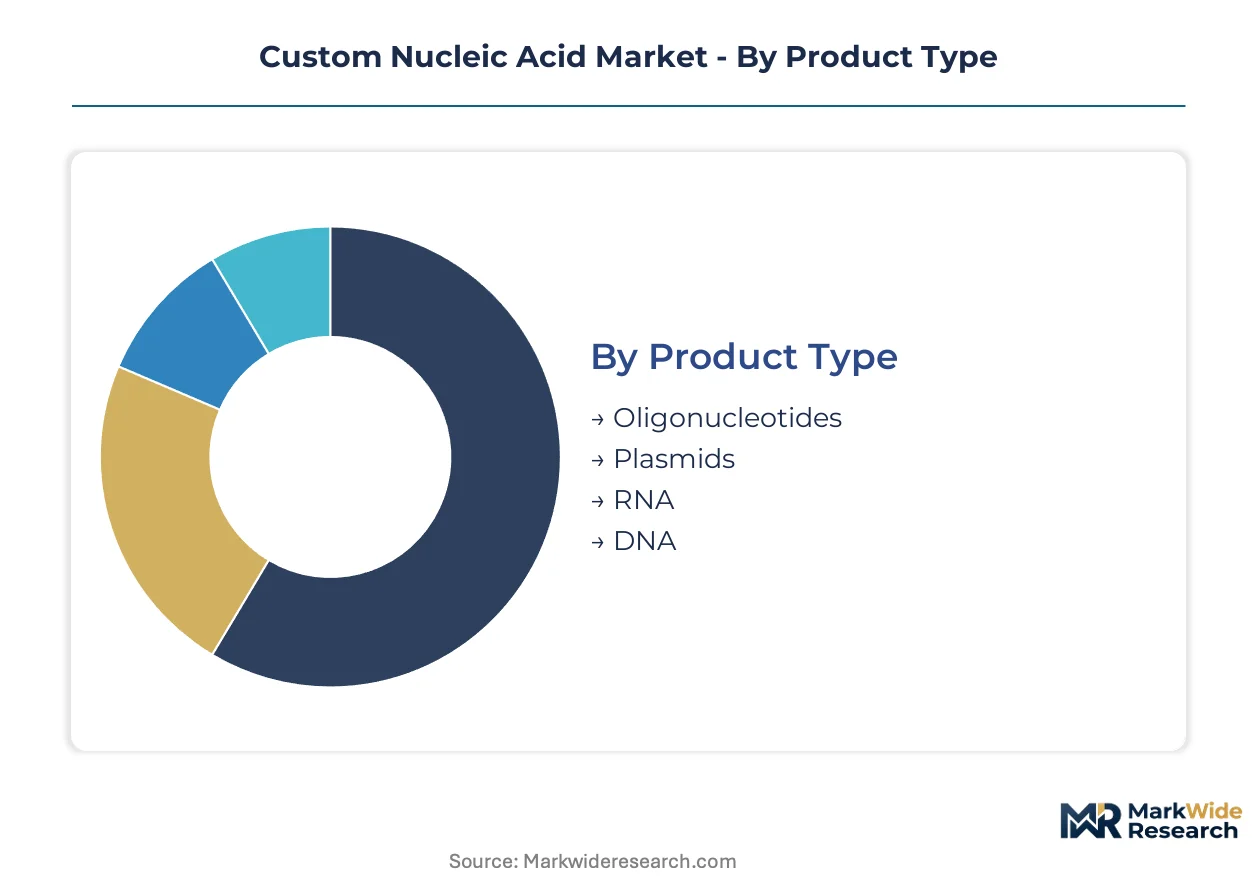
- Oligonucleotides:Sequence-defined DNA and RNA molecules manufactured through solid-phase phosphoramidite chemistry or emerging enzymatic platforms. Antisense and siRNA therapeutics in United States clinical pipelines pull demand for kilogram-scale GMP production with sub-ppm impurity profiles.
- Plasmids:Circular DNA vectors serving as gene therapy raw material and mRNA manufacturing templates. Synthetic biology platforms and viral vector producers in the United States and Germany are industrializing kilogram-scale production currently supplied by fragmented providers.
- RNA:Messenger RNA, guide RNA, and long non-coding RNA constructs requiring specialized handling for stability. Lipid nanoparticle formulation workflows create integrated supply opportunities.
- DNA:Gene constructs, donor templates, and double-stranded fragments for CRISPR editing and cloning applications. Research institutions dominate procurement volumes at standard purity grades.
The dominant share belongs to oligonucleotides, while plasmids are closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive automated platforms from manual synthesis workflows, with throughput and error rates determining per-base economics.
- Synthesis:Solid-phase phosphoramidite chemistry remains the workhorse for sub-200-base sequences, while enzymatic platforms using template-independent polymerases compress turnaround times for longer constructs. Gene synthesis providers are adopting enzymatic systems to displace traditional workflows.
- PCR:Polymerase chain reaction reagents and primers constitute high-volume, lower-margin research-grade demand. Standardized chemistries and automated purification sustain price compression.
- Sequencing:Custom adapters, barcodes, and capture probes for next-generation sequencing workflows. Clinical diagnostic laboratories in the United States drive specification tightening for batch-to-batch consistency.
- Amplification:Isothermal and quantitative amplification chemistries requiring modified nucleotides and specialized primer architectures. Point-of-care diagnostic developers concentrate demand.
Synthesis commands the largest revenue pool, though enzymatic platforms are expanding most quickly.
End User:
Customer type determines procurement sophistication, with pharmaceutical sponsors imposing vendor qualification protocols that exclude research-grade suppliers.
- Pharmaceutical Companies:Integrated sponsors internalizing oligonucleotide synthesis capabilities to protect intellectual property and compress development timelines. FDA accelerated approval pathways for nucleic acid therapeutics expand budgets for qualified custom synthesis.
- Biotech Firms:Venture-funded developers lacking captive manufacturing infrastructure and dependent on contract manufacturing organizations with GMP certification. EMA Annex 2 compliance requirements extend supplier qualification burdens for European-facing programs.
- Research Institutions:Academic laboratories and core facilities procuring research-use-only grades with standard desalting or HPLC purification. Price sensitivity and fragmented purchasing characterize this segment.
- Contract Research Organizations:Service providers bridging discovery and clinical stages with variable purity requirements. Sponsor audit demands drive ISO 13485 and ISO 9001 certification investments.
Pharmaceutical companies retain the dominant procurement volume, while biotech firms are gaining share fastest.
Application:
Volume and margin profiles diverge sharply between therapeutic-grade and research-grade applications, with regulatory burden as the primary discriminator.
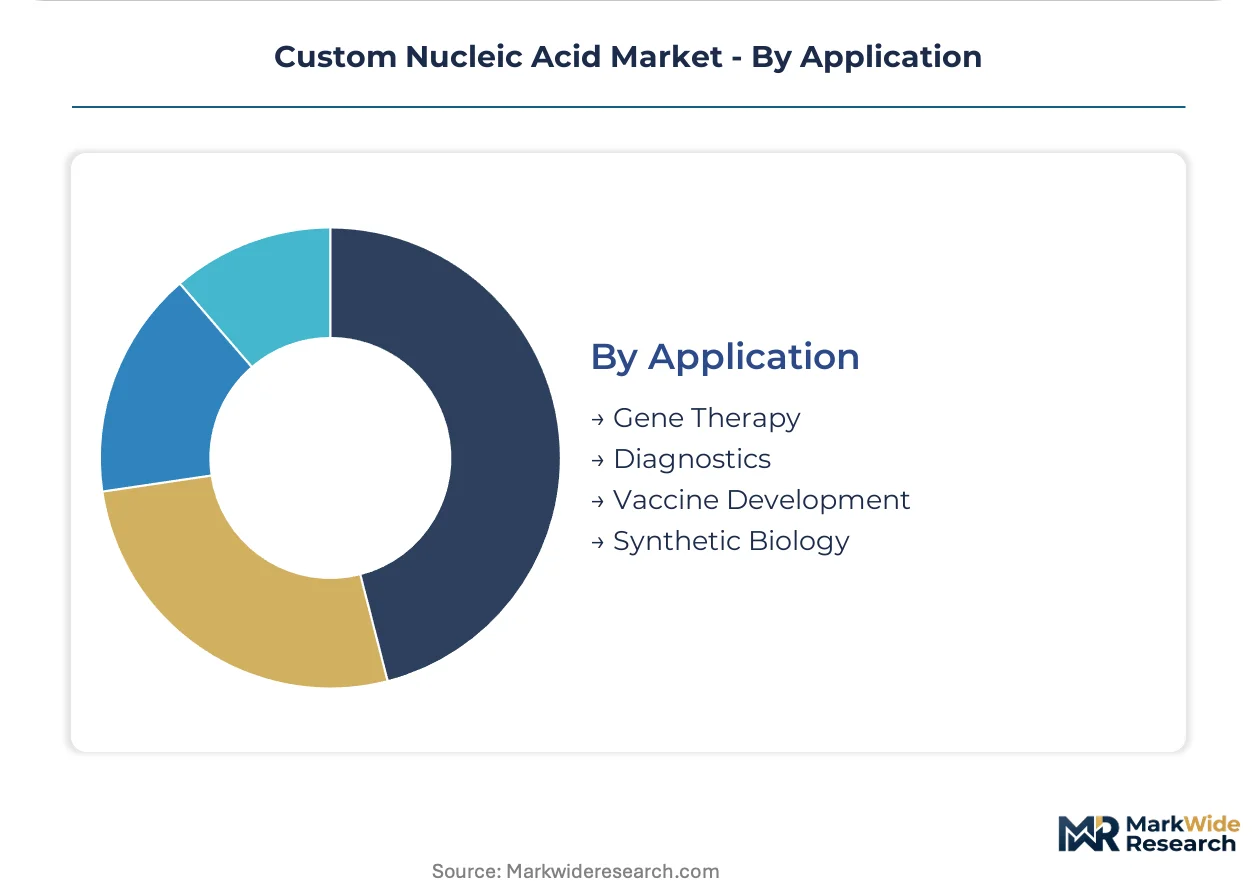
- Gene Therapy:Viral vector manufacturing, CRISPR editing workflows, and nucleic acid active pharmaceutical ingredients requiring GMP-grade oligonucleotides and plasmids. FDA Chemistry, Manufacturing, and Controls guidance shapes product specifications and batch-release protocols in the United States.
- Vaccine Development:mRNA manufacturing platforms and adjuvant formulations pulling demand for high-purity RNA constructs and lipid nanoparticle integration. Pandemic-era capacity investments are now repurposing toward therapeutic indications.
- Diagnostics:PCR primers, FISH probes, and next-generation sequencing adapters for clinical and research testing. ISO 13485 certification timelines of 12-18 months constrain new entrant access to medical device-grade segments.
- Synthetic Biology:Engineered gene circuits, metabolic pathway optimization, and industrial enzyme production. Kilogram-scale plasmid demand from fermentation-based manufacturing platforms is outpacing current supplier capacity.
Gene therapy holds the dominant application share, with synthetic biology climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical feedstock supply for phosphoramidite monomers concentrates among German and Swiss manufacturers, while therapeutic-grade manufacturing capacity clusters in FDA-regulated zones. GMP-certified oligonucleotide production requires proximity to sponsor audit infrastructure and qualified analytical laboratories.
United States
Gene therapy sponsors in Boston and San Francisco drive GMP oligonucleotide procurement for antisense and siRNA clinical programs. FDA's Chemistry, Manufacturing, and Controls guidance for oligonucleotide therapeutics mandates sub-ppm impurity thresholds and electronic batch records. The Research Triangle Park corridor anchors contract manufacturing capacity expansion as CDMOs build dedicated cleanroom suites for therapeutic-grade synthesis.
Germany
Specialty phosphoramidite chemical production concentrates in Ludwigshafen and Leverkusen, supplying global solid-phase synthesis workflows. EMA's Annex 2 revisions for biological substances extend endotoxin control requirements beyond prior small-molecule standards. The Heidelberg-Mannheim biotech cluster absorbs quality consulting and certification services as European sponsors adapt to tightened GMP protocols.
Switzerland
Swissmedic's alignment with FDA purity standards attracts gene therapy developers seeking dual-continent regulatory pathways. Basel's pharmaceutical corridor hosts integrated platform providers combining oligonucleotide synthesis with lipid nanoparticle formulation. The Lake Geneva region concentrates precision medicine infrastructure where plasmid DNA demand from viral vector manufacturers outpaces qualified supplier capacity.
China
NMPA's accelerated review pathways for innovative nucleic acid therapeutics compress development timelines for domestic biotech sponsors. Shanghai's Zhangjiang Hi-Tech Park clusters enzymatic synthesis platform providers serving synthetic biology applications. Suzhou Industrial Park anchors GMP plasmid manufacturing investments as viral vector developers localize supply chains.
United Kingdom
MHRA's post-Brexit regulatory autonomy enables tailored approval frameworks for mRNA therapeutics and CRISPR-based editing programs. The Golden Triangle between London, Cambridge, and Oxford concentrates academic gene therapy research pulling research-grade oligonucleotide volumes. Stevenage's cell and gene therapy cluster attracts CDMO investments for GMP-certified oligo production serving European-facing pipelines.
Custom Nucleic Acid Market Competitive Landscape
Integrated life science conglomerates and specialized oligonucleotide synthesis houses split the market along therapeutic-grade certification lines. Consolidation pressures concentrate high-complexity production among platform providers with captive analytical instrumentation portfolios. Three archetypes dominate: diversified conglomerates with reagent-to-service integration, pure-play synthesis specialists with proprietary chemistries, and emerging enzymatic platform disruptors. Competitive moves center on GMP facility buildouts and strategic partnerships with lipid nanoparticle formulation providers.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify upstream-to-downstream integration strategies spanning synthesis instrumentation through clinical-grade manufacturing. Integrated DNA Technologies anchors the high-complexity custom oligo specialist tier with proprietary phosphoramidite chemistries. These three companies represent divergent paths to value capture: instrumentation lock-in, synthesis chemistry differentiation, and end-to-end therapeutic service bundling.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Integrated DNA Technologies |
| Danaher Corporation |
| Agilent Technologies |
| Eurofins Scientific |
| Lonza |
| Bachem |
| LGC Biosearch Technologies |
| Others |
Value Network & Pricing Analysis
Phosphoramidite monomer supply concentration among German and Swiss specialty chemical manufacturers creates simultaneous pricing tier compression and geographic sourcing rigidity across the custom nucleic acid value chain. This single-source dependency forces GMP-certified oligonucleotide producers to absorb feedstock volatility while maintaining fixed contract pricing with pharmaceutical sponsors.
Pricing Analysis
FDA's Chemistry, Manufacturing, and Controls guidance dictates the pricing tier structure across therapeutic-grade, diagnostic-grade, and research-use segments. Three-tier pricing separates GMP-certified active pharmaceutical ingredients from ISO 13485-compliant diagnostic reagents and standard desalted research oligos, with certification level and impurity thresholds as primary differentiation drivers. Cost compression in the research-grade tier is intensifying because enzymatic synthesis platforms are displacing phosphoramidite workflows for longer constructs. Academic laboratories exhibit the highest price sensitivity, while gene therapy sponsors prioritize supply security over unit economics.
Supply Chain Analysis
Thermo Fisher Scientific, Danaher Corporation, and Lonza hold concentrated contract manufacturing capacity for therapeutic-grade oligonucleotides across the United States, Germany, and Switzerland. Specialty phosphoramidite chemical production draws from Ludwigshafen and Leverkusen in Germany, while GMP plasmid manufacturing rests on Basel and Zurich facilities in Switzerland. Single-source vulnerability in phosphoramidite monomer supply creates structural exposure to feedstock disruption. Distribution runs through qualified supplier agreements with pharmaceutical sponsors rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic synthesis substitution threatens established phosphoramidite chemistry incumbents, requiring defensive capability investments to preserve pricing power and customer lock-in.
For Market Incumbents: Harden GMP facility networks against enzymatic disruptors by expanding cleanroom capacity in the Research Triangle Park corridor and securing backward integration into phosphoramidite monomer production. FDA accelerated approval pathway expansion for nucleic acid therapeutics creates sponsor consolidation pressure that favors integrated platform providers with captive analytical instrumentation. For New Entrants and Emerging Players: China's NMPA accelerated review pathways for innovative nucleic acid therapeutics represent the most penetrable geographic entry point for enzymatic synthesis specialists. Synthetic biology platforms in Shanghai's Zhangjiang Hi-Tech Park offer white-space demand for rapid-turnaround gene synthesis services. A research-grade-to-GMP upgrade pathway serves as the optimal go-to-market angle. For Investors and Strategic Acquirers: EMA's Annex 2 GMP revisions for biological substances reshape the acquisition landscape by elevating quality consulting and certification capabilities to strategic value. The five-to-ten-year viability window favors contract manufacturing organizations with demonstrated FDA and EMA dual-continent compliance. The signal to watch is pharmaceutical sponsor internalization announcements that fragment contract manufacturing revenue.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Buildout | FDA Chemistry, Manufacturing, and Controls guidance mandates sub-ppm impurity thresholds that require dedicated cleanroom infrastructure. |
| Enzymatic Platform Adoption | Template-independent polymerase systems compress turnaround times for sequences exceeding 200 bases versus phosphoramidite chemistry. |
| Phosphoramidite Backward Integration | Specialty chemical feedstock concentration in Ludwigshafen and Leverkusen creates margin vulnerability for non-integrated manufacturers. |
| Lipid Nanoparticle Partnership | mRNA therapeutic developers seek end-to-end suppliers combining oligonucleotide synthesis with formulation integration. |
| EMA Annex 2 Compliance Services | European Good Manufacturing Practice revisions extend endotoxin control requirements beyond prior small-molecule standards. |
Research Methodology
Desk research of FDA Chemistry, Manufacturing, and Controls guidance documents, EMA GMP Annex 2 revisions, and ClinicalTrials.gov nucleic acid therapeutic filings preceded structured interviews with gene therapy development executives, regulatory affairs leads at pharmaceutical sponsors, GMP facility quality directors, and contract manufacturing procurement managers. Secondary validation drew from SEC 10-K disclosures of diversified life science conglomerates, ISO certification registry data, and phosphoramidite chemical trade flow records. Bottom-up synthesis volume estimates triangulated against top-down pharmaceutical sponsor R&D expenditure allocations.
Assumptions held fixed include FDA and EMA regulatory trajectory continuity, phosphoramidite chemistry cost structures, and pharmaceutical sponsor outsourcing ratios; variables tested include enzymatic synthesis substitution rates and sponsor internalization decisions. Segmentation modeling spanned product type, purity grade, synthesis platform, end-user sophistication, and regional regulatory cluster across the analysis window. CAGRs derived from sponsor pipeline progression rates, capacity expansion announcements, and therapeutic oligonucleotide approval velocity. Gene therapy clinical stage advancement and synthetic biology platform scaling served as volume projection anchors.
The forecast holds incumbent behavior within observed patterns; aggressive enzymatic platform scaling by emerging disruptors or accelerated sponsor internalization would shift outcomes beyond modeled ranges. Regulatory divergence between FDA and EMA purity thresholds, phosphoramidite monomer supply disruption, and CRISPR therapeutic approval setbacks constitute specific revision risks. Quarterly review of gene therapy sponsor supplier qualification announcements and enzymatic synthesis platform commercialization milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Multiplex Biomarker Imaging Market