
 Fish Vaccines Market | 2026-2036
Fish Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Vaccines Market Foresight
Subscription-based vaccine monitoring and herd health analytics is restructuring how aquaculture operators procure fish vaccines. Merck Animal Health leverages its diagnostics-to-vaccine pipeline to sustain long-term contracts with large salmonid producers. Zoetis dominates the injectable segment through controlled distribution networks in North America and Europe. Kyoto Biken Laboratories anchors Asian supply by specializing in attenuated vaccines for carp and eel species.
Fish vaccines are biologics formulated from inactivated pathogens, attenuated organisms, purified subunits, or recombinant antigens, designed to induce adaptive immunity in finfish against bacterial and viral diseases; most commercial formulations require cold-chain storage at 2–8°C and achieve protective titers within 14–21 days post-administration. Their primary purpose is to reduce antibiotic dependency in intensive aquaculture while securing yield stability for protein supply chains. Inactivated vaccines currently occupy the largest revenue share due to proven efficacy against Aeromonas and Vibrio infections, though DNA vaccines represent the fastest-expanding category as regulatory pathways mature for nucleic-based platforms in salmonids. Oral administration methods are gaining traction in tilapia and carp systems where labor costs for injection are prohibitive, while immersion delivery retains margin concentration in high-value salmonid hatcheries.
The European Medicines Agency oversees centralized marketing authorization for fish vaccines under the EU Veterinary Medicines Regulation, while the FDA Center for Veterinary Medicine evaluates autogenous and licensed products for U.S. aquaculture. REACH compliance for adjuvant chemicals and ECHA substance restrictions shape formulation choices for suppliers accessing European farms. Stakeholders must monitor how evolving DNA vaccine guidelines from the FDA and accelerating national aquaculture health programs in Norway and Chile will reshape competitive access and product registration timelines.
Market Dynamics
The EU Veterinary Medicines Regulation is compressing registration timelines for nucleic-based platforms while Norwegian salmon hatcheries accelerate immersion vaccine protocols, restructuring competitive access for DNA vaccine developers against established inactivated formulations.
Growth Catalysts
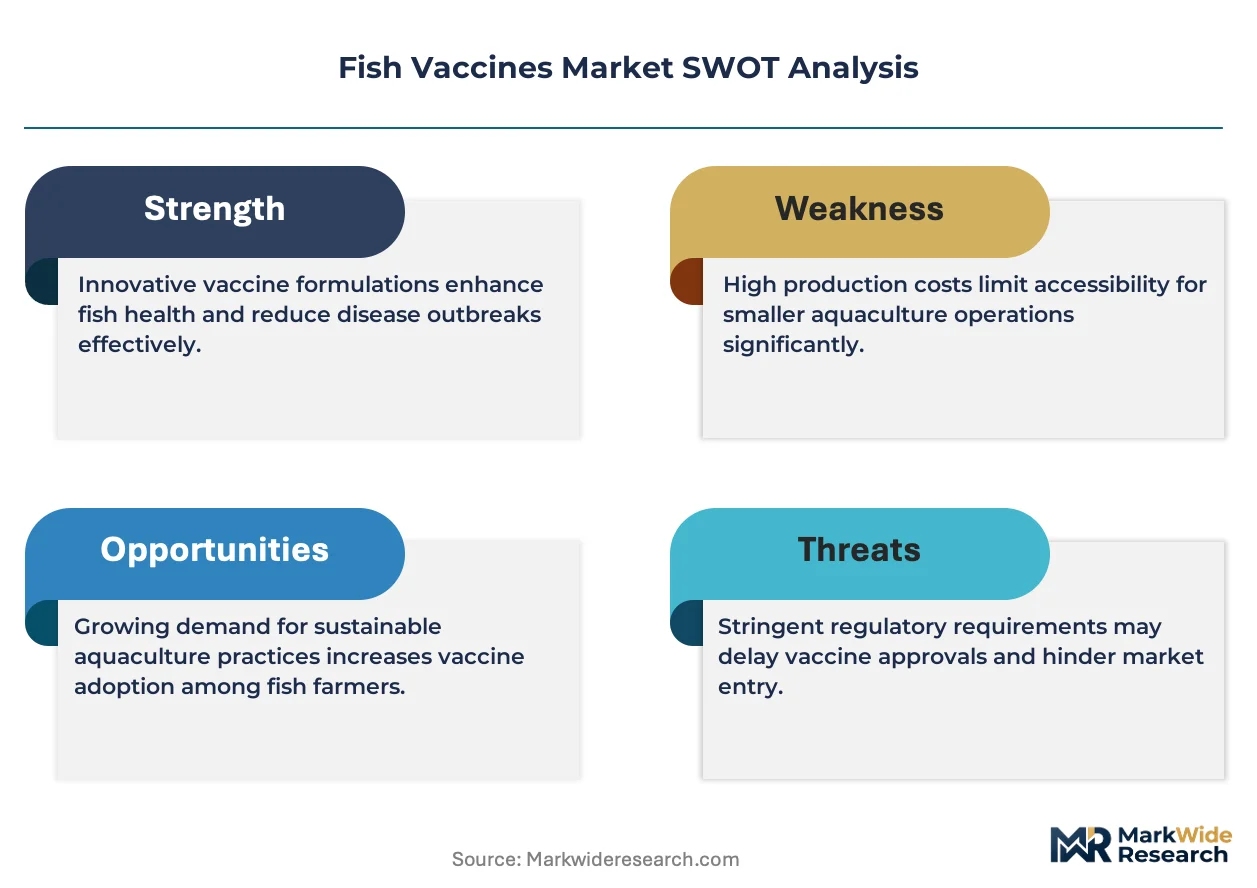
- Regulatory Acceleration:The EU Veterinary Medicines Regulation is streamlining centralized marketing authorization for DNA vaccines, reducing approval bottlenecks that previously favored inactivated platforms. This framework is opening nucleic-based pathways for salmonid producers seeking alternatives to antibiotic-dependent disease management.
- Chilean Demand Concentration:Salmon farming zones across Chile's Los Lagos region are scaling vaccine procurement as bacterial kidney disease pressure intensifies in high-density aquaculture operations. Local operators are prioritizing immersion-administered formulations that align with existing hatchery infrastructure.
- Attenuated Platform Specialization:Asian carp and eel producers are driving adoption of live-attenuated vaccines that deliver single-dose protection against viral hemorrhagic septicemia. These formulations reduce labor costs compared to multi-dose injection protocols in extensive pond systems.
Market Restraints
- Cold-Chain Infrastructure Gaps:Rural aquaculture clusters in Southeast Asia lack reliable 2–8°C storage networks, forcing reliance on less thermolabile inactivated formulations despite their inferior immunogenicity profiles.
- Adjuvant Chemical Restrictions:ECHA substance restrictions under REACH compliance are limiting aluminum-based adjuvant options, compelling reformulation investments that extend development timelines for European market entry.
- Technical Limitation in Oral Delivery:Gastric degradation in tilapia and carp digestive systems reduces antigen bioavailability for oral vaccines, constraining efficacy rates below injectable alternatives in intensive production environments.
Strategic Opportunities
- Underpenetrated Indian Aquaculture:India's shrimp and carp sectors remain vaccine-naive despite rising white spot syndrome outbreaks. CDSCO regulatory pathways for autogenous vaccines present first-mover positioning for platform developers.
- Subscription Monitoring Services:Herd health analytics bundled with vaccine supply contracts are creating recurring revenue streams. Norwegian salmonid producers are piloting these integrated diagnostics-to-vaccine pipelines.
- DNA-Subunit Convergence:Combining recombinant antigen expression with nucleic delivery vectors is enabling multivalent protection against Aeromonas and Vibrio complexes in single-administration protocols.
Industry Challenges
- Skill Shortage in Aseptic Injection:Labor pools capable of intraperitoneal vaccine administration in salmonid hatcheries are contracting in remote Chilean and Norwegian coastal zones, elevating training costs and error rates.
- Batch Certification Delays:EMA lot-release testing for inactivated bacterial vaccines extends lead times by 4–6 weeks, forcing inventory pre-positioning that strains working capital for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Vaccines Market |
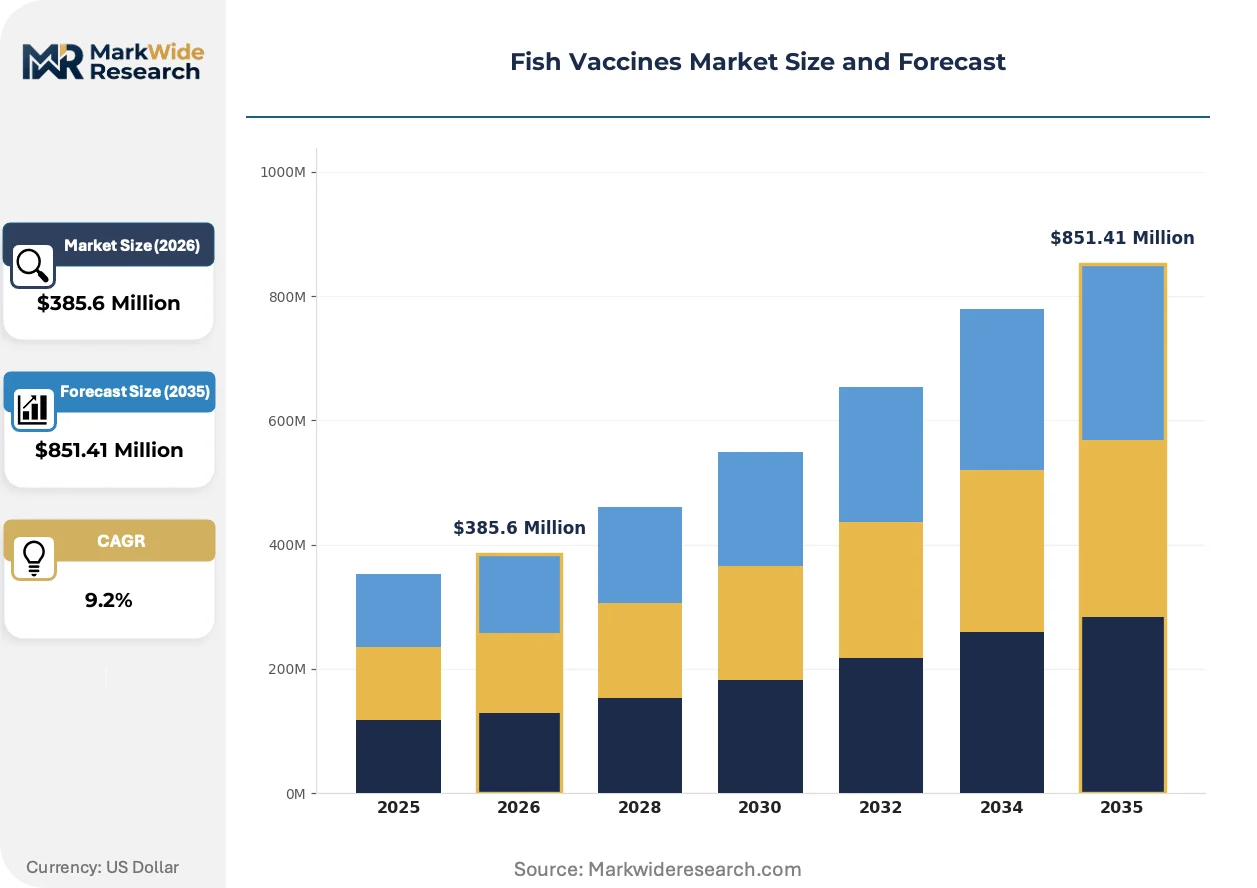
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $851.41 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Attenuated, Subunit, DNA, Recombinant, Toxoid Target Species: Salmonids, Catfish, Tilapia, Carp, Trout, Eels Administration Method: Injection, Oral, Immersion, Spray, Topical End User: Aquaculture Farms, Research Institutions, Government Agencies, Private Hatcheries |
| Companies Covered | Vaxxinova International, Tecnovax, Merck Animal Health, Elanco Animal Health, Veterquimica, Zoetis, Kyoto Biken Laboratories, Phibro Animal Health, HIPRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Vaccines Market Shifts & Advancements
DNA vaccine platforms are compressing development cycles for salmonid pathogens while regulatory frameworks mature across multiple geographies. These shifts are redrawing competitive boundaries between nucleic-based innovators and established inactivated formulation suppliers.
Recombinant subunit technology is electrifying multivalent vaccine design by enabling precise antigen selection against bacterial kidney disease and infectious salmon anemia. Norwegian hatcheries are adopting these platforms at pilot scale ahead of full commercial rollout. The technology is electrifying margin structures by reducing adjuvant volumes and cold-chain intensity compared to whole-cell alternatives.
REACH compliance requirements for adjuvant chemicals are forcing reformulation investments across European suppliers. ECHA substance restrictions are narrowing approved excipient lists, compelling developers to validate novel immunostimulant compounds. DNA vaccine developers are responding fastest, as their platforms require minimal chemical adjuvantation compared to inactivated formulations.
Subscription-based procurement is displacing transactional vaccine purchasing among large salmonid producers. Merck Animal Health and Zoetis are anchoring multi-year contracts that bundle diagnostics, vaccine supply, and mortality analytics. This model concentrates most visibly in Norway, where vertically integrated aquaculture operators prioritize yield predictability over per-dose cost minimization.
Fish Vaccines Market Segmentation
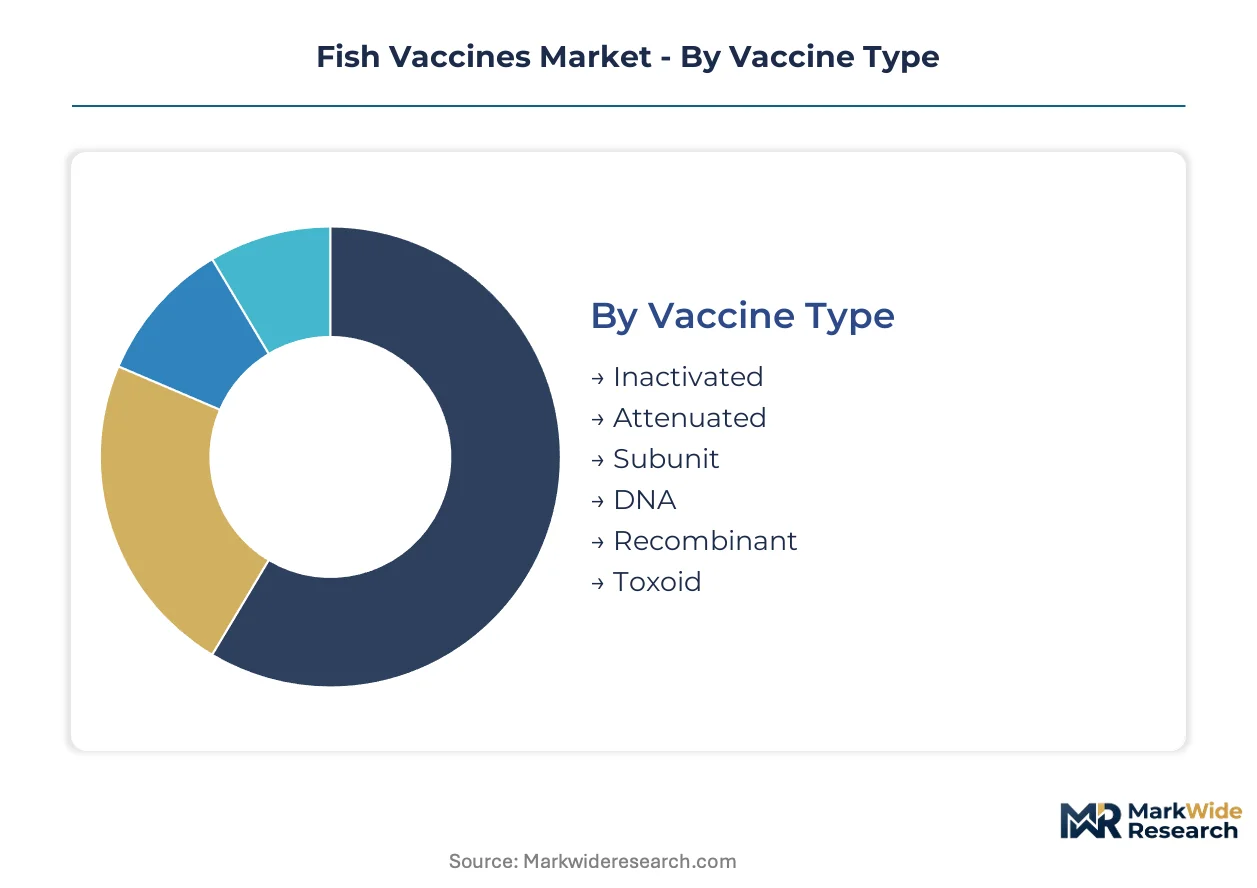
Fish vaccines segment across multiple technical and operational dimensions that determine formulation economics, delivery infrastructure requirements, and regulatory pathways. Understanding these divisions reveals where platform investments concentrate and which combinations unlock margin expansion.
Vaccine Type:
Inactivated formulations function as standalone products requiring minimal cold-chain infrastructure, while DNA and subunit platforms embed into integrated health management systems with diagnostics bundling.
- Inactivated:Whole-cell bacterial preparations killed through formalin or heat treatment retain immunogenic surface antigens. Demand clusters in Southeast Asian carp operations where 2–8°C storage reliability remains inconsistent and cost sensitivity dominates procurement decisions.
- DNA:Nucleic acid vectors encoding pathogen antigens expressed in host cells after intramuscular delivery. Norwegian salmonid hatcheries are scaling immersion-adapted DNA protocols as EMA streamlines centralized marketing authorization for nucleic-based platforms.
- Attenuated:Live pathogens weakened through serial passage deliver single-dose protection. Kyoto Biken Laboratories anchors Asian supply for carp and eel species.
- Subunit:Purified protein antigens selected for precise immune targeting. Reformulation investments accelerate as REACH compliance narrows aluminum-based adjuvant options.
- Recombinant:Genetically engineered antigens produced in bacterial or yeast expression systems. Multivalent designs against Aeromonas and Vibrio complexes reduce administration frequency.
- Toxoid:Bacterial exotoxins inactivated to preserve immunogenicity while eliminating toxicity. Limited commercial penetration outside experimental Vibrio applications.
Volume placements concentrate in Inactivated; the faster expansion belongs to DNA.
Target Species:
Species segmentation maps directly onto geography and production system intensity, with high-value salmonids commanding premium formulation investments versus extensive pond species.
- Salmonids:Atlantic salmon and rainbow trout in intensive marine cage systems drive the highest per-dose vaccine spending globally. Chile's Los Lagos region and Norwegian coastal zones account for dominant procurement volumes as bacterial kidney disease pressure intensifies.
- Carp:Extensive pond aquaculture across India and Southeast Asia operates with minimal vaccination history despite rising white spot syndrome outbreaks. CDSCO regulatory pathways for autogenous vaccines present first-mover positioning for platform developers.
- Tilapia:Warm-water production systems prioritize oral administration methods where labor costs for injection prove prohibitive. Gastric degradation constraints limit efficacy versus injectable alternatives.
- Catfish:Channel catfish operations in the southern United States maintain established vaccination protocols against Edwardsiella ictaluri.
- Trout:Freshwater and anadromous strains occupy niche premium markets with specialized hatchery infrastructure.
- Eels:Japanese and European production concentrates attenuated vaccine demand through Kyoto Biken's regional specialization.
Revenue concentrates in Salmonids; share gains are steepest in Carp as vaccine-naive sectors activate.
Administration Method:
Delivery modality selection hinges on labor economics, fish size at vaccination, and hatchery infrastructure configuration.
- Injection:Intraperitoneal delivery achieves superior antigen bioavailability and protective titers within 14–21 days. Skill shortages in remote Chilean and Norwegian coastal zones elevate training costs and error rates.
- Immersion:Bath exposure suits small fish in hatchery settings where handling stress must be minimized. Norwegian salmon hatcheries are accelerating immersion vaccine protocols ahead of commercial DNA platform rollout.
- Oral:Feed-incorporated antigens reduce labor requirements but suffer gastric degradation in tilapia and carp digestive systems. Procurement is shifting toward this modality where workforce constraints bite hardest.
- Spray:Aerosolized delivery for juvenile fish in tank systems offers intermediate handling intensity.
- Topical:Direct application to skin or gill surfaces remains experimental with limited commercial validation.
Margin concentration sits with Injection; Oral is climbing the fastest as labor costs reshape hatchery economics.
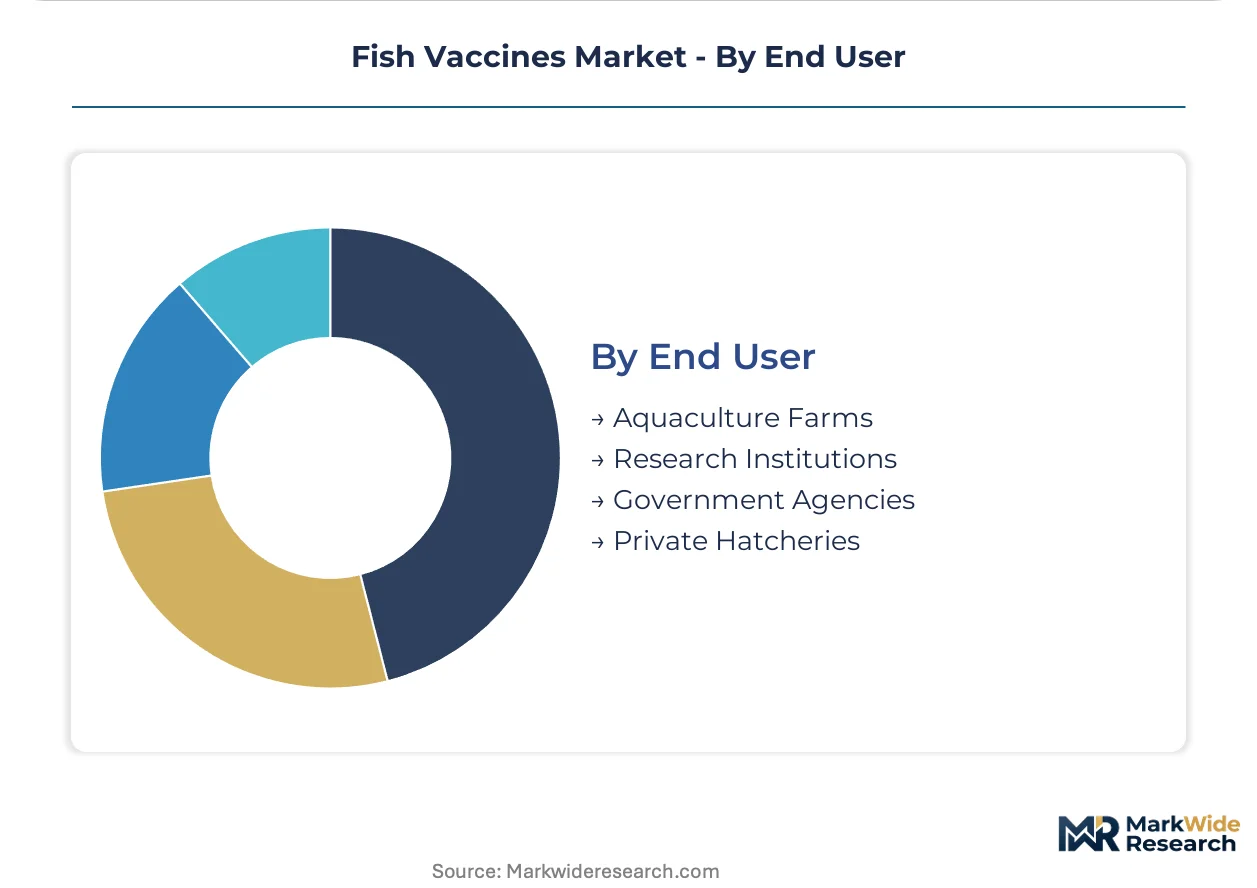
End User:
Customer type determines contract structure, with integrated operators driving subscription-based procurement versus transactional purchasing.
- Aquaculture Farms:Large salmonid producers in Norway and Chile prioritize multi-year contracts bundling diagnostics, vaccine supply, and mortality analytics. Vertically integrated operators favor yield predictability over per-dose cost minimization.
- Private Hatcheries:Smaller-scale operations in India and Southeast Asia remain price-sensitive with limited cold-chain investment capacity. Distribution runs through regional distributors with working capital constraints from EMA lot-release testing delays.
- Research Institutions:Academic and government laboratories pilot novel platforms ahead of regulatory submission.
- Government Agencies:National aquaculture health programs in Norway and Chile shape competitive access through procurement centralization.
Contract value concentrates in Aquaculture Farms; activation rates are highest in Private Hatcheries as vaccine penetration deepens in emerging production zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of fish vaccines concentrates in Norway and Chile where salmonid aquaculture dominates, while consumption spreads across Asian carp and shrimp operations where vaccine penetration remains shallow. The divide creates supply-chain tension between cold-chain-intensive biologics producers and price-sensitive extensive pond systems.
Norway
Atlantic salmon hatcheries along the Norwegian coast drive the highest per-dose vaccine spending globally, with bacterial kidney disease pressure intensifying procurement of immersion-administered formulations. The Norwegian Medicines Agency coordinates with EMA on centralized marketing authorization for DNA vaccine platforms. Bergen and Trondheim harbor clusters anchor nucleic-based vaccine pilot programs ahead of commercial rollout.
Chile
Salmon farming zones in the Los Lagos region scale vaccine procurement as high-density aquaculture operations face escalating disease pressure. The country's national pharmaceutical regulator enforces residue limits that accelerate shifts away from antibiotic-dependent management. Puerto Montt and Chiloé Island concentrate immersion vaccine adoption aligned with existing hatchery infrastructure.
United States
Channel catfish operations in the southern states maintain established vaccination protocols against Edwardsiella ictaluri, while emerging demand surfaces in offshore aquaculture permitting zones. The FDA Center for Veterinary Medicine evaluates autogenous and licensed products under evolving nucleic-based guidelines. Mississippi Delta processing clusters sustain injectable formulation demand despite labor cost pressures.
India
Shrimp and carp sectors remain largely vaccine-naive despite rising white spot syndrome outbreaks across Andhra Pradesh and Gujarat pond systems. CDSCO regulatory pathways for autogenous vaccines present positioning opportunities for platform developers entering untapped production zones. Kochi and Visakhapatnam aquaculture belts show early trial activity for oral delivery methods.
Japan
Japanese eel and carp producers sustain demand for live-attenuated vaccines through specialized hatchery networks. PMDA oversight of veterinary biologics maintains stringent batch certification requirements that favor established suppliers with regulatory navigation experience. Shizuoka and Aichi prefectures concentrate domestic vaccine manufacturing serving regional Asian export markets.
Fish Vaccines Market Competitive Landscape
Capital-heavy producers with captive manufacturing infrastructure compete with asset-light formulation specialists outsourcing biological production to contract manufacturing organizations. The market structure tilts toward consolidation at the premium salmonid tier while fragmenting across Asian carp and shrimp segments. Three archetypes dominate: vertically integrated animal health conglomerates with diagnostics-to-vaccine pipelines, regional specialists commanding single-species or single-geography positions, and research-derived spinouts commercializing university nucleic-platform patents. Dominant competitive moves include multi-year subscription contracting bundling analytics with supply, and backward integration into adjuvant chemistry to preempt REACH compliance disruptions.
Within the integrated animal health tier, Merck Animal Health and Zoetis exemplify scale-driven positions spanning multiple species and geographies. Kyoto Biken Laboratories occupies a specialist archetype, its name signaling Japanese origin and concentrated focus on attenuated platforms. These three entities represent distinct strategic postures: the conglomerate bundling diagnostics and vaccines into recurring revenue structures, the diversified pharmaceutical incumbent leveraging controlled distribution networks, and the regional laboratory anchoring Asian supply through species-specific expertise.
| Leading Market Players |
|---|
| Vaxxinova International |
| Tecnovax |
| Merck Animal Health |
| Elanco Animal Health |
| Veterquimica |
| Zoetis |
| Kyoto Biken Laboratories |
| Phibro Animal Health |
| HIPRA |
| Others |
Supply & Pricing Matrix
DNA vaccine platform maturation is compressing development timelines while simultaneously redrawing cost structures and supplier concentration, as nucleic-based formulations reduce adjuvant dependency and cold-chain intensity versus inactivated alternatives. Norwegian and Chilean salmonid producers now wield procurement leverage over formulation specialists locked into legacy whole-cell production infrastructure.
Pricing Analysis
Margin tightening in inactivated formulations reflects REACH-driven adjuvant reformulation costs and EMA lot-release testing delays that strain distributor working capital. Three-tier pricing structure across premium DNA-subunit combinations, standard inactivated bacterial vaccines, and economy-grade attenuated platforms separates Norwegian integrated operators from Indian private hatcheries. Pricing pressure stems from oral delivery method adoption in tilapia and carp systems where labor cost constraints override efficacy premiums. Private hatcheries in Southeast Asia exhibit highest price sensitivity; Norwegian vertically integrated salmonid producers prioritize yield predictability over per-dose minimization.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and Chilean cold-chain infrastructure for nucleic-based platform distribution. Manufacturing concentration in Norway, Chile, and Japan draws from live-attenuated strain banks, recombinant antigen expression systems, and synthetic DNA vector production. Supply chain risk centers on aluminum-based adjuvant restrictions under ECHA substance limitations that force reformulation investments. Distribution runs through controlled veterinary networks anchored by Merck Animal Health and Zoetis, with regional distributors serving price-sensitive Asian carp operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in fish vaccines is becoming a vertical-integration race, with incumbents pursuing backward control over adjuvant chemistry and diagnostic bundling to preempt regulatory disruption and secure recurring revenue structures.
For Market Incumbents: Deploy subscription-based diagnostics-to-vaccine pipelines to lock in Norwegian and Chilean salmonid producers before DNA platform commoditization accelerates. Consolidate formulation capacity in Bergen and Puerto Montt clusters to compress EMA and national regulator lot-release lead times. Counter emerging nucleic-platform specialists by anchoring long-term contracts with mortality analytics that yield-predictability-dependent operators cannot replicate internally. For New Entrants and Emerging Players: Capture India's vaccine-naive shrimp and carp sectors through CDSCO autogenous vaccine pathways before incumbents establish cold-chain presence in Andhra Pradesh and Gujarat. Target oral delivery method specialization for tilapia systems where gastric degradation constraints have stalled incumbent efficacy gains. Pursue platform licensing from Japanese research institutions to bypass PMDA batch certification barriers that favor established suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated animal health conglomerates seeking nucleic-platform patents and regional hatchery relationships. Long-term viability hinges on regulatory navigation capabilities across EMA, FDA, and CDSCO frameworks rather than single-market dominance. Watch for DNA vaccine guideline finalization from FDA Center for Veterinary Medicine as inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Adjuvant Chemistry Backward Integration | ECHA REACH compliance narrows approved excipient lists, forcing in-house immunostimulant production. |
| Immersion Delivery Infrastructure Expansion | Norwegian hatcheries accelerate bath-administered DNA protocols ahead of commercial platform rollout. |
| Diagnostics-to-Vaccine Pipeline Bundling | Merck Animal Health anchors multi-year contracts with mortality analytics that lock in yield predictability. |
| CDSCO Autogenous Vaccine Pathway Entry | India's shrimp and carp sectors present first-mover positioning before incumbent cold-chain establishment. |
| Recombinant Subunit Multivalent Design | Precise antigen selection against Aeromonas and Vibrio complexes reduces administration frequency in salmonids. |
Research Methodology
Document review covered EMA centralized marketing authorization filings, FDA Center for Veterinary Medicine nucleic-based guidelines, CDSCO autogenous vaccine regulations, and Chilean national pharmaceutical regulator residue limit enforcements, complemented by interviews with aquaculture health program directors, veterinary biologics regulatory affairs leads, salmonid hatchery operations managers, and shrimp farm procurement officers. Secondary validation drew from EU Veterinary Medicines Regulation implementation documents, Norwegian Medicines Agency DNA vaccine pilot program disclosures, and REACH compliance adjuvant restriction notices. Bottom-up demand modeling across species segments and top-down supply capacity assessments triangulated volume and value estimates.
Cross-segment growth trajectories emerged from vaccine type, target species, administration method, and end-user contracting structure dimensions across the projection horizon. CAGRs derived from regression analysis of historical adoption curves in Norwegian and Chilean salmonid operations, adjusted for regulatory acceleration effects and cold-chain infrastructure buildout rates in Indian and Southeast Asian production zones. Forecast inputs incorporated EMA lot-release testing delay distributions, oral delivery method efficacy degradation coefficients, and attenuated vaccine single-dose protection duration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA DNA vaccine guideline finalization timing, ECHA adjuvant substance restriction scope expansion, and Indian aquaculture health program centralization decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
US Bio Pesticides Market