
 Global Neoantigen Cancer Vaccine Market | 2026-2036
Global Neoantigen Cancer Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neoantigen Cancer Vaccine Market Foresight
Modular trial designs that bundle biomarker testing with vaccine manufacturing are repositioning procurement decisions for oncology centers. BioNTech SE leverages its integrated mRNA production network to sustain supply security across European and North American clinical sites. Moderna Inc competes through dedicated neoantigen pipelines that anchor its oncology diversification beyond infectious disease platforms. Gritstone bio, Inc. specializes in AI-driven epitope prediction, differentiating its offering through computational speed rather than manufacturing scale.
Neoantigen cancer vaccines comprise personalized immunotherapeutics engineered from patient-specific tumor mutations, synthesized as peptide, mRNA, or dendritic cell formulations to elicit targeted T-cell responses against malignant cells. Manufacturing requires next-generation sequencing of tumor biopsies, bioinformatic epitope prediction, and GMP-compliant synthesis with lot release timelines typically spanning four to eight weeks. Peptide-based platforms currently occupy the broadest installed base due to established chemistry and cold-chain simplicity, while mRNA-based formats are recording the fastest expansion as lipid nanoparticle delivery technology matures. Melanoma indication programs dominate active clinical trial enrollment, though non-small cell carcinoma represents the largest addressable patient population for eventual commercial deployment.
FDA breakthrough therapy designation and EMA's PRIME scheme are compressing regulatory review timelines for personalized oncology products, while WHO prequalification frameworks are beginning to address cell and gene therapy standards that encompass neoantigen platforms. The EU AI Act introduces compliance obligations for machine learning components embedded in epitope prediction algorithms, reshaping software validation requirements for European developers. Stakeholders must monitor evolving reimbursement paradigms for single-patient manufacturing, as current payment systems designed for batch pharmaceuticals face structural strain from individualized production economics.
Market Dynamics
Personalized manufacturing economics are compressing procurement cycles for oncology centers, forcing them to restructure payment workflows around single-patient production timelines rather than batch pharmaceutical purchasing patterns.
Growth Catalysts
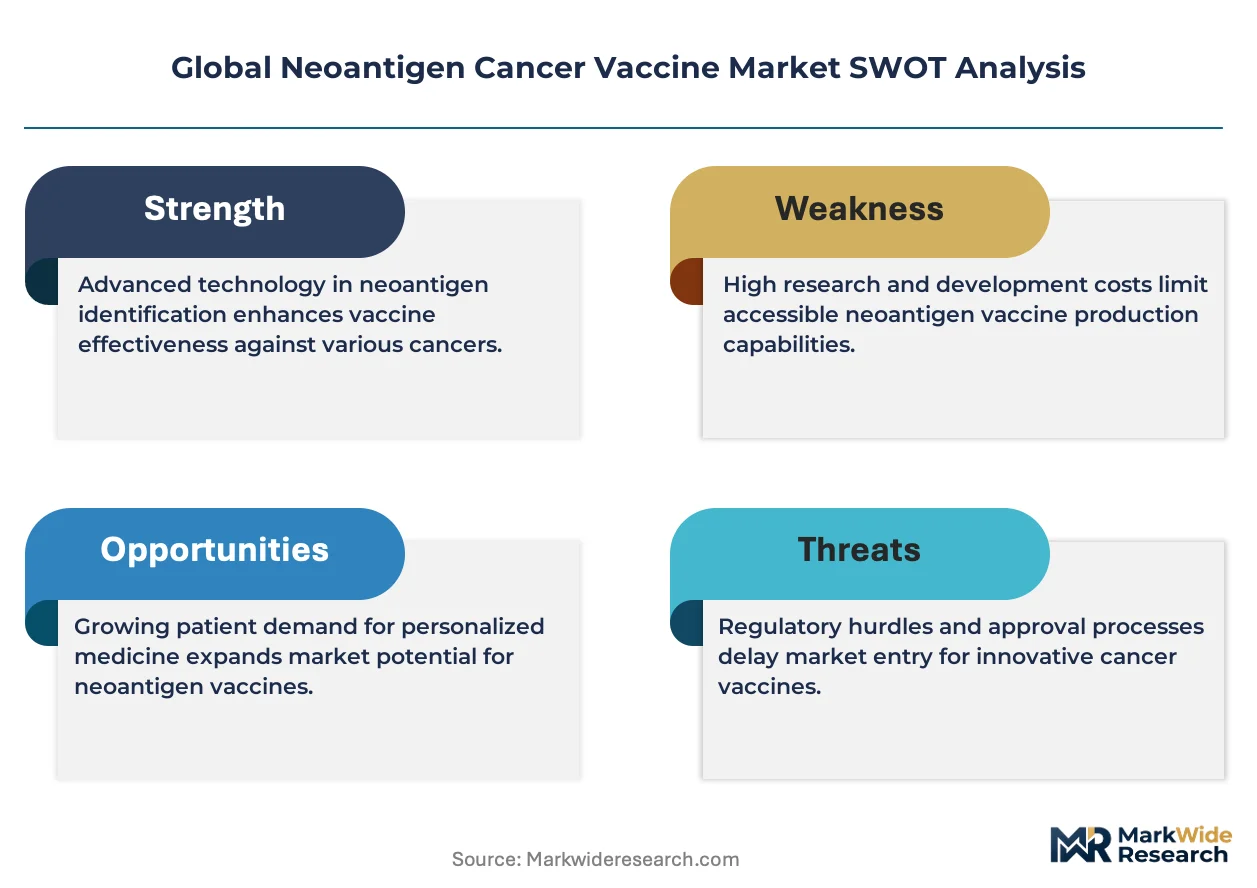
- FDA Breakthrough Therapy Designation:Accelerated review pathways compress development timelines for novel vaccine platforms, compressing the gap between clinical proof and commercial readiness.
- Lipid Nanoparticle Delivery Maturation:Advances in mRNA encapsulation technology are expanding the viable patient population by improving cellular uptake efficiency in solid tumor indications.
- German Manufacturing Cluster Density:Concentrated mRNA production infrastructure in the Rhine-Main region anchors supply security for European and North American clinical trial networks.
Market Restraints
- GMP Synthesis Cost Structure:Lot release timelines spanning four to eight weeks impose working capital intensity that strains mid-cap oncology center budgets.
- Cold-Chain Peptide Distribution:Established peptide platforms require specialized logistics infrastructure that fragments supply security outside major metropolitan hospital networks.
- EU AI Act Compliance Friction:Machine learning validation requirements for epitope prediction algorithms impose software development overhead on European developers.
Strategic Opportunities
- Non-Small Cell Lung Carcinoma Expansion:The largest addressable patient population for commercial deployment remains underpenetrated relative to melanoma-focused clinical development.
- WHO Prequalification Frameworks:Emerging cell and gene therapy standards are creating regulatory harmonization pathways for neoantigen platform export to middle-income health systems.
- AI-Driven Epitope Prediction Convergence:Integration of next-generation sequencing with computational immunology is compressing biomarker-to-vaccine manufacturing workflows.
Industry Challenges
- Bioinformatics Talent Scarcity:Computational immunology expertise required for patient-specific mutation analysis concentrates in a narrow geographic and institutional base.
- Single-Patient Reimbursement Complexity:Health technology assessment frameworks designed for batch pharmaceuticals strain under individualized production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neoantigen Cancer Vaccine Market |
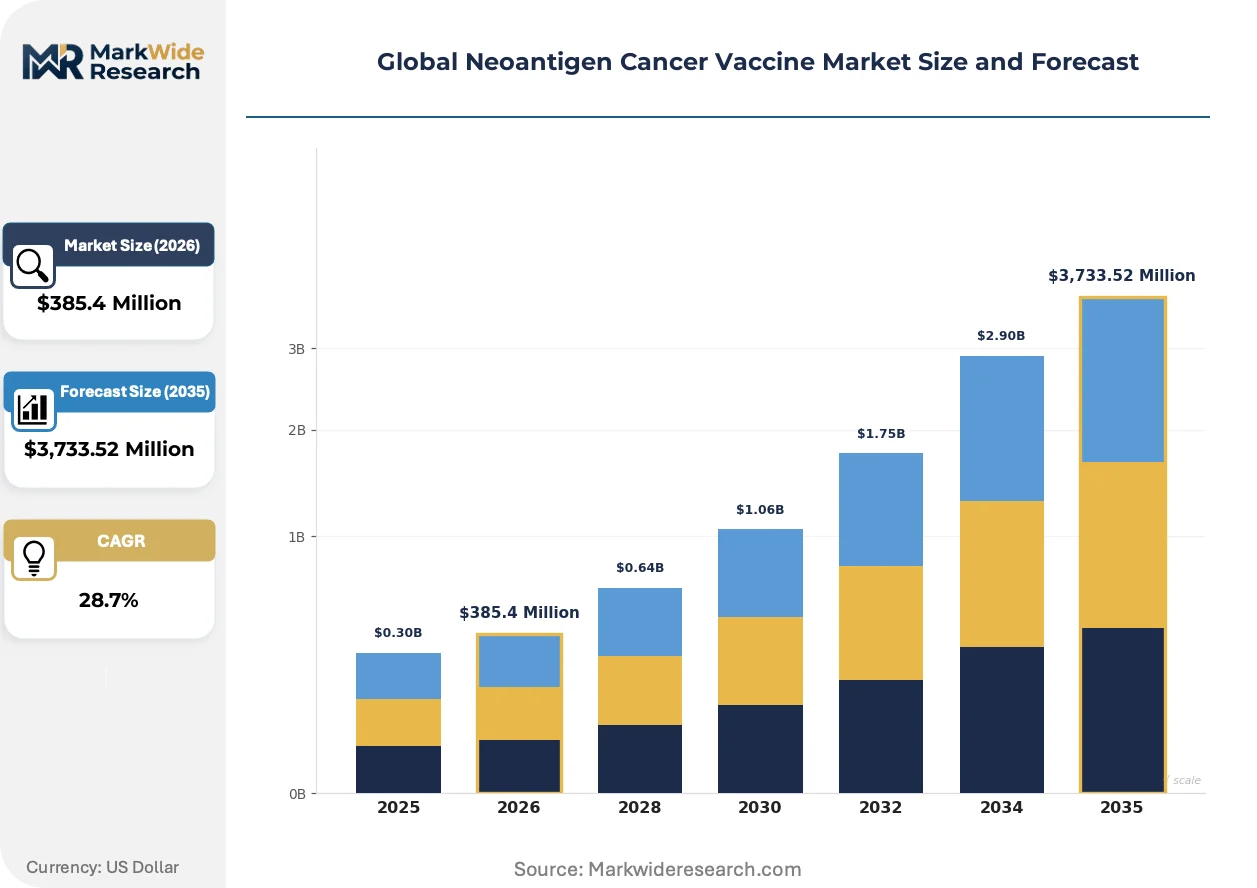
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $3,733.52 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Peptide-Based, mRNA-Based, Dendritic Cell-Based, DNA-Based, Viral Vector-Based Indication: Melanoma, Non-Small Cell Carcinoma, Glioblastoma, Colorectal Carcinoma, Ovarian Carcinoma End User: Oncology Centers, Research Institutes, Biotechnology Firms, Diagnostic Laboratories, Specialty Clinics Delivery Mode: Intramuscular Injection, Subcutaneous Injection, Intradermal Injection, Intravenous Infusion |
| Companies Covered | BioNTech SE, Moderna Inc, Merck & Co., Inc., F. Hoffmann-La Roche Ltd., Gritstone bio, Inc., Agenus Inc., CureVac N.V., OSE Immunotherapeutics SA, Vaccibody AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neoantigen Cancer Vaccine Market Shifts & Advancements
Modular clinical trial architectures are displacing traditional phase-separated development models, bundling biomarker discovery with manufacturing scale-up in compressed regulatory timelines.
Artificial intelligence platforms for neoantigen prediction are integrating directly into GMP manufacturing workflows, enabling real-time epitope refinement during patient-specific vaccine synthesis. Oncology centers in the United States and Germany are adopting these systems at the fastest pace, driven by reimbursement pressure to demonstrate response predictability. This convergence is compressing the traditional separation between diagnostic sequencing and therapeutic manufacturing, collapsing procurement decisions into single-vendor relationships.
The EU AI Act introduces mandatory conformity assessments for machine learning components embedded in clinical decision-support software, including epitope prediction algorithms used in vaccine design. European developers must now document training data provenance and algorithmic transparency to maintain market access. Developers in Germany and Switzerland are responding by segregating EU-facing product versions from global platforms to isolate compliance scope.
Academic medical centers are consolidating purchasing authority for personalized immunotherapy protocols, displacing decentralized procurement by individual oncologists. This concentration forces vaccine manufacturers to restructure sales organizations around centralized pharmacy and therapeutics committees rather than physician detailing. The shift is most visible in the United States, where major cancer center networks are standardizing preferred vendor lists for neoantigen manufacturing services.
Global Neoantigen Cancer Vaccine Market Segmentation
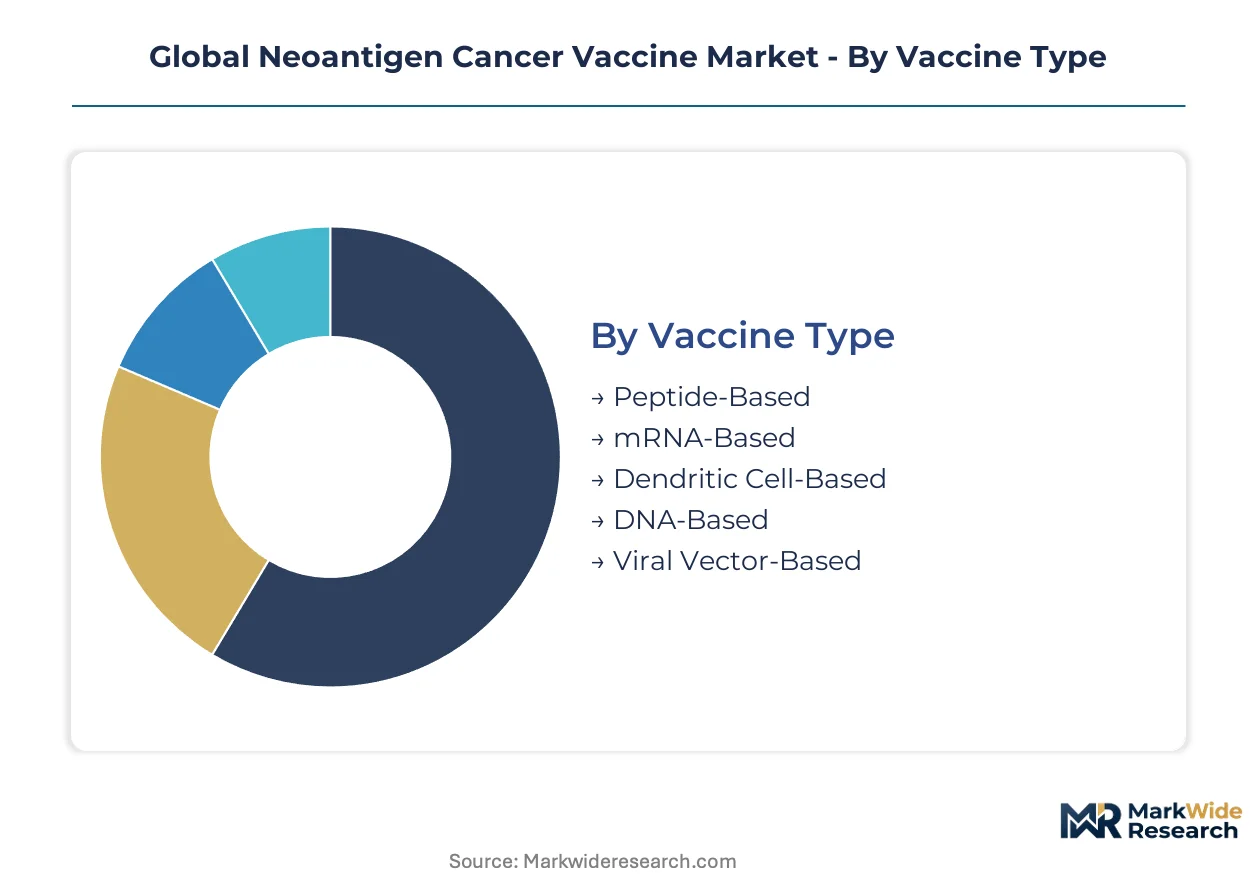
Neoantigen cancer vaccine segmentation reveals how manufacturing complexity and clinical validation status fragment procurement decisions across oncology centers. Each dimension—vaccine type, indication, end user, and delivery mode—carries distinct supply chain implications that reshape vendor selection criteria and reimbursement negotiations.
Vaccine Type:
Manufacturing infrastructure concentrates around established chemistry platforms while mRNA capacity expands fastest in German and Swiss production clusters.
- Peptide-Based:Solid-phase peptide synthesis enables batch production with established cold-chain logistics at 2-8°C. Demand clusters in United States academic medical centers with existing GMP peptide partnerships, constrained by multi-week lot release timelines that strain working capital.
- mRNA-Based:Lipid nanoparticle encapsulation requires specialized microfluidic manufacturing with stringent RNase-free environmental controls. Manufacturing gravity centers on Rhine-Main region facilities serving European and North American trial networks, driven by faster on-demand synthesis cycles.
- Dendritic Cell-Based:Autologous cell processing demands cleanroom facilities with live-cell handling expertise.
- DNA-Based:Plasmid manufacturing leverages established bioprocess infrastructure with simpler stability profiles than RNA.
- Viral Vector-Based:Biosafety level 2+ containment requirements limit production to specialized contract manufacturing organizations.
Peptide-based platforms absorb the bulk of installed capacity; mRNA-based formats are expanding most quickly.
Indication:
Clinical trial enrollment density varies sharply by tumor mutational burden and tissue accessibility for biopsy procurement.
- Melanoma:High tumor mutational burden and accessible cutaneous lesions enable robust neoantigen identification. United States oncology centers dominate active enrollment, supported by mature surgical pathology workflows for serial biopsy collection.
- Non-Small Cell Carcinoma:Largest addressable patient population with established checkpoint inhibitor pretreatment protocols. German lung cancer centers are expanding adoption fastest, driven by reimbursement frameworks for personalized immunotherapy sequencing.
- Glioblastoma:Blood-brain barrier penetration challenges limit delivery mode options and epitope selection.
- Colorectal Carcinoma:Microsatellite instability subtyping directs patient selection for neoantigen approaches.
- Ovarian Carcinoma:Peritoneal dissemination patterns complicate lesion sampling for comprehensive mutational profiling.
Melanoma commands the deepest clinical experience; non-small cell carcinoma offers the steepest expansion trajectory.
End User:
Procurement authority is consolidating from individual oncologists toward centralized pharmacy and therapeutics committees with formal technology assessment capabilities.
- Oncology Centers:Integrated diagnostic and therapeutic infrastructure enables seamless biopsy-to-vaccine workflows. Major United States cancer center networks are standardizing preferred vendor lists, forcing manufacturers to restructure sales organizations around committee-based purchasing.
- Research Institutes:Academic investigator-initiated trials drive early-phase clinical validation with flexible procurement protocols. European institutes in Germany and Switzerland leverage proximity to mRNA manufacturing clusters for rapid protocol activation.
- Biotechnology Firms:In-house manufacturing investments target pipeline assets and platform technology development.
- Diagnostic Laboratories:Sequencing service expansion into therapeutic manufacturing partnerships blurs traditional vendor boundaries.
- Specialty Clinics:Limited scale constrains direct manufacturing relationships, favoring centralized distribution models.
Oncology centers anchor commercial demand; research institutes are gaining share fastest in early-phase development.
Delivery Mode:
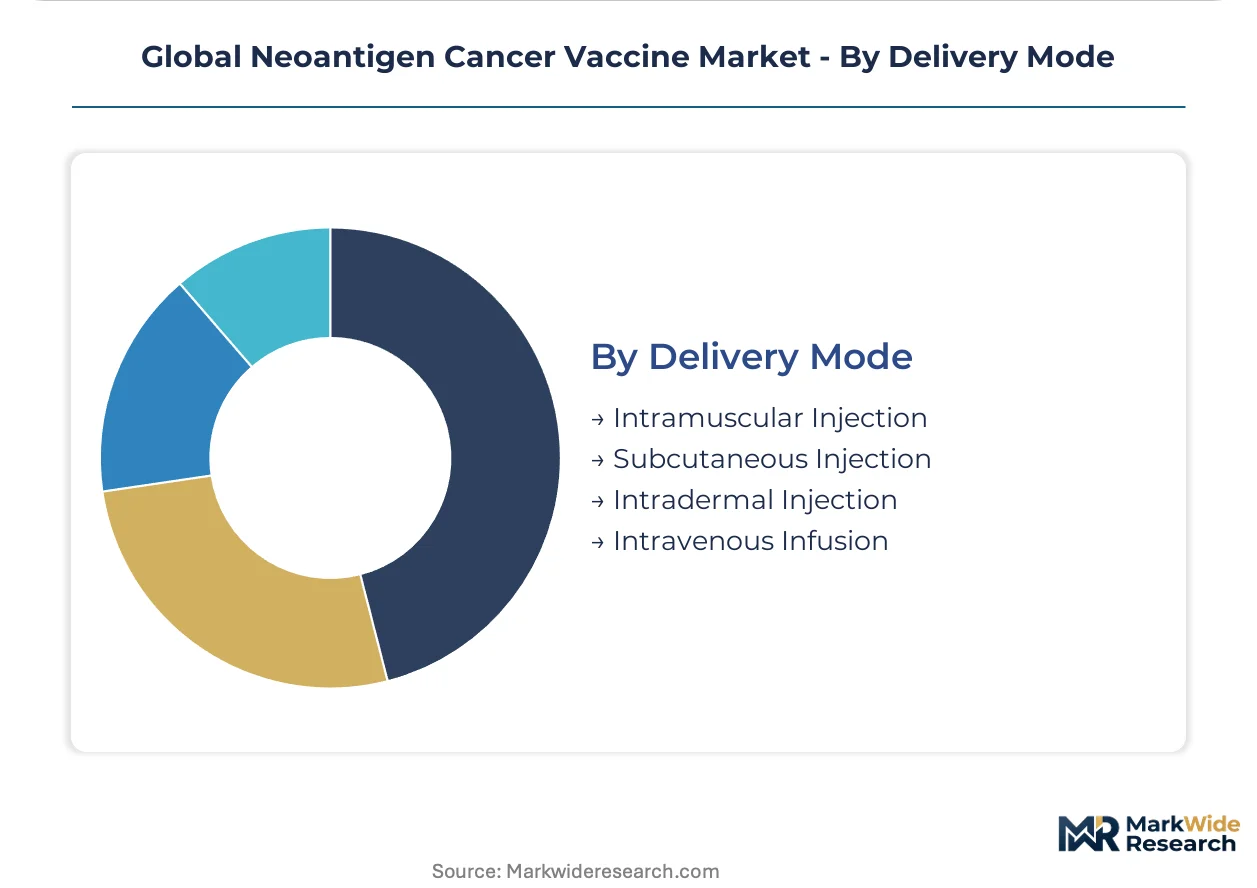
Route selection hinges on target tissue distribution, immune cell density at injection sites, and compatibility with patient-specific vaccine formulations.
- Intramuscular Injection:Large muscle mass accommodates volume loads from lipid nanoparticle suspensions with established lymphatic drainage to regional nodes. United States sites prefer this route for mRNA platforms given familiarity from infectious disease vaccination programs.
- Subcutaneous Injection:Dermal dendritic cell density enables efficient antigen presentation with lower volume constraints. German melanoma centers favor subcutaneous peptide delivery for ambulatory administration.
- Intradermal Injection:Specialized technique requirements limit adoption to specialized nursing protocols.
- Intravenous Infusion:Systemic distribution addresses disseminated disease with higher manufacturing and administration costs.
Intramuscular injection holds the broadest protocol adoption; subcutaneous delivery is climbing the fastest in peptide-based applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Switzerland while consumption concentrates in United States oncology centers, creating transatlantic supply dependencies that reshape procurement timelines and cold-chain logistics networks.
United States
Oncology centers in the United States dominate commercial demand for personalized immunotherapy protocols. FDA breakthrough therapy designation accelerates regulatory pathways for novel vaccine platforms. Major cancer center networks in Boston and New York Metro are consolidating preferred vendor lists for neoantigen manufacturing services.
Germany
The Rhine-Main region anchors the densest mRNA manufacturing infrastructure serving European and North American clinical trial networks. EMA's PRIME scheme compresses review timelines for personalized oncology products. BioNTech SE and CureVac N.V. facilities in Mainz and Tübingen sustain supply security across transatlantic sites.
Switzerland
Swissmedic regulatory frameworks support rapid protocol activation for academic investigator-initiated trials. Basel and Zurich host specialized cleanroom facilities for autologous cell processing. Swiss developers are segregating EU-facing product versions from global platforms to isolate EU AI Act compliance scope.
United Kingdom
London and Cambridge academic medical centers drive early-phase clinical validation with flexible procurement protocols. MHRA recognition of FDA breakthrough therapy pathways enables parallel regulatory submissions. The Greater London oncology network is adopting AI-driven epitope prediction systems at accelerating pace.
China
NMPA cell and gene therapy standards are beginning to address neoantigen platform requirements for domestic market access. Shanghai and Beijing biotech clusters are building GMP peptide synthesis capacity to reduce import dependencies. Chinese developers are targeting WHO prequalification frameworks for middle-income health system exports.
Global Neoantigen Cancer Vaccine Market Competitive Landscape
The competitive structure tilts toward integrated platform specialists with captive manufacturing capacity. Mid-cap biotechnology firms with AI-driven discovery engines occupy the fastest-expanding tier, while established pharmaceutical conglomerates leverage distribution infrastructure for commercial scale-up. Dominant competitive moves include strategic partnerships bundling biomarker testing with manufacturing services, and geographic expansion of GMP synthesis capacity into Rhine-Main and Greater Boston clusters.
Among German-anchored platform developers, BioNTech SE and CureVac N.V. exemplify the integrated manufacturing archetype with concentrated mRNA production infrastructure. Gritstone bio, Inc. represents the computational specialization tier, occupying a position defined by algorithmic speed rather than synthesis scale. These three entities collectively illustrate the strategic divergence between manufacturing gravity and discovery-centric competitive positioning.
| Leading Market Players |
|---|
| BioNTech SE |
| Moderna Inc |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| Gritstone bio, Inc. |
| Agenus Inc. |
| CureVac N.V. |
| OSE Immunotherapeutics SA |
| Vaccibody AS |
| Others |
Supply & Pricing Matrix
Oncology center procurement committees in the United States are consolidating preferred vendor lists for personalized immunotherapy protocols, forcing manufacturers to absorb extended lot release timelines and specialized cold-chain logistics costs into contract structures. This buyer-side concentration compresses margin flexibility across peptide and mRNA production tiers.
Pricing Analysis
Margin tightening in mRNA-based manufacturing reflects lipid nanoparticle encapsulation complexity and RNase-free environmental controls. Pricing stratifies across GMP-certified, clinical-grade, and research-use tiers, with differentiation driven by FDA breakthrough therapy designation status and integrated biomarker testing bundling. Cost-down pressure on peptide platforms accelerates because established chemistry faces commoditization from multi-vendor GMP synthesis networks. Academic medical centers exhibit highest price sensitivity due to grant-funded procurement constraints; integrated cancer center networks with captive pharmacy budgets demonstrate lowest sensitivity.
Supply Chain Analysis
Returns and lot failure protocols for patient-specific vaccines require specialized biohazard handling and destruction documentation that adds administrative overhead to Rhine-Main and Greater Boston distribution nodes. Manufacturing gravity centers on Germany, Switzerland, and the United States, with mRNA production drawing from lipid supplier concentrations in the Rhine-Main region and peptide synthesis anchored in established East Coast pharmaceutical corridors. Raw material dependencies span synthetic lipids, modified nucleosides, and GMP-grade solvents. Single-source vulnerability in lipid nanoparticle formulation equipment creates chokepoint exposure. Distribution runs through centralized pharmacy and therapeutics committees at major oncology networks rather than physician-directed purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Neoantigen Cancer Vaccine Market is consolidating around integrated platform specialists with captive manufacturing capacity, as single-patient production economics and four-to-eight-week lot release timelines force mid-cap developers toward acquisition or partnership exits.
For Market Incumbents: Cement supply security through backward integration into next-generation sequencing and bioinformatic epitope prediction capabilities, insulating against AI-driven computational specialists encroaching on manufacturing relationships. Lock in preferred vendor status with United States cancer center networks by bundling biomarker testing with GMP synthesis under multi-year service agreements. Capacity expansion in the Rhine-Main region reinforces transatlantic clinical trial network access against emerging Swiss and Chinese production clusters. For New Entrants and Emerging Players: Direct-to-oncology-center digital procurement platforms offer lower customer acquisition friction than traditional sales organizations targeting consolidated pharmacy committees. Non-small cell lung carcinoma represents the most penetrable indication given its status as largest addressable patient population with underdeveloped neoantigen protocol penetration relative to melanoma. German lung cancer centers expanding personalized immunotherapy adoption fastest provide geographic beachhead for European market entry. For Investors and Strategic Acquirers: The window for entry favors AI-driven epitope prediction specialists with demonstrated computational speed advantages over manufacturing-scale incumbents, positioned for platform licensing or strategic acquisition. Long-term viability rests on regulatory navigation capabilities across FDA breakthrough therapy and EMA PRIME frameworks. Watch for WHO prequalification framework finalization for cell and gene therapy standards as inflection signal for middle-income health system export viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Modular designs bundling biomarker testing with manufacturing compress regulatory timelines for oncology centers. |
| Manufacturing Scale-Up | Rhine-Main region mRNA capacity expansion secures supply for transatlantic clinical trial networks. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation accelerates commercial readiness for personalized vaccine platforms. |
| Strategic Partnership | Sequencing-to-vaccine service bundling collapses procurement into single-vendor relationships at cancer centers. |
| Pipeline Diversification | Non-small cell lung carcinoma programs address largest addressable population beyond melanoma saturation. |
Research Methodology
Document review covered FDA breakthrough therapy designations, EMA PRIME scheme submissions, ClinicalTrials.gov enrollment data, and EU AI Act implementation guidance, complemented by interviews with drug development executives at mRNA platform developers, regulatory affairs leads managing personalized therapy submissions, hospital procurement managers at United States cancer center networks, and payer access specialists navigating single-patient reimbursement frameworks. Secondary validation drew from SEC biotechnology filings, WHO cell and gene therapy standard drafts, and German mRNA manufacturing cluster economic development reports. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates.
Cross-referencing historical clinical trial activation rates against expert panel input on manufacturing capacity expansion timelines anchored the projection framework. Segmentation modeling spanned vaccine type, indication, end user archetype, and delivery mode, with regulatory pathway clustering by FDA, EMA, and Swissmedic jurisdiction. CAGRs were derived from patient population epidemiology, checkpoint inhibitor pretreatment protocol penetration, and manufacturing scale-up velocity assumptions. Forecast inputs incorporated lipid nanoparticle delivery technology maturation curves and AI-driven epitope prediction algorithm validation timelines.
The model holds under sustained FDA and EMA accelerated review pathway availability; deviation in reimbursement framework adoption for single-patient manufacturing economics or EU AI Act enforcement intensity on machine learning validation would shift commercial deployment trajectories. Practitioners should monitor WHO prequalification framework finalization and oncology center procurement committee vendor consolidation patterns for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market