
 Immunoprecipitation Market | 2026-2036
Immunoprecipitation Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoprecipitation Market Outlook
Multi-source antibody procurement is recalibrating supply strategies across the immunoprecipitation landscape. Thermo Fisher Scientific dominates magnetic bead platform distribution through extensive channel control in North America. GenScript Biotech Corporation anchors recombinant antibody production with in-house mammalian expression systems. Abcam plc differentiates through specialty phospho-specific antibody portfolios that sustain premium positioning in signaling research.
Immunoprecipitation isolates target proteins from complex biological mixtures using antibody-mediated capture on solid-phase matrices such as agarose or superparamagnetic beads, with typical binding capacities ranging from microgram to milligram scales depending on bead surface chemistry. The technique enables downstream analysis of protein-protein interactions, post-translational modifications, and chromatin associations in drug discovery and basic research workflows. Magnetic beads command expanding share due to faster separation protocols and automation compatibility, while agarose retains cost advantages for low-throughput academic settings. Co-immunoprecipitation leads application demand as pharmaceutical firms prioritize target deconvolution in immuno-oncology programs.
FDA biomarker qualification frameworks and EMA's ICH Q2(R1) analytical validation standards shape reagent performance requirements for clinical translation of immunoprecipitation assays. ISO 13485 certification pressures differentiate contract manufacturers serving diagnostic versus research-only segments. Stakeholders must monitor evolving regulatory divergence between jurisdictions as harmonization gaps complicate multi-regional trial designs.
Market Dynamics
Magnetic bead automation protocols are compressing manual workflow timelines across pharmaceutical quality control labs, forcing reagent suppliers to reconfigure kit architectures for liquid-handling compatibility.
Growth Catalysts
- Co-immunoprecipitation workflows:Academic institutions in Germany and the United States are expanding protein interaction studies for immuno-oncology target validation, driving consumable throughput requirements.
- FDA biomarker qualification frameworks:Drug developers must demonstrate analytical validity for immunoprecipitation-based companion diagnostics, expanding assay development service contracts.
- NIH funding concentration:Boston and San Francisco biotech clusters sustain concentrated procurement of high-binding-capacity magnetic bead platforms for chromatin immunoprecipitation sequencing.
Market Restraints
- Recombinant antibody input costs:Mammalian expression system maintenance and serum price volatility constrain margin flexibility for kit manufacturers.
- Supply concentration in coastal China:Agarose resin production clusters near Shanghai create geographic vulnerability to port logistics disruptions.
- Cross-reactivity technical limitations:Phospho-specific antibody batches exhibit lot-to-lot variability that complicates longitudinal study reproducibility.
Strategic Opportunities
- Single-cell immunoprecipitation:Emerging application in rare cell population epigenetic profiling opens premium reagent positioning for oncology researchers.
- India's PLI scheme for biologics:Contract manufacturing incentives attract magnetic bead platform assembly capacity to serve Asia-Pacific demand.
- ISO 13485 certification pathways:Diagnostic-grade reagent qualification enables entry into clinical biomarker testing workflows beyond research-only segments.
Industry Challenges
- Antibody validation specialist scarcity:Cross-reactivity testing and lot qualification require trained immunologists that contract research organizations struggle to retain.
- Multi-regional regulatory divergence:EMA's ICH Q2(R1) analytical validation standards and FDA guidance gaps complicate harmonized assay submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoprecipitation Market |
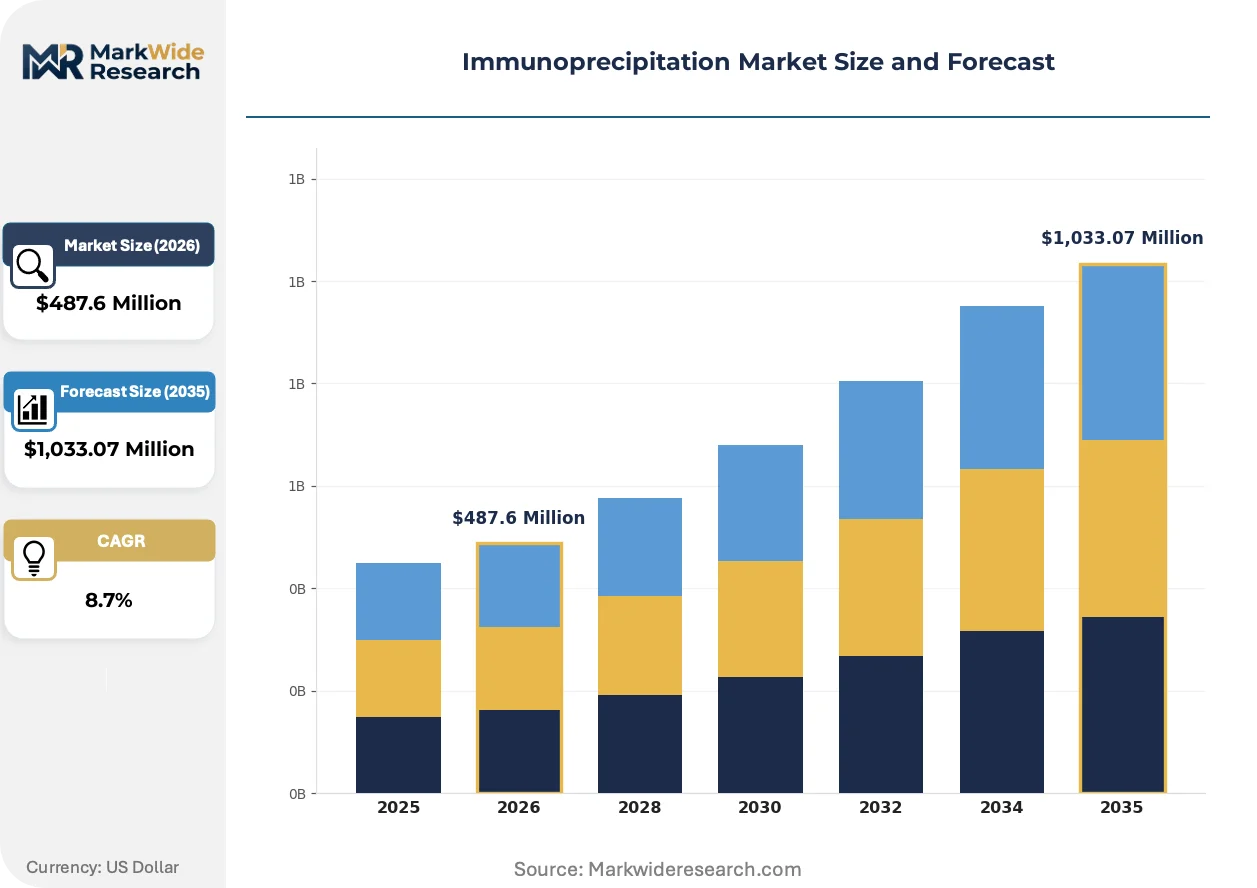
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agarose Beads, Magnetic Beads, Antibodies, Kits Application: Biomarker Discovery, Protein Interaction Studies, Drug Development, Genetic Research Technique: Native IP, Co-IP, Reverse IP, Immunoaffinity Chromatography End User: Academic Research Institutions, Biotechnology Companies, Pharmaceutical Firms, Clinical Laboratories |
| Companies Covered | Abcam plc, Cell Signaling Technology Inc., Merck KGaA, GenScript Biotech Corporation, Abbkine Scientific Co. Ltd., Thermo Fisher Scientific Inc., Takara Bio Inc., Active Motif, Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoprecipitation Market Strategic Shifts
Automation-ready reagent formats and regulatory-grade qualification protocols are restructuring competitive requirements, compressing the viable supplier base to those with certified manufacturing infrastructure.
Superparamagnetic bead surface chemistry with protein A/G recombinant coatings is electrifying capture efficiency benchmarks in high-throughput screening environments. Pharmaceutical hit-to-lead teams in Switzerland and Massachusetts are adopting these platforms for target deconvolution at 384-well density. The technology is electrifying separation speed standards, compressing protocol timelines from hours to minutes and marginalizing agarose for mid-scale applications.
REACH substance restriction proposals for nanomaterial classifications are forcing bead manufacturers to document surface coating biocompatibility profiles. European contract manufacturers must now submit extended safety data sheets for iron oxide core particles used in diagnostic workflows. Magnetic bead suppliers serving EMA-regulated clinical trials are responding by shifting coating chemistries to explicitly exempt polymer formulations.
Consolidated procurement through centralized core facilities is displacing individual lab purchasing autonomy at major research universities. Harvard and Stanford have implemented mandatory kit standardization policies that restrict approved vendor lists to three magnetic bead platforms. This concentration is most visible in United States academic medical centers where shared equipment contracts bundle reagent supply with instrument maintenance agreements.
Immunoprecipitation Market Segmentation
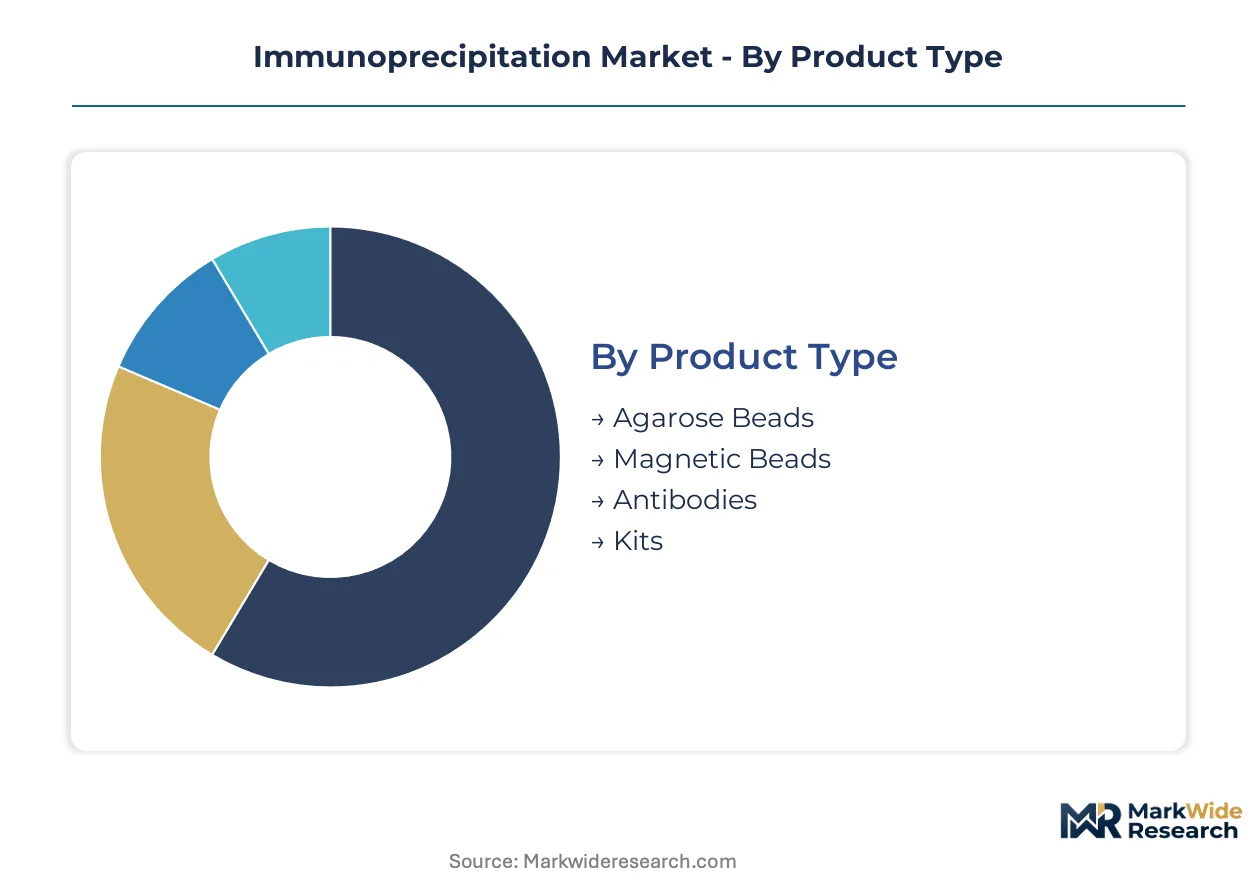
Immunoprecipitation workflows fragment across distinct product architectures, analytical techniques, and institutional end-users. Each segment carries unique supply chain vulnerabilities and regulatory qualification thresholds that reshape vendor positioning.
Product Type:
Supply concentration for bead substrates and antibody inputs varies sharply across material chemistries and expression systems.
- Magnetic Beads:Superparamagnetic iron oxide cores with protein A/G surface coatings enable automation-compatible separation in 384-well pharmaceutical screening formats. Thermo Fisher Scientific's channel dominance in North America sustains premium pricing for high-binding-capacity platforms serving chromatin immunoprecipitation sequencing workflows in Boston and San Francisco biotech clusters.
- Antibodies:Recombinant monoclonal production in mammalian expression systems commands input cost premiums tied to serum price volatility and lot-to-lot consistency requirements. Phospho-specific portfolios from specialty suppliers capture sustained demand in signaling research despite cross-reactivity validation burdens.
- Agarose Beads:Cross-linked polysaccharide matrices retain cost advantages for low-throughput academic settings with manual centrifugation protocols.
- Kits:Pre-configured reagent bundles with validated protocols reduce assay development timelines for contract research organizations facing antibody validation specialist scarcity.
Magnetic beads absorb the bulk of installed capacity in pharmaceutical quality control labs; antibodies are expanding most quickly as recombinant expression technologies mature.
Application:
End-use demand stratifies sharply between exploratory research and regulated clinical translation workflows.
- Protein Interaction Studies:Co-immunoprecipitation workflows dominate academic and pharmaceutical target deconvolution for immuno-oncology programs. Germany's Max Planck Institutes and United States NIH-funded centers sustain concentrated consumable throughput for bait-prey complex characterization.
- Drug Development:FDA biomarker qualification frameworks mandate analytical validity demonstrations for immunoprecipitation-based companion diagnostics. Assay development service contracts expand as developers navigate EMA ICH Q2(R1) validation standard divergence.
- Biomarker Discovery:Exploratory profiling of post-translational modifications in patient cohorts feeds target prioritization pipelines.
- Genetic Research:Chromatin immunoprecipitation sequencing applications in epigenetic mapping concentrate at academic medical centers with shared core facility infrastructure.
Protein interaction studies command the deepest reagent consumption per project; drug development carries the steepest expansion trajectory as regulatory-grade qualification protocols proliferate.
Technique:
Protocol architecture determines reagent format requirements and automation compatibility thresholds.
- Co-IP:Antibody-mediated capture of protein complexes under native or mild denaturing conditions enables interaction mapping with downstream mass spectrometry or western blot readouts. Academic institutions in the United States and Germany are expanding workflows for immuno-oncology target validation, driving multi-well plate consumable demand.
- Native IP:Preservation of physiological protein conformations supports functional assay readouts but constrains buffer formulation flexibility.
- Reverse IP:Antibody immobilization orientation inverts to reduce heavy/light chain interference in downstream detection.
- Immunoaffinity Chromatography:Column-scale antibody immobilization supports preparative purification for biotherapeutic candidate characterization.
Co-IP anchors current protocol volume; reverse IP is gaining share fastest as detection sensitivity requirements tighten.
End User:
Procurement autonomy and vendor qualification standards diverge across institutional categories.
- Academic Research Institutions:Consolidated purchasing through centralized core facilities displaces individual lab autonomy at Harvard, Stanford, and comparable tier-one universities. Mandatory kit standardization policies restrict approved vendor lists to three magnetic bead platforms, bundling reagent supply with instrument maintenance agreements.
- Pharmaceutical Firms:High-throughput screening groups in Switzerland and Massachusetts adopt 384-well magnetic bead automation for hit-to-lead target deconvolution, compressing protocol timelines from hours to minutes.
- Biotechnology Companies:Venture-funded clusters in Boston and San Francisco sustain concentrated procurement of premium binding-capacity platforms.
- Clinical Laboratories:ISO 13485 certification requirements for diagnostic-grade reagents constrain vendor eligibility beyond research-only segments.
Academic institutions represent the broadest addressable base; pharmaceutical firms are climbing the fastest as automation adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where NIH funding patterns and biotech cluster density sustain concentrated procurement of high-binding-capacity magnetic bead platforms for chromatin immunoprecipitation sequencing workflows.
United States
Boston and San Francisco biotech clusters drive sustained kit and reagent procurement volumes for protein interaction studies. FDA biomarker qualification frameworks reshape assay validation requirements for drug development applications. Harvard and Stanford have implemented mandatory kit standardization policies that restrict approved vendor lists to three magnetic bead platforms.
Germany
Max Planck Institutes expand co-immunoprecipitation workflows for immuno-oncology target validation, driving multi-well plate consumable demand. EMA's ICH Q2(R1) analytical validation standards influence reagent performance requirements for clinical translation. Academic research institutions in Baden-Württemberg and Bavaria sustain concentrated throughput for bait-prey complex characterization.
Switzerland
Pharmaceutical hit-to-lead teams adopt 384-well magnetic bead automation for target deconvolution at premium pricing tiers. Swissmedic regulatory frameworks align with EMA standards for diagnostic-grade reagent qualification. Basel and Zurich pharmaceutical quality control labs compress manual workflow timelines through liquid-handling compatibility requirements.
China
Agarose resin production clusters near Shanghai create geographic supply concentration for cross-linked polysaccharide matrices. The country's national pharmaceutical regulator maintains evolving guidance on biomarker qualification that diverges from FDA frameworks. Coastal manufacturing zones face vulnerability to port logistics disruptions that constrain margin flexibility for kit manufacturers.
India
PLI scheme incentives for biologics contract manufacturing attract magnetic bead platform assembly capacity to serve Asia-Pacific demand. CDSCO regulatory pathways for diagnostic-grade reagents remain under development relative to FDA and EMA benchmarks. Bangalore and Hyderabad biotech corridors expand protein interaction research infrastructure with imported reagent dependencies.
Immunoprecipitation Market Competitive Environment
Strategic partnerships dominate the current landscape as reagent suppliers reconfigure kit architectures for liquid-handling compatibility and automation protocols. The vendor base stratifies across three tiers: diversified life science conglomerates with channel control, specialty antibody producers with mammalian expression capabilities, and regional kit assemblers serving cost-sensitive academic segments. Two archetypes anchor competitive positioning: magnetic bead platform specialists with ISO 13485 certification pathways, and recombinant antibody producers with in-house serum-independent expression systems. Capacity expansion in Asia-Pacific assembly operations and portfolio diversification into single-cell immunoprecipitation applications represent the dominant competitive moves.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions that exemplify channel dominance and broad reagent portfolio coverage. Within the specialty antibody tier, Abcam plc and GenScript Biotech Corporation represent archetypes of phospho-specific portfolio differentiation and recombinant mammalian expression capability respectively. These named entities serve as anchors for understanding how competitive positioning stratifies between scale-driven platform distribution and technical specialization in signaling research reagents.
| Leading Market Players |
|---|
| Abcam plc |
| Cell Signaling Technology Inc. |
| Merck KGaA |
| GenScript Biotech Corporation |
| Abbkine Scientific Co. Ltd. |
| Thermo Fisher Scientific Inc. |
| Takara Bio Inc. |
| Active Motif |
| Bio-Rad Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
Antibody validation specialist scarcity in Germany and the United States widens pricing-tier spreads, as labor-cost differentials between coastal China assembly zones and Western mammalian expression facilities force three-tier pricing structures that bundle ISO 13485 certification premiums with unvalidated research-grade alternatives.
Pricing Analysis
Service-bundling separates premium magnetic bead platforms with dedicated field application support from economy agarose kits sold through distributor catalogs without technical consultation. Pricing stratifies across premium, standard, and economy tiers based on automation compatibility and certification grade, with ISO 13485 diagnostic-grade reagents commanding sustained premiums. Cost compression in the economy tier is intensifying because agarose resin production clusters near Shanghai face port logistics volatility. Academic core facilities exhibit highest price sensitivity, while pharmaceutical quality control labs prioritize throughput over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand for 384-well automation-compatible platforms, while distributor networks serve fragmented academic procurement. Manufacturing concentrates in China for agarose substrates, the United States for magnetic bead surface chemistry innovation, and Germany for recombinant antibody production. Raw material dependencies center on iron oxide nanoparticles, protein A/G recombinant coatings, and fetal bovine serum for mammalian expression systems. Single-source vulnerability in Shanghai-area resin production creates geographic risk exposure. Distribution runs through life science conglomerates with North American channel control and regional kit assemblers serving cost-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant antibody production capacity constraints in mammalian expression systems prop pricing power for qualified suppliers, as serum price volatility and lot-to-lot consistency requirements limit rapid capacity expansion.
For Market Incumbents: Hedge against phospho-specific antibody batch variability by captive supply of serum-independent expression systems in Baden-Württemberg or Bavaria. Secure ISO 13485 certification pathways ahead of diagnostic-grade reagent demand inflection. Defend channel control through instrument maintenance agreements that bundle magnetic bead supply with automation platform leases. For New Entrants and Emerging Players: The premium-to-economy price-point gap in magnetic bead platforms offers entry through reverse IP specialty kits targeting academic labs excluded from Harvard-Stanford vendor consolidation. India's PLI scheme for biologics contract manufacturing provides lowest-cost assembly capacity for Asia-Pacific distribution. Lead with single-cell immunoprecipitation applications where incumbent portfolios remain underdeveloped. For Investors and Strategic Acquirers: The window for entry favors recombinant antibody producers with in-house mammalian expression infrastructure over commodity bead assemblers. Long-term viability rests on regulatory-grade qualification capabilities as FDA biomarker frameworks expand assay development service demand. Watch EMA-FDA harmonization progress as the signal for multi-regional trial design acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Diagnostic-grade reagent qualification unlocks clinical biomarker testing workflows beyond research-only segments. |
| Single-Cell IP Application Launch | Premium positioning in rare cell population epigenetic profiling captures oncology researcher procurement budgets. |
| India PLI Manufacturing Scale-Up | Magnetic bead platform assembly capacity serves Asia-Pacific demand with government incentive support. |
| Recombinant Antibody Backward Integration | In-house mammalian expression systems reduce serum price volatility exposure and lot-to-lot variability risk. |
| Academic Core Facility Partnership | Shared equipment contracts at Stanford and Harvard bundle reagent supply with instrument maintenance agreements. |
Study Parameters
Document review covered FDA biomarker qualification guidance, EMA ICH Q2(R1) validation standards, and NIH funding allocation reports, complemented by interviews with drug development executives, regulatory affairs leads at magnetic bead platform suppliers, academic core facility directors, and antibody validation specialists. Secondary sources included SEC filings from life science conglomerates, ISO certification registries, and customs data on agarose resin trade flows. Bottom-up segment sizing triangulated against top-down market estimates from procurement volume analysis at Boston and San Francisco biotech clusters.
Historical capacity utilization rates at mammalian expression facilities were cross-referenced against panel input from recombinant antibody producers to inform supply-constrained pricing assumptions across the analysis window. The forecast framework modeled product type segmentation by material chemistry, application segmentation by regulatory qualification tier, end-user segmentation by procurement autonomy level, and geographic segmentation by biotech cluster density. CAGRs were derived from trajectory fitting to NIH funding patterns and pharmaceutical automation adoption curves, with chromatin immunoprecipitation sequencing throughput serving as a leading indicator for magnetic bead demand.
Inputs from EMA regulatory submissions and FDA guidance documents were available through the study window; gaps in real-time CDSCO pathway development for diagnostic-grade reagents introduce uncertainty bands for Asia-Pacific clinical translation timelines. Forecasts reflect assumptions around biomarker qualification framework stability and serum price volatility ranges. Periodic stress-testing of base assumptions against port logistics disruption scenarios and REACH nanomaterial classification proposals is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Biochips Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Glycomics Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Cosmid DNA Isolation Market