
 Global RNA Analysis Market | 2026-2036
Global RNA Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global RNA Analysis Market Foresight
Modular platform bundling is recalibrating how pharmaceutical companies and academic institutions procure RNA analysis capabilities. Thermo Fisher Scientific leverages its integrated reagent-instrument-software ecosystem to anchor large-scale transcriptome contracts. Illumina specializes in high-throughput sequencing workflows that dominate population-scale RNA studies. QIAGEN controls the sample-to-insight pipeline with automated extraction and analysis modules that reduce hands-on time.
RNA analysis encompasses the quantitative and qualitative characterization of ribonucleic acid molecules through techniques including reverse transcription, amplification, sequencing, and hybridization-based detection, typically operating at picogram sensitivity thresholds and single-nucleotide resolution for transcript identification. Its primary commercial purpose is to decode gene expression patterns, identify disease biomarkers, and validate therapeutic targets across drug development pipelines. NGS Platforms capture the highest-value instrument placements where throughput and read depth determine laboratory competitiveness. RNA-Seq Kits represent the fastest-expanding consumables category as sequencing runs multiply faster than capital equipment refresh cycles. Cloud-Based deployment is displacing on-premise bioinformatics installations as research consortia demand elastic compute for multi-terabyte transcriptome datasets.
FDA oversight of next-generation sequencing-based diagnostic devices and EPA guidelines for laboratory chemical waste management shape product design and facility compliance requirements in the United States. EMA's In Vitro Diagnostic Regulation and ISO 15189 medical laboratory accreditation standards in Europe enforce analytical validation and quality traceability for clinical RNA testing workflows. China's NMPA innovation pathway for breakthrough diagnostic devices accelerates local platform approvals while tightening post-market surveillance. Stakeholders must monitor how fragmented regulatory timelines across jurisdictions affect synchronized product rollouts and service standardization.
Market Dynamics
CRISPR-based transcriptome editing is compressing validation timelines while ISO 13485 mandates force instrument manufacturers to rebuild quality documentation from the ground up. Pharmaceutical sponsors now demand end-to-end RNA biomarker platforms that bundle extraction, sequencing, and cloud analytics into single procurement contracts.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Clinical laboratories across Europe must upgrade analytical validation protocols, creating replacement demand for ISO 15189-compliant RNA testing workflows.
- Pharmaceutical R&D consolidation:Precision oncology programs in the United States, Germany, and China are centralizing RNA biomarker discovery into dedicated transcriptome facilities.
- Single-cell resolution thresholds:Picogram-sensitivity detection methods now enable rare transcript identification that bulk sequencing missed, opening new target validation use cases.
Market Restraints
- Capital equipment refresh cycles:NGS platform replacement timelines extend to seven years in academic settings, slowing instrument revenue recognition.
- Reagent supply concentration:Three vendors control reverse transcription enzyme production, creating input cost volatility when fermentation capacity tightens.
- Technical limitation in FFPE samples:Formalin-fixed tissue yields degraded RNA that fails quality thresholds for clinical sequencing assays.
Strategic Opportunities
- Cloud-based bioinformatics:Elastic compute architectures are displacing on-premise installations as multi-terabyte transcriptome datasets exceed local server capacity.
- China NMPA innovation pathway:Breakthrough diagnostic device designation accelerates local platform approvals while tightening post-market surveillance requirements.
- Liquid biopsy integration:Circulating RNA analysis from blood draws converges with companion diagnostic development, creating service bundling opportunities.
Industry Challenges
- Bioinformatics talent scarcity:Computational biologists capable of multi-omics integration command premium compensation that mid-scale CROs cannot match.
- Cross-platform standardization delays:Lack of harmonized reference materials between Illumina, Thermo Fisher, and Pacific Biosciences workflows complicates multi-site clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RNA Analysis Market |
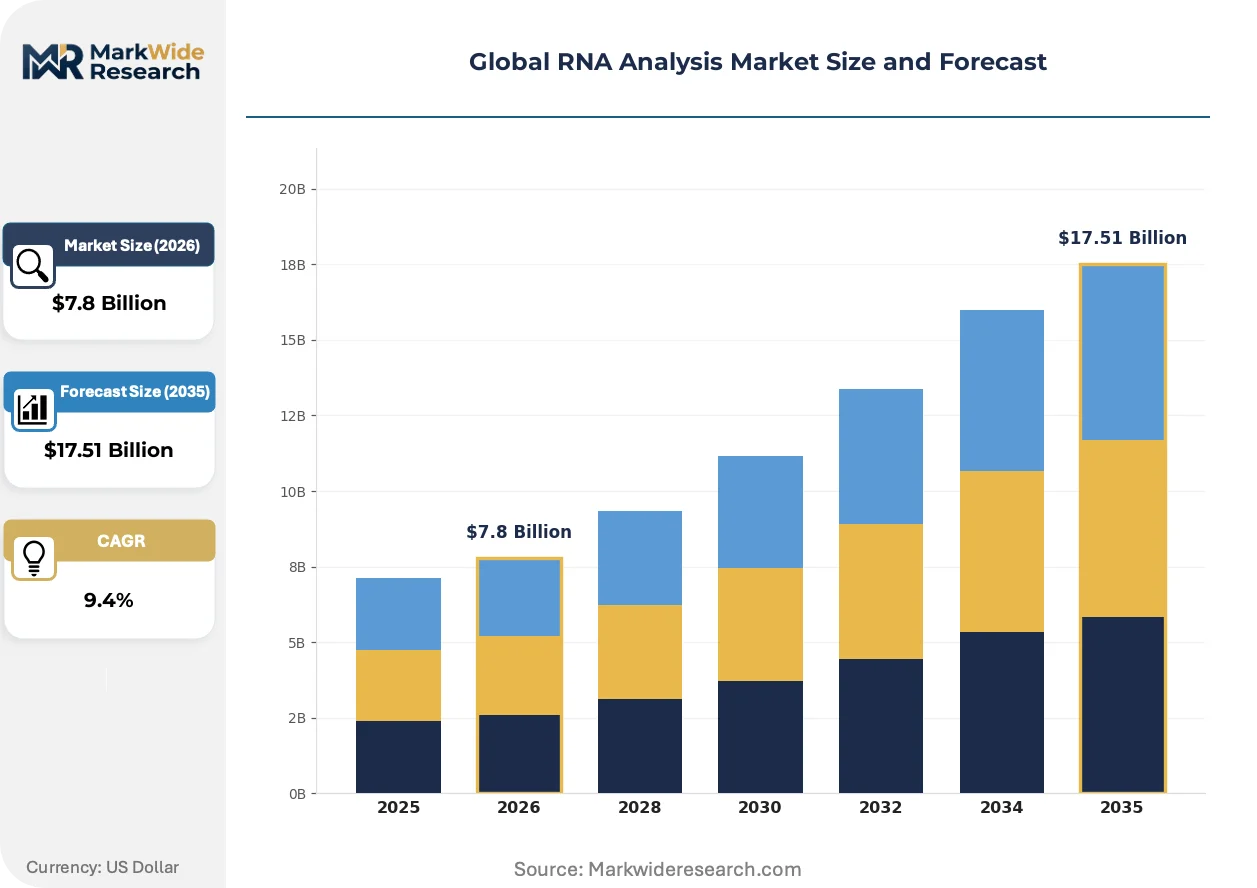
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: qPCR Instruments, Microarrays, NGS Platforms, RNA-Seq Kits, Bioinformatics Software Application: Gene Expression Profiling, Transcriptome Analysis, Biomarker Discovery, Drug Development, Agricultural Biotechnology End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Forensic Laboratories, Biotech Enterprises Deployment Mode: On-Premise, Cloud-Based, Hybrid, Managed Services, SaaS |
| Companies Covered | Agilent Technologies, Bio-Rad Laboratories, Thermo Fisher Scientific, Pacific Biosciences, Eurofins Scientific, Illumina, F. Hoffmann-La Roche, Oxford Nanopore Technologies, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RNA Analysis Market Shifts & Advancements
Artificial intelligence is rewiring how transcriptome data transforms into therapeutic decisions. Machine learning models now predict drug response from RNA signatures faster than traditional biomarker validation pipelines.
Spatial transcriptomics is converging with multiplexed imaging to preserve tissue architecture while quantifying gene expression at single-cell resolution. Pathology departments at cancer centers in Boston and Heidelberg are adopting these platforms for companion diagnostic development. The technology is converging with CRISPR screening to map functional gene networks directly within tumor microenvironments.
FDA oversight of next-generation sequencing-based diagnostic devices tightened analytical validation requirements for tumor mutational burden assays. Device sponsors must now demonstrate reproducibility across multiple operators and reagent lots before premarket submission. Clinical laboratories in the United States are responding by consolidating validation work under single quality management systems rather than site-specific protocols.
Consortium-based procurement is replacing individual laboratory purchases for population-scale RNA studies. Research institutions in the United Kingdom, Netherlands, and Sweden now pool sequencing capacity through shared infrastructure agreements. Academic medical centers negotiate multi-year consumables contracts that lock in reagent pricing in exchange for volume commitments.
Global RNA Analysis Market Segmentation
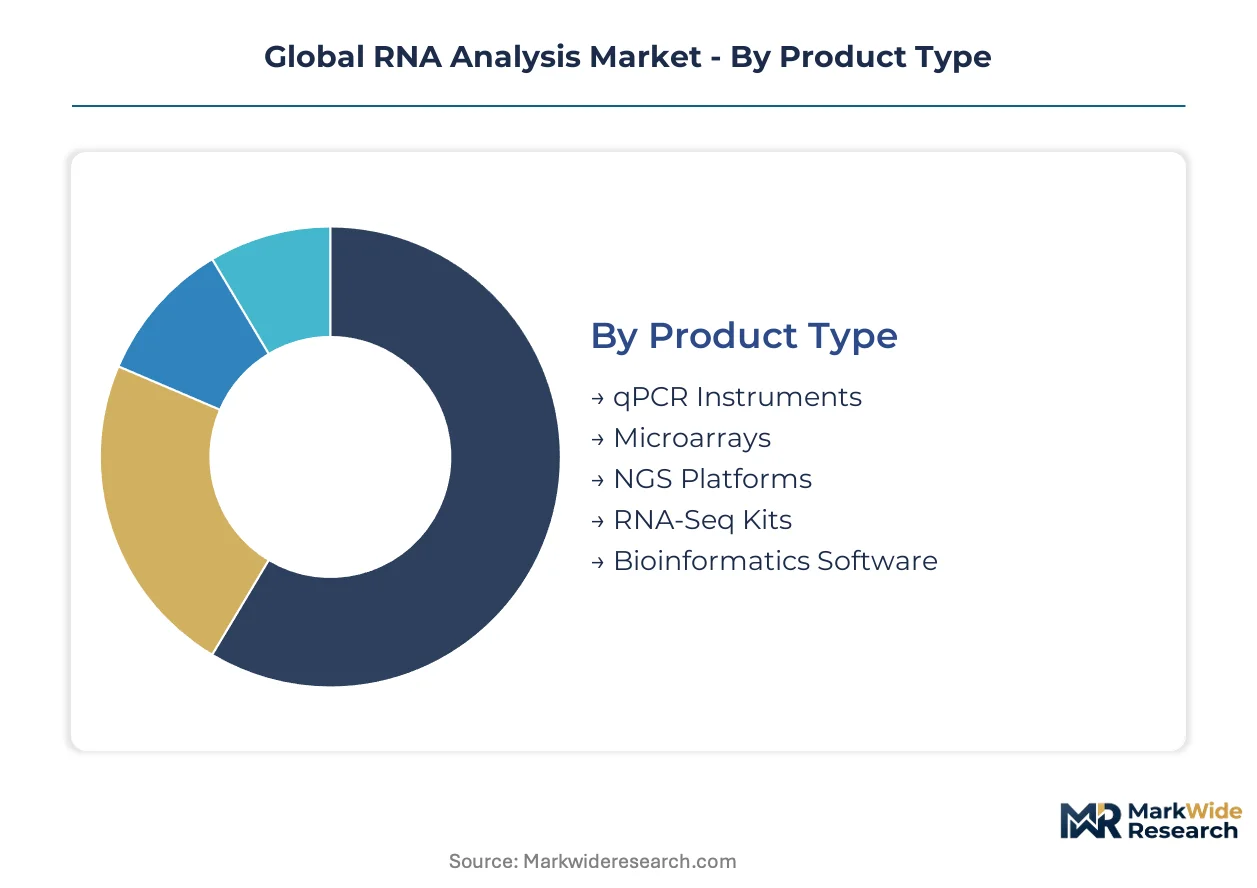
RNA analysis procurement patterns diverge sharply by technical sophistication, throughput requirements, and regulatory exposure. Understanding these segment boundaries clarifies where platform vendors can command premium pricing versus where commoditization pressures dominate.
Product Type:
Capital intensity and reagent dependency separate buyers in this category—high-throughput facilities prioritize instrument ownership while smaller labs favor consumable-heavy workflows.
- NGS Platforms:High-throughput sequencing instruments deliver single-nucleotide resolution across transcriptome-scale datasets. Demand concentrates in United States cancer centers and German precision medicine institutes where read depth determines competitive positioning for biomarker discovery programs.
- RNA-Seq Kits:Library preparation consumables enable transcriptome sequencing without dedicated capital investment. Academic consortia in Sweden and Netherlands favor kit-based procurement to access sequencing capacity through shared infrastructure rather than instrument ownership.
- qPCR Instruments:Quantitative PCR systems provide cost-effective gene expression quantification for validation workflows.
- Microarrays:Hybridization-based expression profiling retains niche applications in agricultural genomics and toxicogenomics screening.
- Bioinformatics Software:Analysis pipelines range from vendor-locked instrument software to open-source alignment tools.
NGS Platforms lead volumes today; RNA-Seq Kits are gaining share fastest.
Application:
Regulatory scrutiny intensity and timeline urgency differentiate applications—clinical-facing programs demand ISO 15189-compliant workflows while exploratory research tolerates higher technical risk.
- Gene Expression Profiling:Quantitative measurement of transcript abundance reveals disease states and drug response patterns. Pharmaceutical sponsors in Germany and China centralize these capabilities into dedicated transcriptome facilities to compress biomarker validation timelines.
- Biomarker Discovery:Systematic RNA signature identification for patient stratification and companion diagnostic development. United States oncology programs drive demand where FDA premarket submission requirements enforce rigorous analytical validation across multiple operators and reagent lots.
- Transcriptome Analysis:Comprehensive RNA cataloging including novel isoform detection and fusion identification.
- Drug Development:Target validation and mechanism-of-action studies leveraging RNA interference and CRISPR screening data.
- Agricultural Biotechnology:Crop trait mapping and stress response characterization in staple grain and oilseed programs.
Gene Expression Profiling anchors current revenue; Biomarker Discovery shows the steepest expansion trajectory.
End User:
Procurement scale and decision velocity distinguish end users—enterprise buyers negotiate multi-year ecosystem contracts while fragmented academic purchasers prioritize instrument flexibility.
- Pharmaceutical Companies:Integrated drug developers demand end-to-end RNA biomarker platforms bundling extraction, sequencing, and cloud analytics into single procurement contracts. United States and China-based sponsors are consolidating vendor relationships to reduce qualification overhead across global development programs.
- Academic Institutions:Research universities and medical schools drive instrument placements through NIH, DFG, and NSFC funding cycles. Seven-year capital refresh timelines in this segment slow revenue recognition but create sustained consumables demand.
- Contract Research Organizations:Service providers require multi-platform compatibility to serve diverse sponsor protocols.
- Biotech Enterprises:Venture-backed developers prioritize speed-to-data over comprehensive workflow ownership.
- Forensic Laboratories:Criminal justice and paternity testing facilities employ RNA degradation analysis for sample quality assessment.
Pharmaceutical Companies dominate procurement value; Academic Institutions generate the highest instrument placement count.
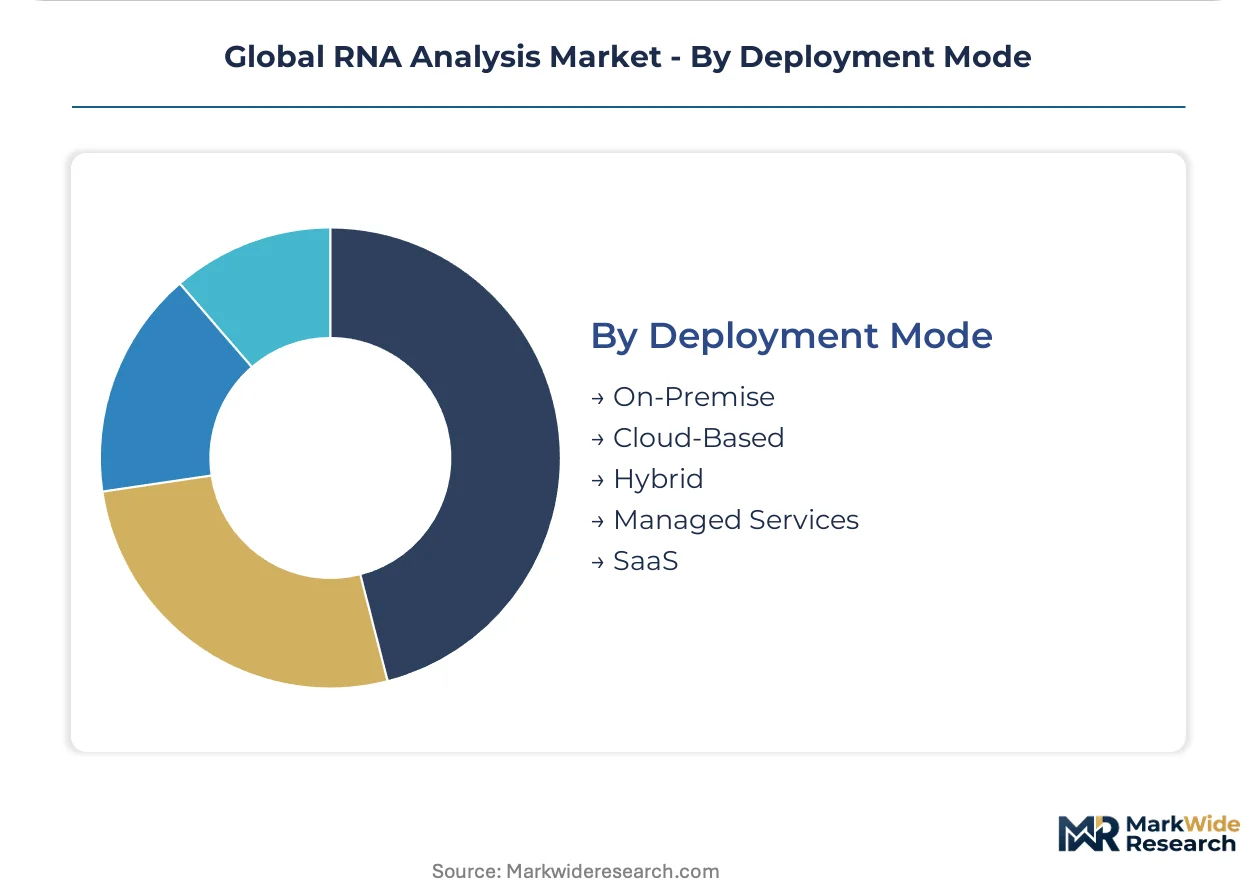
Deployment Mode:
Data sovereignty requirements and computational scale separate deployment preferences—multi-terabyte transcriptome datasets exceed local server capacity while regulated clinical data demands jurisdictional control.
- Cloud-Based:Elastic compute architectures enable processing of population-scale RNA studies without capital infrastructure investment. Research consortia in United Kingdom and Netherlands deploy cloud pipelines to pool analytical capacity across institutional boundaries.
- Hybrid:Split architectures retain sensitive clinical data on-premise while bursting compute-intensive alignment and quantification tasks to cloud infrastructure. German and Swiss medical centers favor this model to satisfy GDPR and local data protection requirements.
- On-Premise:Local server installations persist where network latency or data residency mandates prohibit external compute.
- SaaS:Subscription-based analysis platforms reduce bioinformatics staffing requirements for mid-scale laboratories.
- Managed Services:Outsourced bioinformatics operations transfer operational risk to specialized providers.
On-Premise retains installed base leadership; Cloud-Based deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RNA analysis platforms first achieved commercial scale in the United States during the Human Genome Project era. European precision medicine initiatives and Asian biopharma expansion now redistribute demand across three continents.
United States
FDA oversight of next-generation sequencing-based diagnostic devices tightened analytical validation requirements for tumor mutational burden assays. Clinical laboratories in Boston and San Diego now consolidate validation work under single quality management systems. The National Cancer Institute's precision oncology programs anchor demand for transcriptome-scale biomarker discovery.
Germany
EMA's In Vitro Diagnostic Regulation forces clinical laboratories to upgrade analytical validation protocols, creating replacement demand for ISO 15189-compliant workflows. Heidelberg and Munich cancer centers adopt spatial transcriptomics platforms for companion diagnostic development. The DFG funds instrument placements through multi-year research infrastructure grants.
China
NMPA's innovation pathway for breakthrough diagnostic devices accelerates local platform approvals while tightening post-market surveillance. Beijing and Shanghai biotech clusters centralize RNA biomarker discovery into dedicated transcriptome facilities. Domestic pharmaceutical sponsors consolidate vendor relationships to reduce qualification overhead.
United Kingdom
Research institutions in London, Cambridge, and Oxford pool sequencing capacity through shared infrastructure agreements. Academic medical centers negotiate multi-year consumables contracts that lock in reagent pricing. Cloud-based bioinformatics deployments exceed local server capacity for population-scale RNA studies.
Sweden
Academic consortia in Stockholm and Uppsala favor kit-based procurement to access sequencing capacity through shared infrastructure rather than instrument ownership. The Swedish Research Council funds RNA-Seq kit purchases through national genomics initiatives. Seven-year capital refresh timelines in universities slow instrument revenue recognition.
Global RNA Analysis Market Competitive Landscape
The competitive structure tilts toward integrated ecosystem providers with reagent-instrument-software bundling capabilities. Thermo Fisher Scientific, Illumina, and QIAGEN occupy distinct but overlapping positions across the value chain. Three strategic archetypes dominate: full-stack platform vendors, sequencing specialists, and sample-to-insight workflow providers. M&A activity concentrates on cloud bioinformatics acquisitions and spatial transcriptomics capabilities.
Among full-stack platform vendors, Thermo Fisher Scientific exemplifies the integrated reagent-instrument-software ecosystem model. Illumina anchors the high-throughput sequencing specialist tier with population-scale RNA study dominance. QIAGEN occupies the sample-to-insight workflow position with automated extraction and analysis modules. Pacific Biosciences and Oxford Nanopore Technologies represent long-read sequencing alternatives challenging short-read incumbents.
| Leading Market Players |
|---|
| Agilent Technologies |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Pacific Biosciences |
| Eurofins Scientific |
| Illumina |
| F. Hoffmann-La Roche |
| Oxford Nanopore Technologies |
| QIAGEN |
| Others |
Supply & Pricing Matrix
Pharmaceutical companies consolidating RNA biomarker discovery into dedicated transcriptome facilities command ecosystem-level procurement contracts that reshape how vendors price reagent-instrument-software bundles. This buyer concentration forces suppliers to trade margin for multi-year volume commitments while ISO 13485 certification tiers stratify pricing across quality grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates RNA analysis procurement, with ISO 15189-certified workflows commanding substantial premiums over research-use-only alternatives. Price differentiation rests on analytical validation depth and cloud analytics bundling rather than hardware specifications alone. Cost compression in the economy tier is intensifying because academic consortia pool sequencing capacity through shared infrastructure agreements. Contract research organizations exhibit the highest price sensitivity due to thin margins on sponsor-facing services, while pharmaceutical sponsors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
ISO 13485 quality mandates and FDA premarket submission requirements gate supplier participation, forcing instrument manufacturers to rebuild documentation systems before accessing clinical procurement channels. Manufacturing concentrates in the United States, Germany, and China where precision optics, semiconductor fabrication, and fermentation-based enzyme production anchor the value chain. Reverse transcription enzymes, sequencing flow cells, and cloud compute infrastructure represent critical input dependencies. Single-source vulnerability in reverse transcription enzyme production creates supply risk when fermentation capacity tightens. Distribution runs through direct sales teams for enterprise pharmaceutical accounts and distributor networks for fragmented academic purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RNA analysis market has entered a late-cycle quality phase where ISO 15189-compliant workflows and validated cloud analytics displace unregulated research tools. Pharmaceutical sponsors now demand end-to-end quality documentation that only integrated ecosystem providers can deliver.
For Market Incumbents: Lock in pharmaceutical sponsor relationships through multi-year consumables contracts that embed cloud analytics subscriptions and preempt competitive displacement. Consolidate validation documentation under unified quality management systems to reduce sponsor qualification overhead. Capacity expansion in China leverages NMPA innovation pathway acceleration while hedging against EMA regulatory timeline fragmentation. For New Entrants and Emerging Players: The premium-economy price gap in RNA-Seq kits creates entry opportunity for automated library preparation modules targeting mid-scale academic consortia. Spatial transcriptomics hardware for cancer center pathology departments represents the most penetrable segment given limited incumbent specialization. A kit-first, instrument-later go-to-market angle bypasses seven-year capital refresh barriers in university settings. For Investors and Strategic Acquirers: Cloud bioinformatics specialists are the most active acquirer category in this space, seeking computational biology talent and elastic compute architectures. Long-term viability favors platforms with regulatory pre-approvals across FDA, EMA, and NMPA jurisdictions. Watch for CRISPR-based transcriptome editing validation timelines compressing as the inflection signal for platform obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Workflow Certification | EMA In Vitro Diagnostic Regulation forces clinical laboratory upgrades across European precision medicine institutes. |
| Cloud Analytics Platform Integration | Elastic compute architectures displace on-premise installations for multi-terabyte transcriptome datasets in UK research consortia. |
| Spatial Transcriptomics Capability Acquisition | Heidelberg and Boston cancer centers adopt multiplexed imaging platforms for companion diagnostic development. |
| China NMPA Innovation Pathway Registration | Breakthrough diagnostic device designation accelerates Beijing and Shanghai biotech cluster platform approvals. |
| Automated Sample-to-Insight Pipeline | QIAGEN-style extraction-analysis modules reduce hands-on time for pharmaceutical transcriptome facilities in Germany. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at instrument manufacturers, hospital procurement managers, and cloud bioinformatics specialists with secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, ClinicalTrials.gov RNA biomarker trial registrations, and NMPA breakthrough device designation announcements. Bottom-up instrument placement and consumables consumption models triangulated against top-down pharmaceutical R&D spending allocation estimates.
Comparable historical periods anchored the projection horizon across product type, application, end user, and deployment mode segmentation dimensions with regional regulatory cluster overlays. CAGRs derived from instrument refresh cycle analysis, reagent consumption per sequencing run, and cloud compute pricing elasticity curves. Forecast inputs incorporated CRISPR transcriptome editing adoption velocity and ISO 13485 certification penetration rates.
Caveats apply where FDA premarket submission requirement changes, EMA regulatory timeline fragmentation, or NMPA post-market surveillance tightening could materially shift the outlook. Forecasts reflect documented assumptions about pharmaceutical sponsor consolidation trajectories and academic funding cycle stability. A model refresh is warranted upon material change in cloud bioinformatics talent availability or multi-platform standardization breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Global Glycomics/Glycobiology Market