
 Global Biomarker Technologies Market | 2026-2036
Global Biomarker Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomarker Technologies Market Foresight
Project finance for multi-omics infrastructure is fragmenting competitive access across the biomarker technologies landscape. Thermo Fisher Scientific leverages its captive instrument-installation base to sustain recurring consumable revenue. Illumina anchors high-throughput sequencing demand through controlled flow-cell supply chains. QIAGEN competes in sample-preparation automation with modular platform architectures.
Biomarker technologies encompass analytical platforms that detect and quantify molecular indicators—proteins, nucleic acids, metabolites, or cellular signatures—within biological specimens, typically requiring sensitivity thresholds in the picogram-per-milliliter range and multiplexing capabilities exceeding 500 analytes simultaneously. These technologies serve primarily to stratify patient populations, monitor therapeutic response, and validate drug targets across clinical and research environments. Next-generation sequencing commands the largest share of technology revenue due to expanding oncology panel adoption, while mass spectrometry gains traction in metabolomics applications where untargeted discovery workflows demand high-resolution detection. Protein biomarkers retain the deepest clinical validation among product types, though genetic biomarkers are displacing legacy assays in immuno-oncology companion diagnostics.
FDA's guidance on companion diagnostics and EMA's In Vitro Diagnostic Regulation create dual compliance burdens for platform developers seeking transatlantic market access. China's NMPA has accelerated review pathways for innovative diagnostic reagents, reshaping prioritization in regional R&D portfolios. Stakeholders must monitor evolving harmonization between WHO prequalification standards and national registration requirements to anticipate certification-driven purchasing decisions.
Market Dynamics
Companion diagnostic convergence with immuno-oncology pipelines is compressing development timelines and forcing platform standardization across pharmaceutical and diagnostic vendor ecosystems. This structural pressure is redrawing competitive boundaries between instrument manufacturers and assay developers.
Growth Catalysts
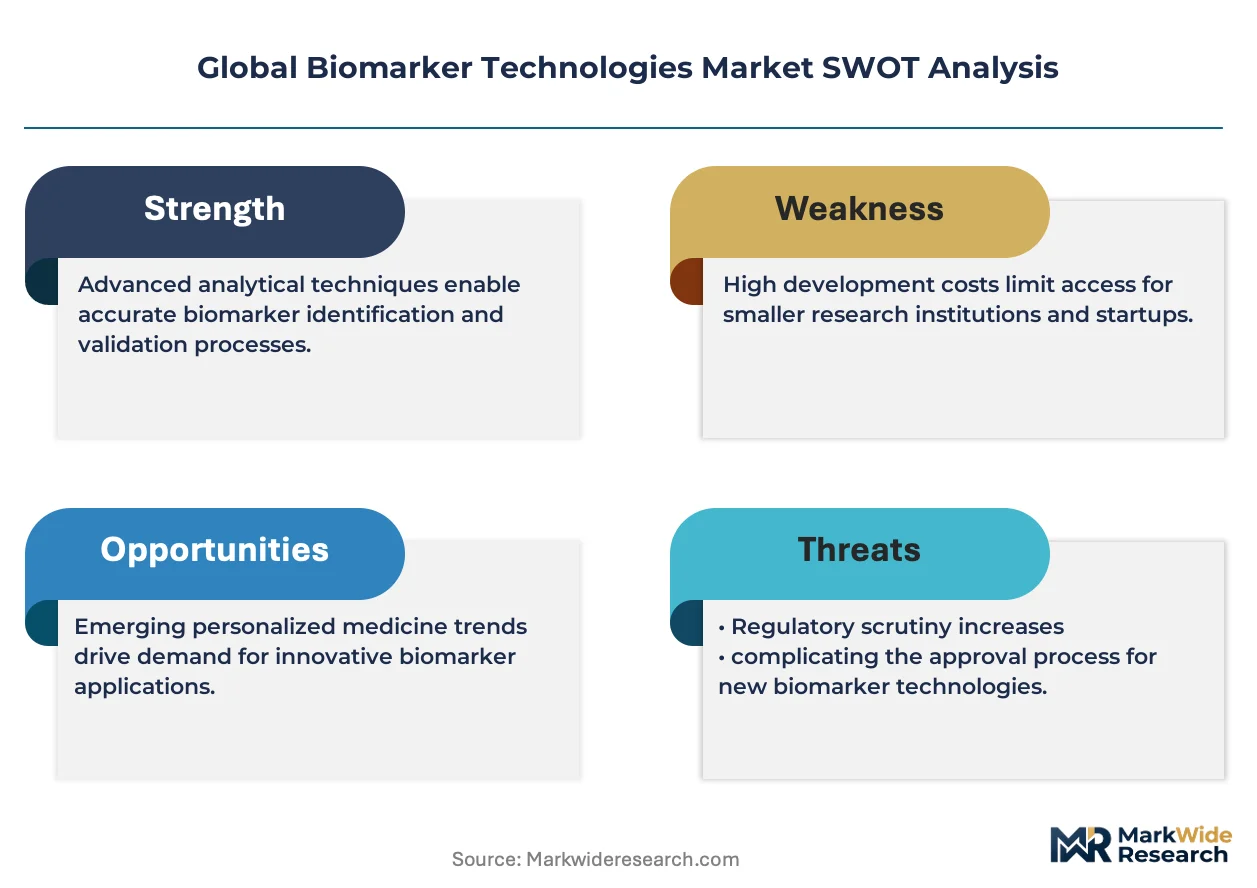
- EMA In Vitro Diagnostic Regulation:The MDR framework mandates clinical evidence thresholds that favor established multi-omics platforms with robust validation datasets, accelerating consolidation among compliant vendors.
- Pharmaceutical biomarker-driven pipelines:Oncology and autoimmune therapeutic development now requires parallel diagnostic stratification, embedding technology procurement into drug development budgets.
- China NMPA accelerated review pathways:Innovative diagnostic reagent approvals now cycle faster than OECD averages, redirecting R&D investment toward NMPA-preferred analyte classes.
Market Restraints
- Flow-cell supply concentration:High-throughput sequencing consumables depend on single-source manufacturing nodes in East Asia, exposing procurement to geopolitical disruption.
- FDA-EMA dual compliance burden:Transatlantic market access requires parallel validation studies with divergent evidentiary standards, inflating regulatory capital requirements.
- Mass spectrometry skill scarcity:Untargeted metabolomics workflows require specialized operator training that outpaces university pipeline output, constraining service lab expansion.
Strategic Opportunities
- India CDSCO emerging pathways:The country's pharmaceutical regulator is streamlining import licenses for reference-standard reagents, opening biobanking infrastructure partnerships.
- Multi-omics data integration:Convergence of proteomic and genomic readouts enables synthetic biomarker signatures with superior predictive validity than single-analyte assays.
- Direct-to-hospital distribution:Bypassing traditional distributor networks reduces assay margin leakage and captures real-time utilization data for consumable replenishment algorithms.
Industry Challenges
- LIMS integration complexity:Legacy hospital information systems require custom API development to ingest multi-omics data streams, delaying platform deployment.
- ISO 15189 accreditation timelines:Clinical laboratory certification for novel biomarker assays extends eighteen to twenty-four months, compressing commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomarker Technologies Market |
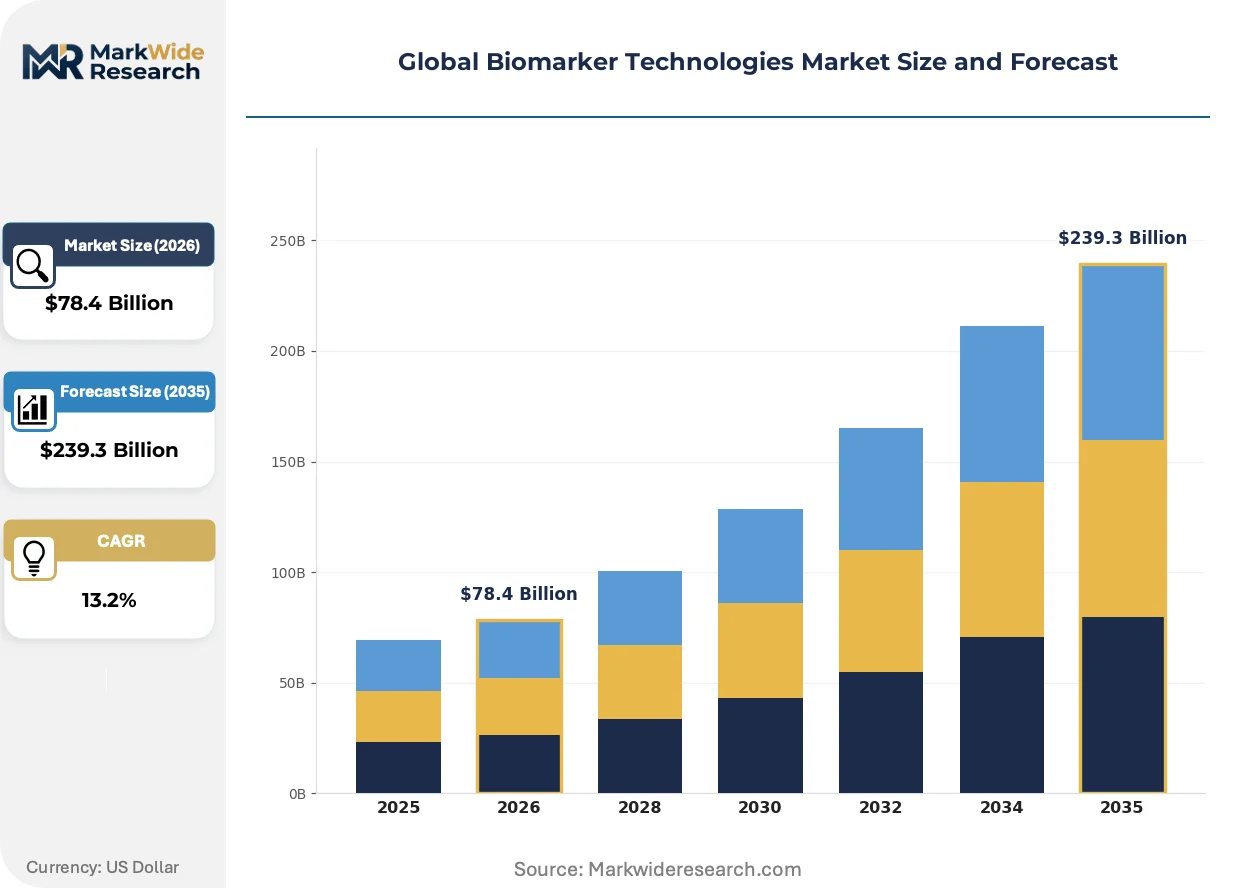
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $239.3 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mass Spectrometry, Microarray, ELISA, PCR, Next-Generation Sequencing, Flow Cytometry Application: Drug Discovery, Diagnostic Testing, Disease Monitoring, Personalized Medicine, Nutrigenomics, Toxicology Screening End User: Pharmaceutical Companies, Diagnostic Laboratories, Academic Institutions, Biotechnology Firms, Research Organizations, Government Agencies Product Type: Protein Biomarkers, Genetic Biomarkers, Metabolic Biomarkers, Lipid Biomarkers, Epigenetic Biomarkers, Cellular Biomarkers |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Abbott, QIAGEN, Illumina, Merck KGaA, Agilent Technologies, Bio-Rad Laboratories, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomarker Technologies Market Shifts & Advancements
Digital pathology integration with spatial transcriptomics is dissolving the boundary between tissue morphology and molecular profiling, enabling single-slide multi-modal analysis that redefines clinical workflow economics.
Single-cell sequencing platforms are rendering obsolete bulk-tumor analysis for immuno-oncology patient stratification. Academic medical centers in Germany and the United States are converting pathology departments to spatial multi-omics units within three-year capital cycles. This transition compresses the addressable market for traditional immunohistochemistry reagents while expanding recurring consumable spend on barcoded library preparation kits.
REACH chemical substance restrictions are forcing reagent reformulation across European proteomics workflows. Manufacturers must substitute legacy organic solvents with aqueous alternatives that maintain picogram-per-milliliter sensitivity thresholds. Protein biomarker assay developers in Switzerland and the Netherlands are absorbing twelve-to-eighteen-month validation delays to maintain CE marking compliance.
Consolidated procurement by integrated delivery networks is displacing decentralized laboratory purchasing autonomy. United States health systems exceeding ten billion dollars in annual revenue now mandate enterprise-wide instrument standardization, locking out specialty platform vendors. This concentration is most visible in Texas and Florida hospital networks, where single-source sequencing contracts span five-year terms with exclusive consumable clauses.
Global Biomarker Technologies Market Segmentation
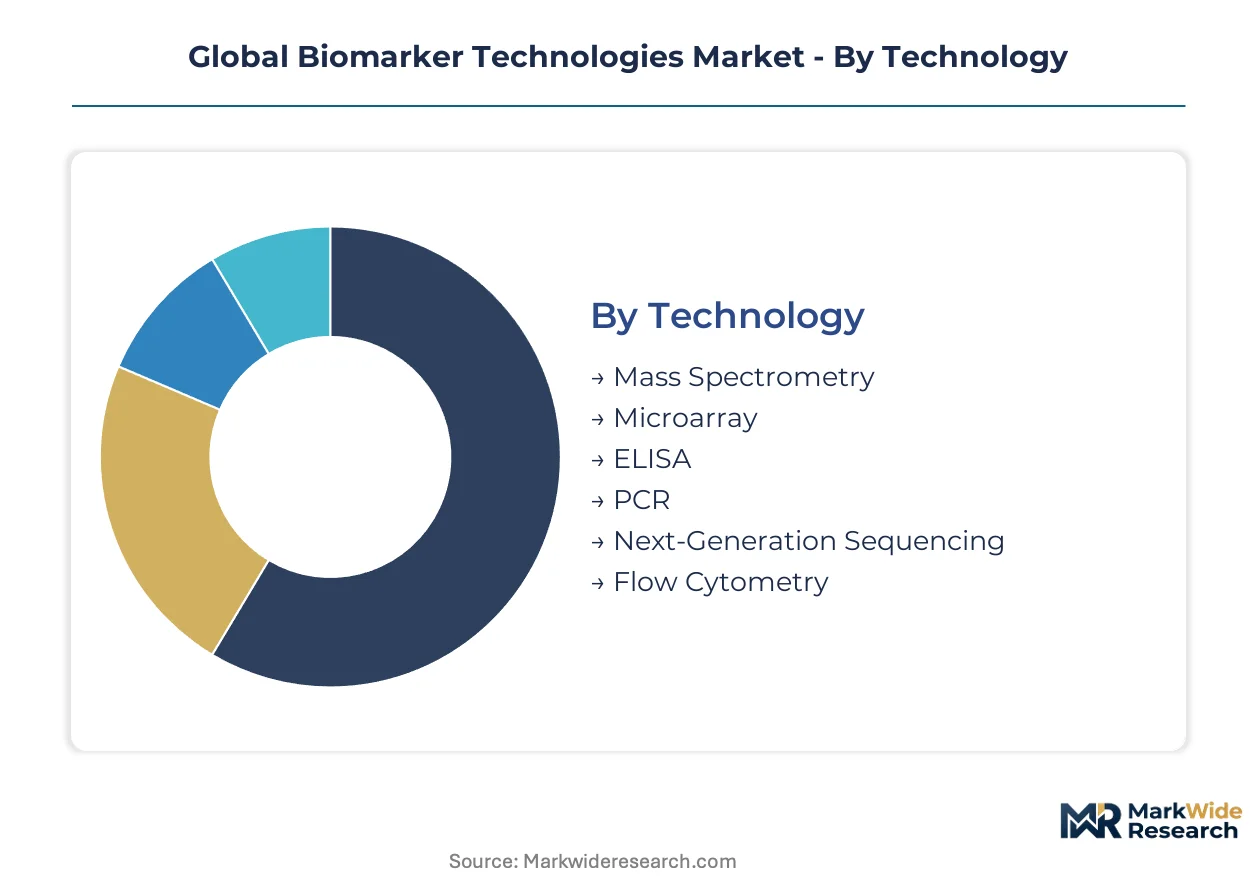
Segmentation in biomarker technologies reveals how capital allocation, regulatory pathways, and clinical validation depth diverge across analytical modalities and user environments. Technology choices determine consumable economics, while end-user concentration shapes distribution channel design.
Technology:
Cost tier stratification separates capital-intensive platforms from benchtop systems, with recurring consumable revenue scaling inversely to instrument portability.
- Next-Generation Sequencing:High-throughput platforms process millions of reads simultaneously through clonal amplification and reversible terminator chemistry. Demand concentrates in United States academic medical centers building precision oncology programs, constrained by flow-cell supply bottlenecks from East Asian manufacturing nodes.
- Mass Spectrometry:Electrospray and MALDI ionization methods achieve picogram-per-milliliter sensitivity for untargeted metabolomics discovery. German pharmaceutical contract research organizations are expanding service capacity, though operator skill scarcity limits throughput scaling.
- PCR:Thermal cycling amplification remains the workhorse for targeted genetic variant detection in resource-limited settings.
- Flow Cytometry:Laser-based cell sorting enables multiparameter immune profiling with fluorescent antibody panels.
- Microarray:Solid-phase hybridization platforms retain cost advantages for fixed-content genetic screening panels.
- ELISA:Colorimetric immunoassays dominate protein quantification in clinical laboratories with moderate throughput requirements.
Next-Generation Sequencing holds installed capacity. Mass Spectrometry is rotating up the share rankings.
Application:
Application scope determines reimbursement coding complexity and the evidentiary threshold for regulatory clearance.
- Drug Discovery:Target validation and pharmacodynamic modeling require multiplexed biomarker panels across preclinical species. China-based contract research organizations are capturing toxico-genomics screening contracts, leveraging NMPA-aligned study designs for domestic pharmaceutical sponsors.
- Diagnostic Testing:Companion diagnostic co-development with therapeutic pipelines demands analytical validation against clinical trial cohorts. United States reference laboratories are consolidating oncology panel menus to capture Medicare coverage determinations.
- Personalized Medicine:Patient stratification algorithms integrate genomic and proteomic signatures for therapy selection.
- Disease Monitoring:Serial biomarker measurement tracks therapeutic response and minimal residual disease.
- Nutrigenomics:Metabolic phenotype analysis links dietary intervention to molecular outcomes in wellness programs.
- Toxicology Screening:Preclinical safety assessment requires high-content cellular biomarker readouts.
Drug Discovery commands the deepest R&D integration. Diagnostic Testing is climbing the fastest as companion diagnostic mandates expand.
End User:
Customer type dictates procurement autonomy, with consolidated health systems imposing enterprise standardization that displaces decentralized purchasing.
- Pharmaceutical Companies:Internal biomarker capabilities support target identification, patient stratification, and regulatory submission packages. Roche and Novartis are building captive sequencing infrastructure in Switzerland and Germany to protect intellectual property around synthetic lethality targets.
- Diagnostic Laboratories:High-throughput service operations demand automated sample preparation and LIMS integration for reimbursement compliance. Quest Diagnostics and LabCorp in the United States are consolidating vendor relationships through five-year exclusive consumable contracts.
- Academic Institutions:Research funding cycles drive instrument refresh rates and core facility shared-access models.
- Biotechnology Firms:Venture-backed developers outsource analytical validation to contract research partners.
- Research Organizations:Non-profit institutes prioritize open-access data generation for consortium participation.
- Government Agencies:Public health surveillance programs require standardized assay formats for inter-laboratory comparability.
Pharmaceutical Companies anchor platform R&D partnerships. Diagnostic Laboratories are gaining share fastest through vertical integration into assay development.
Product Type:
Maturity gradients separate clinically validated protein assays from emerging epigenetic signatures awaiting regulatory qualification.
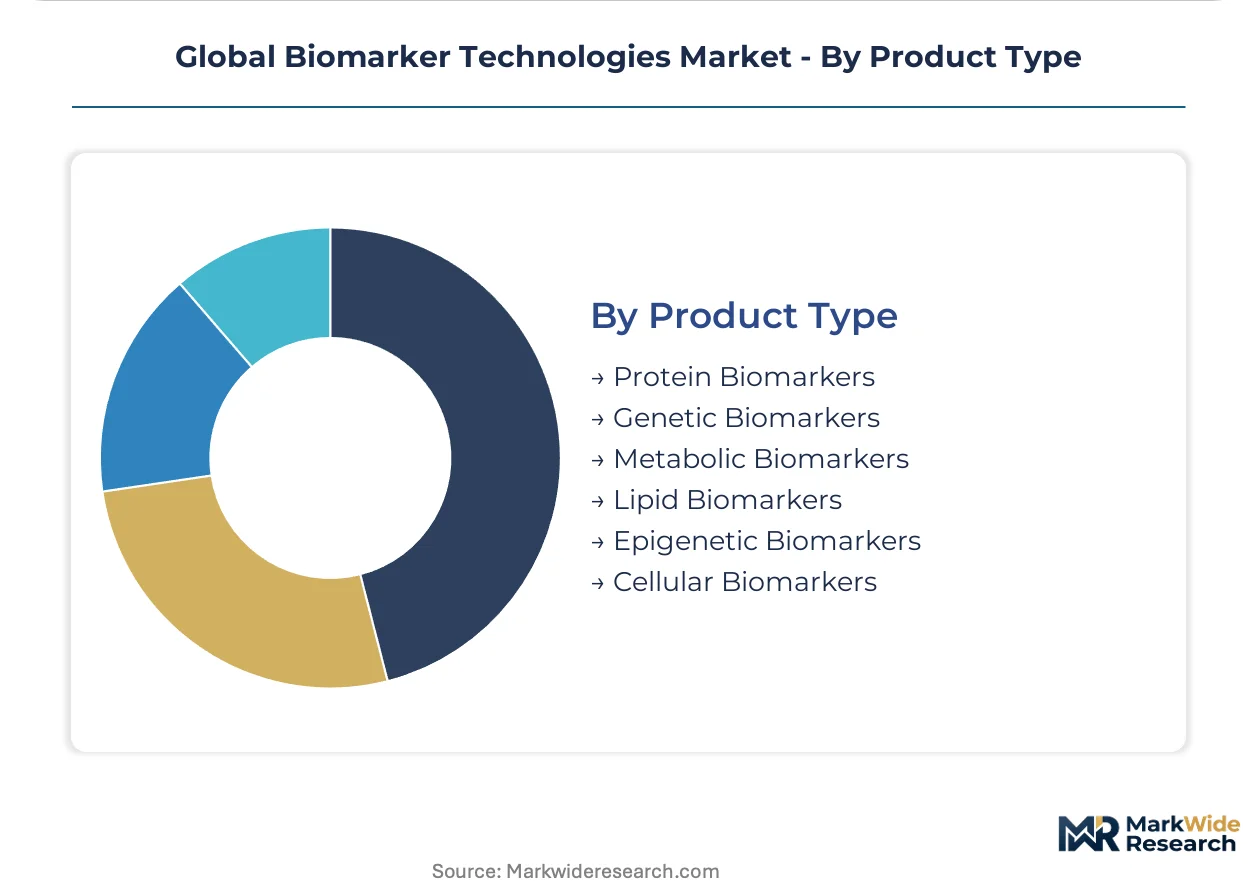
- Protein Biomarkers:Immunoassay-based quantification of circulating cytokines, growth factors, and tissue-derived antigens commands the deepest FDA 510(k) and EMA CE marking portfolios. Diagnostic manufacturers in the Netherlands and Switzerland are absorbing REACH-driven reagent reformulation costs to maintain European market access.
- Genetic Biomarkers:Somatic mutation panels and germline risk scores displace legacy protein assays in immuno-oncology companion diagnostics. Chinese domestic developers are prioritizing NMPA registration for EGFR and ALK variant detection to serve lung cancer screening expansion.
- Metabolic Biomarkers:LC-MS/MS quantification of small-molecule intermediates enables untargeted phenotyping.
- Cellular Biomarkers:Circulating tumor cell enumeration and immune subset profiling require specialized handling protocols.
- Epigenetic Biomarkers:DNA methylation and histone modification assays remain concentrated in research applications.
- Lipid Biomarkers:Lipoprotein subclass analysis supports cardiovascular risk stratification in specialized reference laboratories.
Protein Biomarkers hold installed capacity. Genetic Biomarkers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's In Vitro Diagnostic Regulation and China's NMPA accelerated review pathways are redrawing regional R&D investment maps. Pharmaceutical sponsors now sequence regulatory submission strategies around these divergent approval timelines.
United States
FDA companion diagnostic guidance embeds technology procurement into oncology drug development budgets. Medicare coverage determinations for multi-gene panels concentrate purchasing power within Quest Diagnostics and LabCorp reference networks. The Greater Boston corridor hosts captive sequencing infrastructure at Novartis and Roche facilities protecting synthetic lethality intellectual property.
Germany
EMA MDR clinical evidence thresholds favor multi-omics platforms with robust validation datasets. REACH chemical restrictions force twelve-to-eighteen-month reagent reformulation delays for proteomics assay developers. The Munich-Stuttgart axis anchors pharmaceutical contract research organization expansion in untargeted metabolomics service capacity.
China
NMPA streamlined pathways for innovative diagnostic reagents now cycle faster than OECD regulatory averages. Domestic pharmaceutical sponsors redirect toxico-genomics screening contracts toward China-based contract research organizations. Shanghai and Suzhou bioclusters concentrate lung cancer companion diagnostic development for EGFR and ALK variant detection.
Switzerland
Swissmedic alignment with EMA centralized procedures reduces parallel validation burdens for transatlantic market access. Roche and Novartis maintain captive biomarker infrastructure in Basel and Geneva to protect target stratification algorithms. The country's reagent manufacturers absorb REACH-driven solvent substitution costs to maintain CE marking compliance.
India
CDSCO emerging import license pathways for reference-standard reagents enable biobanking infrastructure partnerships. Pharmaceutical sponsors leverage domestic contract research capacity for preclinical biomarker validation studies. Hyderabad and Bengaluru clusters attract multi-omics platform distributors seeking hospital network penetration beyond traditional distributor channels.
Global Biomarker Technologies Market Competitive Landscape
Channel-controlling players compete with product-specialist players for access to consolidated health system procurement. The vendor base stratifies around instrument-installation scale, consumable lock-in clauses, and LIMS integration depth. Three archetypes dominate: diversified life science conglomerates with captive distribution, precision-focused assay developers with modular automation, and sequencing-platform specialists with controlled consumable supply chains. Competitive moves concentrate on exclusive multi-year consumable contracts and backward integration into sample-preparation chemistry.
Within the diversified conglomerate tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific anchor positions through instrument-installation bases that sustain recurring revenue. Illumina occupies a scale-driven position in high-throughput sequencing demand. These three exemplify how platform control converts to consumable capture across pharmaceutical and diagnostic laboratory customer segments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Abbott |
| QIAGEN |
| Illumina |
| Merck KGaA |
| Agilent Technologies |
| Bio-Rad Laboratories |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across biomarker reagent supply chains, with container rate volatility feeding directly into both East Asian manufacturing concentration and tiered price differentiation for European diagnostic laboratories.
Pricing Analysis
Certification level creates the primary spread across consumable tiers, with FDA 510(k)-cleared assays commanding premiums over CE-marked equivalents in United States hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15189 accreditation status and after-sales service bundling. Cost compression in standard-tier PCR reagents is intensifying because Chinese domestic manufacturers are capturing NMPA-preferred procurement contracts. Academic medical centers exhibit the highest price sensitivity due to grant-funded refresh cycles, while pharmaceutical captive laboratories show the least.
Supply Chain Analysis
Upstream oligonucleotide synthesis and flow-cell manufacturing concentrate in China, South Korea, and the United States, with specialized polymer substrates drawing from German and Swiss chemical suppliers. Reagent formulation depends on high-purity solvents, barcoded library preparation kits, and sequencing-grade enzymes. Single-source vulnerability in East Asian flow-cell fabrication exposes procurement to geopolitical disruption. Distribution runs through direct-to-hospital contracts and exclusive reference laboratory agreements, displacing traditional distributor networks in United States and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement mandates in United States health systems exceeding ten billion dollars in annual revenue, fragmenting vendor access for specialty platform developers.
For Market Incumbents: Build consumable lock-in moats through five-year exclusive sequencing contracts with captive replenishment algorithms. Deepen backward integration into sample-preparation chemistry to capture margin from modular automation competitors. Defend against QIAGEN's platform-agnostic architectures by embedding LIMS integration depth that delays hospital switching costs.
For New Entrants and Emerging Players: Pursue spatial transcriptomics white-space in German academic medical centers converting pathology departments to multi-omics units. Target India's CDSCO-streamlined import pathways for reference-standard reagents, where biobanking infrastructure partnerships bypass entrenched distributor channels. Lead with direct-to-hospital distribution models that capture real-time utilization data for consumable forecasting.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates divesting non-core assay development units under EMA MDR compliance pressure. Long-term viability centers on platforms with validated multi-omics datasets spanning companion diagnostic co-development pipelines. Watch for NMPA approval velocity divergence as signal of regional R&D portfolio reallocation toward Chinese domestic sponsors.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Embeds assay procurement into Novartis and Roche oncology drug development budgets. |
| Flow-Cell Supply Diversification | Reduces Illumina's East Asian single-source exposure through secondary manufacturing qualification. |
| LIMS Integration Partnership | Accelerates deployment timelines by resolving legacy hospital information system API complexity. |
| REACH-Compliant Reagent Reformulation | Maintains CE marking access for Swiss and Dutch protein assay developers absorbing validation delays. |
| Single-Cell Platform Conversion | Captures recurring consumable spend as German and United States pathology departments upgrade capital cycles. |
Research Methodology
Initial hypotheses were tested against primary input from diagnostic laboratory directors, pharmaceutical biomarker leads, regulatory affairs specialists, and hospital procurement managers and refined through secondary validation against FDA 510(k) filings, EMA CE marking databases, NMPA approval registries, and ClinicalTrials.gov companion diagnostic listings. Bottom-up instrument installation counts and consumable throughput estimates were triangulated against top-down pharmaceutical R&D spend allocation and health system capital expenditure disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across technology modality, application purpose, end-user concentration, and product validation maturity. CAGRs were derived from instrument replacement cycles, consumable pull-through rates, and regulatory approval velocity differentials between FDA, EMA, and NMPA pathways. Forecast inputs incorporated biobanking infrastructure buildout timelines and companion diagnostic mandate expansion in immuno-oncology pipelines.
Sensitivities concentrate around flow-cell supply disruption, REACH chemical restriction expansion, and NMPA regulatory pathway acceleration. Forecasts reflect assumptions regarding continued EMA-FDA convergence on companion diagnostic evidence standards. Material shifts in United States integrated delivery network procurement consolidation or Chinese domestic pharmaceutical sponsor R&D reallocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Exosomes Market