
 Vaccine Production Market | 2026-2036
Vaccine Production Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Production Market Outlook
Consolidation among government procurement agencies is realigning contract structures toward multi-year supply agreements with volume guarantees. Pfizer Inc. leverages its mRNA manufacturing infrastructure to sustain pandemic-era production capacity. Sanofi anchors European supply security through diversified antigen production platforms. Serum Institute of India Pvt Ltd dominates high-volume, low-cost supply for Gavi and UNICEF tender programs.
Vaccine production encompasses the end-to-end biomanufacturing of immunological preparations, spanning cell culture propagation at 37°C, antigen purification via chromatography, and aseptic fill-finish at ISO 5 cleanroom classification, yielding prophylactic agents that prime adaptive immunity against infectious pathogens. mRNA vaccines command premium manufacturing margins due to lipid nanoparticle formulation complexity and cold-chain requirements. Live attenuated vaccines occupy mature, high-volume segments where process optimization has stabilized unit costs. Recombinant technology leads R&D pipelines for emerging pathogens.
The FDA enforces Current Good Manufacturing Practice standards through facility inspections and batch release protocols, while the EMA's centralized marketing authorization shapes cross-border commercial access for European manufacturers. WHO prequalification programs determine eligibility for United Nations procurement, directly governing market participation across low-income countries. Stakeholders must monitor regulatory divergence between accelerated emergency pathways and full licensure requirements as pandemic frameworks transition to endemic disease management.
Market Dynamics
mRNA platform standardization is compressing batch-to-batch variability while lipid nanoparticle formulation patents concentrate know-how among established manufacturers, creating asymmetric capability distribution across contract development organizations.
Growth Catalysts
- Pediatric program expansion:Gavi's 2026-2030 strategic period raises procurement volumes for pentavalent and rotavirus formulations across 73 eligible countries.
- WHO prequalification acceleration:The Emergency Use Listing pathway compresses timeline-to-tender for pandemic vaccines, opening UN procurement access.
- Cell culture substitution:Single-use bioreactor adoption displaces egg-based production for influenza, reducing facility footprint and cross-contamination risk.
Market Restraints
- DSPC lipid dependency:Four suppliers control 80% of pharmaceutical-grade phospholipid supply, creating input concentration risk.
- Cold-chain infrastructure gap:Ultra-low temperature storage requirements exclude last-mile distribution in sub-Saharan African markets lacking -70°C capacity.
- EMA batch release backlog:Centralized testing protocols for novel adjuvants extend time-to-market for European commercial launches.
Strategic Opportunities
- Indonesia manufacturing localization:The national immunization program's volume growth creates demand for in-country fill-finish capacity to replace import dependency.
- Combination vaccine R&D:Hexavalent formulations merging DTaP-IPV-Hib-HepB reduce injection burden and capture premium positioning in private markets.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients subsidizes backward integration into antigen raw material production.
Industry Challenges
- Bioprocess engineer scarcity:Cell culture optimization and scale-up troubleshooting require specialized expertise concentrated at three academic centers.
- ISO 14644-1 cleanroom validation:Continuous monitoring system upgrades for Grade A environments demand 18-24 month capital deployment cycles.
- Legacy equipment integration:Paper-based batch records in established facilities conflict with FDA guidance on electronic systems for manufacturing data integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Production Market |
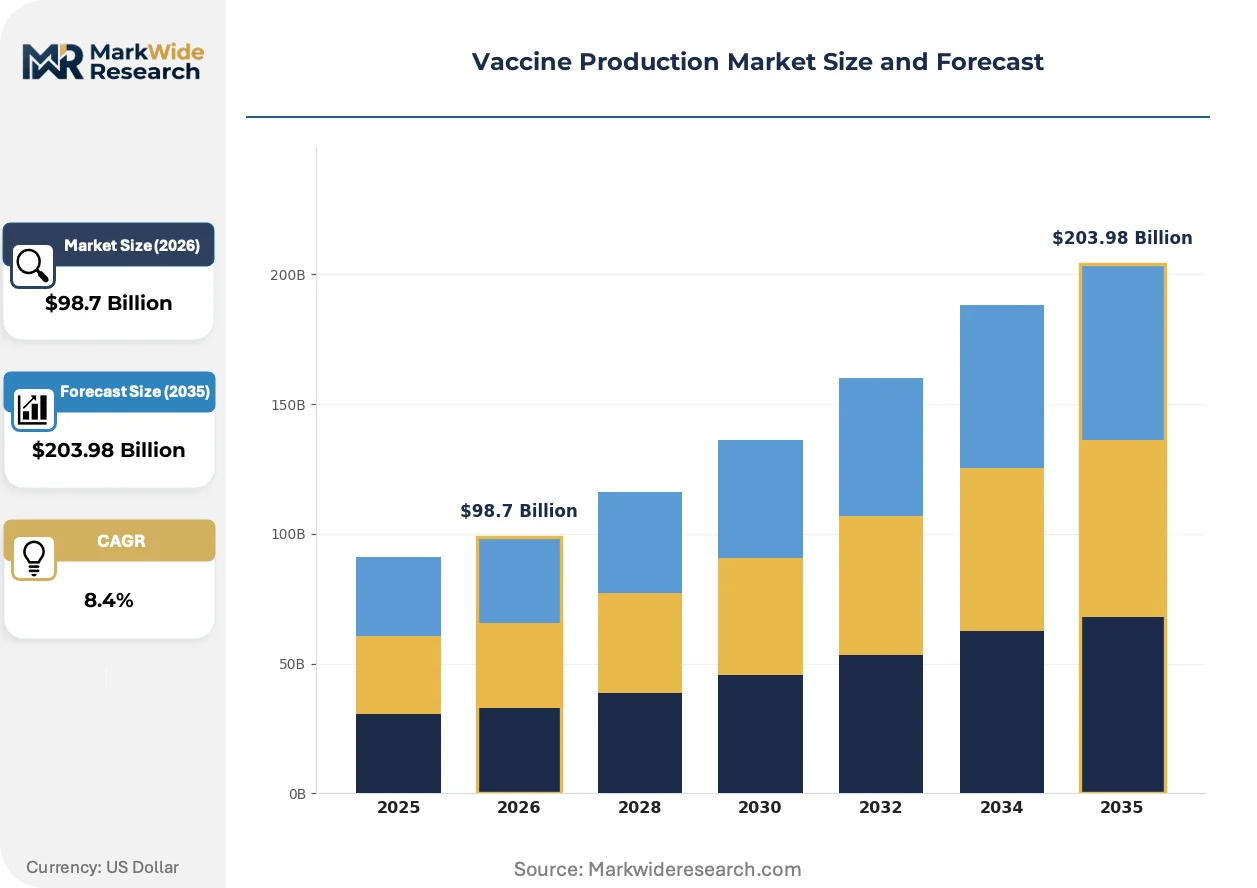
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccines, Inactivated Vaccines, Subunit Vaccines, mRNA Vaccines Manufacturing Stage: Preclinical, Clinical Trials, Commercial Production, Quality Control Technology: Recombinant Technology, Viral Vector Technology, Protein-Based Technology, DNA Technology End User: Pharmaceutical Companies, Research Laboratories, Government Agencies, Healthcare Providers |
| Companies Covered | Merck & Co., Inc., GSK plc, Pfizer Inc., Sanofi, CSL Limited, Johnson & Johnson Services, Inc., AstraZeneca, Serum Institute of India Pvt Ltd, Moderna, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Production Market Strategic Shifts
Continuous bioprocessing is displacing fed-batch paradigms while regulatory frameworks adapt to real-time release testing, compressing the gap between manufacturing innovation and compliance acceptance.
Microfluidic lipid nanoparticle synthesis is decentralizing formulation capacity from centralized mega-sites to modular 2000L production trains. Mid-size biotechs in Switzerland and Singapore are adopting these systems to retain process control without billion-dollar facility commitments. This compression of minimum efficient scale is fragmenting contract manufacturing concentration.
The FDA's Quality Management Maturity program is rewarding inspection history with reduced surveillance frequency. Manufacturers achieving Level 4 designation gain competitive positioning in pediatric tenders where procurement agencies weight regulatory reliability. European suppliers are responding by harmonizing their quality systems across FDA and EMA requirements simultaneously.
Subscription-based procurement is replacing per-dose contracting in high-income country pandemic preparedness frameworks. The US BARDA's Project NextGen and UK Health Security Agency's advance purchase commitments now guarantee minimum volumes across multiple suppliers. This shift is most visible in mRNA respiratory syncytial virus candidates, where developers secure manufacturing capacity before phase III completion.
Vaccine Production Market Segmentation
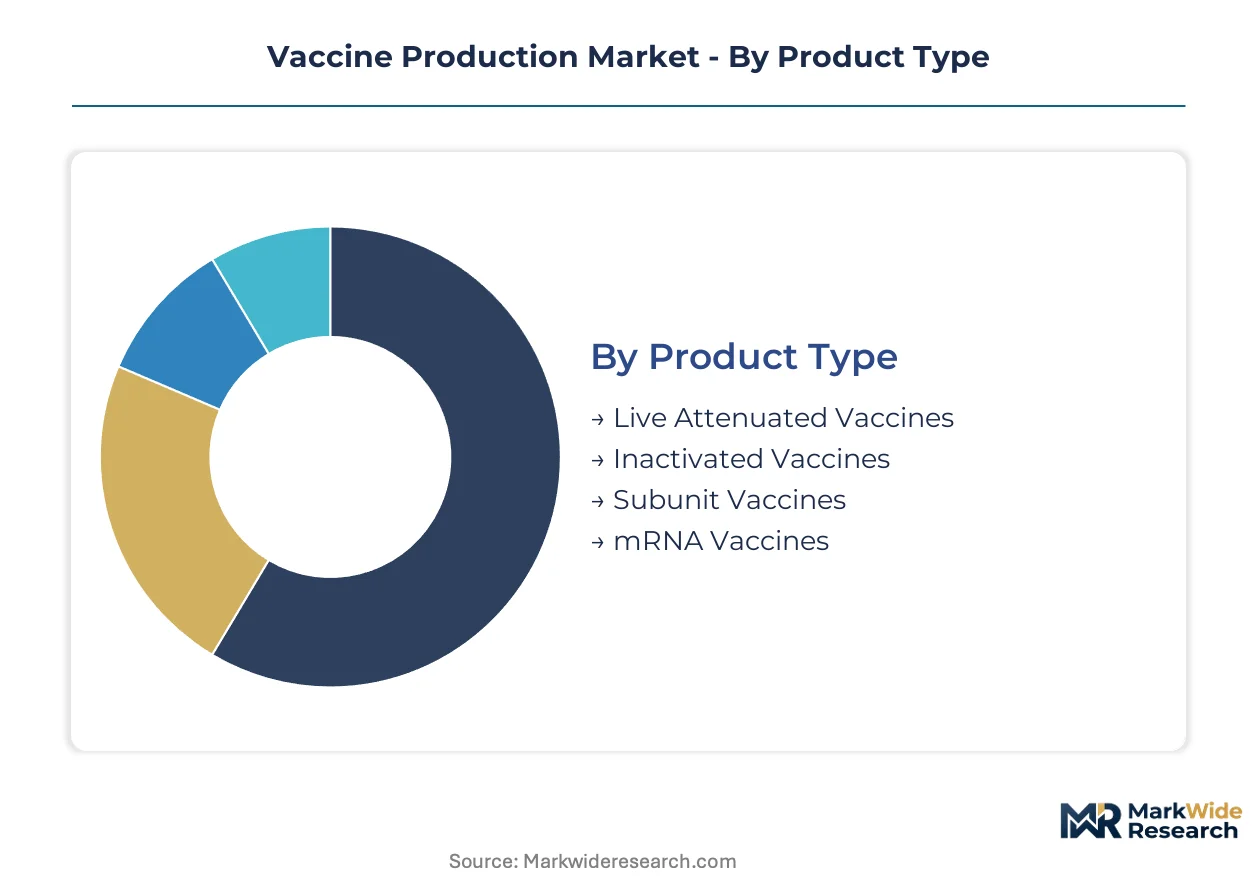
Vaccine production segmentation reveals divergent margin profiles and capital intensity across platform technologies. Manufacturing stage distribution determines regulatory pathway selection and revenue recognition timing for contract manufacturers.
Product Type:
Volume leadership sits with mature platforms while premium capture concentrates in novel modalities requiring specialized infrastructure.
- mRNA Vaccines:Lipid nanoparticle encapsulation of nucleoside-modified mRNA sequences demands -70°C cold-chain infrastructure and single-use bioreactor trains. Demand concentrates in high-income markets where BARDA and UKHSA subscription frameworks guarantee offtake for pandemic preparedness stockpiles.
- Live Attenuated Vaccines:Heat-sensitive viral strains propagated in embryonated eggs or cell culture yield durable cellular immunity at stabilized unit economics. UNICEF and Gavi procurement in India, Nigeria, and Bangladesh drives volume concentration for measles-rubella and rotavirus formulations.
- Inactivated Vaccines:Formalin-inactivated whole virion preparations using established aluminum adjuvant formulations dominate influenza and polio supply.
- Subunit Vaccines:Purified protein antigens with novel adjuvant systems from GSK and Dynavax reduce reactogenicity profiles.
Today's leader: Live Attenuated Vaccines. Tomorrow's challenger: mRNA Vaccines.
Manufacturing Stage:
Revenue visibility improves as candidates advance through clinical phases toward commercial validation.
- Commercial Production:Large-scale GMP manufacturing under FDA, EMA, and WHO prequalification generates recurring contract revenue with multi-year supply agreements. CDMOs in Switzerland and Singapore capture fill-finish volumes for European and Asia-Pacific commercial launches.
- Quality Control:Release testing, stability studies, and batch record review constitute 15-20% of production costs but determine regulatory approval velocity.
- Preclinical:Cell line development and master cell bank establishment precede IND-enabling toxicology studies.
- Clinical Trials:Phase I-III material supply requires adaptive manufacturing with limited batch sizes and extensive documentation.
Commercial Production commands current margins. Quality Control is climbing fastest as real-time release testing expands.
Technology:
Platform selection dictates facility retrofit requirements and partnership strategies with specialized suppliers.
- Recombinant Technology:Yeast and mammalian cell expression systems produce purified antigens for hepatitis B and HPV vaccines. India's PLI scheme subsidizes backward integration into antigen raw material production for domestic and export supply.
- Viral Vector Technology:Adenovirus and AAV platforms enable gene delivery for COVID-19 and emerging infectious disease candidates.
- Protein-Based Technology:Nanoparticle assembly and conjugation chemistry support pneumococcal and meningococcal vaccine production.
- DNA Technology:Plasmid manufacturing at gram scale remains pre-commercial for most indications despite platform flexibility.
Recombinant Technology anchors present capacity. Viral Vector Technology shows steepest expansion trajectory as gene therapy convergence accelerates.
End User:
Procurement concentration among government agencies reshapes contract terms toward volume guarantees and price caps.
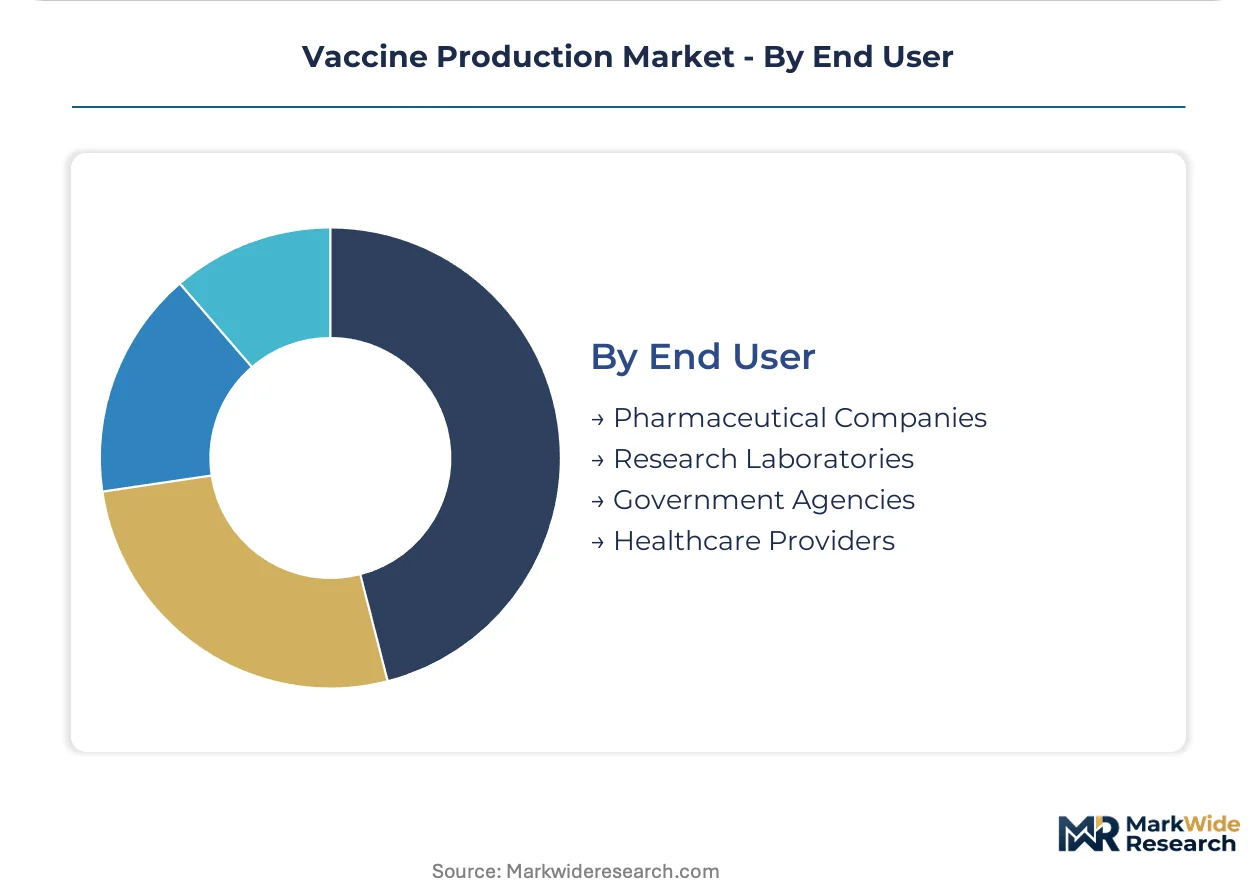
- Government Agencies:National immunization programs and pandemic preparedness authorities in the US, UK, and EU commission advance purchase agreements with minimum volume clauses. Subscription-based procurement replaces per-dose contracting for respiratory pathogen candidates.
- Pharmaceutical Companies:Vertical integration strategies at Pfizer and Sanofi retain process control while outsourcing fill-finish to specialized CDMOs.
- Research Laboratories:Academic and government research institutes require small-batch GMP material for early-phase investigator-initiated trials.
- Healthcare Providers:Hospital systems and private clinics in high-income markets purchase premium combination vaccines outside national procurement frameworks.
Government Agencies dominate tender volumes. Pharmaceutical Companies are gaining procurement sophistication through manufacturing joint ventures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands high-volume contract manufacturing while Switzerland specializes in precision fill-finish operations for European commercial launches. This geographic bifurcation shapes procurement patterns across income tiers.
United States
BARDA subscription frameworks and Project NextGen guarantee minimum offtake volumes for pandemic preparedness stockpiles. FDA Quality Management Maturity programs reward Level 4 manufacturers with reduced surveillance frequency in pediatric tenders. Boston-Cambridge biotech clusters anchor mRNA process development alongside North Carolina's Research Triangle manufacturing infrastructure.
India
Gavi and UNICEF procurement volumes for pentavalent and rotavirus formulations drive capacity expansion across 73 eligible countries. The PLI scheme subsidizes backward integration into antigen raw material production for domestic and export supply. Pune and Hyderabad industrial corridors concentrate fill-finish capacity and viral vector manufacturing platforms.
Switzerland
Specialized CDMOs capture European commercial launch volumes through ISO 5 cleanroom classification and aseptic processing expertise. Swissmedic harmonizes quality systems across FDA and EMA requirements simultaneously. Basel and Zurich regions anchor precision biomanufacturing for recombinant protein and cell culture propagation.
United Kingdom
UK Health Security Agency advance purchase commitments guarantee manufacturing capacity before phase III completion for respiratory pathogen candidates. MHRA post-Brexit regulatory autonomy diverges from EMA centralized protocols on novel adjuvant batch release. Oxford-Cambridge arc concentrates viral vector technology and academic spinout commercialization.
China
NMPA accelerated approval pathways for domestic vaccine candidates compress development timelines against WHO prequalification standards. National immunization program volume growth creates demand for in-country fill-finish capacity to replace import dependency. Suzhou and Shanghai biotech parks anchor mRNA lipid nanoparticle formulation and single-use bioreactor adoption.
Vaccine Production Market Competitive Environment
United States producers anchor one tier; European specialists hold premium positioning through regulatory harmonization. The vendor base fragments across platform technologies rather than geographic concentration alone. Three archetypes dominate: vertically integrated pharmaceutical conglomerates retaining process control, high-volume contract manufacturers serving UN procurement, and precision CDMOs specializing in aseptic fill-finish. Competitive moves concentrate on capacity expansion through modular bioreactor trains and strategic partnerships for lipid nanoparticle formulation know-how.
Within the vertically integrated tier, Pfizer Inc. and Merck & Co., Inc. occupy positions defined by captive mRNA manufacturing infrastructure and pandemic-era capacity retention. Serum Institute of India Pvt Ltd exemplifies the high-volume archetype through Gavi and UNICEF tender dominance. These three entities represent the spectrum from premium technology capture to cost-optimized supply security.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GSK plc |
| Pfizer Inc. |
| Sanofi |
| CSL Limited |
| Johnson & Johnson Services, Inc. |
| AstraZeneca |
| Serum Institute of India Pvt Ltd |
| Moderna, Inc. |
| Others |
Value Chain & Pricing Dynamics
Gavi's 2026-2030 strategic procurement expansion across 73 eligible countries is forcing manufacturers to reconfigure capacity toward high-volume, low-margin tenders and away from premium private-market positioning.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard pediatric vaccines while mRNA platforms sustain premium capture through lipid nanoparticle complexity. Contract manufacturers operate on three-tier pricing structure across premium, standard, and economy levels differentiated by WHO prequalification status and cold-chain certification. Cost compression in high-volume tenders is intensifying because Serum Institute of India scales backward integration into antigen raw material production. Government procurement agencies show lowest price sensitivity; private healthcare providers in high-income markets exhibit highest willingness to pay for combination formulations.
Supply Chain Analysis
Freight costs for -70°C ultra-low temperature shipments from European formulation sites to sub-Saharan African distribution points consume 15-25% of landed product value. Pharmaceutical-grade phospholipid supply concentrates in Germany, Japan, and the United States, with four suppliers controlling 80% of DSPC input for lipid nanoparticle production. Manufacturing draws from single-use bioreactor consumables, chromatography resins, and aseptic fill-finish isolators vulnerable to semiconductor-linked lead time extension. Tariff exposure on Chinese-sourced single-use bags and tubing creates input cost volatility. Distribution runs through UNICEF's Copenhagen distribution hub for Gavi-eligible countries and direct national tender fulfillment for self-procuring governments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through recurring pediatric immunization procurement cycles that reset every strategic period regardless of pandemic disruption.
For Market Incumbents: Anticipate mRNA platform commoditization by securing lipid nanoparticle formulation patents and building modular 2000L production trains in Switzerland or Singapore to retain process control. Defend against Serum Institute of India's cost-optimized scale by investing in FDA Quality Management Maturity Level 4 designation for pediatric tender preference weighting. Prioritize EMA-WHO dual harmonization to capture European commercial launches and UN procurement simultaneously. For New Entrants and Emerging Players: CDMO partnerships with Indonesian national immunization program localization initiatives offer the most penetrable entry vector for fill-finish capacity replacement of import dependency. Target combination vaccine R&D white space in hexavalent DTaP-IPV-Hib-HepB formulations where injection burden reduction commands private-market premium. Deploy microfluidic lipid nanoparticle synthesis platforms to achieve minimum efficient scale without billion-dollar facility commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with precision CDMOs specializing in aseptic fill-finish and ISO 5 cleanroom validation, positioned for European commercial launch volume capture. Five-to-ten-year viability rests on regulatory harmonization capability across FDA, EMA, and WHO prequalification pathways. Monitor EMA batch release velocity for novel adjuvants as inflection indicator for time-to-market compression and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Modular bioreactor trains in Pune and Hyderabad capture Gavi tender volume expansion across 73 eligible countries. |
| Regulatory Approval Pathway | WHO Emergency Use Listing acceleration opens UN procurement access for pandemic vaccine developers. |
| Backward Integration | India's PLI scheme subsidizes antigen raw material production for export supply security. |
| Licensing Agreement | Lipid nanoparticle formulation patents concentrate know-how among established mRNA manufacturers. |
| Pipeline Diversification | Hexavalent combination vaccines reduce injection burden and capture premium positioning in private markets. |
Study Parameters
Direct dialogue with bioprocess engineers, regulatory affairs leads at FDA and EMA, Gavi procurement officers, and UNICEF supply chain managers grounded qualitative insights in operational reality. Secondary validation drew from FDA facility inspection records, WHO prequalification listings, ClinicalTrials.gov protocol registries, and Gavi annual progress reports. Bottom-up capacity modeling across single-use bioreactor installations and top-down procurement volume analysis triangulated market sizing.
Bottom-up segmentation by platform technology, manufacturing stage, and end-user procurement archetype anchored volume projections across the analysis window. Modeled dimensions included mRNA versus live attenuated versus recombinant technology splits, commercial production versus clinical trial material supply stages, and government agency versus pharmaceutical company versus healthcare provider end-user channels. CAGRs derived from compound growth of identified procurement volumes and capacity expansion announcements. Forecast inputs incorporated Gavi 2026-2030 strategic period volume commitments and BARDA subscription framework minimum offtake guarantees.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between accelerated emergency pathways and full licensure requirements, phospholipid supply concentration risk, and cold-chain infrastructure buildout pace in sub-Saharan Africa. Forecasts reflect assumptions about procurement agency consolidation and platform technology transition timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Global Pegylated Proteins Market