
 Global RNA-Interference (Rnai) Market | 2026-2036
Global RNA-Interference (Rnai) Market Size, Share, and Industry Trends Forecast 2026-2036
Global RNA-Interference (Rnai) Market Foresight
Buyer concentration among biopharmaceutical companies is expanding as large developers internalize RNAi discovery platforms while smaller innovators fragment across niche indications. Alnylam Pharmaceuticals dominates commercial-stage RNAi therapy with proprietary GalNAc conjugate delivery technology. Arrowhead Pharmaceuticals leverages its TRiM platform to sustain partnerships across multiple therapeutic areas. Silence Therapeutics anchors European development capacity with specialized lipid nanoparticle formulation expertise.
RNA interference denotes a conserved biological mechanism wherein double-stranded RNA triggers sequence-specific degradation of complementary messenger RNA, typically employing 21-23 nucleotide small interfering RNA molecules processed by the Dicer enzyme complex within the RNA-induced silencing complex. This pathway enables precise knockdown of disease-causing genes, supporting therapeutic applications in oncology, genetic disorders, and viral infections where conventional small-molecule or antibody approaches prove inadequate. Small interfering RNA products command the largest current revenue share given mature manufacturing protocols and established clinical validation. Lipid nanoparticle delivery systems attract the fastest development investment due to demonstrated hepatic tropism and scalable production. Micro RNA segments occupy emerging positions in cardiovascular conditions where endogenous regulatory networks offer polygenic intervention opportunities.
FDA nucleic acid therapy guidance and EMA's Committee for Advanced Therapies framework shape trial endpoints, manufacturing quality standards, and post-market surveillance obligations for RNAi developers. The EU AI Act and GDPR provisions increasingly influence automated target identification platforms and patient genomic data handling across European development programs. Stakeholders must monitor evolving reimbursement negotiations for single-administration genetic therapies versus chronic dosing paradigms.
Market Dynamics
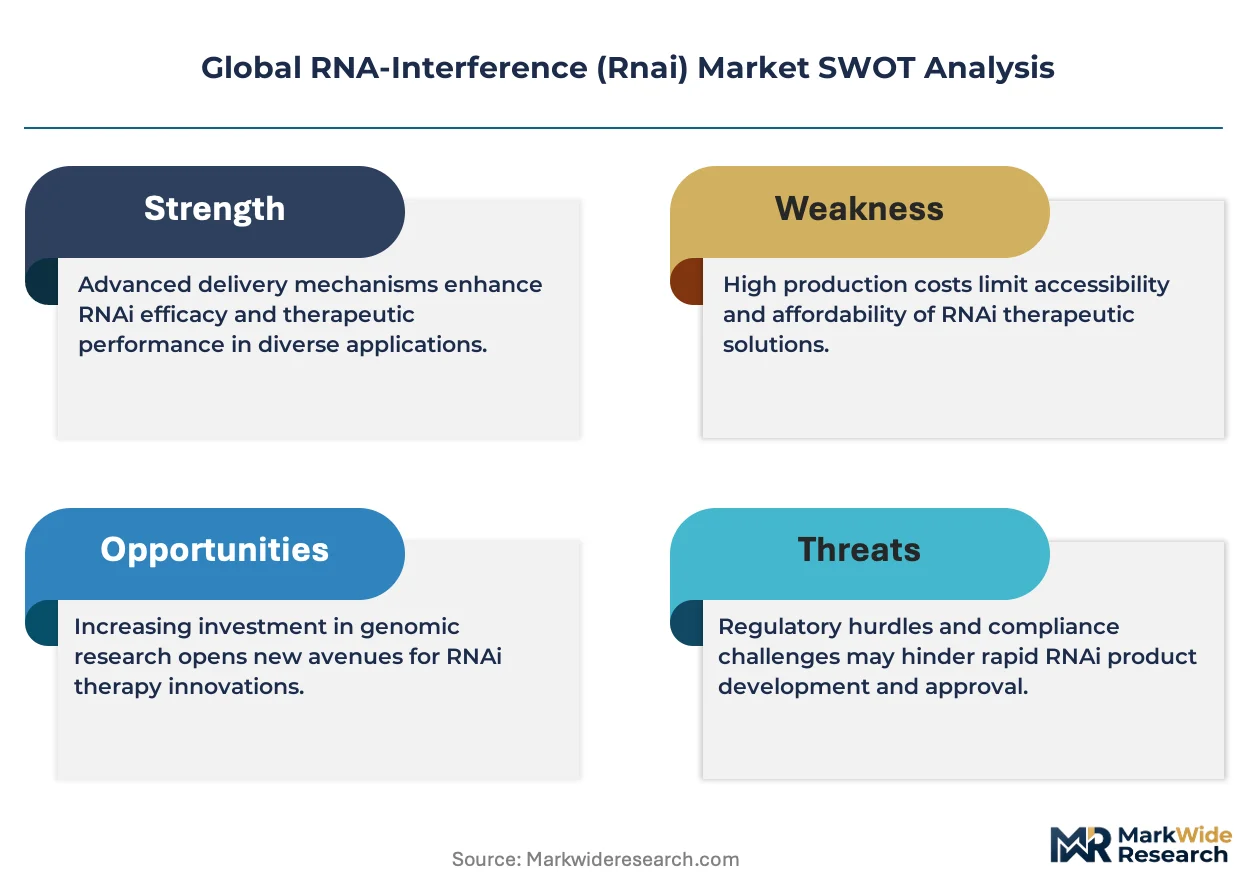
GalNAc conjugate delivery chemistry is compressing development timelines for hepatocyte-targeted RNAi therapeutics, while FDA and EMA nucleic acid guidance frameworks accelerate regulatory pathways for first-in-class genetic disorder treatments.
Growth Catalysts
- Accelerated Approval Pathways:FDA nucleic acid therapy guidance and EMA's Committee for Advanced Therapies framework compress clinical trial phases for orphan genetic indications.
- Biopharmaceutical Platform Internalization:Large developers are absorbing RNAi discovery capabilities in-house, consolidating target validation and lead optimization under single organizational control.
- Specialized Manufacturing Infrastructure:Contract development organizations in Germany and Japan have scaled lipid nanoparticle production lines, enabling commercial supply security for approved therapies.
Market Restraints
- Input Cost Volatility:High-purity synthetic oligonucleotide precursors and specialized lipids for nanoparticle formulation face supply concentration among European and Asian chemical suppliers.
- Delivery Tissue Limitation:Current lipid nanoparticle and GalNAc platforms demonstrate validated tropism primarily for hepatocytes, restricting addressable disease targets to liver-expressed genes.
- Reimbursement Friction:Single-administration genetic therapies encounter resistance from payers accustomed to chronic dosing paradigms, complicating market access negotiations.
Strategic Opportunities
- Extrahepatic Delivery Expansion:Central nervous system and ocular targeting technologies remain underdeveloped, offering first-mover positioning for neurological and retinal genetic conditions.
- MicroRNA Cardiovascular Applications:Endogenous regulatory networks in heart failure and atherosclerosis represent polygenic intervention opportunities beyond single-gene knockdown approaches.
- Automated Target Identification:Machine learning platforms for siRNA sequence optimization and off-target prediction are compressing preclinical discovery timelines for novel indications.
Industry Challenges
- Talent Scarcity in Oligonucleotide Chemistry:Specialized expertise in large-scale synthetic RNA manufacturing and analytical method development remains concentrated among a limited pool of experienced practitioners.
- IP Landscape Complexity:Fundamental RNAi mechanism patents, delivery platform rights, and sequence-specific claims create overlapping exclusivity zones requiring careful freedom-to-operate analysis.
- Integration with Legacy Biologics Infrastructure:RNAi manufacturing requires distinct cleanroom specifications, analytical equipment, and quality control protocols compared to monoclon antibody production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RNA-Interference (Rnai) Market |
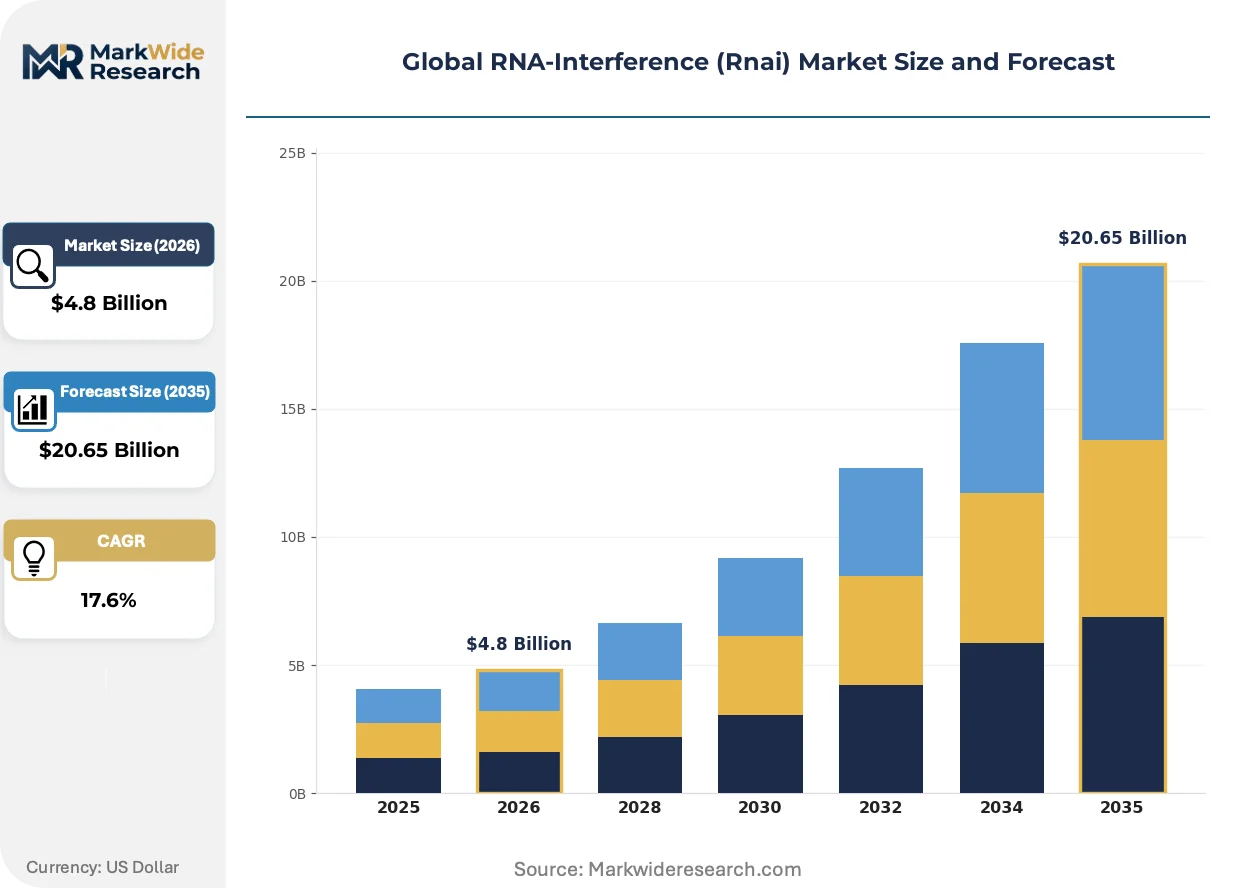
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Interfering RNA, Micro RNA, Short Hairpin RNA, Dicer-Substrate RNA, Others Therapy Area: Oncology, Genetic Disorders, Viral Infections, Neurological Diseases, Cardiovascular Conditions Delivery Mode: Lipid Nanoparticles, Viral Vectors, Conjugates, Physical Methods, Polymer-Based Systems End User: Biopharmaceutical Companies, Research Institutes, Contract Research Organizations, Academic Laboratories |
| Companies Covered | Alnylam Pharmaceuticals, Arrowhead Pharmaceuticals, Silence Therapeutics, Novo Nordisk, Novartis, Ionis Pharmaceuticals, Sanofi, Arbutus Biopharma, Sirnaomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RNA-Interference (Rnai) Market Shifts & Advancements
Delivery platform engineering and computational target discovery are converging to expand RNAi therapeutics beyond established hepatocyte applications into immunology, oncology, and neurological disease categories.
Artificial intelligence-driven siRNA sequence design is automating off-target prediction and chemical modification selection, compressing lead optimization cycles from months to weeks. Biopharmaceutical discovery groups at Alnylam and Arrowhead have integrated these platforms into iterative design loops. The technology is automating previously manual sequence-activity relationship mapping, enabling parallel evaluation of hundreds of candidate molecules.
EMA's updated nucleic acid therapy quality guidelines and FDA's emerging guidance on long-acting genetic medicines are harmonizing manufacturing standards for lipid nanoparticle and conjugate-based products. These frameworks mandate enhanced characterization of impurity profiles and stability testing protocols. European developers face particular scrutiny under the EU AI Act for automated target identification algorithms processing patient genomic data.
Biopharmaceutical procurement of RNAi manufacturing services is consolidating toward full-service partnerships spanning discovery chemistry through commercial supply. Small and mid-cap developers are abandoning fragmented vendor relationships in favor of integrated CDMO alliances with dedicated oligonucleotide capacity. This concentration is most visible in the United States and Germany, where specialized facilities command premium pricing for guaranteed slot allocation.
Global RNA-Interference (Rnai) Market Segmentation
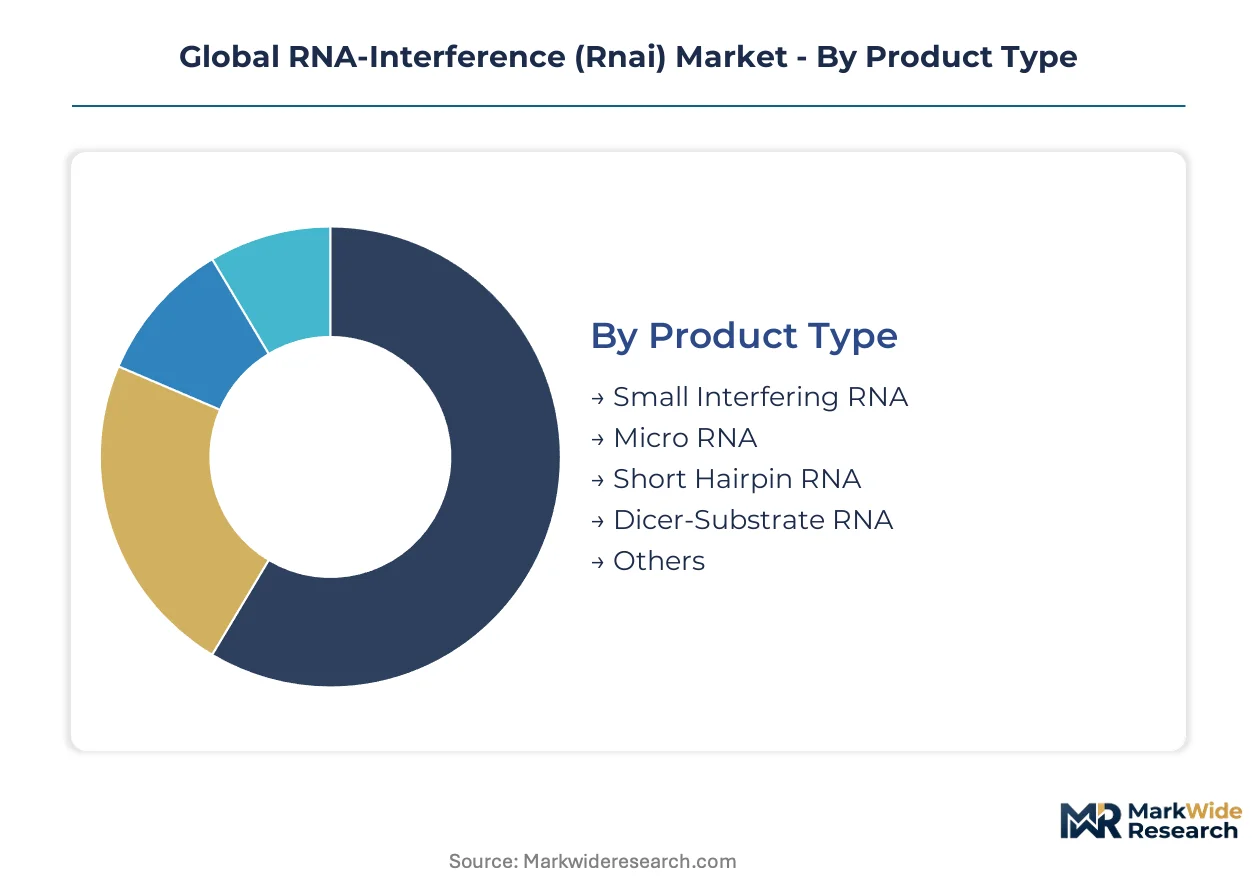
RNAi therapeutic development demands precise alignment between molecular format, disease target, delivery technology, and development partner. Segmentation reveals where manufacturing maturity, clinical validation, and commercial infrastructure concentrate across the value chain.
Product Type:
Double-stranded RNA length and processing mechanism define pharmacokinetic profiles and manufacturing complexity for each molecular class.
- Small Interfering RNA:Synthetic 21-23 nucleotide duplexes processed by Dicer bypass endogenous machinery for direct RISC loading. Hepatic tropism from GalNAc conjugation has locked in demand from Alnylam and Arrowhead pipeline candidates targeting transthyretin and hepatitis B.
- Micro RNA:Endogenous regulatory molecules modulate multiple gene networks simultaneously. Cardiovascular applications in heart failure attract development investment from Silence Therapeutics and Regulus Therapeutics where polygenic intervention offers advantages over single-target knockdown.
- Short Hairpin RNA:Vector-encoded hairpin structures enable sustained expression from DNA templates. Viral delivery programs in neurological gene silencing exploit this durability for central nervous system targets.
- Dicer-Substrate RNA:Longer 25-30 base pair substrates enhance potency through optimized Dicer cleavage. Specialized oncology applications leverage improved target engagement kinetics.
- Others:Bifunctional RNA chimeras and self-delivering modifications occupy exploratory preclinical portfolios.
Mature deployment sits with Small Interfering RNA. Newer deployment is concentrated in Micro RNA cardiovascular networks.
Therapy Area:
Disease biology determines whether single-gene knockdown suffices or broader regulatory modulation proves necessary.
- Oncology:Tumor suppressor restoration and oncogene silencing drive siRNA combinations with checkpoint inhibitors. Solid tumor penetration limitations restrict programs to liver metastases and hematologic malignancies where vascular access simplifies delivery.
- Genetic Disorders:Monogenic conditions with liver-expressed pathogenic proteins represent the commercial core. Transthyretin amyloidosis, acute hepatic porphyria, and primary hyperoxaluria approvals have validated this segment's reimbursement potential.
- Viral Infections:Hepatitis B surface antigen knockdown from Arrowhead and Vir Biotechnology programs demonstrates durable viral suppression. SARS-CoV-2 RNAi prophylaxis research continues despite pandemic transition.
- Neurological Diseases:Blood-brain barrier penetration challenges constrain development to intrathecal administration routes. Huntington's disease and Alzheimer's programs remain preclinical or early clinical.
- Cardiovascular Conditions:Lipid metabolism and vascular inflammation targets exploit liver-mediated systemic effects. PCSK9 silencing competes directly with monoclonal antibody and small-molecule alternatives.
Genetic Disorders command the deepest clinical infrastructure. Neurological Diseases represent the steepest expansion trajectory pending delivery breakthroughs.
Delivery Mode:
Tissue targeting specificity and manufacturing scalability separate platform winners from legacy approaches.
- Lipid Nanoparticles:Ionizable lipids encapsulate RNA cargo for endosomal escape. German CDMOs including Evonik and Merck KGaA have scaled GMP production for COVID-19 vaccine transfer applications.
- Conjugates:GalNAc-siRNA conjugates from Alnylam's proprietary chemistry enable subcutaneous dosing with 10,000-fold hepatocyte enrichment. Manufacturing simplicity relative to nanoparticles supports cost positioning.
- Viral Vectors:Adeno-associated and lentiviral platforms sustain expression for shRNA applications. Immunogenicity and packaging capacity limits restrict expansion beyond neurological and ocular indications.
- Physical Methods:Electroporation and hydrodynamic injection remain research tools with limited therapeutic translation.
- Polymer-Based Systems:Polyethylenimine and dendrimer formulations occupy exploratory development for tumor-targeted applications.
Conjugates anchor current commercial supply. Lipid Nanoparticles are gaining share fastest through platform versatility and COVID-19 manufacturing infrastructure redeployment.
End User:
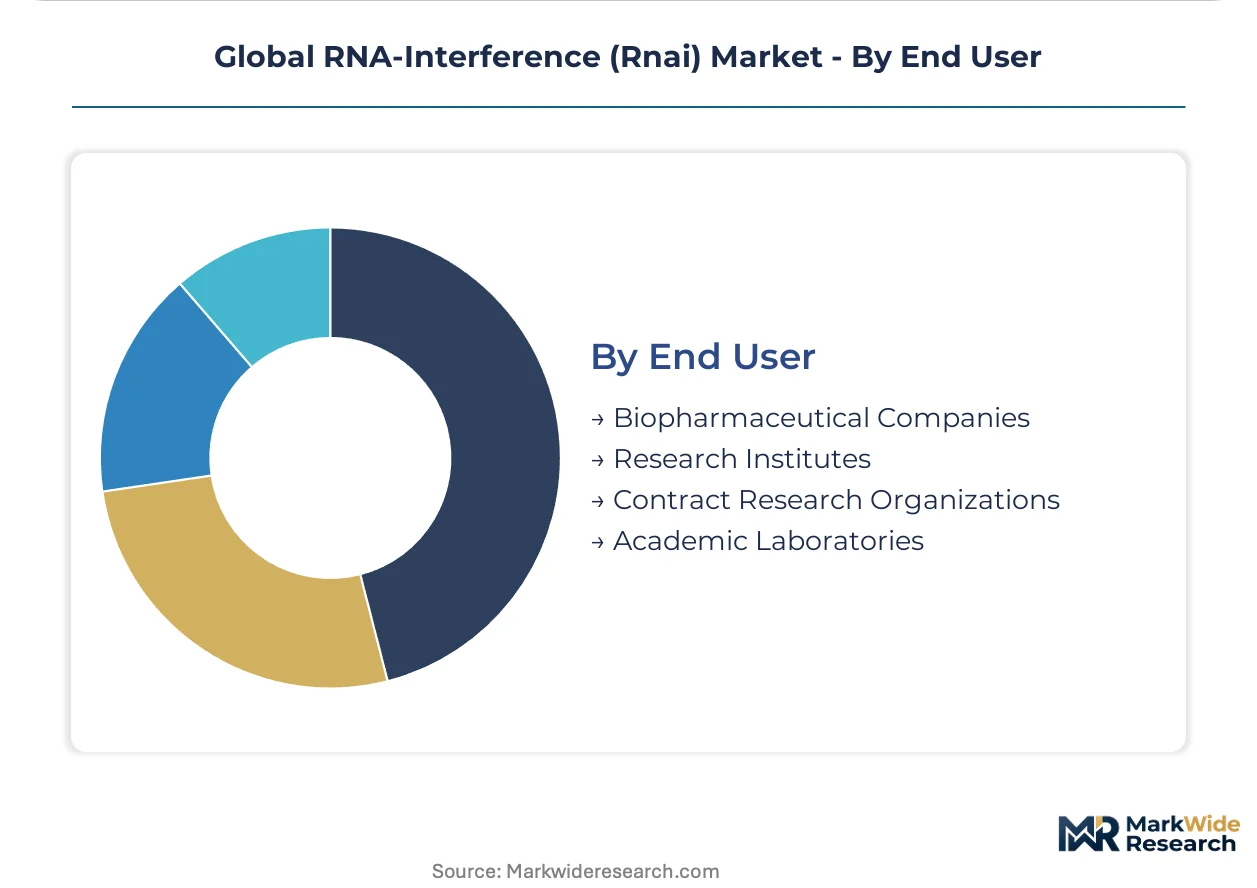
Development stage and capital intensity determine which organizational types dominate demand at each value chain position.
- Biopharmaceutical Companies:Platform internalization at Roche, Novartis, and Takeda has concentrated late-stage development and commercialization capacity. In-house chemistry manufacturing controls supply security for approved therapies.
- Research Institutes:Broad Institute, Scripps Research, and Max Planck Institutes advance target biology and delivery mechanisms through NIH and EU Horizon funding.
- Contract Research Organizations:Charles River Laboratories and LabCorp have built specialized nucleic acid pharmacology and toxicology capabilities to service developer outsourcing demand.
- Academic Laboratories:University-based discovery programs in Boston, San Francisco, and Heidelberg generate intellectual property licensed to commercial developers.
Biopharmaceutical Companies hold the dominant procurement position. Academic Laboratories feed the earliest-stage pipeline despite limited direct revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic oligonucleotide precursor supply concentrates among specialized chemical manufacturers in Germany and Japan, anchoring RNAi therapeutic production capacity in these jurisdictions while FDA and EMA regulatory frameworks shape commercialization pathways across North America and Europe.
United States
FDA nucleic acid therapy guidance compresses clinical trial phases for orphan genetic indications. The Inflation Reduction Act provisions influence pricing negotiations for single-administration genetic therapies. Greater Boston and San Francisco Bay Area clusters host Alnylam Pharmaceuticals and Arrowhead Pharmaceuticals headquarters with integrated discovery-through-commercial infrastructure.
Germany
Evonik and Merck KGaA have scaled GMP lipid nanoparticle production lines serving global RNAi developers. EMA's Committee for Advanced Therapies framework harmonizes quality standards for nucleic acid products across European markets. Heidelberg and Munich academic laboratories generate intellectual property licensed to commercial developers.
Japan
METI industrial policy supports domestic biopharmaceutical manufacturing capacity expansion for advanced therapies. PMDA accelerated review pathways align with FDA breakthrough designation timelines. Osaka and Tokyo metropolitan areas concentrate contract development organizations with specialized oligonucleotide synthesis capabilities.
United Kingdom
Silence Therapeutics anchors European RNAi development from London with lipid nanoparticle formulation expertise. MHRA post-Brexit regulatory autonomy enables parallel approval pathways with FDA and EMA. Cambridge and Oxford research institutes advance target biology through UK Research and Innovation funding.
Switzerland
Novartis and Roche maintain RNAi platform investments through internalized discovery capabilities and strategic partnerships. Swissmedic regulatory frameworks emphasize manufacturing quality standards for biologics and nucleic acid therapies. Basel and Zurich clusters integrate pharmaceutical headquarters with specialized CDMO networks.
Global RNA-Interference (Rnai) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue extrahepatic delivery technologies and cardiovascular microRNA applications. The competitive structure concentrates around platform-owning biopharmaceutical companies with internalized manufacturing capacity, while smaller innovators fragment across niche indications and partnership-dependent development models. Three archetypes dominate: integrated platform holders controlling end-to-end discovery through commercial supply, delivery technology specialists licensing access to hepatocyte-targeting chemistries, and indication-focused developers outsourcing manufacturing to contract organizations. Consolidation through acquisition of discovery platforms and capacity expansion in specialized oligonucleotide synthesis represent the primary competitive vectors.
Within the integrated platform tier, Alnylam Pharmaceuticals exemplifies end-to-end control over GalNAc conjugate chemistry and commercial manufacturing. Arrowhead Pharmaceuticals occupies a partnership-intensive position leveraging its TRiM platform across multiple therapeutic areas. Silence Therapeutics represents European-centered capacity with specialized lipid nanoparticle expertise serving regional development programs.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| Silence Therapeutics |
| Novo Nordisk |
| Novartis |
| Ionis Pharmaceuticals |
| Sanofi |
| Arbutus Biopharma |
| Sirnaomics |
| Others |
Supply & Pricing Matrix
Specialized oligonucleotide chemists concentrated in Germany and Japan command wage premiums that compress margin spreads between premium GalNAc-conjugated therapies and standard lipid nanoparticle formulations, with labor-cost differentials between Heidelberg and Osaka manufacturing clusters directly feeding into three-tier pricing stratification across hepatocyte-targeted and exploratory extrahepatic delivery platforms.
Pricing Analysis
Volume concentration in approved genetic disorder therapies supports premium pricing for Alnylam's Onpattro and Amvuttra franchises, while margin compression runs through early-stage cardiovascular microRNA candidates where clinical validation remains incomplete. Price differentiation hinges on FDA/EMA approval status and GalNAc conjugate chemistry exclusivity versus open-platform lipid nanoparticle alternatives. Cost compression in the standard tier is intensifying because CDMO slot scarcity in Germany forces developers to accept elevated manufacturing fees. Academic research institutes exhibit highest price sensitivity due to grant-funded procurement constraints, whereas integrated biopharmaceutical companies with captive synthesis capacity demonstrate lowest sensitivity.
Supply Chain Analysis
Cold-chain logistics costs for lipid nanoparticle formulations with strict temperature stability requirements anchor total delivered cost structures, with freight expenditure representing a material line item in European and Japanese distribution networks. High-purity phosphoramidite precursors and ionizable lipids draw from specialized chemical manufacturers in Germany, Japan, and Switzerland, creating geographic concentration risk. Single-source vulnerability persists for Dicer-substrate RNA manufacturing equipment where German suppliers dominate precision synthesis platform production. Distribution runs through full-service CDMO partnerships spanning discovery chemistry to commercial fill-finish, with Alnylam and Arrowhead internalizing critical GalNAc conjugation steps to secure supply continuity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RNAi therapeutic landscape sits in a platform-transition phase where GalNAc-hepatocyte delivery is displacing first-generation lipid nanoparticle systems, with automated siRNA design algorithms compressing discovery timelines and reshaping competitive economics for developers across all capitalization tiers.
For Market Incumbents: Anchor manufacturing capacity in Germany and Japan through dedicated cleanroom investments or exclusive CDMO slot arrangements, insulating against oligonucleotide synthesis bottlenecks. Secure freedom-to-operate positions in extrahepatic delivery patents before Arrowhead and Silence Therapeutics consolidate CNS and ocular targeting intellectual property. Backward integration into phosphoramidite precursor production reduces exposure to European chemical supplier concentration.
For New Entrants and Emerging Players: Launch via automated target identification platforms licensed to biopharmaceutical incumbents, avoiding capital-intensive manufacturing buildout. Cardiovascular microRNA modulation in heart failure represents the most penetrable segment given polygenic intervention advantages over saturated single-gene knockdown markets. A go-to-market angle centered on EMA's Committee for Advanced Therapies regulatory consulting services addresses developer capability gaps in European nucleic acid submissions.
For Investors and Strategic Acquirers: Re-rating potential sits with delivery technology specialists possessing validated extrahepatic platforms given FDA's emerging long-acting genetic medicine guidance and unmet neurological disease demand. The five-to-ten-year viability window favors developers with integrated chemistry manufacturing control over partnership-dependent models vulnerable to CDMO pricing power. Watch for PMDA accelerated review pathway harmonization with FDA timelines as the inflection signal for Japanese market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc Manufacturing Scale-Up | Alnylam's internalized conjugation chemistry secures supply continuity for transthyretin amyloidosis franchise expansion. |
| Extrahepatic Delivery Partnership | Arrowhead's TRiM platform licensing to neurological disease developers unlocks CNS penetration revenue streams. |
| Automated siRNA Design Integration | Machine learning sequence optimization compresses lead optimization cycles from months to weeks at discovery-stage biopharmaceuticals. |
| EMA Advanced Therapies Consultation | Early engagement with Committee for Advanced Therapies harmonizes quality standards across European nucleic acid development programs. |
| Lipid Nanoparticle Capacity Expansion | Evonik and Merck KGaA GMP line scaling supports commercial supply security for approved hepatitis B RNAi therapies. |
Research Methodology
Independent corroboration across regulatory submission databases, CDMO capacity utilization reports, and biopharmaceutical R&D pipeline disclosures underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at US and German payers, and oligonucleotide manufacturing specialists provided forward-looking perspective. Secondary validation drew from FDA nucleic acid therapy guidance documents, EMA Committee for Advanced Therapies framework updates, ClinicalTrials.gov RNAi program listings, and European customs data on synthetic oligonucleotide precursor trade flows. Bottom-up therapeutic candidate enumeration and top-down market sizing triangulated to segment-level outputs.
Comparable-period anchoring to historical approval timelines for Patisiran, Givosiran, and Lumasiran established baseline assumptions for regulatory pathway duration and commercial uptake curves across the projection horizon. The analytical framework modeled value progression across molecular format, therapy area, delivery mode, and development partner archetype dimensions. CAGRs derived from fitted growth curves incorporating manufacturing capacity constraints, reimbursement negotiation dynamics, and platform technology substitution effects. Forecast inputs included PMDA accelerated review pathway adoption rates and EU AI Act compliance cost burdens for automated target identification platforms.
Regulatory guidance revision, manufacturing input cost volatility, and extrahepatic delivery clinical trial failures are the dominant revision risks that could compress or extend projected value trajectories. Stakeholders should weight assumptions against their own operating context and risk tolerance for nucleic acid therapy development timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Blood Brain Barrier Technologies Market