
 US Value-Based Healthcare Service Market | 2026-2036
US Value-Based Healthcare Service Market Size, Share, and Industry Trends Forecast 2026-2036
US Value-Based Healthcare Service Market Intelligence
Cloud-native data interoperability is fragmenting legacy electronic health record architectures into modular, API-driven service layers. UnitedHealth Group leverages its Optum analytics engine to anchor risk-adjusted payment models across Medicare Advantage networks. Privia Health competes through physician practice management tools that sustain capitated contracts in outpatient settings. Signify Health, Inc. specializes in-home health assessments that extend value-based contract reach beyond facility walls.
Value-based healthcare service encompasses the design, administration, and optimization of payment and care delivery models that tie provider reimbursement to patient outcomes rather than service volume, typically integrating clinical quality metrics with total cost of care benchmarks. These services deploy predictive analytics engines and care coordination platforms to reduce hospital readmission rates while aligning physician incentives with population health targets. Accountable Care Organizations currently occupy the largest payment model segment as CMS-mandated participation drives hospital system consolidation into risk-bearing entities. Bundled Payments represent the fastest-expanding category, particularly for orthopedic and cardiac episodes where episode cost predictability attracts employer-sponsored plan adoption. Care Coordination services capture concentrated margin pools as payers outsource complex chronic disease management to specialized vendors.
CMS rules under the Medicare Shared Savings Program and the Affordable Care Act framework shape provider participation thresholds and quality reporting requirements for value-based entities. HIPAA compliance obligations and FDA oversight of clinical decision support algorithms constrain how analytics platforms integrate patient data for risk stratification. Stakeholders must monitor whether CMS finalizes mandatory ACO participation timelines for traditional Medicare beneficiaries before committing capital to alternative payment infrastructure.
Market Dynamics
Medicare Advantage enrollment expansion and CMS-mandated ACO participation timelines are compressing provider reimbursement timelines while forcing hospital systems into risk-bearing contract structures faster than infrastructure can adapt.
Growth Catalysts
- Medicare Shared Savings Program:CMS-mandated participation thresholds push hospital systems into risk-bearing ACO structures, expanding the addressable market for contract administration services.
- Cloud-native interoperability:API-driven data exchange layers enable real-time quality metric reporting that satisfies payer requirements without legacy EHR overhaul costs.
- Texas and Florida hospital concentration:These states' large Medicare Advantage populations create concentrated demand for bundled payment administration expertise.
Market Restraints
- HIPAA compliance friction:Privacy rule constraints on patient data sharing limit how analytics platforms stratify risk across competing health system boundaries.
- Physician practice consolidation:Independent physician attrition reduces the pool of entities capable of entering direct capitated contracts with payers.
- Legacy EHR technical debt:Proprietary data architectures in Cerner and Epic installations resist modular extraction without expensive middleware development.
Strategic Opportunities
- In-home assessment expansion:Medicare Advantage supplemental benefit flexibility permits payers to extend value-based contract reach beyond facility walls into patient residences.
- Employer-sponsored bundled payments:Self-insured employers in manufacturing and logistics verticals seek episode-based pricing for orthopedic procedures absent CMS complexity.
- Social determinants data integration:Convergence of clinical records with housing and transportation datasets enables refined risk adjustment models that capture non-clinical cost drivers.
Industry Challenges
- Actuarial talent scarcity:Health systems struggle to hire personnel capable of reconciling clinical quality metrics with total cost of care benchmarks in real-time reporting environments.
- Multi-payer contract complexity:Providers managing simultaneous Medicare Advantage, commercial, and Medicaid value-based contracts face incompatible quality measure specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Value-Based Healthcare Service Market |
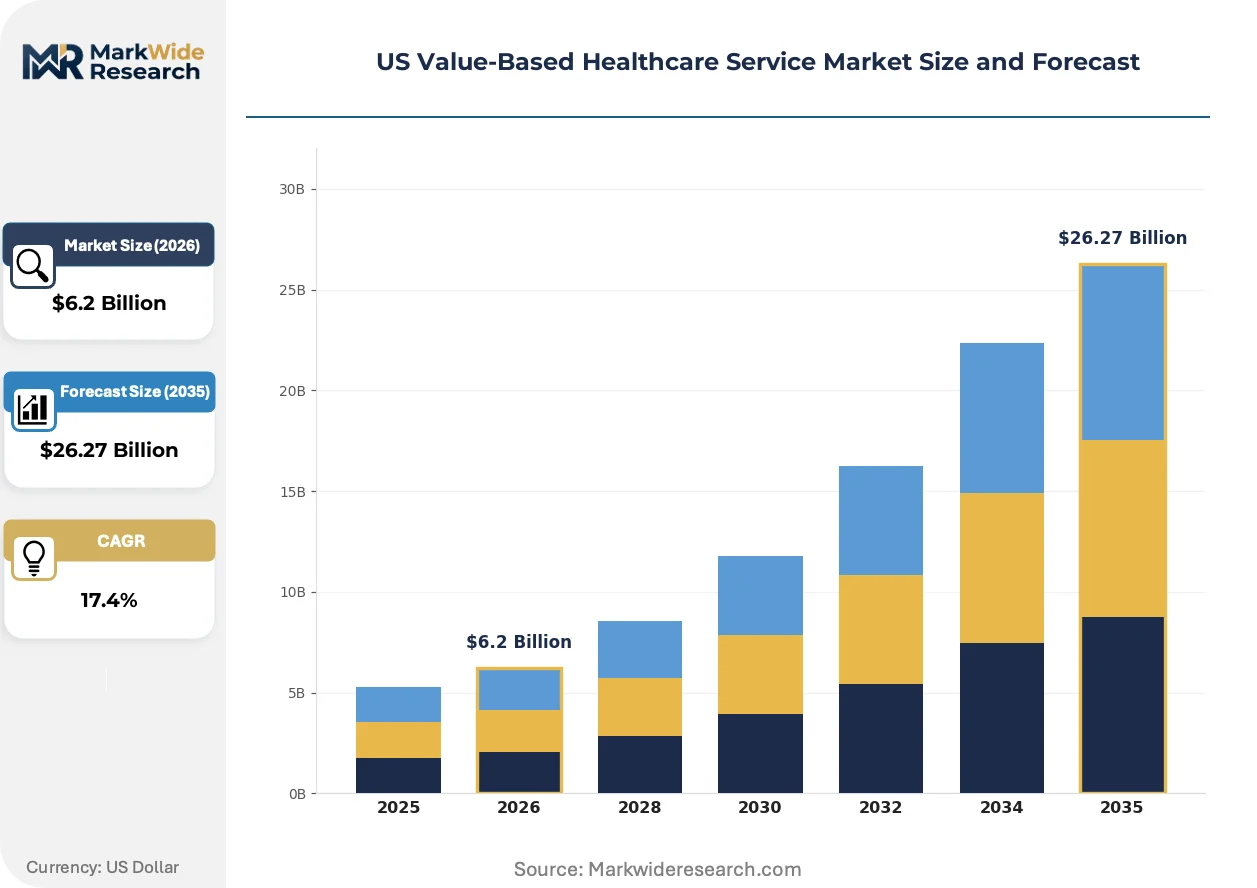
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Care Coordination, Patient Engagement, Analytics, Quality Improvement Payment Model: Accountable Care Organizations, Bundled Payments, Shared Savings Programs, Capitation End User: Hospitals, Physician Practices, Insurance Providers, Outpatient Clinics Technology: Telehealth Solutions, Electronic Health Records, Data Analytics Platforms, Patient Portals |
| Companies Covered | Change Healthcare, Privia Health, UnitedHealth Group, Koninklijke Philips N.V., Deloitte, Humana, Signify Health, Inc., Cigna, McKesson Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Value-Based Healthcare Service Market Strategic Shifts & Innovations
Artificial intelligence and machine learning architectures are penetrating care coordination platforms, compressing the lag between clinical event detection and intervention deployment while forcing legacy rule-based systems into obsolescence.
Federated learning models applied to distributed patient datasets enable risk stratification without centralized data repositories. Medicare Advantage plans at Anthem and Centene deploy these architectures to predict hospitalization events within 72-hour windows. The approach is rendering obsolete the batch-processing analytics engines that previously dominated population health management.
CMS rules under the Medicare Shared Savings Program and the Affordable Care Act framework tighten quality reporting requirements and accelerate mandatory participation timelines for traditional Medicare beneficiaries. Hospital systems in Texas and Florida respond by consolidating into regional ACOs capable of bearing downside risk. The policy shift most acutely affects independent physician practices lacking capital reserves for risk-based contract infrastructure.
Self-insured employers now demand episode-based pricing for cardiac and orthopedic procedures, bypassing traditional fee-for-service intermediaries. Manufacturing and logistics employers in the Southeast negotiate directly with health systems for bundled payment arrangements. This procurement evolution concentrates contract volume with administrators capable of managing multi-stakeholder episode accountability across disparate care settings.
US Value-Based Healthcare Service Market Segmentation
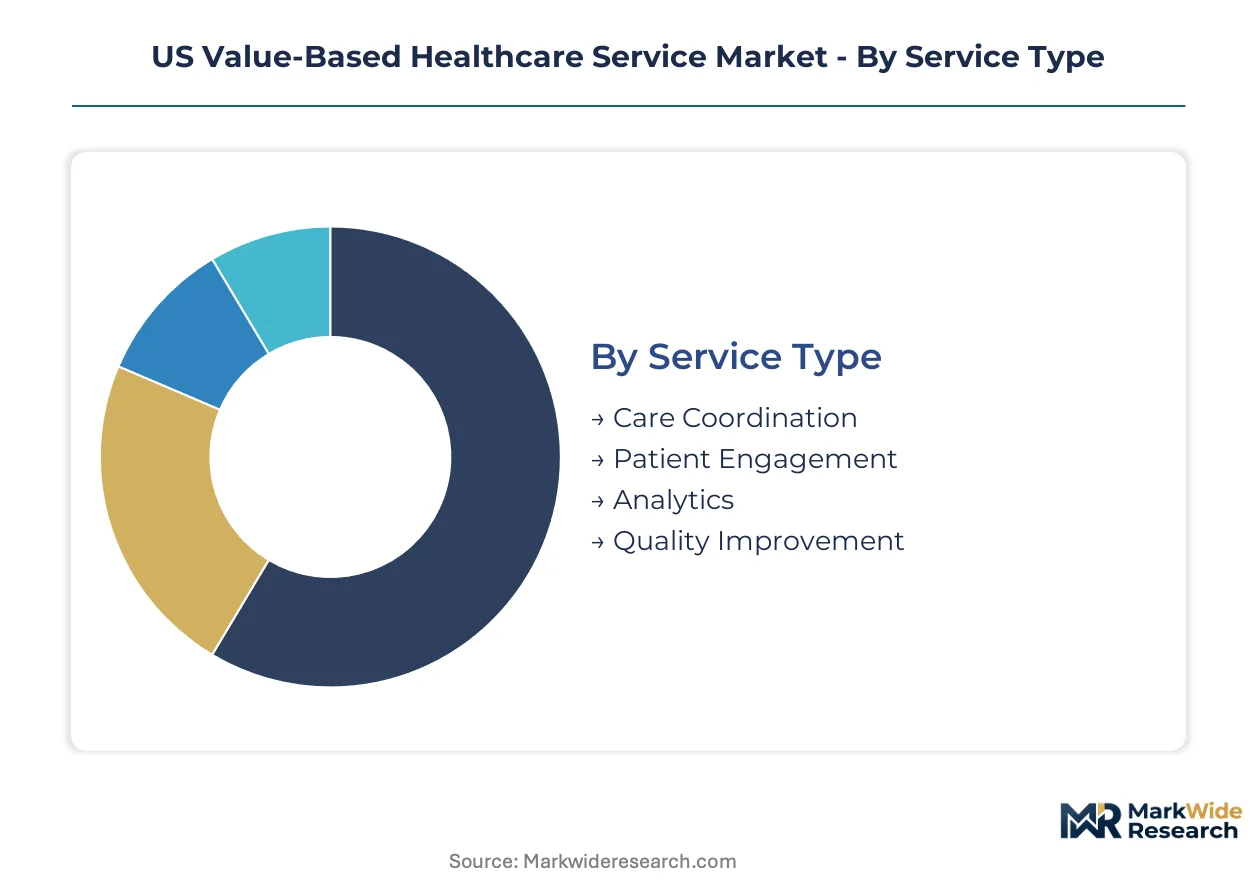
Service delivery models in the US value-based healthcare market fragment across four critical dimensions. Payment structures, technology infrastructure, and end-user capabilities determine contract viability and margin capture for vendors navigating CMS-mandated participation timelines.
Service Type:
After-sales service intensity varies sharply across service types, with ongoing platform maintenance and algorithm recalibration creating recurring revenue streams distinct from initial implementation fees.
- Care Coordination:Chronic disease management platforms integrate nurse navigators with predictive triage algorithms. Texas and Florida hospital systems concentrate procurement of these services as Medicare Advantage enrollment swells in Sun Belt retirement corridors.
- Patient Engagement:Digital outreach tools and automated adherence monitoring extend value-based contract reach beyond facility walls. Demand concentrates among Medicare Advantage plans seeking supplemental benefit differentiation through in-home touchpoints.
- Analytics:Risk stratification engines process claims and clinical data for real-time quality metric reporting. HIPAA compliance constraints limit cross-system data sharing despite API-driven interoperability advances.
- Quality Improvement:Clinical workflow redesign services align physician incentives with HEDIS and Star Rating benchmarks. Physician practice consolidation reduces the addressable market of independent entities capable of direct contracting.
By volume, Care Coordination leads. By growth pace, Patient Engagement is ahead.
Payment Model:
Cost tier stratification separates infrastructure-light shared savings arrangements from capital-intensive capitation models requiring actuarial reserves and downside risk tolerance.
- Accountable Care Organizations:CMS-mandated participation thresholds push hospital systems into risk-bearing entities spanning Medicare Shared Savings Program tracks. Downside risk exposure demands sophisticated data infrastructure that smaller physician groups cannot finance.
- Bundled Payments:Episode-based pricing for orthopedic and cardiac procedures attracts self-insured employers seeking cost predictability. Manufacturing and logistics employers in the Southeast negotiate directly with health systems, bypassing traditional intermediaries.
- Shared Savings Programs:One-sided risk models allow gradual provider transition from fee-for-service. CMS track selection determines quality reporting requirements and benchmark calculation methodologies.
- Capitation:Global per-member-per-month payments transfer full utilization risk to provider organizations. Privia Health and similar vendors compete through physician practice management tools sustaining these outpatient contracts.
By revenue concentration, Accountable Care Organizations dominate. By expansion velocity, Bundled Payments are climbing fastest.
End User:
Customer type determines contract complexity, with integrated delivery networks demanding enterprise-scale platforms and independent practices seeking modular, lower-commitment solutions.
- Hospitals:Health systems consolidate into regional ACOs capable of bearing downside risk across Medicare Advantage and traditional Medicare lines. Texas and Florida concentration creates demand spikes for bundled payment administration expertise.
- Physician Practices:Independent and employed physicians require incentive alignment tools linking quality metrics to reimbursement. Attrition among independent practices narrows the pool of entities entering direct capitated contracts.
- Insurance Providers:Medicare Advantage plans at Anthem and Centene deploy federated learning architectures for hospitalization prediction. Payer analytics engines compress intervention deployment windows to 72-hour horizons.
- Outpatient Clinics:Ambulatory surgery centers and specialty clinics seek episode-based pricing tools for procedural bundles. Site-of-care shift policies accelerate migration from inpatient to outpatient settings.
By contract volume, Hospitals anchor procurement. By platform sophistication requirements, Insurance Providers set the technical benchmark.
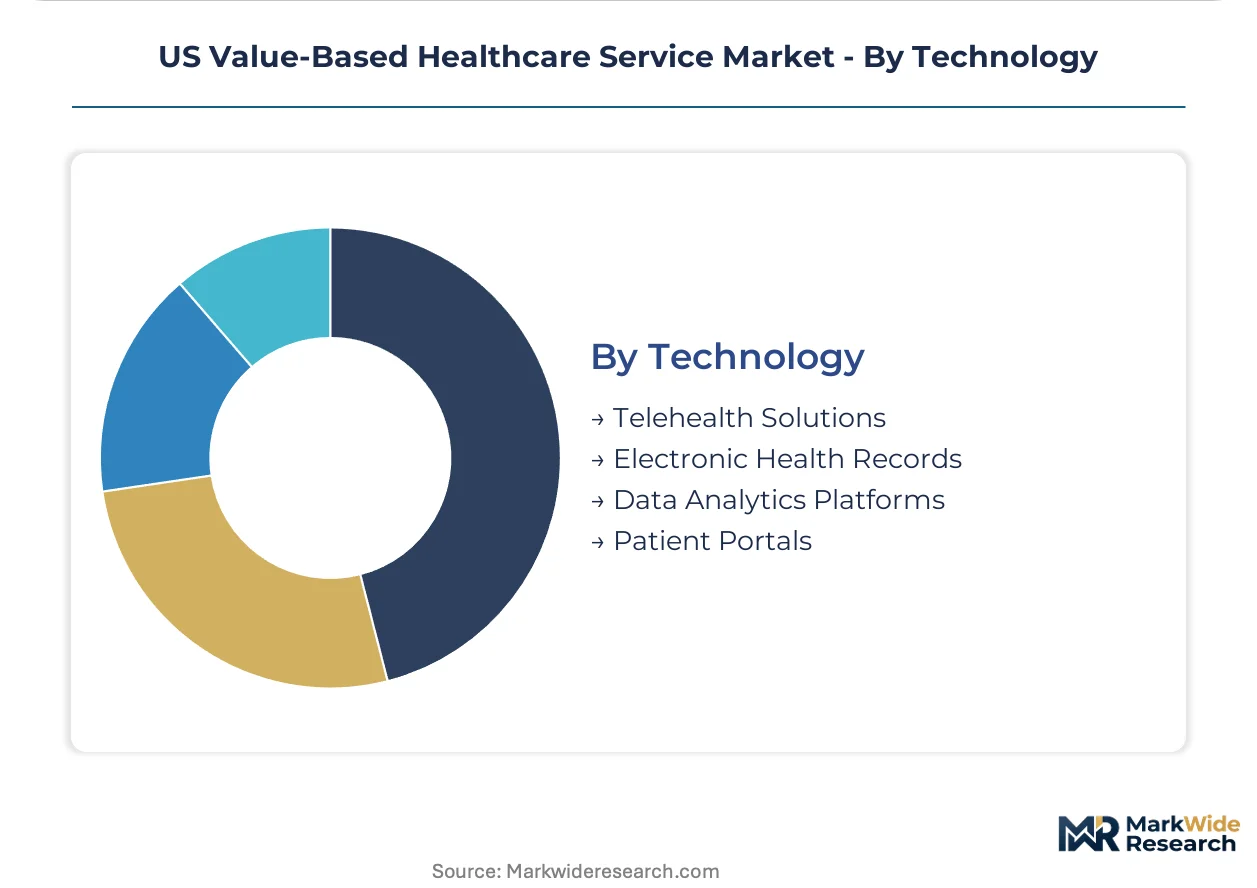
Technology:
Maturity curves separate legacy electronic health record architectures from cloud-native interoperability layers enabling real-time quality metric exchange.
- Telehealth Solutions:Remote monitoring and virtual visit platforms extend care coordination into patient residences. Medicare Advantage supplemental benefit flexibility permits reimbursement for in-home assessments previously excluded from facility-based contracts.
- Electronic Health Records:Cerner and Epic proprietary data architectures resist modular extraction without expensive middleware development. Technical debt burdens health systems attempting API-driven interoperability without full system replacement.
- Data Analytics Platforms:Predictive engines stratify population risk and identify care gaps for intervention targeting. FDA oversight of clinical decision support algorithms constrains how platforms integrate patient data for automated recommendations.
- Patient Portals:Consumer-facing interfaces enable self-service access to quality metrics and cost transparency tools. Adoption lags among Medicare populations with lower digital literacy rates.
By installed base, Electronic Health Records retain dominance. By investment trajectory, Data Analytics Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare Advantage enrollment density and hospital system consolidation patterns concentrate value-based contract demand across distinct US sub-regions. State-level Medicaid expansion decisions and CMS regional office enforcement priorities further fragment procurement behaviors.
Texas
Houston and Dallas-Fort Worth hospital systems absorb the largest share of bundled payment administration contracts as Medicare Advantage penetration exceeds national averages. CMS regional office oversight of Medicare Shared Savings Program tracks shapes provider risk-bearing timelines. The Texas Medical Center anchors specialty ACO formation for cardiac and orthopedic episodes.
Florida
Retirement corridor demographics in Tampa and Miami metropolitan areas drive Medicare Advantage plan competition for supplemental benefit differentiation. The state's Agency for Health Care Administration monitors Medicaid managed care quality metrics that intersect with value-based reporting requirements. Jacksonville health systems concentrate procurement of in-home assessment services.
California
Los Angeles and San Francisco Bay Area integrated delivery networks pioneer capitation models for commercial employer populations alongside Medicare lines. Department of Managed Health Care regulations enforce prompt pay rules that compress value-based reconciliation cycles. Sacramento-area health systems test social determinants data integration with housing authority partnerships.
Northeast Corridor
Boston and New York City academic medical centers deploy federated learning architectures for population risk stratification across multi-hospital networks. State insurance exchange regulations in Massachusetts and New York mandate quality disclosure that accelerates provider reporting infrastructure investment. Philadelphia health systems consolidate into regional ACOs capable of bearing downside risk across state lines.
Midwest
Chicago and Detroit hospital systems retrofit legacy Epic installations with API-driven interoperability layers for real-time quality metric exchange. Illinois and Michigan Medicaid expansion programs create dual-eligible populations requiring coordinated Medicare-Medicaid value-based contract structures. Cleveland Clinic anchors cardiac episode bundled payment design for employer-sponsored plans.
US Value-Based Healthcare Service Market Key Industry Players
Channel-controlling players compete with product-specialist players for contract administration margins across Medicare Advantage and employer-sponsored lines. Consolidation around vertically integrated health plans with captive analytics capabilities has compressed standalone vendor addressable market. Three archetypes dominate: payer-affiliated platforms, physician practice management vendors, and independent analytics specialists. M&A activity concentrates on care coordination capabilities, while strategic partnerships target EHR interoperability middleware.
Within the payer-affiliated tier, UnitedHealth Group exemplifies vertical integration of analytics engines with risk-bearing network administration. Among physician practice management specialists, Privia Health occupies a position linking outpatient incentive alignment tools to capitated contract sustainability. Signify Health, Inc. represents the independent analytics archetype, anchoring in-home assessment services that extend value-based reach beyond facility walls.
| Leading Market Players |
|---|
| Change Healthcare |
| Privia Health |
| UnitedHealth Group |
| Koninklijke Philips N.V. |
| Deloitte |
| Humana |
| Signify Health, Inc. |
| Cigna |
| McKesson Corporation |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure concentration among Amazon Web Services, Microsoft Azure, and Google Cloud Platform in US data centers anchors margin capture downstream at the care coordination platform layer. Hospital systems negotiating SaaS contracts for value-based administration tools face asymmetric pricing power against these hyperscale providers.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate Medicare Advantage plan procurement of analytics services. Three-tier pricing structure across enterprise, mid-market, and practice-level deployments differentiates by data volume and API call frequency. Pricing pressure stems from CMS-mandated quality reporting compression timelines that squeeze implementation budgets. Independent physician practices exhibit highest price sensitivity; integrated delivery networks absorb premium tiers for enterprise interoperability.
Supply Chain Analysis
Tariff exposure between US and China for semiconductor components constrains edge computing hardware availability for in-home assessment devices. Supply draws from Taiwan for advanced chips, Mexico for final assembly, and domestic US facilities for FDA-regulated medical-grade sensors. Single-source vulnerability concentrates in specialized GPU architectures for federated learning workloads. Distribution runs through GPO contracts and direct health system procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial talent scarcity constrains provider capacity to reconcile clinical quality metrics with total cost benchmarks in real-time environments. Organizations that secure this capability gap gain decisive contract administration advantages.
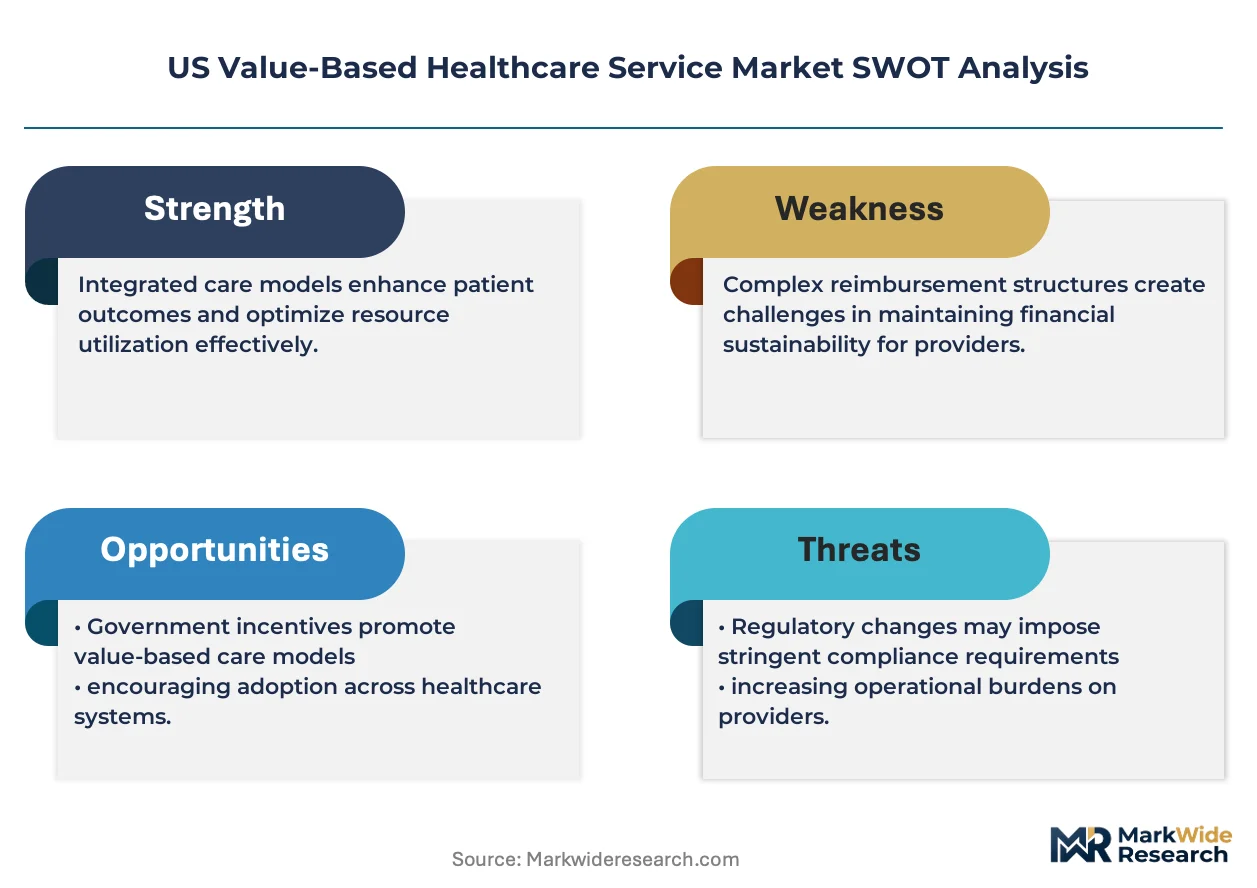
For Market Incumbents: Build data moat depth through federated learning architectures that stratify risk without centralized data repositories. Anchor defensive positioning by acquiring nurse navigator staffing networks before competitors lock in exclusive arrangements. Counter the threat of cloud-native entrants by embedding analytics engines directly into Epic and Cerner workflows through API middleware investments. For New Entrants and Emerging Players: Build out in-home assessment service footprints in Jacksonville and Tampa where Medicare Advantage supplemental benefit flexibility permits reimbursement expansion. The employer-sponsored bundled payment segment for orthopedic episodes offers lowest competitive density. Pursue direct contracting with self-insured logistics employers in the Southeast bypassing traditional payer intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across capitation model infrastructure requiring actuarial reserves and downside risk tolerance. Long-term viability favors platforms with captive physician practice management capabilities. Target acquisition archetypes: care coordination vendors with nurse navigator networks. Monitor CMS finalization of mandatory ACO participation timelines as inflection signal for infrastructure demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Deployment | Anthem and Centene compress hospitalization prediction windows to 72 hours without centralized data repositories. |
| Physician Practice Management Acquisition | Privia Health sustains capitated outpatient contracts through incentive alignment tools linking quality metrics to reimbursement. |
| In-Home Assessment Service Expansion | Signify Health extends value-based contract reach beyond facility walls into Medicare Advantage supplemental benefits. |
| API-Driven EHR Interoperability Investment | Texas and Florida hospital systems retrofit legacy Epic installations for real-time quality metric exchange. |
| Social Determinants Data Partnership | Sacramento-area health systems integrate housing authority datasets to refine risk adjustment models capturing non-clinical cost drivers. |
Research Approach
A spread of perspectives from CMS policy officers, Medicare Advantage plan actuaries, hospital system CFOs, and physician practice administrators converged on the working assumptions. Primary interviews combined with secondary validation against CMS Medicare Shared Savings Program track data, hospital procurement databases, and GPO contracts. SEC filings from UnitedHealth Group and Privia Health anchored top-down revenue triangulation against bottom-up contract volume estimates.
Demand-supply-balance framing modeled Medicare Advantage enrollment trajectories against actuarial talent availability and cloud infrastructure capacity constraints. Segmentation dimensions spanned payment model, service type, end-user archetype, and technology deployment mode. CAGRs derived from regression analysis of historical contract value growth rates adjusted for CMS policy acceleration effects. Federated learning adoption curves and social determinants data integration timelines supplied healthcare-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated health plans would shift outcomes through accelerated physician practice consolidation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Global Contract Sterilization Market