
 Global Value Based Healthcare Services Market | 2026-2036
Global Value Based Healthcare Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Value Based Healthcare Services Market Foresight
Hospital capacity planning in the United States is shifting toward risk-based contracting models that tie reimbursement to patient outcomes. Epic Systems dominates the electronic health record infrastructure that enables outcome tracking across integrated delivery networks. Cerner (Oracle) leverages cloud-native architecture to support population health analytics for multi-hospital systems. Athenahealth competes in the ambulatory segment with revenue cycle tools calibrated to value-based payment workflows.
Value Based Healthcare Services encompass clinical and administrative functions that align provider compensation with measured patient outcomes rather than service volume. Core technical specifications include HEDIS quality metrics, risk-adjusted mortality indices, and episode-based cost benchmarks that evaluate care efficiency across defined treatment periods. Population Health Management leads in revenue contribution as payers demand stratification tools for chronic disease cohorts. Telehealth delivery models represent the fastest-expanding segment as remote monitoring platforms integrate biometric feeds into risk-scoring algorithms. Patient Engagement remains comparatively mature, with margin pools concentrating in platforms that combine wearable data with personalized care navigation.
FDA digital health guidance and CMS Medicare Advantage star ratings shape product standards for clinical decision support tools. HIPAA interoperability rules and EU GDPR constrain cross-border health data flows, forcing vendors to architect region-specific cloud deployments. Stakeholders must monitor how NHTSA-equivalent patient safety frameworks migrate into outpatient settings as liability models evolve under risk-bearing contracts.
Market Dynamics
Provider risk-bearing arrangements are compressing reimbursement timelines and forcing hospital systems to restructure care delivery around episode-based cost accountability. CMS Medicare Shared Savings Program rules and commercial ACO contracts accelerate this shift toward outcome-contingent compensation.
Growth Catalysts
- Statutory health insurer pilots in Germany:Outcome-based reimbursement for orthopedic procedures creates demand templates that commercial payers replicate across European markets.
- Remote patient monitoring platforms:Biometric feed integration into risk-scoring algorithms enables continuous outcome measurement outside acute settings.
- HEDIS quality metrics standardization:Payer reporting requirements drive provider investment in population health management infrastructure.
Market Restraints
- HIPAA interoperability constraints:Cross-border health data flows face architectural limitations that force redundant region-specific cloud deployments.
- EU GDPR compliance costs:Data localization requirements impose structural overhead on multi-national platform vendors.
- Legacy EHR fragmentation:Proprietary data formats in existing hospital systems impede seamless outcome tracking across integrated delivery networks.
Strategic Opportunities
- Telehealth delivery convergence:Wearable data streams combined with personalized care navigation platforms open margin pools in patient engagement.
- CMS Medicare Advantage star ratings:Quality-based bonus payments create procurement pressure for clinical decision support tools that improve measurable outcomes.
- Statutory health insurance in Germany:Outcome-based pilots for chronic disease management expand addressable market for risk-stratification tools.
Industry Challenges
- Clinical informatics talent scarcity:Shortage of specialists capable of designing risk-adjusted mortality indices and episode-based cost benchmarks constrains implementation velocity.
- Multi-hospital system integration complexity:Cloud-native population health analytics require reconfiguration of existing revenue cycle workflows across disparate facility footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Value Based Healthcare Services Market |
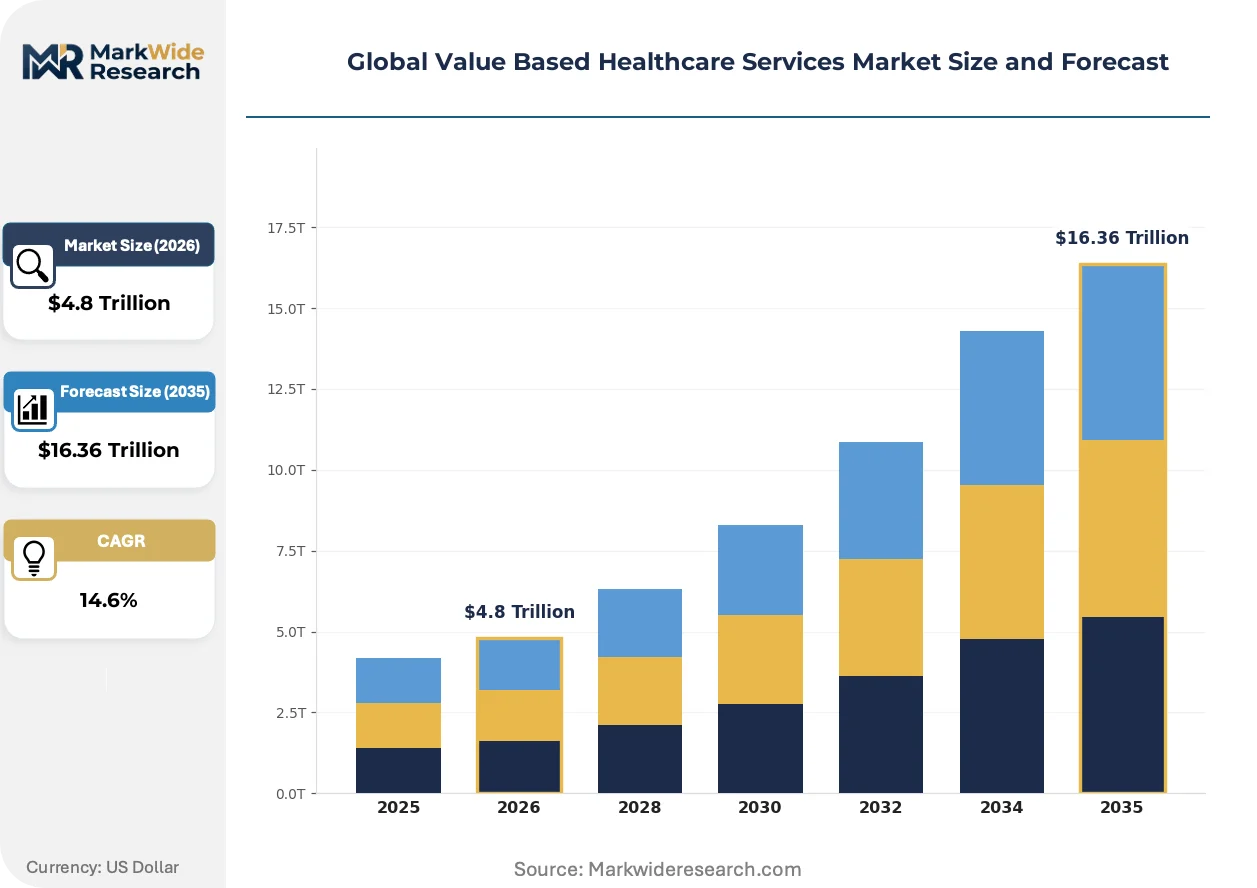
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $16.36 Trillion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Care Coordination, Population Health Management, Risk Adjustment, Outcome Measurement, Patient Engagement Therapy Area: Cardiology, Oncology, Orthopedics, Neurology, Endocrinology End User: Hospitals, Ambulatory Centers, Physician Groups, Payers, Long-term Care Facilities Delivery Model: In-person Consulting, Telehealth, Remote Monitoring, Mobile Health Applications, Home Care Services |
| Companies Covered | Cerner (Oracle), CareCloud, Persivia, GE HealthCare Technologies, HealthEdge, Innovaccer, Epic Systems, Thermo Fisher Scientific, Athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Value Based Healthcare Services Market Shifts & Advancements
Artificial intelligence and remote sensing technologies are compressing the gap between clinical encounter and outcome measurement. This convergence enables real-time risk adjustment that traditional claims-based models cannot replicate.
Machine learning algorithms applied to continuous biometric feeds are unifying previously siloed data streams from wearables, EHRs, and pharmacy systems. Integrated delivery networks in the United States deploy these tools to flag deterioration before acute events. The technology is unifying risk scoring across ambulatory and inpatient settings into single episode-based accountability frameworks.
EU GDPR data portability requirements are forcing health technology vendors to architect modular consent management systems. This regulatory pressure accelerates investment in privacy-preserving analytics that process sensitive health data without cross-border transfer. Vendors serving German statutory health insurers respond by localizing computation within national boundaries.
Hospital procurement departments now require outcome guarantees in bundled payment negotiations with commercial payers. Traditional fee-for-service contracts lose share to arrangements tying reimbursement to HEDIS quality metric performance. This pattern concentrates in United States markets where CMS Medicare Shared Savings Program participation creates competitive pressure for risk-bearing capability.
Global Value Based Healthcare Services Market Segmentation
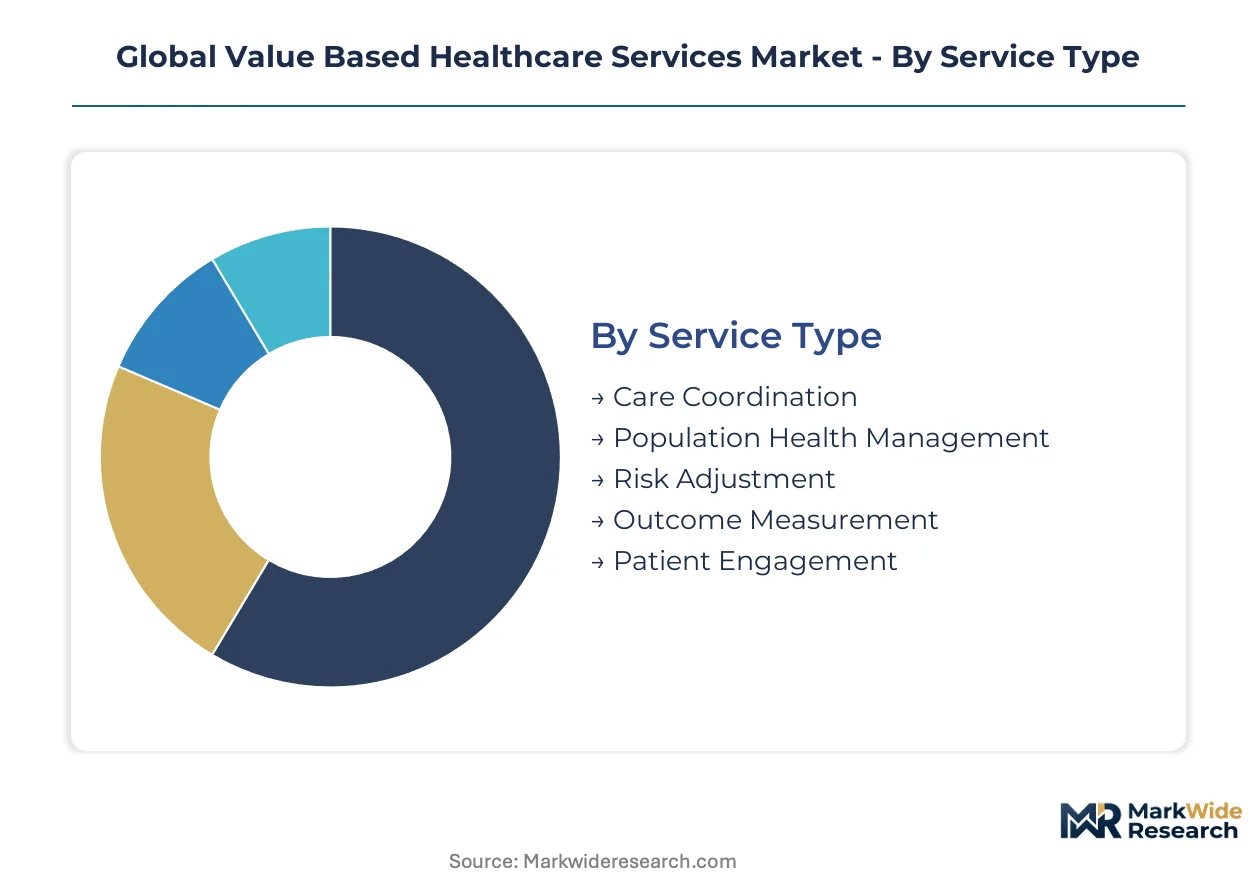
Value Based Healthcare Services require granular segmentation because reimbursement models, regulatory requirements, and technology infrastructure vary dramatically across service functions, clinical domains, and care settings. Buyers prioritize different capabilities depending on whether they seek population-level risk stratification or episode-specific outcome accountability.
Service Type:
Provider organizations select service types based on their maturity in risk-bearing contracts and existing health IT infrastructure.
- Population Health Management:Stratification tools for chronic disease cohorts combine claims data with social determinants to identify high-risk patients. Demand concentrates in United States integrated delivery networks where CMS Medicare Shared Savings Program participation requires comprehensive registry management. HEDIS quality metrics standardization drives platform investment across multi-hospital systems.
- Patient Engagement:Platforms integrating wearable biometric feeds with personalized care navigation capture margin pools as payers seek continuous rather than episodic member touchpoints. German statutory health insurers pilot these tools for diabetes and cardiovascular cohorts under outcome-based reimbursement pilots. GDPR-compliant consent architectures constrain vendor deployment strategies across European markets.
- Care Coordination:Transition management between acute and post-acute settings reduces readmission penalties under CMS Hospital Readmissions Reduction Program rules.
- Risk Adjustment:Hierarchical condition category scoring engines enable accurate premium calibration for Medicare Advantage plans.
- Outcome Measurement:Episode-based cost benchmarking platforms evaluate care efficiency across defined treatment periods for bundled payment contracts.
Population Health Management leads volumes today; Patient Engagement is gaining share fastest.
Therapy Area:
Therapy-specific segmentation reflects varying feasibility of outcome quantification and differential reimbursement pressure from public and private payers.
- Orthopedics:Episode-based cost accountability is technically straightforward given procedural homogeneity and defined recovery trajectories. German statutory health insurers have made this the pilot domain for outcome-based reimbursement, creating demand templates that commercial payers replicate. Prosthetic implant registries in Sweden and Australia provide longitudinal outcome benchmarks that enable risk-sharing contracts.
- Oncology:Value-based arrangements face complexity from heterogeneous disease pathways and novel therapy pricing. United States commercial payers experiment with indication-specific outcomes rather than drug-specific reimbursement. FDA accelerated approval pathways create tension between rapid access and evidence generation for outcome guarantees.
- Cardiology:Remote monitoring of implantable devices enables continuous outcome measurement outside acute settings.
- Endocrinology:Diabetes management platforms integrate continuous glucose monitor data with pharmacy claims for comprehensive risk scoring.
- Neurology:Functional outcome measurement for stroke and Parkinson's disease remains less standardized than surgical specialties.
Orthopedics dominates current contract volume; Oncology shows the steepest expansion trajectory as immuno-oncology pricing pressures intensify.
End User:
End-user categories differ in capital availability, risk-bearing appetite, and legacy system constraints that shape procurement priorities.
- Hospitals:Integrated delivery networks in the United States deploy enterprise population health analytics across multi-facility footprints. Epic Systems and Cerner infrastructure investments create path dependency in vendor selection. Bundled payment negotiations with commercial payers now require outcome guarantees that force restructuring of care delivery around episode accountability.
- Payers:Medicare Advantage organizations procure clinical decision support tools to improve star ratings and capture quality bonus payments. Risk adjustment accuracy directly affects revenue adequacy for chronic disease enrollees. German statutory health insurers pilot outcome-based models that shift procurement toward stratification platforms.
- Ambulatory Centers:Surgery centers seek episode-based benchmarking tools for bundled payment participation.
- Physician Groups:Independent practices prioritize revenue cycle tools calibrated to value-based payment workflows.
- Long-term Care Facilities:Skilled nursing facilities face readmission penalty exposure that drives care transition investment.
Hospitals anchor procurement spending; Payers are expanding fastest as Medicare Advantage enrollment climbs.
Delivery Model:
Delivery model selection reflects workforce availability, patient acuity, and reimbursement parity between virtual and in-person services.
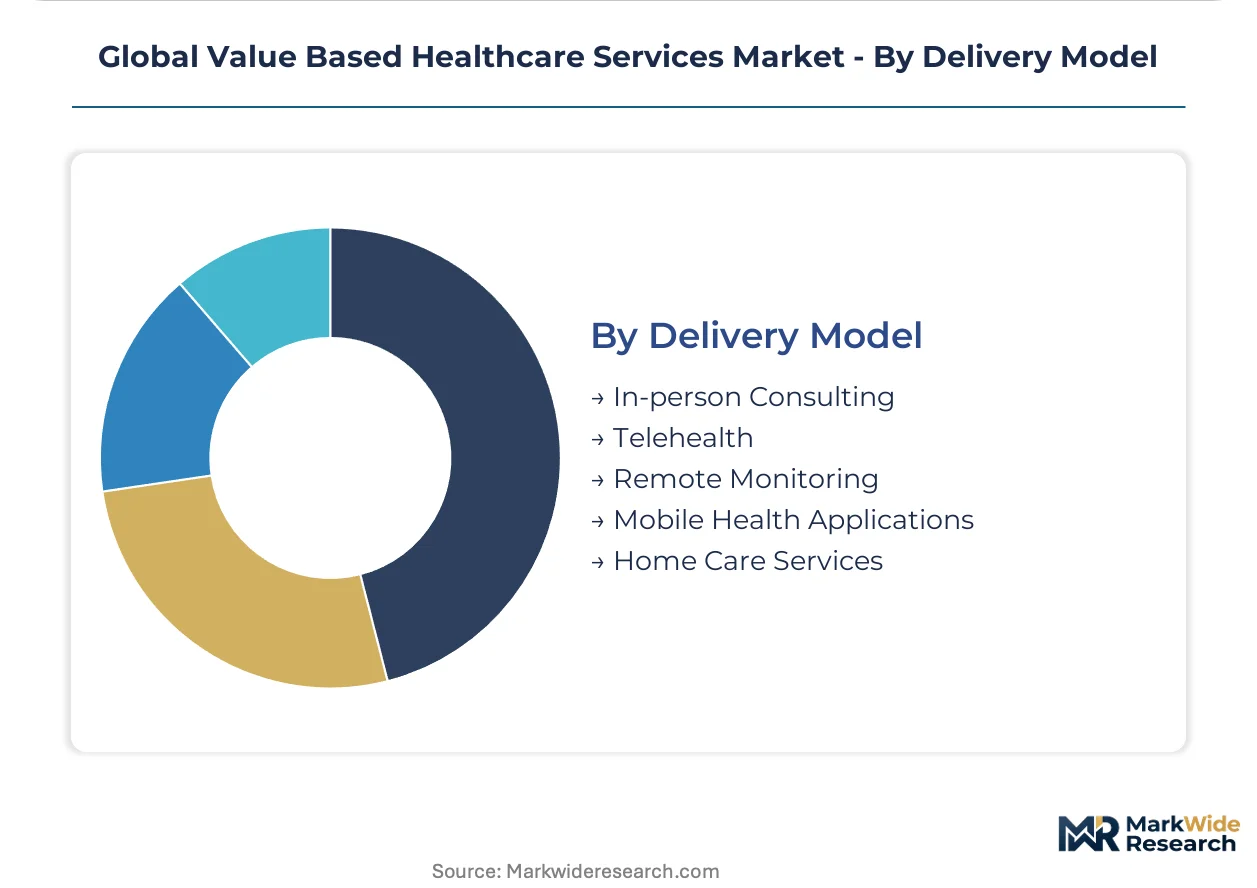
- Telehealth:Synchronous video platforms integrate with asynchronous remote monitoring for hybrid chronic disease management. United States Medicare telehealth flexibilities extended through congressional action sustain reimbursement parity that drives platform investment. Biometric feed integration into risk-scoring algorithms enables continuous outcome measurement outside traditional care settings.
- Remote Monitoring:Continuous data streams from wearables and implantables unify risk scoring across ambulatory and inpatient episodes. Machine learning algorithms applied to these feeds flag deterioration before acute events. FDA digital health guidance on software as a medical device shapes product development standards.
- In-person Consulting:Care coordination remains dependent on face-to-face encounters for complex multi-morbidity patients.
- Mobile Health Applications:Patient-facing tools for medication adherence and symptom tracking support self-management programs.
- Home Care Services:Post-acute nursing and therapy services complete episode-based accountability frameworks.
Telehealth commands the largest current deployment base; Remote Monitoring is climbing the fastest as sensor technology and AI analytics converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies as GDPR compliance costs in Europe push health technology investment toward jurisdictions with clearer interoperability frameworks. United States HIPAA rules and CMS incentive structures attract platform development capital that might otherwise flow to European markets.
United States
Medicare Shared Savings Program participation and commercial ACO contract proliferation drive integrated delivery networks toward population health analytics procurement. CMS Medicare Advantage star ratings create direct procurement pressure for clinical decision support tools. Epic Systems and Cerner infrastructure investments concentrate in Wisconsin and Kansas City metro areas, anchoring vendor ecosystems around established EHR footprints.
Germany
Statutory health insurer pilots for orthopedic outcome-based reimbursement establish demand templates that commercial payers replicate across European markets. Federal Joint Committee regulations on selective contracting enable risk-sharing arrangements previously blocked by fee-for-service statutes. Berlin and Munich health technology clusters localize computation within national boundaries to satisfy GDPR data portability requirements.
United Kingdom
NHS England long-term plan commitments to integrated care systems accelerate procurement of stratification tools for chronic disease cohorts. National Institute for Health and Care Excellence technology appraisals create outcome measurement standards that shape vendor product specifications. London and Greater Manchester integrated care boards pilot episode-based cost benchmarking for elective procedures.
China
National pilot programs for diagnosis-related group payment reform in tertiary hospitals create demand for cost-accountability infrastructure. National Medical Products Administration digital health guidance shapes software-as-a-medical-device standards for remote monitoring platforms. Shanghai and Beijing hospital clusters deploy AI-enabled risk scoring for diabetes and cardiovascular management under municipal value-based procurement pilots.
Australia
Prosthetic implant registries in Victoria and New South Wales provide longitudinal outcome benchmarks that enable risk-sharing contracts for orthopedic procedures. Therapeutic Goods Administration software guidance aligns with FDA digital health frameworks to reduce vendor compliance duplication. Sydney and Melbourne integrated care networks pilot bundled payment arrangements for joint replacement episodes.
Global Value Based Healthcare Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and modular consent management systems. The market structure consolidates around electronic health record incumbents with path-dependent customer relationships and fragmented specialized vendors addressing specific risk-bearing workflow gaps. Three archetypes dominate: integrated platform providers, population health analytics specialists, and revenue cycle workflow optimizers. M&A activity concentrates on acquiring clinical informatics talent and cloud-native technology stacks; strategic partnerships focus on biometric feed integration and wearable data platforms.
Among United States-based platform providers, Epic Systems, Cerner (Oracle), and Athenahealth exemplify distinct strategic positioning within value-based care infrastructure. Epic Systems represents the integrated delivery network anchor with enterprise population health deployment across multi-facility footprints. Cerner (Oracle) occupies the cloud-native migration path for hospital systems restructuring around episode accountability. Athenahealth sits within the ambulatory specialist tier with revenue cycle tools calibrated to value-based payment workflows.
| Leading Market Players |
|---|
| Cerner (Oracle) |
| CareCloud |
| Persivia |
| GE HealthCare Technologies |
| HealthEdge |
| Innovaccer |
| Epic Systems |
| Thermo Fisher Scientific |
| Athenahealth |
| Others |
Supply & Pricing Matrix
Cloud infrastructure licensing fees cascade through SaaS pricing tiers as health technology vendors pass hyperscaler cost volatility to provider buyers. HIPAA-compliant data center investments in the United States and GDPR-localized computation in Germany create regional cost premiums that stratify platform subscription rates.
Pricing Analysis
Distributor margins for population health analytics platforms compress as Epic Systems and Cerner pursue direct hospital system contracts. Subscription pricing stratifies across enterprise, mid-market, and ambulatory tiers based on EHR integration depth and risk-adjustment module sophistication. Cost compression in the mid-market tier intensifies because Athenahealth and CareCloud compete on revenue cycle automation bundling. Ambulatory physician groups exhibit highest price sensitivity; integrated delivery networks with CMS Medicare Shared Savings Program participation show lowest sensitivity due to outcome-contingent reimbursement upside.
Supply Chain Analysis
FDA 510(k) clearance and EU MDR certification gating constrain biometric sensor suppliers to established medical device manufacturers in the United States, Germany, and Switzerland. Cloud-native analytics platforms draw from AWS and Azure hyperscaler infrastructure, specialized clinical informatics labor pools, and wearable OEM hardware partnerships. Single-source vulnerability concentrates in EHR data integration layers where Epic and Cerner APIs control patient record access. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers for ambulatory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as provider risk-bearing contracts shift procurement toward outcome-guaranteed platform specifications. Demand tilts toward premium-tier population health analytics with embedded AI risk-scoring as Medicare Advantage star ratings intensify quality-based bonus competition.
For Market Incumbents: Anchor defensive positioning through backward integration into clinical informatics talent pipelines and captive development of modular consent architectures for GDPR compliance. Cloud-native migration pressure from Oracle Cerner threatens legacy installed-base retention. Priority lever rests on embedding population health modules directly into EHR workflows to increase switching costs. For New Entrants and Emerging Players: AI-enabled remote monitoring algorithms offer technology-first wedge into the patient engagement segment where wearable data integration remains technically fragmented. White-space concentrates in German statutory health insurer pilot programs for diabetes and cardiovascular cohorts. Go-to-market angle targets mid-size physician groups seeking revenue cycle tools calibrated to value-based payment workflows without Epic infrastructure dependency. For Investors and Strategic Acquirers: Consolidation pressure builds where clinical informatics talent scarcity constrains implementation velocity for risk-adjusted mortality index deployment. Long-term viability favors platforms with demonstrated CMS Medicare Advantage star rating improvement metrics and multi-hospital system referenceability. Acquisition target archetype: cloud-native population health specialists with HIPAA-compliant AWS GovCloud deployments. Signal to watch is German Federal Joint Committee expansion of selective contracting authority beyond orthopedic pilots.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic-integrated deployments anchor multi-facility population health contracts with outcome guarantees. |
| Software Companion Development | FDA-cleared algorithms for continuous glucose monitoring expand addressable diabetes management market. |
| Reimbursement Strategy | CMS Medicare Advantage star rating optimization drives clinical decision support procurement decisions. |
| CE Marking Pathway | EU MDR compliance enables German statutory health insurer pilot program participation. |
| Strategic Partnership | Biometric feed integration with Apple Health and Fitbit APIs unifies ambulatory risk scoring. |
Research Methodology
Multiple input streams — executive interviews with population health platform vendors, hospital purchasing committee discussions, and payer formulary director consultations — were reconciled against CMS Medicare data releases, FDA 510(k) clearance databases, and German Federal Joint Committee contracting records. Secondary validation drew from GPO contract repositories, hospital procurement databases, and EU GDPR enforcement actions. Bottom-up segment sizing triangulated against top-down reimbursement flow analysis across the analysis window.
Historical claims volume trajectories were cross-referenced against panel input from health system CFOs and Medicare Advantage plan actuaries. Segmentation dimensions modeled include service type, therapy area, end-user category, and delivery model complexity tier. CAGRs derived from reimbursement policy velocity and EHR infrastructure replacement cycles. Forecast inputs incorporated CMS Medicare Shared Savings Program participation thresholds and German statutory health insurer pilot expansion timelines.
The model holds under current CMS rulemaking continuity and stable HIPAA interoperability enforcement; deviation in Medicare Advantage star rating methodology or EU GDPR cross-border data flow restrictions would shift platform investment priorities. Forecasts reflect documented assumptions regarding telehealth reimbursement parity and cloud infrastructure cost trajectories. A model refresh is warranted upon material change in German Federal Joint Committee selective contracting authority or FDA software-as-medical-device guidance revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Medical Spa Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Long Term Care Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Hospice Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Medical Waste Disposal Services Market