
 Nutraceutical Contract Manufacturing Services Market | 2026-2036
Nutraceutical Contract Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Contract Manufacturing Services Market Analytics
Turnkey formulation and packaging services is decoupling product ownership from production expertise across the nutraceutical value chain. Catalent leverages integrated clinical-to-commercial pathways to anchor high-complexity biologic-nutrition hybrid projects. Lonza Group AG sustains leadership in probiotic strain encapsulation through dedicated fermentation infrastructure. Sirio Pharma differentiates via Asia-Pacific manufacturing scale combined with Western regulatory registration support.
Nutraceutical contract manufacturing services encompass third-party production of dietary supplements, functional foods, and wellness products under client branding, typically requiring cGMP-compliant facilities capable of handling moisture-sensitive actives, controlled-release matrices, and clean-label formulation constraints. The primary commercial purpose centers on converting R&D-stage concepts into shelf-stable, regulation-compliant finished goods without capital-intensive facility ownership. Probiotics commands premium unit economics due to cold-chain viability requirements and strain-specific stability protocols, while Powder delivery modes dominate volume throughput for bulk sports nutrition supply. E-commerce Retailers represent the fastest-growing end-user channel, driven by direct-to-consumer subscription models that demand flexible batch sizes and rapid label turnaround.
FDA registration requirements and NSF Certified facility audits shape baseline market access for US-focused contract manufacturers, while ISO Certification and GMP adherence operate as non-negotiable qualifiers for pharmaceutical company clients evaluating vendor qualification. The EU's novel food regulations and EFSA health claim substantiation requirements create parallel compliance burdens for European-bound production. Stakeholders must monitor how tightening adulteration enforcement and evolving NDI guidance reshape liability allocation between brand owners and their manufacturing partners.
Market Dynamics
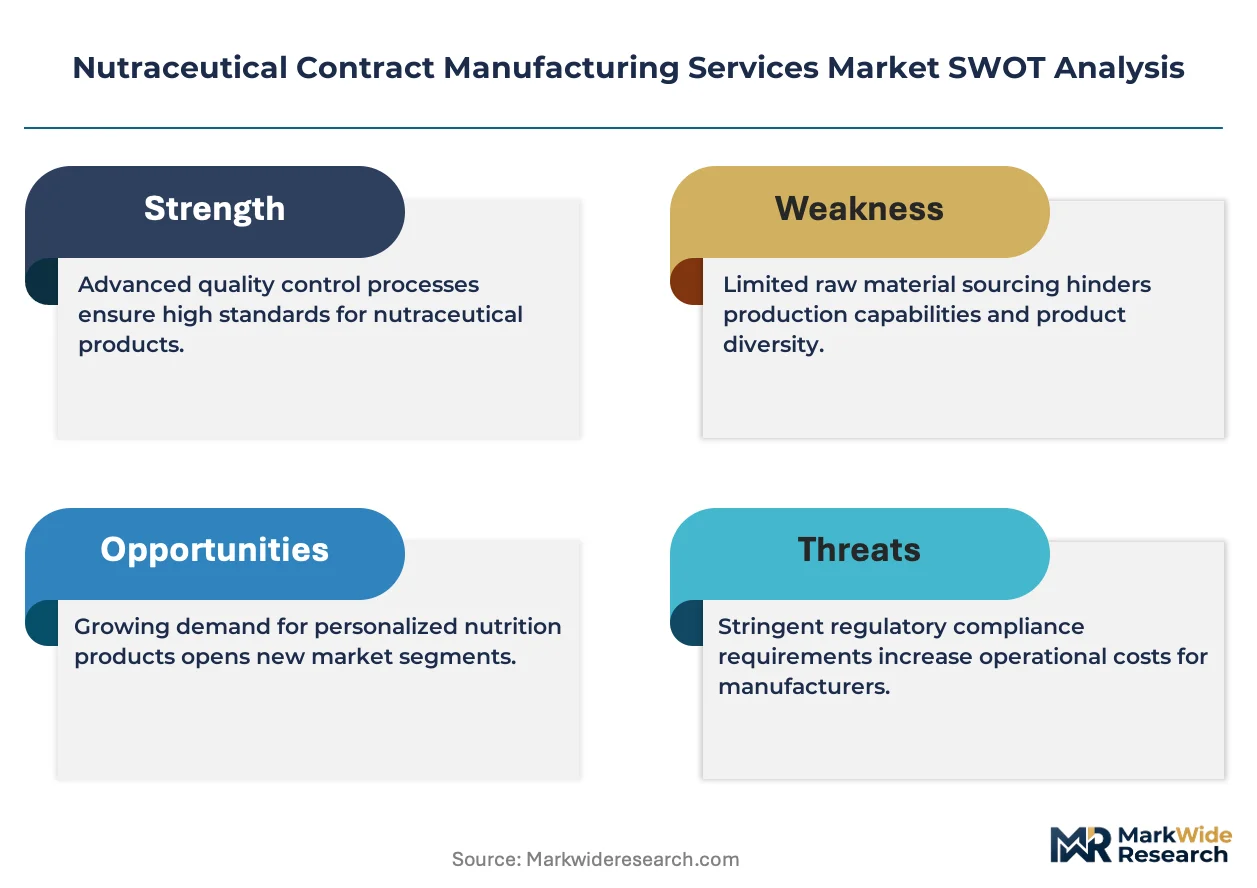
Third-party specialists now capture formulation complexity that sports nutrition brands previously kept in-house, driven by FDA's tightening New Dietary Ingredient notification requirements and the capital burden of cGMP-certified fermentation infrastructure for probiotic stability protocols.
Growth Catalysts
- NDI notification expansion:FDA's evolving guidance on novel dietary ingredients forces brand owners toward contract partners with dedicated regulatory affairs teams, consolidating demand among qualified manufacturers.
- Direct-to-consumer subscription velocity:E-commerce retailers require flexible batch sizes and rapid label turnaround, privileging contract manufacturers with digital workflow integration over captive facilities.
- Probiotic cold-chain infrastructure:Strain-specific viability requirements and encapsulation expertise concentrate demand among specialists with dedicated fermentation capacity and temperature-controlled logistics.
Market Restraints
- Aluminum and gelatin input volatility:Softgel and tablet coating materials face price instability from energy-intensive production processes, compressing margin buffers for high-volume contract manufacturers.
- Utah-California production cluster concentration:Dense geographic clustering of cGMP-certified facilities creates regional disruption risk from seismic events, water scarcity, or labor pool competition.
- EFSA health claim substantiation burden:European-bound production requires parallel clinical evidence packages that extend time-to-market and deter smaller brand clients from EU expansion.
Strategic Opportunities
- India's PLI scheme for nutraceuticals:Production-linked incentives for active pharmaceutical ingredient and formulation manufacturing attract contract manufacturers seeking cost-competitive fermentation scale.
- Biologic-nutrition hybrid convergence:Postbiotic peptides and engineered probiotic strains create premium service tiers for manufacturers with clinical trial-to-commercial pathways.
- Amazon and Shopify fulfillment integration:Direct-to-consumer platforms demand manufacturers with embedded packaging-for-fulfillment capabilities, displacing traditional wholesale-distributor relationships.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating simultaneous FDA NDI submissions, NSF facility audits, and EU novel food applications command premium compensation and extend client onboarding timelines.
- Legacy ERP integration friction:Brand owners' quality management systems often require manual data bridges to contractor batch records, creating compliance documentation gaps and audit trail vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Contract Manufacturing Services Market |
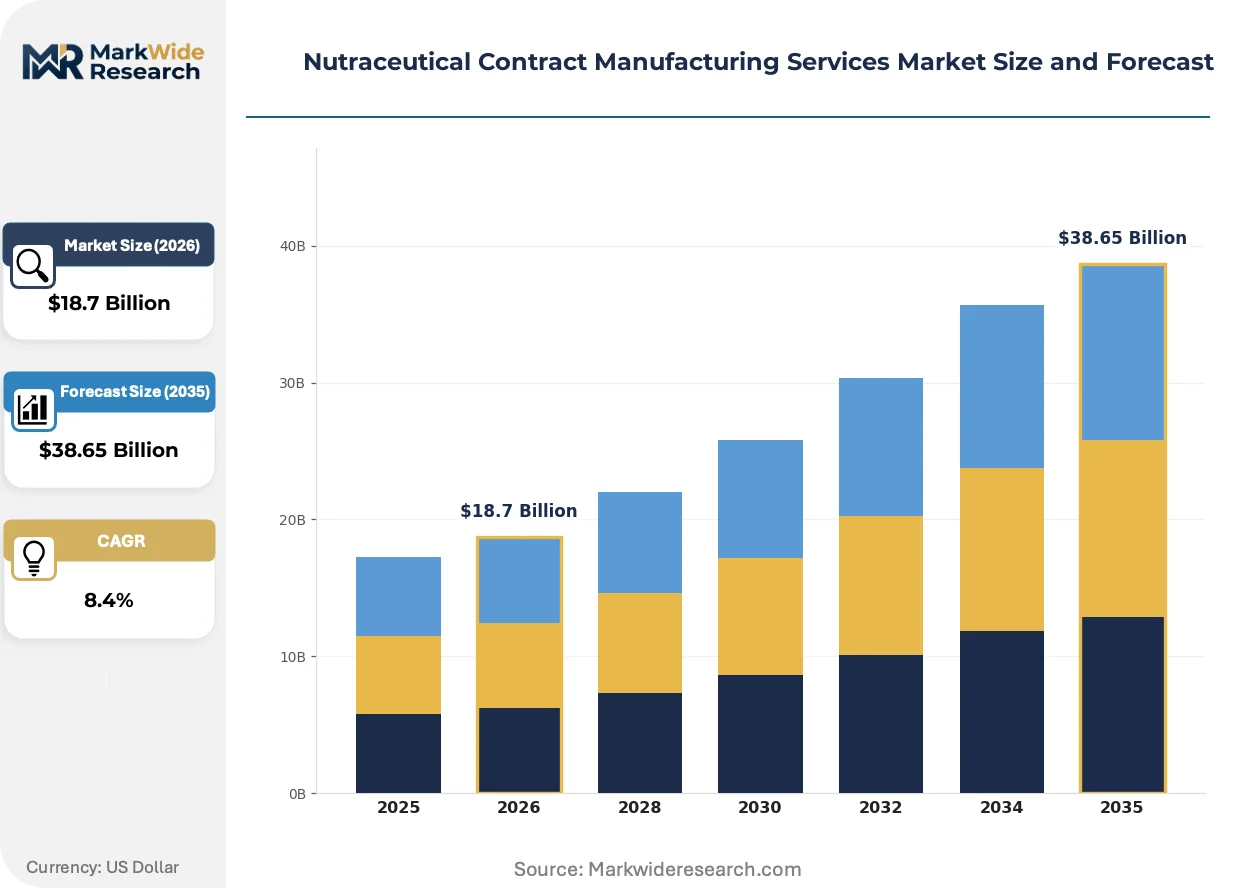
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Herbal Supplements, Probiotics, Weight Management Delivery Mode: Powder, Capsule, Liquid, Chewable End User: Pharmaceutical Companies, Health Food Stores, E-commerce Retailers, Fitness Centers Regulatory Compliance: GMP, ISO Certification, NSF Certified, FDA Registered |
| Companies Covered | Glanbia, Tishcon Corporation, Catalent, Aenova Group, Robinson Pharma, Lonza Group AG, Sirio Pharma, Thermo Fisher Scientific (Patheon), Royal DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Contract Manufacturing Services Market Evolving Landscape
Continuous manufacturing platforms and single-use bioreactor systems are compressing batch cycle times while clean-label formulation constraints are redrawing acceptable excipient boundaries across the contract manufacturing base.
Microencapsulation via spray-drying and fluid-bed coating is expanding into moisture-sensitive active protection for sports nutrition powders, enabling shelf-stable probiotic inclusion in ambient distribution channels. Functional beverage brands adopt these technologies at accelerating pace to bypass refrigerated supply chain requirements. The structural consequence is expanding into premium pricing tiers for manufacturers with validated stability protocols, compressing commodity powder margins.
REACH authorization requirements for novel excipients and the EU Green Deal's packaging waste directives are forcing reformulation of controlled-release matrices and tablet film coatings. Industrial consequence includes accelerated substitution of synthetic polymers with plant-derived alternatives. Sports nutrition and women's health segments bound for European distribution are most affected, responding with dual-track formulation development for EU and US specifications.
Subscription-model direct-to-consumer brands now consolidate procurement with single-source contract manufacturers capable of end-to-end service from stability testing to Amazon-compliant labeling. This consolidation displaces multi-vendor sourcing strategies common among traditional retail-channel brands. The shift is most visible among California and New York headquartered wellness startups targeting millennial and Gen-Z demographics with personalized nutrition stacks.
Nutraceutical Contract Manufacturing Services Market Segmentation
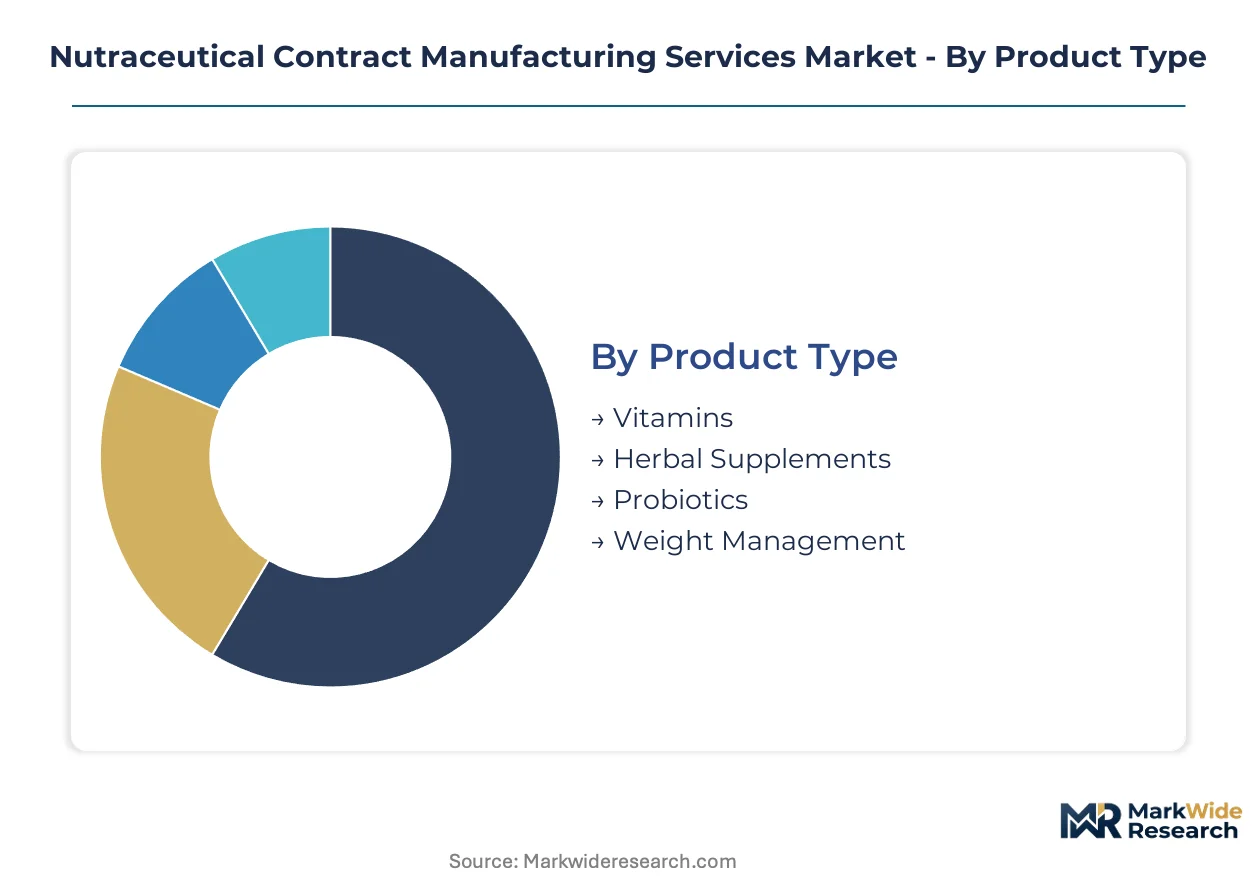
Contract manufacturing economics vary sharply across product categories and delivery formats. Manufacturers configure facility layouts, quality systems, and regulatory staffing around specific segment requirements rather than pursuing generic capacity.
Product Type:
Standardization dominates vitamin production while probiotic manufacturing demands bespoke fermentation and encapsulation infrastructure.
- Vitamins:High-volume synthesis and tableting operations support commodity pricing with established USP monograph testing protocols. Demand concentrates among mass-market retailers and institutional buyers in the United States, where cGMP compliance costs are amortized across enormous batch sizes.
- Probiotics:Strain-specific viability requirements and cold-chain logistics create premium service tiers. Manufacturing concentrates with specialists possessing dedicated fermentation capacity in California and Utah, driven by direct-to-consumer brands seeking shelf-stable ambient distribution.
- Herbal Supplements:Botanical sourcing complexity and adulteration testing burdens shape vendor qualification.
- Weight Management:Thermogenic actives and appetite suppressants face heightened FDA scrutiny on structure-function claims.
Most installed capacity flows through Vitamins. Expansion is steepest in Probiotics.
Delivery Mode:
Volume economics favor powder formats while margin capture concentrates in specialized encapsulation and liquid bottling.
- Powder:Bulk sports nutrition supply dominates throughput with flexible batch sizing for subscription-model brands. E-commerce retailers in California and New York drive demand for rapid label turnaround and Amazon-compliant packaging configurations.
- Capsule:Two-piece hardshell and softgel technologies accommodate moisture-sensitive actives with modified-release architectures. Pharmaceutical company clients in the United States prioritize NSF Certified facilities with validated dissolution profiles.
- Liquid:Functional beverage brands seek aseptic filling and hot-fill alternatives to refrigerated distribution.
- Chewable:Palatability masking and stability testing extend development timelines for pediatric and senior formulations.
Unit margins peak in Capsule manufacturing. Volume throughput concentrates in Powder.
End User:
Channel requirements diverge between compliance-heavy pharmaceutical procurement and velocity-driven direct-to-consumer fulfillment.
- E-commerce Retailers:Subscription models and personalized nutrition stacks demand flexible MOQs and digital workflow integration. Wellness startups headquartered in California and New York consolidate procurement with single-source manufacturers capable of end-to-end service from stability testing to Amazon-compliant labeling.
- Pharmaceutical Companies:Stringent vendor qualification and audit protocols privilege manufacturers with ISO Certification and established quality management systems. FDA registration and NSF facility audits operate as baseline qualifiers for contract awards.
- Health Food Stores:Regional distribution networks and co-op buying structures favor mid-sized manufacturers with organic certification capabilities.
- Fitness Centers:Private-label protein and pre-workout formulations prioritize rapid product iteration and flavor customization.
Procurement consolidation is most advanced among E-commerce Retailers. Pharmaceutical Companies impose the steepest qualification barriers.
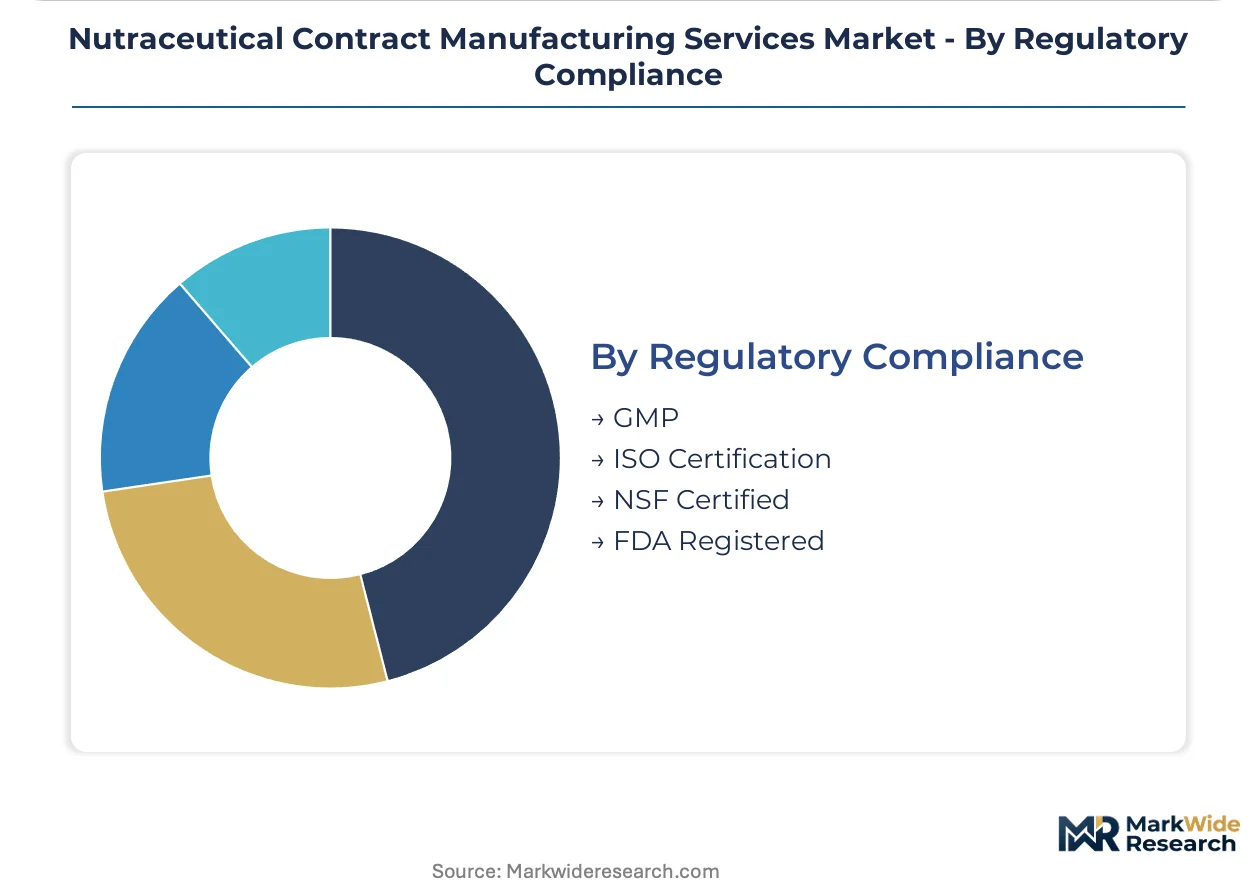
Regulatory Compliance:
Certification tier directly determines addressable customer segments and pricing power.
- FDA Registered:Baseline market access for US-focused manufacturers with drug establishment registration and NDI notification capabilities. Brand owners outsource complex regulatory submissions to contract partners with dedicated affairs teams.
- NSF Certified:Athletic banned-substance testing and GMP for Sport protocols unlock sports nutrition and professional team supply contracts. Facilities in Utah and California cluster around this certification tier to serve performance nutrition brands.
- GMP:Fundamental quality system requirements with facility inspections and documentation standards.
- ISO Certification:International quality management standards supporting pharmaceutical and export-oriented production.
Customer stickiness is strongest at FDA Registered tier. NSF Certified capacity commands the highest service premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States contract manufacturers command premium pricing for cGMP-certified capacity while Indian producers leverage fermentation scale under government incentive schemes. Geographic clustering of qualified facilities creates divergent risk-reward profiles across major supply bases.
United States
Direct-to-consumer subscription brands and pharmaceutical company outsourcing drive demand concentration. FDA's evolving NDI notification requirements and NSF Certified facility audits shape baseline market access. California and Utah host dense clusters of cGMP-certified production facilities serving e-commerce retailers with rapid label turnaround capabilities.
India
Cost-competitive fermentation scale and active pharmaceutical ingredient expertise attract contract manufacturers seeking probiotic production capacity. The PLI scheme for nutraceuticals provides production-linked incentives for formulation manufacturing. Maharashtra and Gujarat industrial corridors anchor expanding dedicated fermentation infrastructure for Western regulatory registration support.
Germany
Pharmaceutical-grade quality systems and precision encapsulation technologies serve premium European brand owners. EFSA health claim substantiation requirements and REACH authorization for novel excipients create parallel compliance burdens. Bavaria and Baden-Württemberg concentrate specialized manufacturing serving dual EU-US specification requirements.
Switzerland
Clinical trial-to-commercial pathways and biologic-nutrition hybrid convergence attract high-complexity projects. Swissmedic regulations and precision fermentation expertise support premium service tiers. Basel and Zurich regions anchor integrated development capabilities for engineered probiotic strains and postbiotic peptides.
China
Asia-Pacific manufacturing scale combines with domestic brand owner consolidation for regional supply security. NMPA dietary supplement regulations and GB standards for functional foods shape facility qualification. Yangtze River Delta and Pearl River Delta clusters concentrate encapsulation and powder processing capacity for export-oriented production.
Nutraceutical Contract Manufacturing Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated clinical-to-commercial pathways commanding premium positioning against commodity powder processors. The vendor base organizes around three strategic archetypes: fermentation-scale probiotic specialists, integrated pharmaceutical-nutrition hybrids, and regional scale players with Western regulatory registration support. Dominant competitive moves include geographic expansion into cost-competitive jurisdictions and portfolio diversification toward biologic-nutrition hybrid convergence.
Within the integrated pharmaceutical-nutrition tier, Catalent and Thermo Fisher Scientific (Patheon) occupy positions exemplifying clinical trial-to-commercial pathway capabilities. Lonza Group AG anchors the fermentation-specialist archetype with dedicated infrastructure for strain-specific viability protocols. Sirio Pharma represents the Asia-Pacific scale model combining regional manufacturing with Western regulatory affairs support.
| Leading Market Players |
|---|
| Glanbia |
| Tishcon Corporation |
| Catalent |
| Aenova Group |
| Robinson Pharma |
| Lonza Group AG |
| Sirio Pharma |
| Thermo Fisher Scientific (Patheon) |
| Royal DSM |
| Others |
Value Network & Pricing Analysis
Aluminum and gelatin input volatility propagates through softgel and tablet coating production into compressed margin buffers for high-volume contract manufacturers serving sports nutrition brands. This cost pressure concentrates most acutely among commodity powder processors lacking encapsulation expertise to command premium service tiers.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for fermentation-scale probiotic manufacturing while California and Utah cGMP-certified facilities maintain premium positioning through NSF Certified capacity scarcity. Three-tier pricing structure across premium, standard, and economy levels separates strain-specific viability protocols from commodity vitamin tableting and generic powder processing. Pricing pressure stems from energy-intensive aluminum and gelatin production costs that compress margins for high-volume softgel manufacturers. Pharmaceutical company clients exhibit lowest price sensitivity due to stringent vendor qualification requirements, while fitness center private-label brands face acute cost compression.
Supply Chain Analysis
Direct-to-brand channels handle subscription-model demand from California and New York wellness startups requiring rapid label turnaround and Amazon-compliant packaging configurations. Manufacturing capacity concentrates in the United States, India, and China, with strain-specific fermentation expertise anchored in Utah-California clusters and cost-competitive scale emerging in Maharashtra-Gujarat corridors. Raw material dependencies center on aluminum for tablet coatings, gelatin for softgel encapsulation, and specialized probiotic strains requiring cold-chain viability protocols. Single-source vulnerability runs through dense geographic clustering of cGMP-certified facilities exposed to seismic disruption and water scarcity. Distribution runs through direct-to-consumer fulfillment integration displacing traditional wholesale-distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutraceutical contract manufacturing services market compounds steadily as direct-to-consumer subscription velocity locks in recurring demand for flexible batch production. Outsourcing penetration among sports nutrition brands and pharmaceutical companies deepens the addressable base.
For Market Incumbents: Acquire dedicated fermentation infrastructure and regulatory affairs talent pools to defend against emerging India-based competitors leveraging PLI scheme cost advantages. Prioritize NSF Certified capacity additions in Utah and California to maintain premium positioning as subscription-model brands consolidate procurement with single-source partners. Backward integration into strain-specific probiotic development creates differentiation from commodity powder processors. For New Entrants and Emerging Players: Microencapsulation technology via spray-drying and fluid-bed coating offers white-space entry into moisture-sensitive active protection for ambient distribution channels. Target functional beverage brands seeking to bypass refrigerated supply chain requirements through validated stability protocols. India's PLI scheme provides the most penetrable geography for cost-competitive fermentation scale with Western regulatory registration support. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs talent scarcity and legacy ERP integration friction extend client onboarding timelines for smaller manufacturers. Long-term viability favors contract manufacturers with integrated clinical-to-commercial pathways serving biologic-nutrition hybrid convergence. Watch for FDA NDI notification guidance tightening as the inflection signal accelerating demand toward qualified manufacturers with dedicated compliance teams.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Expansion | Dedicated FDA NDI submission teams attract brand owners facing notification complexity. |
| Probiotic Fermentation Infrastructure | Cold-chain viability protocols and strain-specific expertise unlock premium service tiers. |
| Direct-to-Consumer Fulfillment Integration | Amazon-compliant labeling and packaging capabilities displace wholesale-distributor relationships. |
| Microencapsulation Technology Investment | Spray-drying and fluid-bed coating enable shelf-stable probiotic inclusion in ambient channels. |
| India Manufacturing Footprint | PLI scheme incentives reduce cost base for Western regulatory registration support. |
Research Methodology
Bottom-up e-commerce retailer and pharmaceutical company demand modeling reconciled against top-down cGMP-certified facility capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors, contract manufacturing procurement leads, quality assurance managers, and direct-to-consumer brand founders combined with secondary validation against FDA establishment registrations, NSF Certified facility audits, EFSA health claim submissions, and India's PLI scheme beneficiary disclosures. Triangulation across these sources ensures segmentation integrity for probiotics, vitamins, herbal supplements, and weight management product categories.
Historical trendline analysis of batch cycle times, certification tier penetration, and channel mix evolution informed projection framework development across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end-user channel, and regulatory compliance tier with geographic production cluster overlays. CAGRs derive from fitted growth curves adjusted for NDI notification expansion velocity and probiotic cold-chain infrastructure buildout rates. Forecast inputs incorporate subscription-model adoption patterns and biologic-nutrition hybrid project pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA NDI guidance evolution, EFSA health claim substantiation burden shifts, and aluminum-gelatin input price volatility. Forecasts reflect documented assumptions regarding outsourcing penetration rates and certification tier demand elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
European Union Cross Border Healthcare Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Surgical Fluid Disposal Market