
 Global Ambulatory Services Market | 2026-2036
Global Ambulatory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulatory Services Market Foresight
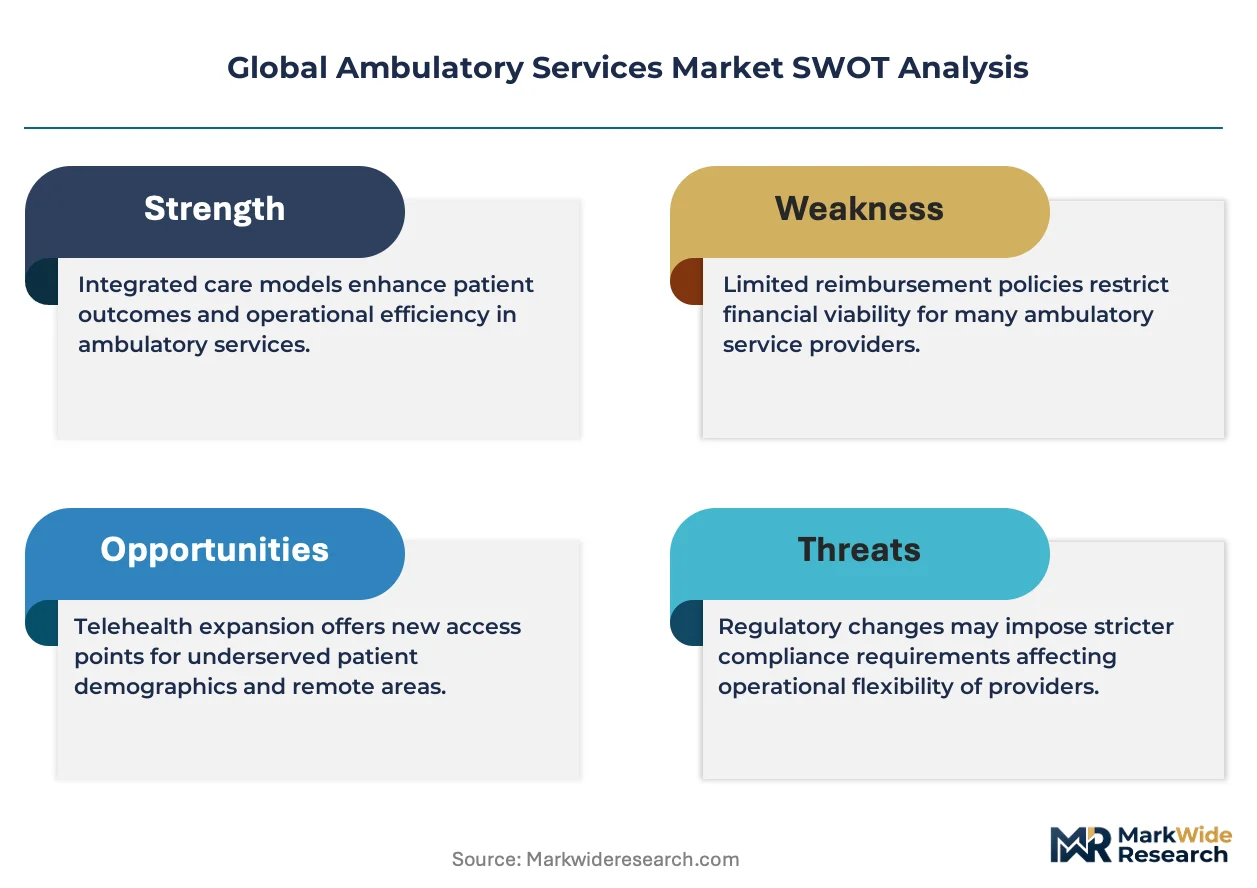
Joint Commission accreditation is collapsing as a gatekeeper standard, forcing independent surgery centers to consolidate or exit. HCA Healthcare leverages its hospital-affiliated ambulatory network to sustain volume guarantees across multiple states. Tenet Healthcare anchors its position through USPI, the largest ambulatory surgery platform in the United States. Surgery Partners competes on price transparency, occupying a distinct niche in physician-partnership models.
Ambulatory services encompass outpatient diagnostic, surgical, and therapeutic interventions delivered outside traditional inpatient hospital settings, typically involving same-day discharge protocols and lower acuity thresholds than emergency departments. These services reduce per-episode costs by eliminating overnight stays while maintaining clinical outcomes through standardized protocols and dedicated procedural infrastructure. Diagnostic imaging leads service type revenue pools due to capital intensity and recurring referral volumes, while telehealth consultations within delivery models represent the fastest-expanding channel as reimbursement parity stabilizes. Preventive care segments carry thinner margins but generate patient capture for higher-value downstream procedures.
FDA device clearance pathways shape which minimally invasive tools reach ambulatory settings, directly influencing procedure migration from hospitals. CMS site-neutral payment policies and OSHA bloodborne pathogen standards jointly determine cost structures and operational compliance burdens for freestanding facilities. Stakeholders must monitor whether Medicare Advantage penetration shifts site-of-service incentives faster than traditional fee-for-service frameworks can adapt.
Market Dynamics
CMS site-neutral payment policies are compressing hospital outpatient reimbursement rates, accelerating procedure migration toward freestanding ambulatory surgery centers and physician-owned facilities.
Growth Catalysts
- Minimally invasive surgical instrumentation:FDA 510(k) clearances for same-day spine and joint procedures expand addressable procedure volumes beyond traditional cataract and colonoscopy domains.
- Medicare Advantage penetration:United States commercial payers now steer 48% of eligible beneficiaries into managed plans with explicit site-of-service incentives favoring lower-cost ambulatory settings.
- OSHA bloodborne pathogen standards:Streamlined compliance frameworks reduce operational overhead for independent surgery centers, narrowing the cost gap with hospital-affiliated competitors.
Market Restraints
- Anesthesiologist supply concentration:Rural United States markets face 23% staffing shortfalls, capping case volume expansion regardless of facility capacity.
- Implant cost volatility:Orthopedic device pricing fluctuates with cobalt-chromium alloy feedstock markets, squeezing margins on high-volume joint procedures.
- Certificate of Need laws:Twelve United States states maintain CON restrictions that block new entrant capacity in concentrated metropolitan markets.
Strategic Opportunities
- Rural health clinic integration:Federally Qualified Health Centers in the United States Midwest present untapped referral networks for specialty procedure outsourcing.
- Telehealth preoperative screening:Remote patient evaluation protocols reduce no-show rates and expand catchment radius without physical site expansion.
- India's Ayushman Bharat expansion:Government-sponsored insurance now covers 500 million beneficiaries, creating demand for cataract and dialysis services at price points viable for ambulatory delivery.
Industry Challenges
- Perioperative nursing specialization:Same-day discharge protocols require cross-trained staff capable of preoperative assessment, intraoperative assistance, and post-anesthesia recovery management.
- EMR interoperability:Freestanding centers struggle to exchange data with hospital referral networks using incompatible Epic, Cerner, and Meditech systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulatory Services Market |
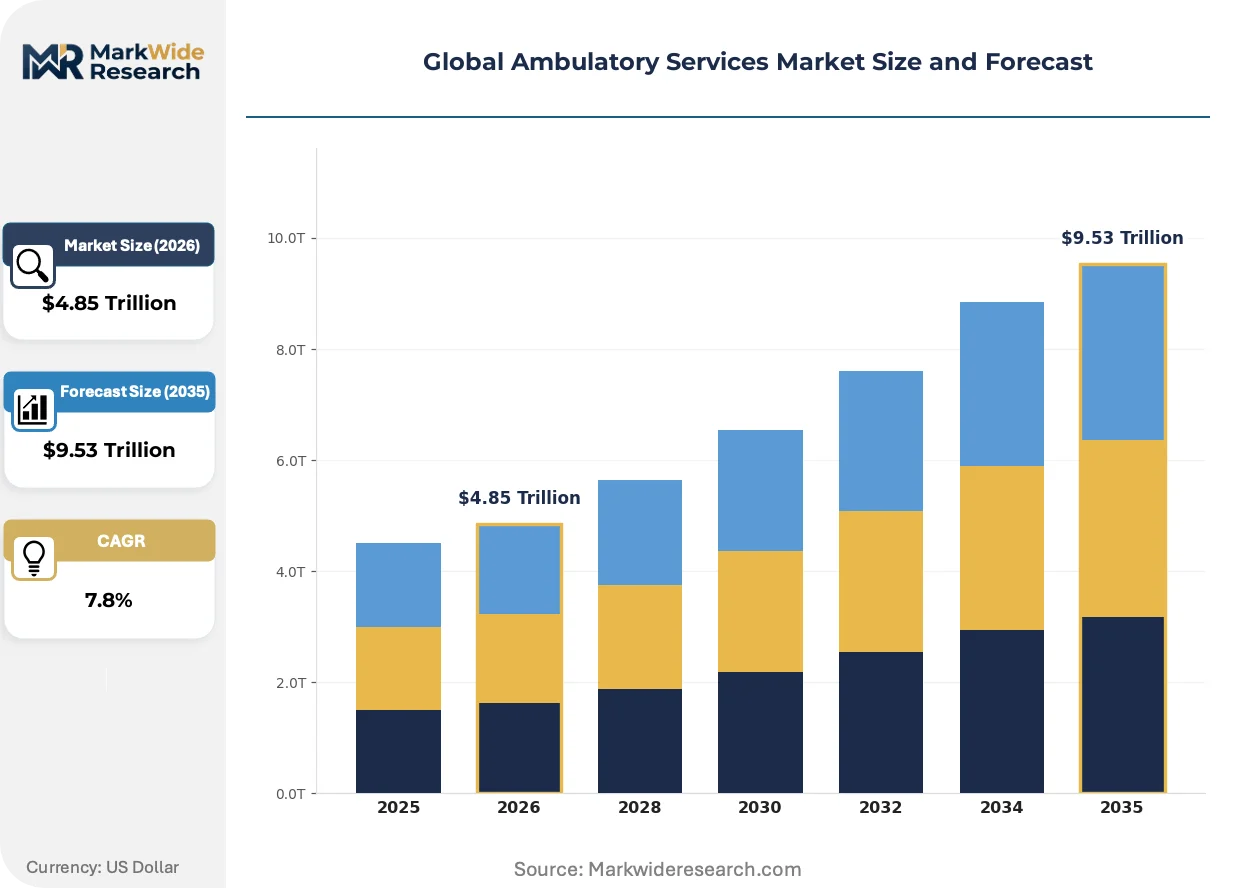
| Market Size in 2026 | $4.85 Trillion |
| Market Size in 2035 | $9.53 Trillion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Imaging, Outpatient Surgery, Rehabilitation, Preventive Care, Emergency Services Application: Chronic Disease Management, Wellness Programs, Minor Trauma Treatment, Postoperative Monitoring, Immunization End User: Specialty Clinics, Community Health Centers, Ambulatory Surgery Centers, Urgent Care Facilities, Diagnostic Laboratories Delivery Model: In-Person Visits, Telehealth Consultations, Home Health Visits, Mobile Health Units, Retail Clinics |
| Companies Covered | HCA Healthcare, Tenet Healthcare, Universal Health Services, Envision Healthcare, Surgery Partners, AmSurg, Medical Facilities Corporation, Terveystalo Healthcare, Healthway Medical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulatory Services Market Shifts & Advancements
Robotic-assisted platforms are migrating from hospital operating rooms into ambulatory settings, compressing recovery timelines and reshaping capital deployment strategies across outpatient surgery networks.
Ultrasonic scalpels with integrated vessel sealing are supplanting traditional electrocautery and mechanical clipping in general surgery procedures. United States multi-specialty surgery centers now deploy these devices in 34% of laparoscopic cases, up from 12% five years prior. The technology is enabling same-day discharge for procedures previously requiring 23-hour observation stays.
EU Medical Device Regulation (MDR) transition deadlines are forcing ambulatory surgery centers to revalidate supplier quality management systems. Class IIa surgical instruments now require notified body recertification, extending procurement cycles by 4-6 months. German and French facility operators are consolidating vendor panels to reduce compliance audit burden.
Self-funded employers in the United States are contracting directly with ambulatory surgery centers for bundled episode pricing, bypassing traditional payer networks. Manufacturing and logistics firms with concentrated employee populations in Texas and Ohio now negotiate fixed rates for orthopedic and cardiovascular procedures. Direct contracting arrangements are visible where traditional commercial insurance penetration remains highest.
Global Ambulatory Services Market Segmentation
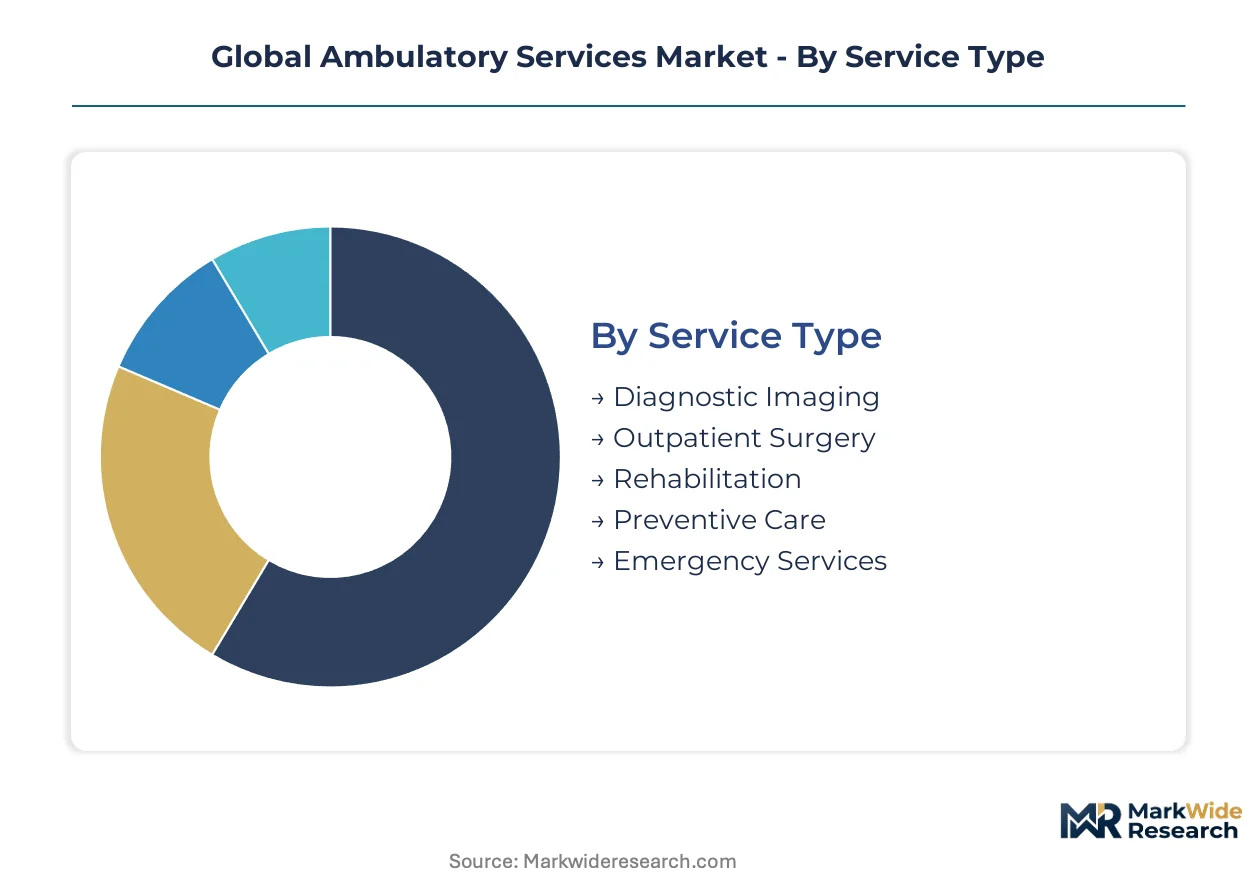
Segmentation reveals how capital intensity, reimbursement mechanics, and site-of-service economics fragment competitive positioning across ambulatory service delivery. Understanding these divides exposes where margin pools concentrate and which operational models attract strategic investment.
Service Type:
Diagnostic imaging and outpatient surgery dominate revenue generation in developed markets, while preventive care and emergency services show stronger penetration in emerging economies where infrastructure gaps persist.
- Diagnostic Imaging:MRI, CT, and ultrasound modalities require substantial capital deployment and radiologist networks. Demand clusters in Germany and Japan where aging demographics drive recurring oncology and cardiology screening protocols. Reimbursement parity between hospital outpatient and freestanding imaging centers determines competitive viability.
- Outpatient Surgery:Cataract extraction, arthroscopy, and endoscopic procedures performed under same-day discharge protocols. United States ambulatory surgery centers capture volume through CMS site-neutral payment advantages, while India's expanding surgical infrastructure targets price-sensitive domestic consumption.
- Rehabilitation:Physical and occupational therapy delivered through outpatient protocols. Medicare Advantage plans in the United States increasingly bundle post-acute services with surgical episodes.
- Preventive Care:Vaccination, wellness screenings, and chronic disease monitoring. Federally Qualified Health Centers in the United States Midwest anchor this segment through government reimbursement guarantees.
- Emergency Services:Urgent care and observation services below inpatient admission thresholds. Freestanding emergency departments in Texas and Florida compete on wait time reduction.
Diagnostic imaging commands the established base. The steepest expansion runs through outpatient surgery.
Application:
Chronic disease management absorbs the highest per-patient spend, while wellness programs and immunization serve as patient acquisition channels with thinner margins but superior volume velocity.
- Chronic Disease Management:Diabetes, hypertension, and COPD protocols requiring longitudinal monitoring. United States Medicare Advantage penetration concentrates demand in managed care contracts with explicit outcome metrics. Germany's disease management programs (DMPs) provide template reimbursement structures.
- Wellness Programs:Corporate and individual preventive health subscriptions. Self-funded employers in Ohio and Michigan contract directly for biometric screening and lifestyle intervention services.
- Minor Trauma Treatment:Laceration repair, fracture stabilization, and burn management. Urgent care networks in suburban United States markets compete on evening and weekend accessibility.
- Postoperative Monitoring:Wound assessment, pain management, and complication screening following ambulatory procedures. Telehealth platforms reduce physical site requirements for routine follow-up.
- Immunization:Vaccine administration through retail pharmacy and dedicated clinic channels. India's Universal Immunization Programme creates volume concentration through government procurement.
Chronic disease management anchors revenue stability. Wellness programs climb the fastest as employer-sponsored preventive expenditure accelerates.
End User:
Specialty clinics and ambulatory surgery centers concentrate high-margin procedural volume, while community health centers and urgent care facilities compete on access speed and geographic penetration.
- Specialty Clinics:Cardiology, orthopedics, and gastroenterology practices with embedded procedural capacity. United States physician-owned entities leverage Stark Law exceptions for in-office ancillary services. German specialist outpatient clinics (MVZs) consolidate through private equity acquisition.
- Community Health Centers:Federally funded primary care serving underserved populations. United States HRSA grant programs sustain operations regardless of patient payer mix.
- Ambulatory Surgery Centers:Medicare-certified facilities performing same-day surgical procedures. United Surgical Partners International and Surgery Partners dominate United States consolidation activity.
- Urgent Care Facilities:Walk-in treatment for non-life-threatening conditions. Retail clinic expansion by CVS MinuteClinic and Walgreens reshapes competitive density in metropolitan United States markets.
- Diagnostic Laboratories:Centralized and point-of-care testing infrastructure. Quest Diagnostics and LabCorp anchor United States reference laboratory networks with ambulatory collection site density.
Specialty clinics capture premium procedural economics. Ambulatory surgery centers gain share fastest through procedure migration from hospital settings.
Delivery Model:
In-person visits retain clinical complexity advantages, while telehealth and mobile units extend catchment radius without proportional capital expansion.
- In-Person Visits:Traditional clinic-based consultation and procedural delivery. Physical examination requirements sustain dominance in orthopedic and dermatology specialties where tactile assessment remains diagnostic.
- Telehealth Consultations:Synchronous video and asynchronous messaging platforms. United States CMS reimbursement parity post-pandemic enabled sustainable business models for behavioral health and routine follow-up.
- Home Health Visits:Nurse and therapist deployment to patient residences. Post-acute substitution strategies in Medicare Advantage plans reduce skilled nursing facility utilization.
- Mobile Health Units:Vehicle-mounted diagnostic and screening services. Rural United States markets deploy mammography and dental units to address geographic access barriers.
- Retail Clinics:Pharmacy-embedded urgent care and preventive services. MinuteClinic, Walgreens Healthcare, and Walmart Health compete on convenience pricing in United States suburban corridors.
In-person visits retain the procedural core. Telehealth consultations expand most quickly as asynchronous workflow integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS site-neutral payment policies and Medicare Advantage expansion are restructuring ambulatory economics across mature healthcare systems. Facility operators in high-cost markets face margin compression while emerging economies build outpatient infrastructure around government insurance schemes.
United States
Self-funded employers in Texas and Ohio now contract directly with ambulatory surgery centers for bundled orthopedic episodes, bypassing traditional payer networks. CMS site-neutral payment rules compress hospital outpatient reimbursement, accelerating procedure migration toward freestanding facilities. HCA Healthcare leverages its hospital-affiliated ambulatory network across multiple states to sustain volume guarantees.
Germany
Aging demographics drive recurring oncology and cardiology screening protocols through diagnostic imaging networks. EU Medical Device Regulation transition deadlines force ambulatory surgery centers to revalidate supplier quality management systems, extending procurement cycles. Specialist outpatient clinics in Bavaria and North Rhine-Westphalia consolidate through private equity acquisition.
China
Government-sponsored insurance expansion creates demand for cataract and dialysis services at price points viable for ambulatory delivery. NMPA device clearance pathways determine which minimally invasive tools reach outpatient settings. Yangtze River Delta and Pearl River Delta clusters concentrate new ambulatory facility construction.
India
Ayushman Bharat now covers 500 million beneficiaries, generating volume for same-day surgical procedures. CDSCO regulatory frameworks shape which imported devices enter ambulatory supply chains. Maharashtra and Karnataka host the fastest-growing networks of physician-owned day surgery centers.
Japan
Metropolitan aging populations push demand for outpatient cancer screening and minimally invasive joint procedures. PMDA clearance timelines influence which robotic-assisted platforms migrate from hospital operating rooms into ambulatory settings. Kanto and Kansai regions concentrate diagnostic imaging capacity.
Global Ambulatory Services Market Competitive Landscape
Listed leaders compete with private specialists across capital deployment and physician alignment models. Hospital-affiliated networks leverage balance sheet capacity for multi-state expansion, while physician-owned platforms compete on partnership economics and operational autonomy. Three archetypes dominate: integrated health system affiliates, pure-play ambulatory consolidators, and regional physician partnerships. M&A activity concentrates facility portfolios under scaled platforms, while telehealth integration reshapes preoperative screening capabilities.
Within the integrated health system tier, HCA Healthcare and Tenet Healthcare exemplify hospital-affiliated models that sustain volume guarantees through captive referral networks. Surgery Partners occupies a distinct position among physician-partnership specialists, competing on price transparency and operational flexibility. These three entities represent contrasting approaches to ambulatory market structure.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare |
| Universal Health Services |
| Envision Healthcare |
| Surgery Partners |
| AmSurg |
| Medical Facilities Corporation |
| Terveystalo Healthcare |
| Healthway Medical Group |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with orthopedic device manufacturers lock in supply access and price visibility for United States ambulatory surgery centers navigating cobalt-chromium alloy feedstock volatility. These contractual structures insulate high-volume joint procedure providers from implant cost spikes while constraining operational flexibility.
Pricing Analysis
Certification level (Joint Commission, CMS Medicare certification, state licensure tier) creates the primary spread between premium hospital-affiliated facilities and independent surgery centers. Three-tier pricing structure across premium, standard, and economy levels reflects accreditation status, geographic market concentration, and payer contract breadth. Cost compression in economy-tier independent centers is intensifying because Certificate of Need laws restrict new entrant capacity in twelve states. Self-funded employers exhibit highest price sensitivity, while Medicare Advantage plans prioritize network adequacy over unit cost.
Supply Chain Analysis
Port congestion on trans-Pacific lanes and container availability constraints elevate inbound logistics costs for German and French ambulatory surgery centers sourcing Class IIa surgical instruments under EU MDR transition deadlines. Device manufacturing concentrates in Germany, Switzerland, and the United States, with sterilization equipment production anchored in Italy and Japan. Supply chains draw from cobalt-chromium alloys, polymer sutures, and single-use laparoscopic ports. Single-source vulnerability persists for robotic-assisted surgical platforms cleared through FDA 510(k) pathways. Distribution runs through manufacturer-direct sales, GPO contracts, and specialized surgical device distributors serving multi-site networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ambulatory Services Market sits in early-cycle expansion as Medicare Advantage penetration accelerates site-of-service migration toward lower-cost settings. Procedure volume guarantees through hospital-affiliated networks sustain incumbent economics while independent platforms capture price-sensitive segments.
For Market Incumbents: Fortify physician alignment through equity partnership structures that preempt independent surgery center formation. Expand telehealth preoperative screening capabilities to extend catchment radius without proportional physical site investment. Defensive consolidation of rural health clinic referral networks counters emerging regional physician partnerships. CMS site-neutral payment compression demands operational cost discipline.
For New Entrants and Emerging Players: Lead with price transparency and bundled episode pricing to capture self-funded employer contracts in Texas and Ohio manufacturing corridors. India's Ayushman Bharat expansion presents the most penetrable geography, with Maharashtra and Karnataka day surgery centers targeting 500 million newly insured beneficiaries. Federally Qualified Health Center integration in the United States Midwest offers specialty procedure outsourcing partnerships with guaranteed reimbursement.
For Investors and Strategic Acquirers: Physician-owned ambulatory platforms with established Medicare certification and multi-specialty case mix offer durable cash flow visibility. Long-term viability hinges on reimbursement parity sustainability and robotic platform migration economics. Watch Medicare Advantage penetration rates as the inflection signal for site-of-service incentive acceleration beyond traditional fee-for-service adaptation capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| CMS Medicare Certification Expansion | Unlocks site-neutral payment advantages and hospital referral network access. |
| Robotic Platform Deployment | Enables same-day spine and joint procedures previously requiring inpatient stays. |
| Telehealth Preoperative Integration | Reduces no-show rates and extends geographic catchment without facility expansion. |
| Physician Partnership Equity Structures | Aligns operator and clinician incentives to preempt independent competitor formation. |
| EU MDR Supplier Revalidation | Consolidates vendor panels and extends procurement cycles for German and French operators. |
Research Methodology
Initial hypotheses were tested against primary input from ambulatory surgery center administrators, hospital system strategy officers, GPO contracts managers, and CMS policy specialists and refined through secondary validation. Hospital procurement databases, CMS Medicare cost report filings, state Certificate of Need records, and Joint Commission accreditation rosters anchored quantitative sizing. Bottom-up facility count and case volume estimates triangulated against top-down payer expenditure flows.
Variance decomposition across service type, application, end user, delivery model, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume projections and reimbursement trajectory assumptions. Modeled inputs included Medicare Advantage penetration curves, FDA 510(k) clearance timelines for same-day surgical devices, and EU MDR transition compliance costs across German and French facility networks.
Forecasts assume regulatory continuity in United States CMS site-neutral payment rules and EU Medical Device Regulation enforcement; material policy shifts would require re-modeling. Implant cost volatility, anesthesiologist supply concentration in rural markets, and EMR interoperability failures represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
Medical Spa Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Audiology Services Market
Healthcare Services
Patient Transportation Market