

Hospital Command Center Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Command Center Operations Market Insights
Subscription-based software-defined analytics is recalibrating how hospitals procure command center capabilities, shifting capital expenditure into recurring operational budgets. GE HealthCare leverages its Edison platform architecture to anchor enterprise-wide deployments across multi-hospital networks. Philips sustains competitive differentiation through deep integration of patient monitoring telemetry into command center visualization layers. Siemens Healthineers specializes in blending imaging workflow orchestration with real-time bed management dashboards.
Hospital command center operations encompass the centralized coordination of clinical resources, patient flows, and facility logistics through digital platforms that process real-time data streams from electronic health records, IoT sensors, and communication systems, typically operating with sub-minute refresh cycles for bed availability and staff location tracking. The primary purpose is to reduce operational friction in acute care settings where delayed discharges and emergency department boarding cascade into capacity failures and revenue loss. Cloud-based operation modes are capturing the fastest expansion as health systems shed on-premises infrastructure burdens and pursue elastic scaling during demand surges. Artificial Intelligence within technology integration is where margin pools concentrate deepest, particularly for predictive admission and discharge algorithms that command premium licensing fees. Patient Flow Management remains the most mature functional application, though Emergency Response modules are accelerating as mass casualty readiness regains institutional priority.
FDA scrutiny of clinical decision support software shapes vendor development roadmaps, particularly for AI modules that influence triage or resource allocation without direct clinician oversight. HIPAA compliance frameworks constrain data architecture choices, forcing hybrid cloud designs that keep protected health information within hospital-controlled environments while pushing analytics workloads to external infrastructure. Stakeholders must weigh the pace of AI validation against competitive pressure to deploy predictive capabilities before operational margins erode further.
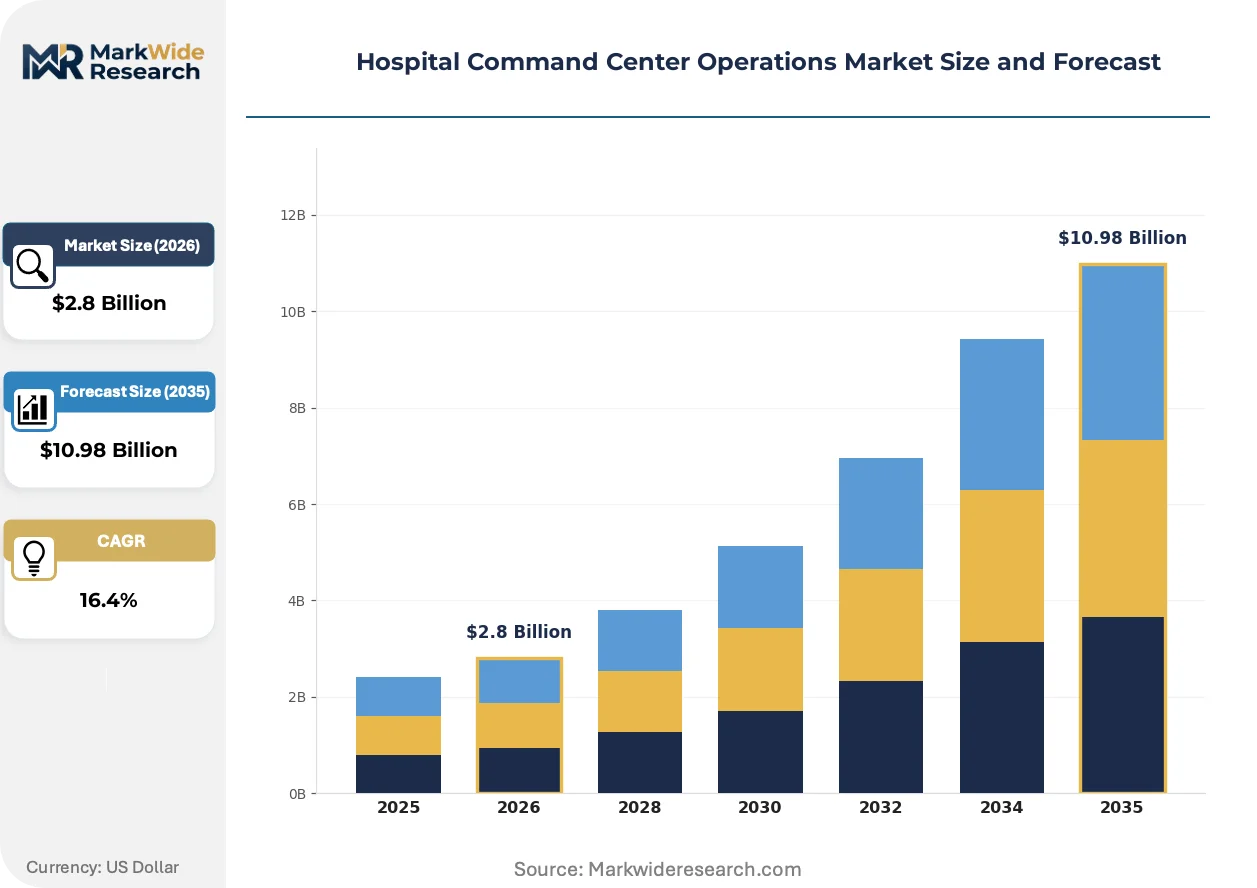
Market Dynamics
Subscription-based software procurement is overtaking capital-heavy infrastructure investments across United States health systems, compressing vendor sales cycles and locking hospital networks into recurring revenue relationships with platform providers.
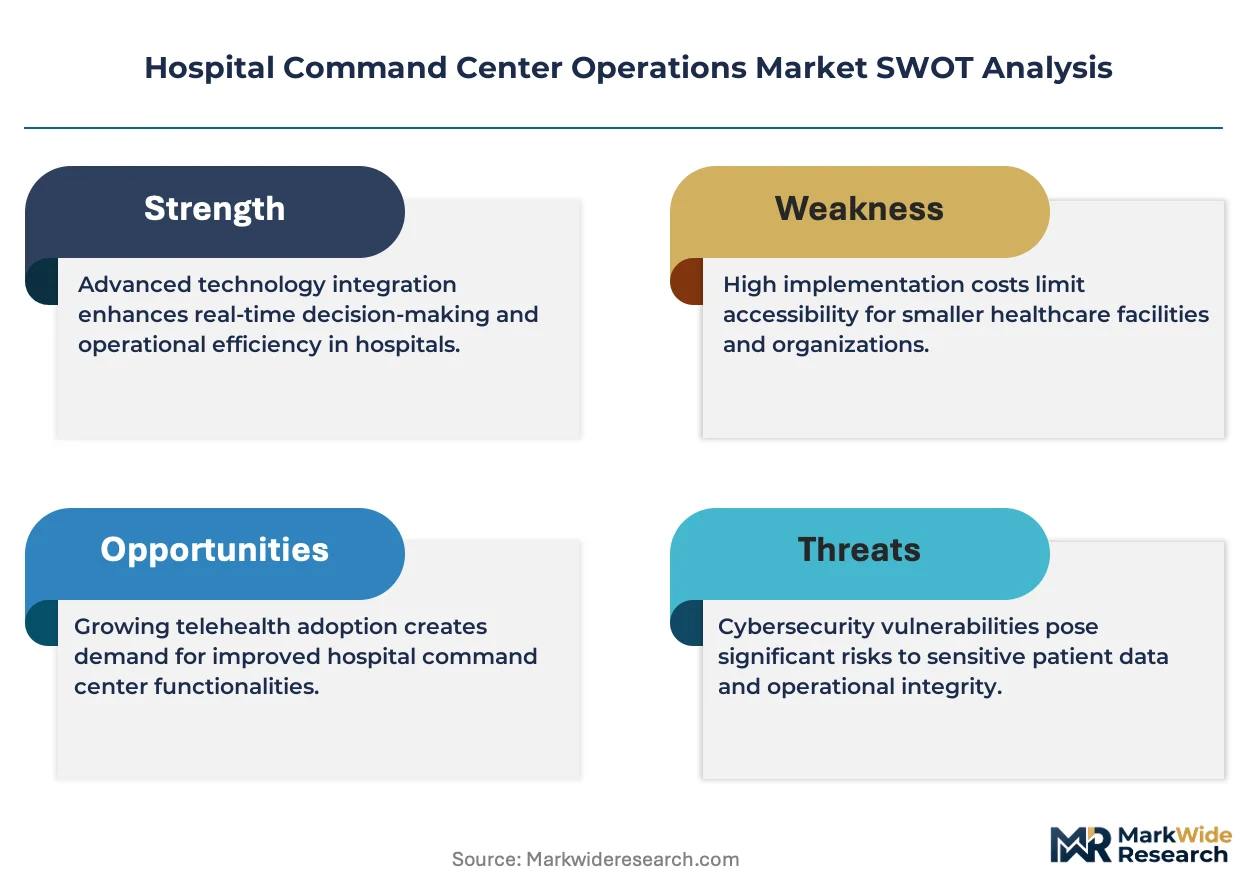
Growth Catalysts
- FDA Pre-Certification Pathway:The FDA's streamlined validation framework for clinical decision support software accelerates deployment timelines for AI-enabled patient monitoring modules in acute care settings.
- Bed Management Automation:Real-time capacity orchestration platforms reduce emergency department boarding hours and capture previously lost admission revenue for margin-constrained hospitals.
- United States Labor Shortages:Registered nurse vacancy rates exceeding twenty percent in several states force operational modernization through centralized command platforms that amplify existing staff productivity.
Market Restraints
- HIPAA Hybrid Cloud Architecture:Protected health information localization requirements inflate infrastructure costs and constrain vendor architecture flexibility for analytics workloads.
- AI Validation Timelines:FDA scrutiny of predictive admission algorithms without direct clinician oversight extends development roadmaps and defers revenue recognition for module vendors.
- Legacy EHR Integration:Proprietary data formats from dominant electronic health record vendors create interoperability friction that slows command center deployment velocity.
Strategic Opportunities
- Rural Hospital Networks:Underpenetrated critical access facilities in the United States present white-space demand for cloud-native command platforms that substitute for unavailable specialist labor.
- Mass Casualty Readiness:Emergency Response module adoption is accelerating as institutional priority for disaster preparedness mandates surge-capacity simulation capabilities.
- Telemedicine Convergence:Integration of virtual care command interfaces with physical bed management creates unified coordination layers for hybrid care delivery models.
Industry Challenges
- Interoperability Engineering Talent:Scarce technical specialists capable of bridging HL7 FHIR standards with proprietary IoT sensor protocols command premium compensation that strains vendor margins.
- Sub-Minute Latency Requirements:Real-time staff location tracking and bed availability refresh cycles demand edge computing infrastructure investments that complicate cloud migration roadmaps.
- Clinician Workflow Adoption:Frontline nursing staff resistance to algorithmic discharge recommendations requires change management investments that extend implementation timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Command Center Operations Market Trends and Innovations
Artificial intelligence modules are penetrating deeper into operational decision layers, shifting competitive differentiation from data visualization toward predictive action recommendations that automate resource allocation without human intervention.
Cloud-native command platforms is overtaking on-premises deployments as United States health systems shed data center infrastructure burdens and pursue elastic scaling during seasonal demand surges. Large integrated delivery networks in Texas and California are completing enterprise-wide migrations within eighteen-month windows. This architecture shift is compressing vendor competitive moats by standardizing integration protocols and reducing switching costs between platform providers.
The FDA's tightened oversight of clinical decision support software is reshaping vendor development roadmaps, particularly for AI modules influencing triage or resource allocation without direct clinician oversight. Manufacturers must now document algorithmic training data provenance and performance across demographic subgroups before commercial deployment. United States-based vendors are responding by establishing dedicated regulatory affairs functions and pre-submission consultation pathways that parallel pharmaceutical approval timelines.
Health system procurement committees are consolidating vendor relationships around enterprise-wide platform contracts rather than point-solution purchases for individual facilities. Subscription pricing models with per-bed or per-admission metrics are displacing perpetual license structures that dominated early market development. This pattern is most visible in the southeastern United States, where hospital consolidation has concentrated purchasing authority within regional corporate offices that negotiate multi-year agreements spanning dozens of facilities.
Hospital Command Center Operations Market Segmentation
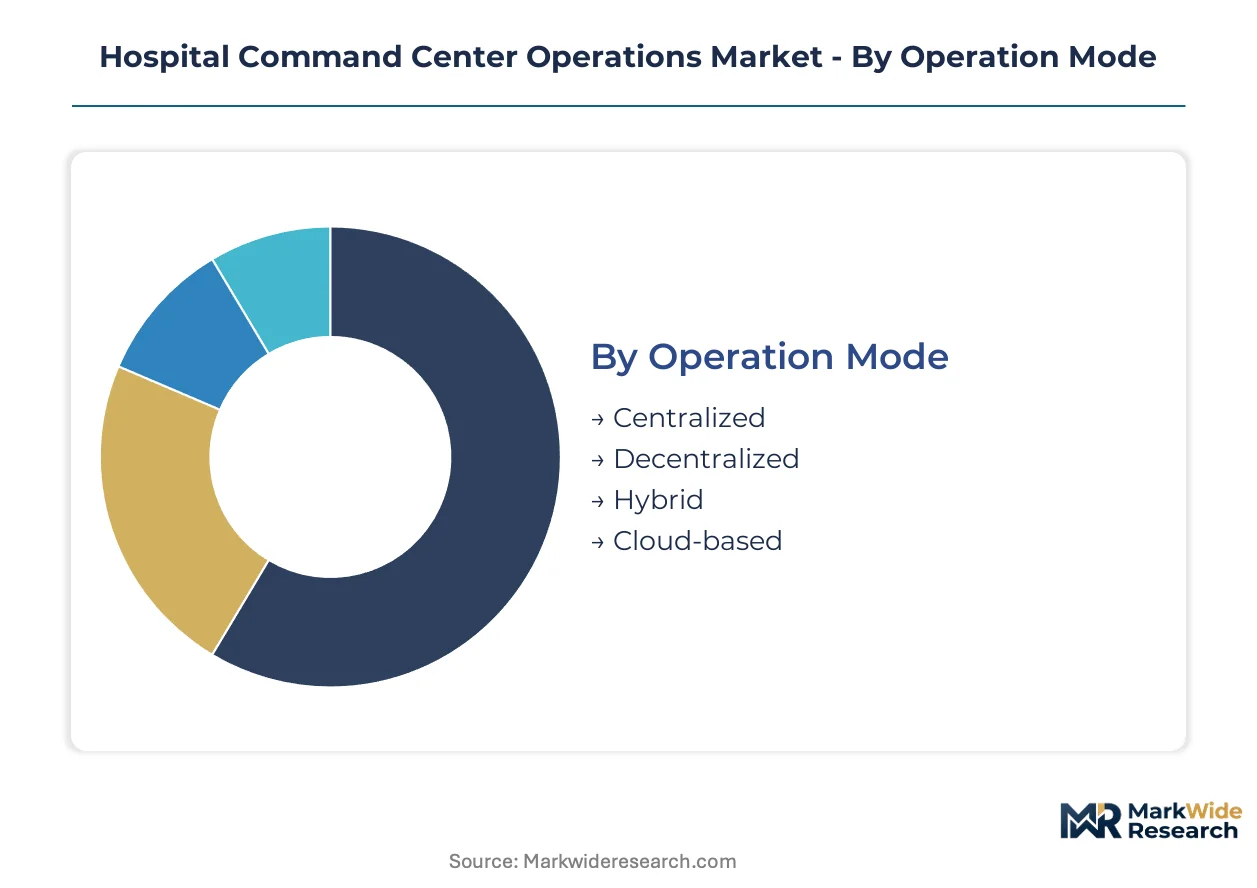
Hospital command center procurement patterns diverge sharply across operational architectures and technology maturity levels. Buyers with legacy infrastructure investments prioritize hybrid deployment models, while greenfield facilities gravitate toward cloud-native platforms that minimize capital expenditure.
Operation Mode:
Cost tier separates buyers most decisively, with capital-constrained networks favoring subscription models and well-capitalized systems absorbing upfront infrastructure spend.
- Cloud-based:Elastic compute resources enable surge scaling during seasonal demand peaks without data center expansion. United States health systems in Texas and California are completing enterprise-wide migrations within compressed eighteen-month windows to shed infrastructure burdens.
- Hybrid:Protected health information remains localized within hospital-controlled environments while analytics workloads process externally. HIPAA compliance frameworks force this architecture for organizations handling sensitive patient telemetry.
- Centralized:Single-tenant platforms anchor large integrated delivery networks seeking unified visibility across dozens of facilities.
- Decentralized:Edge computing nodes at individual campuses serve critical access hospitals with limited IT specialist staffing.
Cloud-based deployments lead volumes today; hybrid architectures are gaining share fastest among mid-tier health systems.
Technology Integration:
Application criticality determines vendor selection, with life-safety systems commanding premium validation investment and administrative modules competing on price.
- Artificial Intelligence:Predictive admission and discharge algorithms command premium licensing fees. FDA pre-certification pathways now require documented training data provenance across demographic subgroups before commercial deployment.
- Machine Learning:Operational pattern recognition refines bed turnover predictions and staff scheduling optimization. United States labor shortages exceeding twenty percent registered nurse vacancy rates amplify demand for productivity-enhancing automation.
- Data Analytics:Real-time dashboard visualization aggregates electronic health record streams with IoT sensor feeds.
- Internet of Things:Sub-minute refresh cycles for staff location tracking and equipment positioning demand edge infrastructure.
- Blockchain:Immutable audit trails support supply chain provenance and credential verification workflows.
Artificial Intelligence leads volumes today; Machine Learning is climbing the fastest as operational margins erode.
Functional Application:
Customer type shapes module prioritization, with academic medical centers emphasizing research integration and community hospitals focusing on throughput velocity.
- Patient Flow Management:Mature bed orchestration platforms reduce emergency department boarding hours and capture previously lost admission revenue. Real-time capacity dashboards refresh with sub-minute latency to prevent cascade failures.
- Emergency Response:Mass casualty readiness modules are accelerating as institutional priority for disaster preparedness mandates surge-capacity simulation capabilities. Regulatory pressure from CMS emergency preparedness requirements drives procurement.
- Resource Allocation:Automated staff deployment matches caregiver availability with patient acuity fluctuations.
- Staff Coordination:Communication layer integration unifies paging, secure messaging, and location services.
- Equipment Tracking:RFID and BLE sensor networks locate critical devices across sprawling campus footprints.
Patient Flow Management leads volumes today; Emergency Response is expanding most quickly.
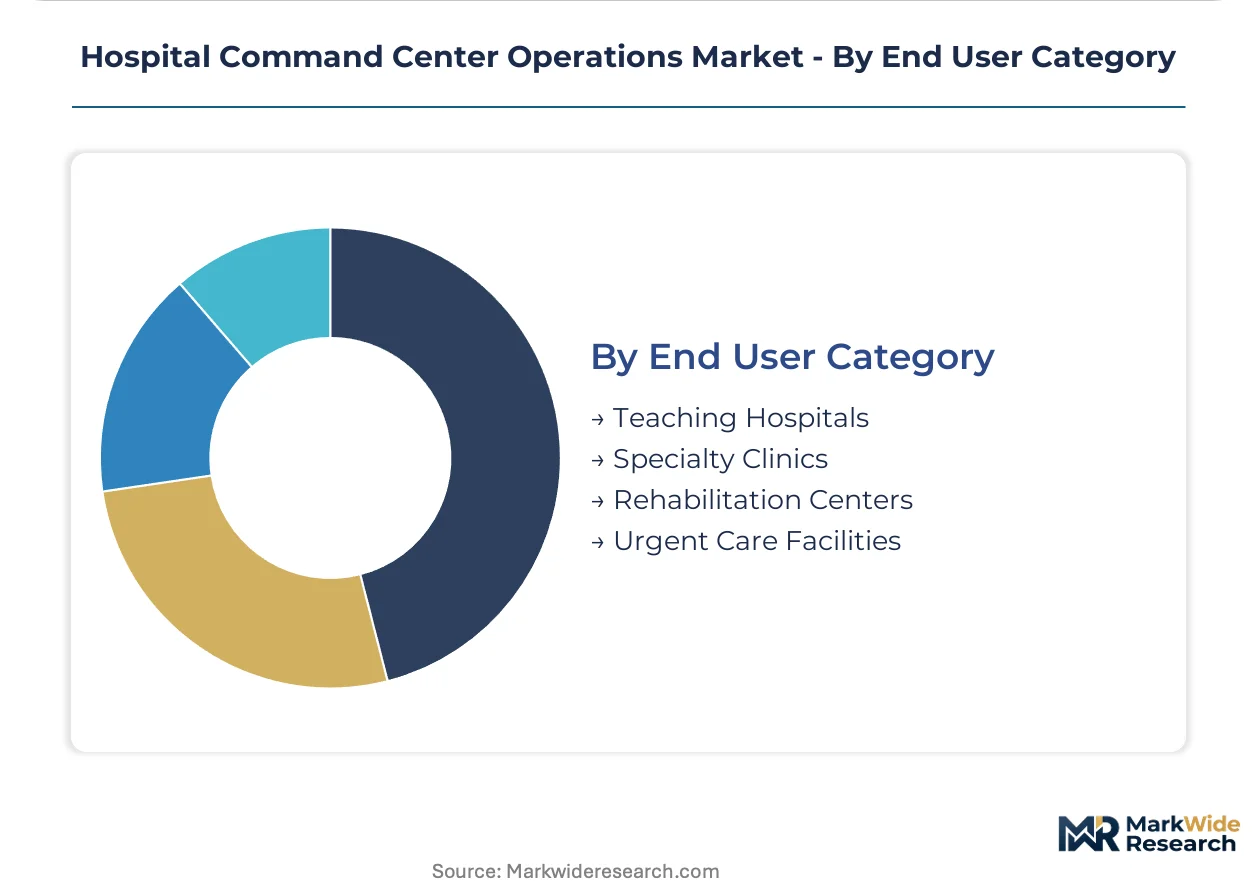
End User Category:
Volume scale differentiates implementation complexity, with the largest teaching hospitals requiring multi-year deployment roadmaps and smaller facilities demanding rapid time-to-value.
- Teaching Hospitals:Academic medical centers integrate command platforms with research data repositories and resident training workflows. Epic and Cerner electronic health record dominance creates interoperability engineering challenges that extend implementation timelines.
- Urgent Care Facilities:Retail health locations prioritize rapid patient throughput and seamless referral coordination with affiliated hospital networks. Subscription pricing with per-visit metrics aligns costs with fluctuating demand.
- Specialty Clinics:Procedure-focused settings emphasize equipment utilization and specialized staff scheduling.
- Rehabilitation Centers:Long-stay patient populations require distinct discharge planning algorithms and family communication portals.
Teaching Hospitals lead volumes today; Urgent Care Facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of hospital command center procurement, while Germany and the United Kingdom trail with smaller but accelerating deployments as European health systems modernize operational infrastructure.
United States
Hospital consolidation and registered nurse vacancy rates exceeding twenty percent drive urgent demand for centralized command platforms. FDA pre-certification pathways for clinical decision support software streamline AI module deployment timelines. Texas and California health systems complete enterprise-wide cloud migrations within compressed eighteen-month windows.
Germany
University hospital networks prioritize integrated command centers to coordinate complex patient flows across multi-site academic medical centers. EMA oversight of clinical decision support tools shapes vendor validation requirements for predictive algorithms. The Rhine-Ruhr metropolitan cluster hosts concentrated pilot programs for real-time capacity orchestration platforms.
United Kingdom
NHS England operational modernization mandates accelerate procurement of patient flow management systems to reduce emergency department boarding. GDPR compliance frameworks constrain data architecture choices, forcing hybrid cloud designs for protected health information. London teaching hospitals anchor early adoption of AI-enabled discharge prediction modules.
Japan
Aging demographics and shrinking clinical workforces compel metropolitan hospitals to deploy automation-heavy command platforms. PMDA regulatory timelines for AI-enabled patient monitoring extend vendor development roadmaps. The Kanto region surrounding Tokyo concentrates deployment of sub-minute latency bed management systems.
Australia
State health department consolidation of purchasing authority drives enterprise-wide platform contracts across public hospital networks. TGA scrutiny of clinical decision support software mirrors FDA validation stringency for predictive algorithms. New South Wales and Victoria lead cloud-native command center adoption among tertiary referral hospitals.
Hospital Command Center Operations Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established health technology conglomerates anchoring enterprise-wide deployments while niche software vendors capture point-solution opportunities. The vendor landscape organizes around three archetypes: imaging equipment manufacturers extending into operational software, electronic health record incumbents embedding command capabilities, and pure-play analytics specialists. Consolidation pressure intensifies as health system procurement committees favor single-vendor relationships over fragmented point solutions. Strategic partnerships between hardware manufacturers and cloud infrastructure providers accelerate deployment velocity for hybrid architectures.
Within the imaging-to-software extension archetype, GE HealthCare, Philips, and Siemens Healthineers occupy positions that leverage installed base relationships across multi-hospital networks. These conglomerates exemplify platform-centric competitive strategy, anchoring enterprise contracts through deep integration of telemetry and visualization layers. Their geographic origins—United States, Netherlands, and Germany respectively—reflect historical health technology manufacturing concentrations that now feed software-defined service expansion.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips |
| Siemens Healthineers |
| Oracle Health |
| Epic Systems |
| TeleTracking Technologies |
| Care Logistics |
| Qventus |
| Dedalus |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up software specialists anchor pricing discipline across the Hospital Command Center Operations Market, concentrating vendor ownership among financial sponsors that prioritize recurring revenue predictability over transactional margin capture. This ownership pattern tightens supply-side coordination between cloud infrastructure providers and clinical workflow integrators, compressing procurement timelines while elevating subscription renewal rates as the dominant pricing mechanism.
Pricing Analysis
Capacity additions in United States health systems are reshaping price floors for cloud-native command platforms as Texas and California integrated delivery networks complete enterprise-wide migrations within compressed deployment windows. Subscription-based SaaS tiers dominate procurement, with per-bed or per-admission metrics displacing perpetual licenses. Price differentiation hinges on FDA pre-certification status and integration depth with Epic or Cerner electronic health records. Pricing pressure stems from health system procurement committees consolidating vendor relationships around enterprise-wide contracts. Community hospital networks exhibit highest price sensitivity; academic medical centers absorb premium tiers for research-enabled modules.
Supply Chain Analysis
Dual-sourcing requirements from United States health system procurement committees mandate multi-supplier qualification for both cloud infrastructure and clinical decision support modules. Supply concentration centers on the United States for software development, Ireland and India for technical implementation services, and Taiwan for edge computing hardware components. Critical inputs include HL7 FHIR interoperability engines, real-time IoT sensor telemetry, and HIPAA-compliant hybrid cloud architecture. Single-source vulnerability runs through dominant electronic health record vendors whose proprietary data formats create integration friction. Distribution feeds through group purchasing organizations and direct enterprise contracts with regional health system corporate offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hospital Command Center Operations Market reads as a late-cycle quality story as health system procurement shifts toward FDA-validated AI modules with documented training data provenance across demographic subgroups. Demand gravity concentrates in premium specifications that automate resource allocation without direct clinician oversight.
For Market Incumbents: Deploy regulatory affairs infrastructure as the primary defensive lever. Establish dedicated FDA pre-submission consultation pathways that parallel pharmaceutical approval timelines for AI-enabled patient monitoring modules. Fortify enterprise-wide platform contracts against point-solution disintermediation by embedding deep telemetry integration from existing imaging and monitoring installed bases. Capacity additions in cloud infrastructure by hyperscaler partners create margin pressure from below; anchor differentiation through clinical validation depth rather than price competition. For New Entrants and Emerging Players: Rural critical access hospitals present the most penetrable white-space target for cloud-native command platforms that substitute for unavailable specialist labor. Mass casualty readiness modules offer secondary entry point as CMS emergency preparedness requirements institutionalize surge-capacity simulation capabilities. Pursue channel partnerships with group purchasing organizations rather than direct enterprise sales to accelerate procurement committee access. Subscription pricing with rapid time-to-value demonstrations outperforms capital-intensive infrastructure pitches in this segment. For Investors and Strategic Acquirers: Health technology conglomerates seeking imaging-to-software extension represent the most active acquirer category in this space. Long-term viability hinges on AI validation velocity outpacing regulatory scrutiny escalation. Target acquisition profiles center on pure-play analytics specialists with established FDA pre-certification pathways and health system reference contracts spanning multiple facilities. Monitor FDA guidance document releases on clinical decision support software as the critical inflection signal for valuation compression or expansion across the vendor landscape.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway Establishment | Accelerates commercial deployment timelines for AI modules influencing triage decisions without clinician oversight. |
| Enterprise-Wide Platform Contract Consolidation | Locks multi-hospital networks into recurring revenue relationships spanning dozens of facilities. |
| Hybrid Cloud Architecture Deployment | Satisfies HIPAA protected health information localization while enabling elastic analytics scaling. |
| HL7 FHIR Interoperability Engineering Investment | Reduces integration friction with dominant Epic and Cerner electronic health record formats. |
| Mass Casualty Readiness Module Development | Captures institutional priority shift toward disaster preparedness and CMS emergency compliance. |
Research Methodology
Direct dialogue with hospital chief information officers, health system procurement committee chairs, biomedical engineers, and group purchasing organization contract managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, CMS emergency preparedness guidance documents, hospital procurement databases, and GPO contract disclosure records. Bottom-up facility-level deployment tracking triangulated against top-down health system technology spend analysis.
Bottom-up modeling aggregated individual facility adoption curves across operation modes, technology integration tiers, and functional applications. Segmentation dimensions spanned cloud versus hybrid deployment architecture, AI versus machine learning capability depth, patient flow versus emergency response module prioritization, and teaching hospital versus urgent care facility end-user category. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and elasticity-adjusted for labor shortage severity by state. Forecast inputs incorporated registered nurse vacancy rates and hospital consolidation transaction velocity.
Underlying measurement precision varies by segment; cloud-based deployments and patient flow management modules carry tighter precision than blockchain-enabled applications or decentralized edge architectures. Forecasts reflect assumptions regarding FDA validation timeline stability and health system capital allocation priority persistence. Deviation in FDA pre-certification pathway scope expansion or registered nurse labor market recovery would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.