
 Australia Senior Living Market | 2026-2036
Australia Senior Living Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Senior Living Market Analysis
Queensland's retirement community pipeline is reconfiguring supply dynamics across eastern Australia. Bolton Clarke leverages its vertically integrated care model to sustain occupancy premiums in coastal markets. Arcare differentiates through purpose-built dementia design, while Lendlease anchors master-planned developments with integrated health precincts.
Australia senior living encompasses age-qualified residential accommodation with embedded care services, typically featuring 24-hour emergency response systems, universal design standards, and graduated assistance from independent through skilled nursing levels. The primary commercial purpose centers on capturing lifetime value from ageing cohorts through fee-for-service care escalation. Assisted living commands the deepest margin pools due to care premium pricing, while memory care represents the fastest-growing segment as dementia prevalence climbs among Australians aged over eighty-five. Independent living retains the largest volume footprint but faces yield compression from rental-focused occupancy models.
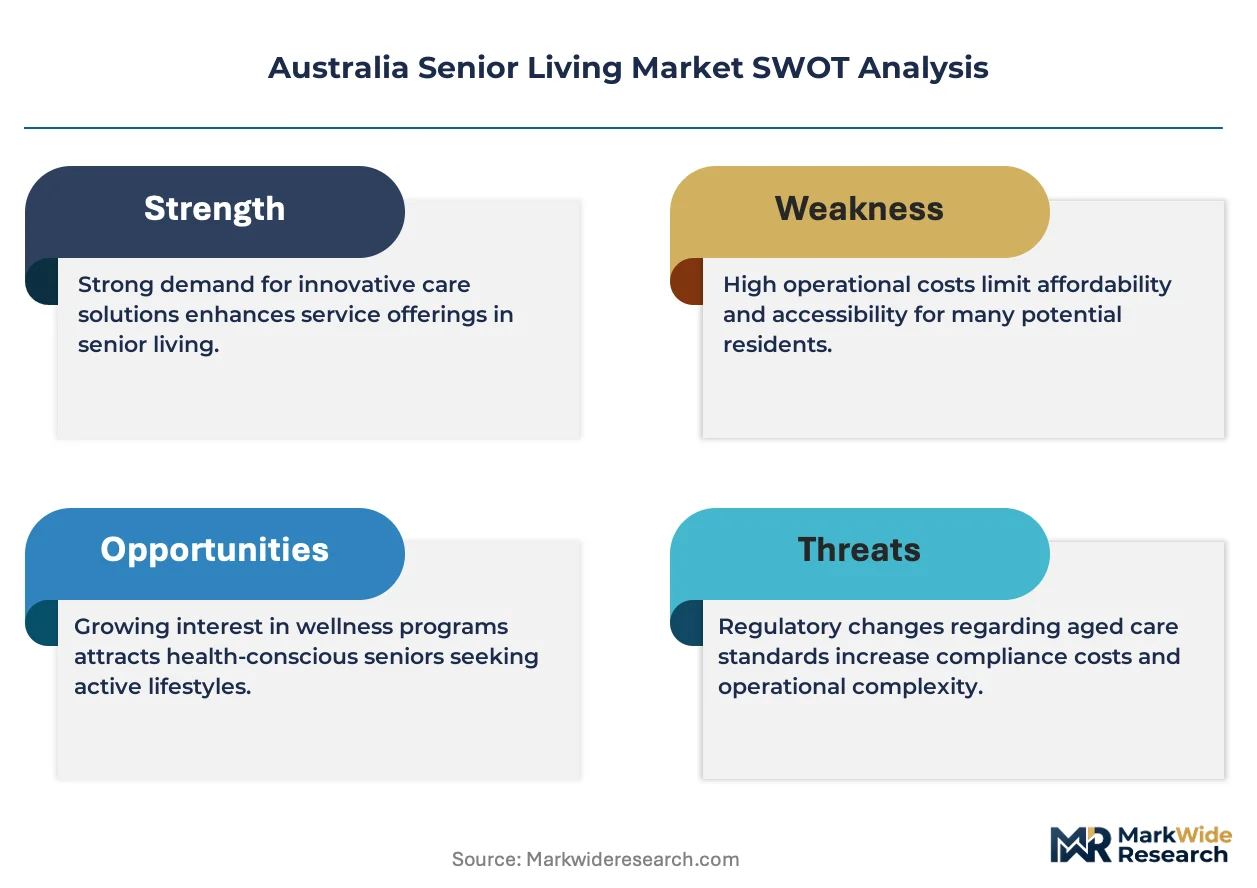
The Aged Care Quality and Safety Commission enforces star-rating transparency that directly shapes consumer choice and facility viability. Aged Care Act reforms and NDIS interface protocols from the National Disability Insurance Agency further determine service bundling obligations and funding access for operators. Stakeholders must monitor regulatory divergence between federally funded aged care and state-level planning controls as the decisive variable for greenfield site feasibility.
Market Dynamics
The Aged Care Quality and Safety Commission's star-rating transparency regime is forcing capital redeployment into dementia-capable infrastructure, compressing development timelines for operators unable to secure premium ratings.
Growth Catalysts
- Downsizing retiree cohorts:Queensland and New South Wales report surging waitlists as coastal retirement communities attract ageing Australians seeking lifestyle transitions without care dependency.
- Aged Care Act reforms:Federal funding accessibility improvements are unlocking capital flows into purpose-built developments that integrate independent living with graduated care escalation.
- Universal design mandates:State-level planning controls in Victoria and South Australia are normalizing accessibility standards that expand addressable demand across mobility-limitation spectrums.
Market Restraints
- Construction cost volatility:Specialist dementia-fitout materials and skilled trades shortages in southeastern states are inflating per-bed development costs beyond feasibility thresholds for mid-tier operators.
- NDIS interface complexity:National Disability Insurance Agency protocol misalignment with aged care funding streams creates administrative friction that delays service bundling approvals.
- Land supply concentration:Greenfield site availability clusters disproportionately in master-planned corridors controlled by integrated developers, limiting independent operator expansion.
Strategic Opportunities
- Regional Queensland penetration:Coastal markets north of Brisbane exhibit supply deficits relative to inbound retiree flows, presenting first-mover advantages for dementia-capable developments.
- Technology convergence:Integration of remote health monitoring with emergency response systems is enabling lower-acuity care models that preserve margin structures.
- Integrated health precincts:State planning incentives for co-located medical services are creating regulatory tailwinds for retirement communities anchoring multi-generational health hubs.
Industry Challenges
- Registered nurse scarcity:Aged care sector wage competition with acute hospitals is intensifying recruitment bottlenecks for 24-hour skilled nursing coverage.
- Compliance timeline compression:Strengthened Aged Care Quality and Safety Commission audit frequencies are forcing operational reconfigurations that disrupt occupancy stability.
- Legacy system integration:Resident management software migration from on-premise to cloud architectures faces data migration risks that threaten care continuity during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Senior Living Market |
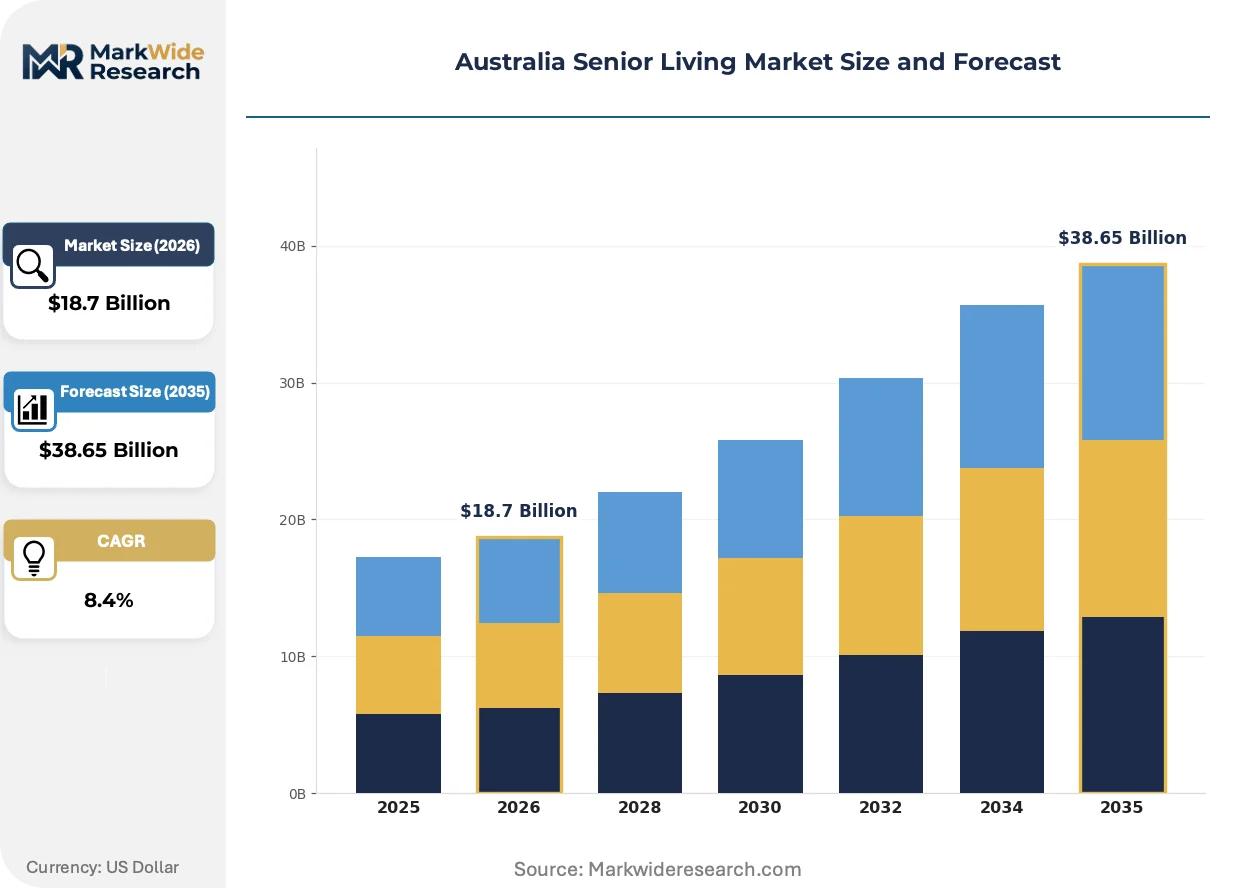
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Independent Living, Assisted Living, Memory Care, Skilled Nursing Facility Type: Retirement Communities, Nursing Homes, Continuing Care Retirement Communities, Senior Apartments Occupancy Model: Ownership, Rental, Leasehold, Shared Ownership End User: Active Seniors, Individuals with Disabilities, Couples, Family Caregivers |
| Companies Covered | Bolton Clarke, Arcare, Opal HealthCare, Lendlease, Stockland, Regis Healthcare, Australian Unity, IRT Group, Estia Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Senior Living Market Emerging Trajectories
Dementia care architecture is migrating from institutional models toward domestic-scale environments that reduce agitation triggers and extend resident independence timelines. This transformation is compressing traditional skilled nursing bed requirements while elevating design specification complexity.
Sensor-based fall detection and ambient monitoring is migrating from reactive alert systems toward predictive analytics platforms that flag mobility deterioration before incident occurrence. Leading operators in New South Wales and Victoria are deploying these systems across independent living units to delay care escalation. The technology is migrating from premium-tier communities into standard offerings as hardware costs decline and insurer risk-adjustment incentives mature.
The Aged Care Quality and Safety Commission's expanded incident reporting mandates are reshaping operational transparency expectations across the sector. Providers must now publish standardized quality indicators that directly influence consumer choice and referral network access. Facilities with sub-four-star ratings face occupancy compression as downsizing retirees prioritize visible quality benchmarks in site selection.
Retiree buyers are compressing decision cycles through digital pre-qualification platforms that virtualize community tours and care-level assessments. This channel shift is displacing traditional referral relationships with aged care assessment teams and financial advisors. The pattern concentrates most visibly in Queensland's southeastern corridor where inbound interstate migrants lack established local advisory networks.
Australia Senior Living Market Segmentation
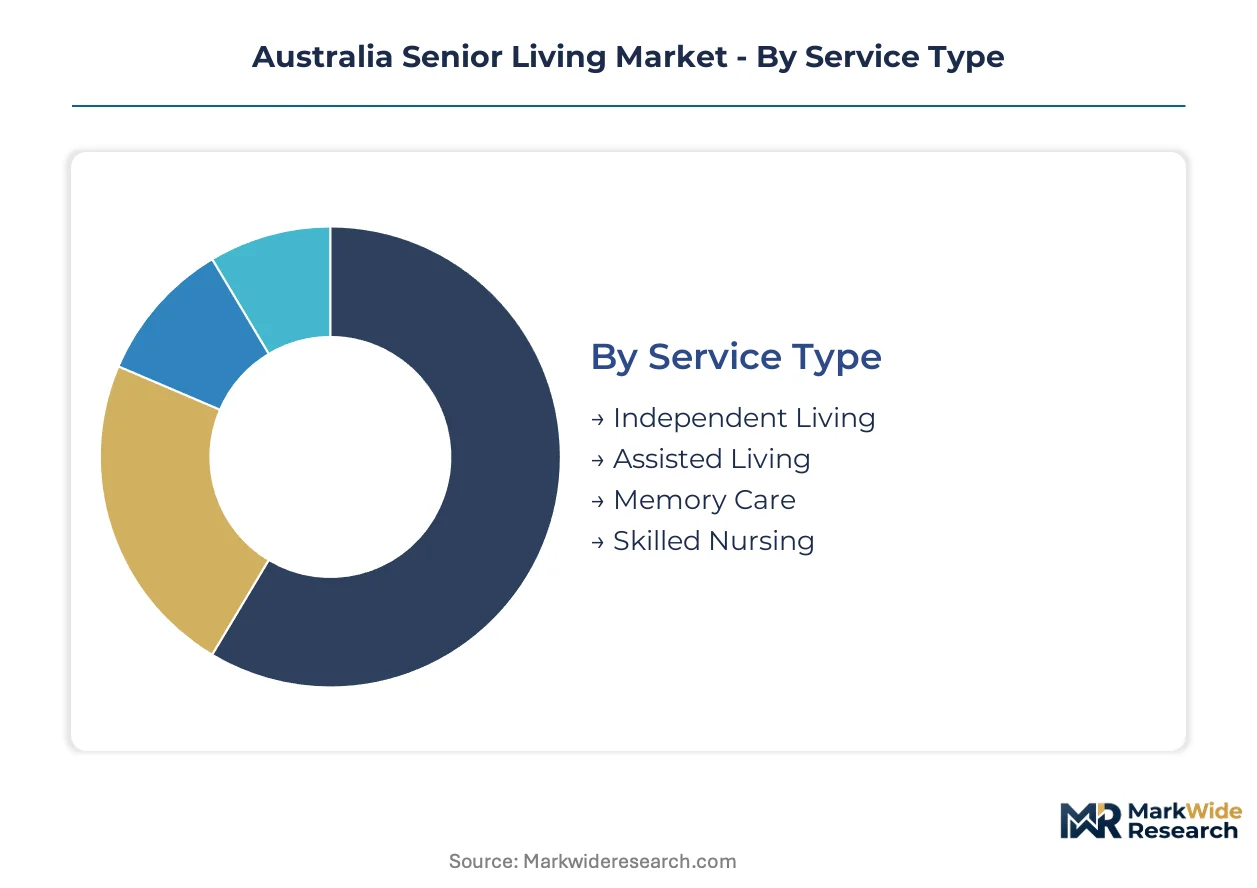
Segmentation in Australian senior living reveals distinct operational economics across care intensity levels. Operators configure service portfolios around regulatory compliance thresholds and land-use planning incentives that vary by state jurisdiction.
Service Type:
After-sales service intensity escalates sharply from independent living through skilled nursing, with care escalation protocols determining lifetime value capture per resident.
- Independent Living:Self-contained dwellings with emergency response systems and optional lifestyle services. Demand concentrates in Queensland's coastal corridors where downsizing retirees seek lifestyle transitions without care dependency.
- Assisted Living:Graduated personal care services including medication management and daily activity support. New South Wales operators report deepest margin pools here due to care premium pricing and regulatory clarity under Aged Care Act reforms.
- Memory Care:Purpose-built dementia-capable environments with specialized staffing ratios and behavioral design protocols. The Aged Care Quality and Safety Commission's star-rating transparency is accelerating capital redeployment into this segment.
- Skilled Nursing:24-hour registered nurse coverage with clinical intervention capabilities. Wage competition with acute hospitals in Victoria and South Australia intensifies recruitment bottlenecks for this segment.
Independent Living holds the largest share; momentum sits with Memory Care.
Facility Type:
Cost tier differentiation separates master-planned integrated developments from retrofit conversions, with capital intensity determining operator entry barriers.
- Retirement Communities:Master-planned developments integrating housing with lifestyle amenities and graduated care access. Lendlease anchors these precincts with co-located medical services in southeastern coastal corridors.
- Nursing Homes:Institutional-scale facilities delivering high-acuity care under federal funding protocols. Compliance timeline compression from strengthened Aged Care Quality and Safety Commission audits disrupts occupancy stability.
- Continuing Care Retirement Communities:Single-site lifetime care progression from independent living through skilled nursing. Bolton Clarke leverages vertical integration to sustain occupancy premiums in these formats.
- Senior Apartments:Age-qualified rental housing without embedded care services. Yield compression pressures this segment as rental-focused models compete with ownership alternatives.
Retirement Communities command premium pricing; Nursing Homes face margin compression from regulatory compliance costs.
Occupancy Model:
Customer type segmentation separates capital-rich downsizers from cash-flow-constrained retirees, shaping fee structures and exit provisions.
- Ownership:Freehold or strata-title purchase with deferred management fees. Arcare deploys this model in purpose-built dementia developments to align resident incentives with care quality investments.
- Rental:Monthly fee structures without capital entry requirements. Queensland's inbound interstate migrants favor this model where local advisory networks are absent.
- Leasehold:Long-term lease arrangements with refundable ingoing contributions. State-level planning controls in Victoria normalize accessibility standards that expand addressable demand under this structure.
- Shared Ownership:Partial equity stakes with operator retention of residual interest. This model reduces entry barriers while preserving operator balance sheet capacity for greenfield development.
Ownership dominates revenue concentration; Rental is expanding most quickly among inbound coastal migrants.
End User:
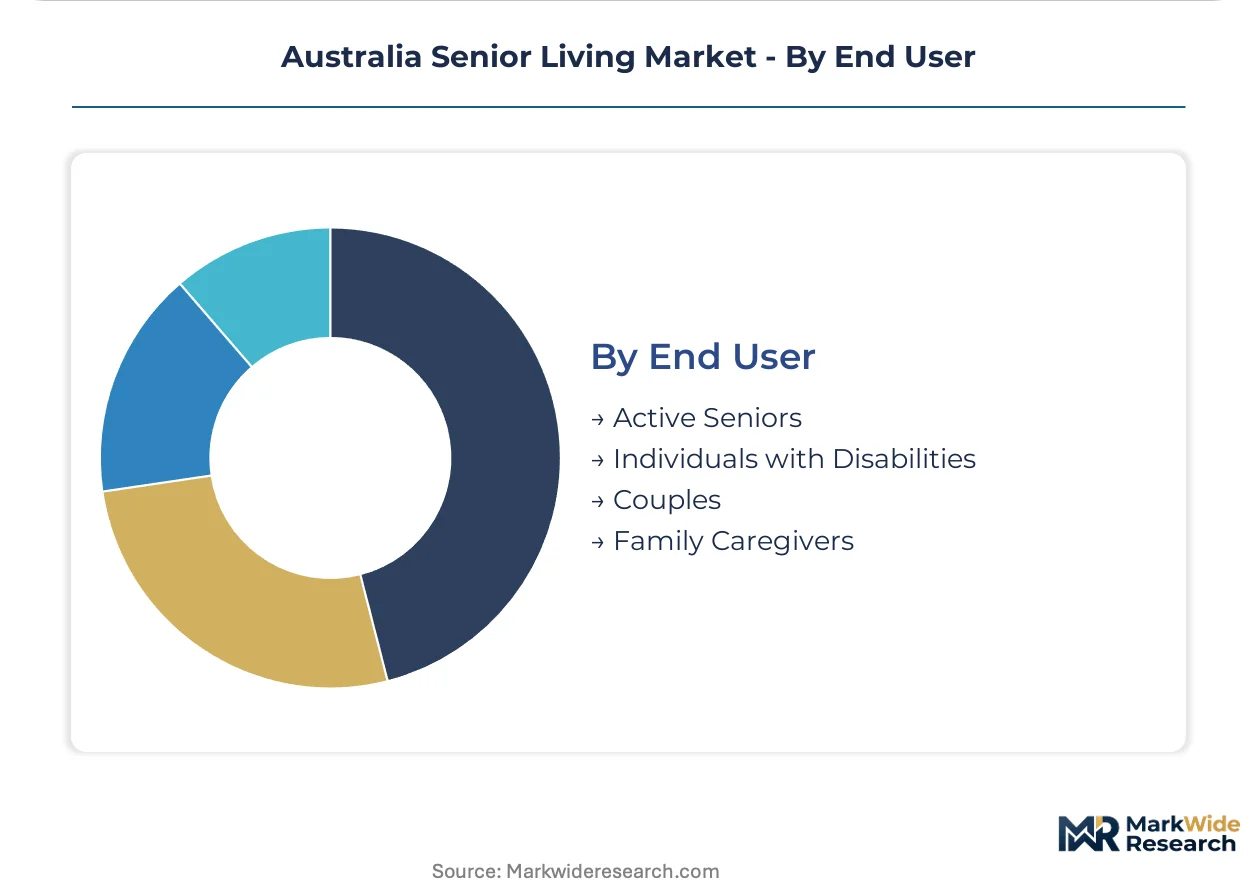
Application-based segmentation aligns service bundling with functional capacity spectra, from fully independent activity to intensive caregiver support requirements.
- Active Seniors:Physically capable retirees seeking lifestyle amenities and social infrastructure. Digital pre-qualification platforms compress their decision cycles in Queensland's southeastern corridor.
- Individuals with Disabilities:Residents requiring NDIS interface protocols alongside aged care funding streams. Administrative friction from National Disability Insurance Agency misalignment delays service bundling approvals.
- Couples:Paired residents with divergent care needs demanding flexible accommodation configurations. Universal design mandates in South Australia expand suitable inventory for this segment.
- Family Caregivers:Informal support networks seeking respite and transitional care options. Sensor-based fall detection systems enable lower-acuity models that preserve their capacity to delay formal care escalation.
Active Seniors represent the largest addressable base; Individuals with Disabilities present the steepest regulatory complexity gradient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Queensland concentrate ownership-model demand from downsizing capital-rich retirees, while Victoria and South Australia skew toward leasehold structures under stricter state-level accessibility mandates. Western Australia's sparse coastal development limits comparable pipeline density.
New South Wales
Downsizing retirees from Sydney's affluent suburbs drive waitlist accumulation in coastal retirement communities from the Central Coast to the Illawarra. The Aged Care Quality and Safety Commission's star-rating transparency shapes site selection decisively. Master-planned developments in the Hunter Region anchor integrated health precincts with co-located medical services.
Queensland
Inbound interstate migrants from Victoria and New South Wales compress decision cycles through digital pre-qualification platforms lacking local advisory networks. State planning controls prioritize greenfield site availability in master-planned corridors. The Sunshine Coast and Gold Coast exhibit acute supply deficits relative to retiree inflow volumes.
Victoria
Universal design mandates normalize accessibility standards that expand addressable demand across mobility-limitation spectrums. The Aged Care Act reforms interface with state-level planning protocols to determine service bundling feasibility. Geelong and the Mornington Peninsula cluster dementia-capable infrastructure investment.
South Australia
Leasehold occupancy models dominate as retirees seek refundable ingoing contributions with lower capital entry barriers. State accessibility standards exceed federal baselines, elevating development specification costs. Adelaide's inner-ring suburbs concentrate retrofit conversions of existing residential stock.
Western Australia
Perth's metropolitan expansion absorbs limited retirement community development relative to eastern state pipelines. Land supply concentration in master-planned corridors favors integrated developers over independent operators. Mandurah and Bunbury anchor sparse coastal retirement offerings.
Australia Senior Living Market Vendor Landscape
Capability concentration sits with vertically integrated care providers; scale advantage sits with diversified property developers. The market structures around three tiers: healthcare-specialist operators, master-planned community developers, and hybrid care-property platforms. Dominant competitive moves include portfolio diversification across care intensity levels and geographic expansion along southeastern coastal corridors.
Within the healthcare-specialist tier, Bolton Clarke and Arcare exemplify vertically integrated care models that sustain occupancy premiums through dementia-capable infrastructure. Lendlease anchors the property-developer archetype, leveraging master-planned precincts with integrated health services. These three occupy distinct strategic positions that collectively span the market's capability requirements.
| Leading Market Players |
|---|
| Bolton Clarke |
| Arcare |
| Opal HealthCare |
| Lendlease |
| Stockland |
| Regis Healthcare |
| Australian Unity |
| IRT Group |
| Estia Health |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on specialist dementia-fitout materials from southeastern Australian suppliers determines both pricing tier spreads and supply chain shape, compressing margins for mid-tier operators while concentrating procurement power with vertically integrated developers controlling master-planned corridors.
Pricing Analysis
Queensland's coastal markets command premiums over South Australian leasehold structures, with three-tier pricing stratification across premium dementia-capable developments, standard assisted-living configurations, and economy rental-focused inventory. Price differentiation hinges on star-rating certification from the Aged Care Quality and Safety Commission and geographic proximity to integrated health precincts. Cost compression in standard assisted-living tiers intensifies as construction material volatility feeds through development budgets. Inbound interstate migrants in Queensland exhibit highest price sensitivity, while downsizing Sydney retirees in New South Wales show lowest elasticity due to accumulated housing equity.
Supply Chain Analysis
Export-control restrictions on sensor-based health monitoring technologies from the United States limit predictive analytics platform deployment across Australian independent living units. Component sourcing concentrates in China for ambient monitoring hardware, Germany for clinical-grade sensor systems, and domestic Australian fabrication for universal design fixtures. Raw material dependencies include lithium-ion battery cells for emergency power systems, specialized acoustic dampening materials for dementia environments, and medical-grade stainless steel for clinical fitouts. Single-source vulnerability runs through Chinese-manufactured fall-detection sensors subject to tariff exposure. Distribution runs through master-planned developer procurement consortia rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing through digital pre-qualification platforms that displace traditional aged care assessment team referral relationships, with interoperability between resident management software and National Disability Insurance Agency protocols determining competitive access.
For Market Incumbents: Build switching-cost moats through cloud-architecture resident management systems that embed operational data and delay competitive displacement. Consolidate position by acquiring regional Queensland development sites ahead of inbound retiree flow acceleration. Counter wage competition from acute hospitals through registered nurse training pipeline investments in partnership with Queensland and New South Wales tertiary institutions. For New Entrants and Emerging Players: Pursue white-space penetration in regional Queensland coastal markets north of Brisbane where supply deficits exceed current development pipelines. Target the memory care segment as the fastest-growing category with lowest incumbent density outside southeastern metropolitan corridors. Deploy direct-to-consumer digital acquisition channels that bypass established referral networks absent among interstate migrant cohorts. For Investors and Strategic Acquirers: Aged Care Act reforms reshape the acquisition landscape by unlocking federal funding accessibility for purpose-built integrated developments. Five-to-ten year viability concentrates on operators with dementia-capable infrastructure already compliant with Aged Care Quality and Safety Commission star-rating thresholds. Monitor NDIS interface protocol standardization as the decisive signal for service bundling margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dementia-Capable Infrastructure Investment | Aged Care Quality and Safety Commission star-rating compliance secures referral network access and occupancy premiums. |
| Cloud-Architecture Resident Management Migration | Operational data portability raises switching costs and enables predictive care escalation analytics. |
| Regional Queensland Greenfield Development | First-mover positioning in supply-constrained coastal corridors captures inbound interstate retiree flows. |
| Integrated Health Precinct Anchoring | State planning incentives for co-located medical services reduce regulatory friction and extend resident lifetime value. |
| NDIS Interface Protocol Standardization | Administrative friction reduction unlocks service bundling approvals for Individuals with Disabilities segment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with aged care facility operators, development project directors, and Aged Care Quality and Safety Commission audit specialists, alongside secondary validation through state-level planning authority filings, National Disability Insurance Agency protocol documentation, and operator star-rating disclosures. Primary fieldwork encompassed facility operators in Queensland and New South Wales, construction procurement managers specializing in dementia-fitout materials, and residential aged care financial planners. Secondary sources included Australian Bureau of Statistics demographic projections, Aged Care Quality and Safety Commission quality indicator datasets, and state planning authority development approval registers. Bottom-up unit economics modeling triangulated against top-down market sizing across service type, facility type, and occupancy model segmentations.
Forecast inputs considered care intensity migration patterns, regulatory compliance timeline compression effects, and inbound interstate retiree flow velocity across the analysis window. Segmentation dimensions modeled encompassed service type transitions, facility type capital intensity tiers, occupancy model preference shifts, and end-user functional capacity spectra. CAGRs derived from cohort-specific demand elasticity coefficients applied to demographic base cases. Industry-specific forecast inputs included dementia prevalence curves among Australians aged over eighty-five and construction cost volatility indices for specialist aged care materials.
Sensitivities concentrate around Aged Care Act implementation pacing, NDIS protocol standardization velocity, and construction material cost trajectories. Forecasts reflect documented assumptions regarding regulatory stability and demographic projection accuracy. Material shifts in federal-state funding interface protocols or acute hospital wage inflation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Audiology Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Medical Spa Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Transitional Care Management Services Market