
 Fully Automated Coagulometer Market | 2026-2036
Fully Automated Coagulometer Market Size, Share, and Industry Trends Forecast 2026-2036
Fully Automated Coagulometer Market Foresight
Integration of artificial intelligence into assay interpretation is rewriting how coagulometers deliver diagnostic confidence. Sysmex Corporation leverages its hematology automation heritage to extend coagulation workflows into consolidated laboratory lines. Werfen anchors its position through specialized hemostasis expertise and deep channel control in European hospital networks. Siemens Healthineers competes by embedding coagulation modules within broader integrated laboratory instruments.
A fully automated coagulometer is a clinical diagnostic instrument that measures blood clotting parameters through optical, mechanical, or electromechanical detection methods, typically processing samples at throughput rates exceeding 100 tests per hour with minimal technician intervention. These systems perform prothrombin time, activated partial thromboplastin time, fibrinogen assays, and D-dimer quantification to guide anticoagulant therapy decisions and pre-surgical risk stratification. Optical coagulometers dominate installed bases due to established reagent ecosystems and broad assay menus, while point-of-care devices represent the fastest-expanding deployment category as health systems push testing closer to emergency departments and catheterization labs. Blood coagulation testing applications capture the largest share of utilization, though monitoring anticoagulant therapy applications are gaining share as direct oral anticoagulant use expands patient volumes requiring routine surveillance.
The FDA enforces quality system regulation and premarket notification requirements for coagulometer manufacturers, while ISO 15189 accreditation standards shape how clinical laboratories validate and operate these instruments within accredited frameworks. The EU MDR and IVDR transition timelines are forcing manufacturers to renew technical documentation and clinical evidence packages for European market access. Stakeholders must monitor how FDA guidance on artificial intelligence-enabled diagnostic devices will reshape algorithm validation requirements and predicate device pathways for next-generation coagulation platforms.
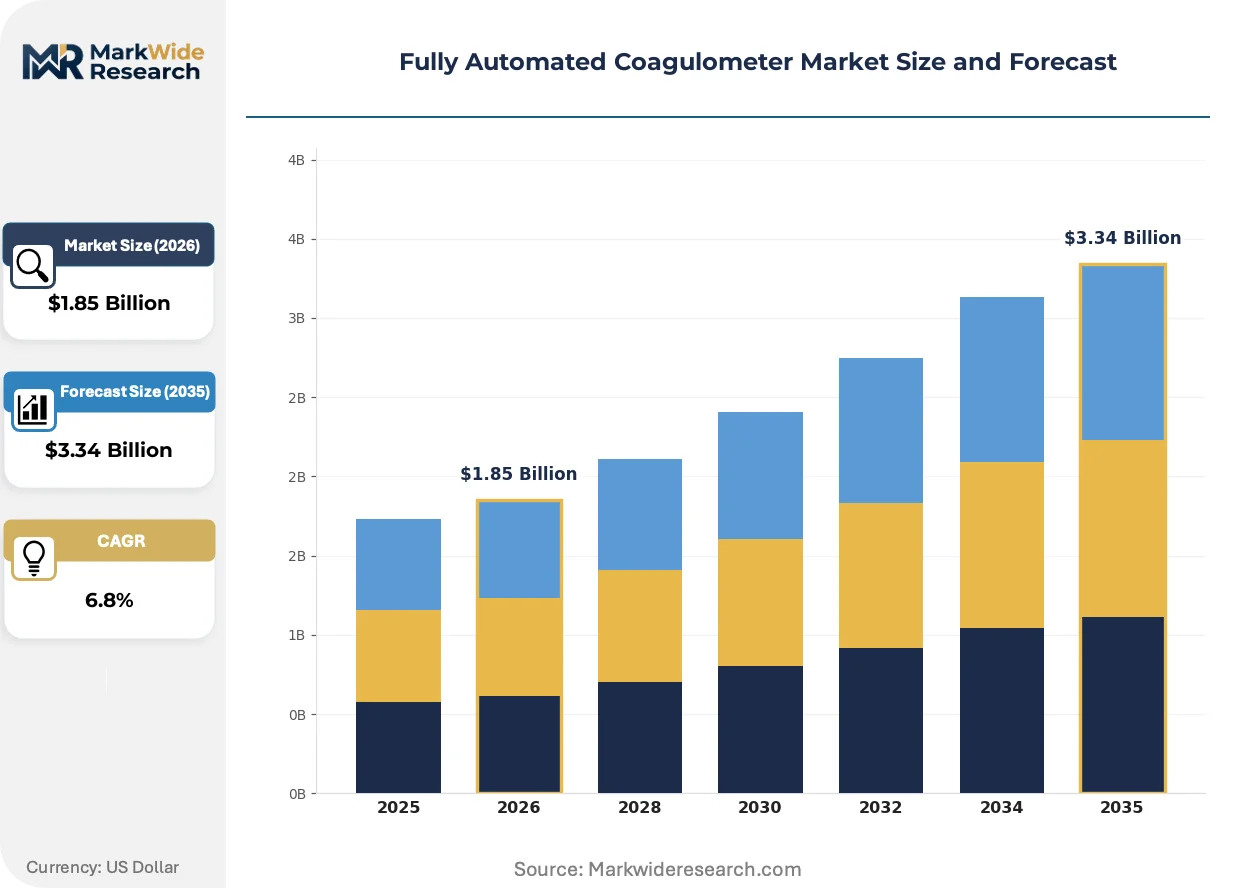
Market Dynamics
Integrated health networks in the United States are consolidating laboratory procurement around high-throughput automation platforms, compressing vendor diversity and elevating platform-scale economics over point-product competition.
Growth Catalysts
- EU IVDR compliance deadlines:The European Union's In Vitro Diagnostic Regulation mandates renewed clinical evidence packages, accelerating replacement cycles for aging installed bases across German and French hospital networks.
- Direct oral anticoagulant expansion:Cardiology departments are scaling routine surveillance testing as DOAC prescribing broadens the addressable patient population requiring periodic coagulation monitoring.
- Optical detection maturation:Established reagent ecosystems and broad assay menus are lowering switching costs for laboratories migrating from semi-automated workflows.
Market Restraints
- Reagent lock-in economics:Closed-system architectures tether operating costs to proprietary consumable pricing, constraining total-cost-of-ownership negotiations for mid-sized clinical laboratories.
- Capital intensity thresholds:High-throughput platforms require substantial upfront investment and dedicated floor space, excluding smaller independent diagnostic facilities from automation upgrades.
- Technical substitution risk:Point-of-care coagulometers are capturing emergency department volume that previously flowed to central laboratory instruments, fragmenting test economics.
Strategic Opportunities
- Underpenetrated Indian diagnostics:Tier-2 and Tier-3 cities present whitespace as CDSCO streamlined approval pathways and PLI scheme incentives attract automation vendors to establish localized service infrastructure.
- AI-enabled assay interpretation:Machine learning algorithms for fibrinogen endpoint detection and D-dimer quantification are creating differentiation vectors beyond hardware specifications.
- Channel innovation through group purchasing:Consolidated procurement entities in the United States are negotiating enterprise-wide automation contracts that bundle coagulation modules with hematology and chemistry lines.
Industry Challenges
- ISO 15189 accreditation complexity:Clinical laboratories face extended validation timelines when migrating to new automation platforms, delaying revenue recognition for equipment vendors.
- Legacy LIS integration friction:Middleware compatibility gaps between next-generation coagulometers and existing laboratory information systems are prolonging implementation cycles and elevating IT consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fully Automated Coagulometer Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Coagulometers, Mechanical Coagulometers, Electromechanical Coagulometers, Immunoturbidimetric Coagulometers, Chromogenic Coagulometers Application: Blood Coagulation Testing, Monitoring Anticoagulant Therapy, Diagnosing Hemophilia, Detecting Thrombophilia, Pre-Surgical Screening End User: Clinical Laboratories, Diagnostic Centers, Research Institutes, Blood Banks, Biopharmaceutical Companies Deployment: Standalone Systems, Integrated Laboratory Instruments, Point-of-Care Devices, Bench-Top Analyzers |
| Companies Covered | Siemens Healthineers, Werfen, HORIBA, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Sysmex Corporation, Haemonetics Corporation, Diagnostica Stago, Maccura Biotechnology Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fully Automated Coagulometer Market Shifts & Advancements
Artificial intelligence integration and regulatory harmonization pressures are simultaneously elevating performance expectations and compressing product development timelines across the coagulation diagnostics sector.
Electromechanical detection methods are hybridizing with optical architectures to expand assay compatibility beyond traditional plasma-based testing. Academic medical centers in Japan and South Korea are piloting these hybrid platforms for whole-blood hemostasis assessment in trauma settings. The convergence is compressing the historical segmentation between central laboratory and near-patient testing modalities.
FDA guidance on artificial intelligence-enabled diagnostic devices is reshaping algorithm validation requirements for next-generation platforms. Predicate device pathways are narrowing as the agency demands prospective clinical performance data for AI-augmented coagulation interpretation. Manufacturers targeting the United States market are restructuring quality management systems to accommodate premarket submission requirements for software-as-medical-device components.
Health system consolidation is concentrating purchasing authority within integrated delivery networks that negotiate multi-year automation contracts spanning multiple diagnostic disciplines. Independent service organizations are displacing manufacturer-direct service models in secondary markets where response time commitments outweigh brand loyalty. This shift is most pronounced in the United States, where IDN procurement offices now control instrumentation decisions previously delegated to individual laboratory directors.
Fully Automated Coagulometer Market Segmentation
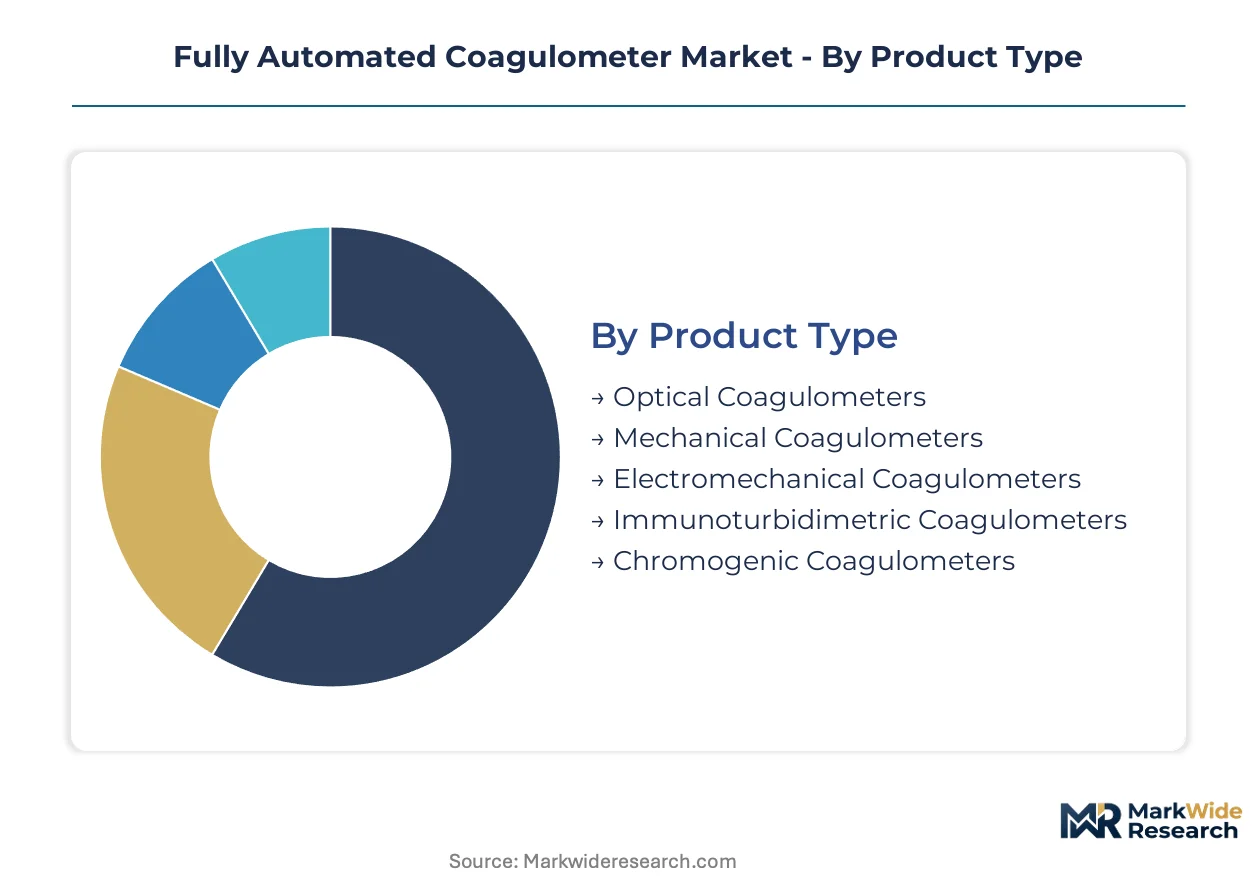
Segmentation in fully automated coagulometers reveals how detection physics, clinical workflow integration, and procurement authority reshape vendor competitive position. Laboratories select platforms based on throughput requirements, reagent ecosystem maturity, and health network standardization mandates.
Product Type:
Cost tier differentiation across detection architectures determines laboratory switching economics and vendor margin structures.
- Optical Coagulometers:These systems employ turbidimetric or nephelometric light scatter detection to measure clot formation kinetics in plasma samples. German and French hospital networks concentrate procurement around established optical platforms due to broad assay menus and mature reagent supply chains. FDA quality system regulations favor predicate device pathways for optical architectures, compressing regulatory timelines for incremental hardware upgrades.
- Mechanical Coagulometers:Mechanical detection uses physical probe movement to sense fibrin strand formation, offering assay compatibility with viscous or lipemic samples that confound optical methods. Demand concentrates in Japanese academic medical centers pursuing whole-blood hemostasis research. The technology commands premium pricing but faces constrained installed base expansion due to narrower reagent ecosystems.
- Electromechanical Coagulometers:Hybrid architectures combining electronic signal processing with mechanical sensing elements.
- Immunoturbidimetric Coagulometers:Specialized platforms for D-dimer and fibrin degradation product quantification using antigen-antibody complex detection.
- Chromogenic Coagulometers:Colorimetric substrate-based systems for specific factor assays and antithrombin activity measurement.
Optical Coagulometers hold installed capacity. Electromechanical Coagulometers is rotating up the share rankings.
Application:
Clinical utility intensity varies sharply across hemostasis testing workflows, with surveillance applications expanding faster than diagnostic screening.
- Blood Coagulation Testing:Routine prothrombin time and activated partial thromboplastin time screening for coagulation pathway integrity assessment. United States integrated delivery networks standardize on high-throughput automation for this volume category, negotiating enterprise contracts that bundle coagulation with chemistry and hematology lines.
- Monitoring Anticoagulant Therapy:Therapeutic drug monitoring for warfarin, heparin, and direct oral anticoagulants requiring precise INR and anti-Xa quantification. Cardiology departments across United States health systems are scaling testing frequency as DOAC prescribing broadens, making this application the steepest expansion trajectory within hemostasis diagnostics.
- Diagnosing Hemophilia:Factor activity assays and inhibitor detection for congenital bleeding disorder characterization.
- Detecting Thrombophilia:Genetic and acquired hypercoagulability testing including protein C, protein S, and antithrombin deficiency screening.
- Pre-Surgical Screening:Coagulation status verification prior to invasive procedures to inform transfusion planning.
Blood Coagulation Testing anchors laboratory throughput economics. Monitoring Anticoagulant Therapy is climbing the fastest in absolute test volume.
End User:
Customer type concentration determines service infrastructure requirements and contract negotiation leverage across the value chain.
- Clinical Laboratories:Hospital-based and reference laboratories processing >100 coagulation samples daily with dedicated automation lines. United States health system consolidation has concentrated purchasing authority within integrated network procurement offices, displacing individual laboratory director decision rights.
- Diagnostic Centers:Independent outpatient facilities serving physician office referrals with moderate test volumes. Indian tier-2 and tier-3 cities present whitespace as CDSCO streamlined approval pathways and PLI scheme incentives attract automation vendors to establish localized service presence.
- Research Institutes:Academic centers pursuing hemostasis mechanism studies and assay development.
- Blood Banks:Transfusion services performing donor screening and component therapy quality verification.
- Biopharmaceutical Companies:Drug development organizations requiring coagulation safety profiling for anticoagulant and hemostatic therapeutic candidates.
Clinical Laboratories command platform standardization authority. Diagnostic Centers is gaining share fastest among non-hospital settings.
Deployment:
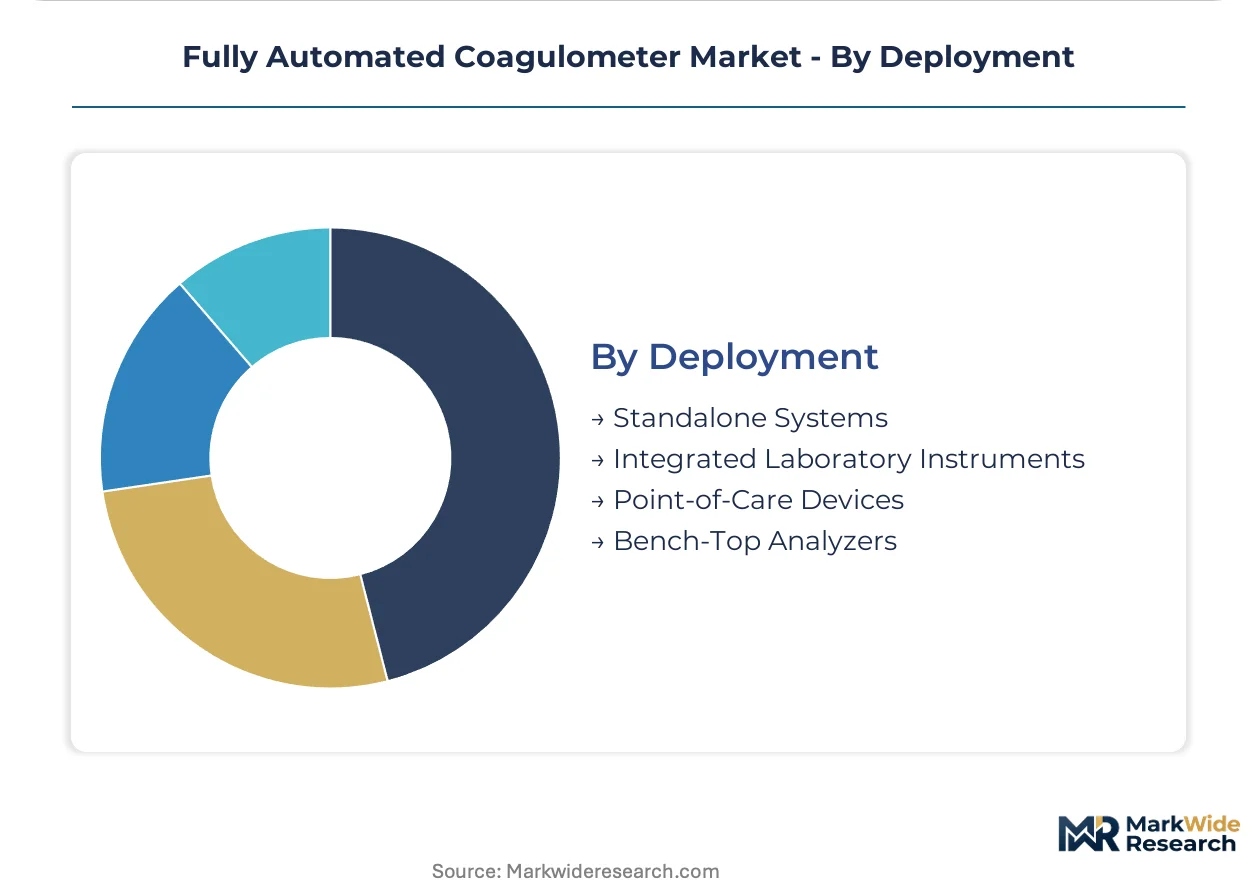
Physical configuration and workflow integration depth segment procurement criteria across central laboratory and distributed testing environments.
- Standalone Systems:Dedicated coagulation analyzers operating independently within laboratory automation islands. Mid-sized United States hospitals favor these for flexibility during phased automation upgrades, though middleware compatibility gaps with legacy LIS systems prolong implementation cycles.
- Integrated Laboratory Instruments:Coagulation modules embedded within consolidated chemistry-immunoassay-hematology automation tracks. Large United States integrated delivery networks concentrate procurement here, negotiating multi-year contracts that span diagnostic disciplines and compress vendor diversity.
- Point-of-Care Devices:Portable or compact systems deployed in emergency departments, catheterization labs, and operating suites. Emergency departments across United States health systems are pushing testing closer to clinical decision points, fragmenting test economics that previously flowed to central laboratories.
- Bench-Top Analyzers:Compact moderate-throughput systems for small laboratories or specialized research applications.
Integrated Laboratory Instruments hold enterprise contract value. Point-of-Care Devices is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in coagulation diagnostics favor established manufacturing hubs in Germany and Japan, while import dependence shapes procurement patterns in India and Brazil. The United States maintains a net importer position for high-throughput automation platforms. Regulatory divergence between FDA quality system requirements and EU IVDR compliance timelines is fragmenting vendor certification strategies across major markets.
United States
Integrated delivery networks in Texas and California are consolidating laboratory procurement around enterprise automation contracts spanning multiple diagnostic disciplines. FDA quality system regulations for in vitro diagnostic devices mandate rigorous design controls and post-market surveillance, elevating compliance costs for foreign manufacturers. The Boston-Cambridge medical technology cluster anchors domestic R&D activity for next-generation coagulation platforms with AI-enabled interpretation.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are accelerating replacement cycles for aging coagulometer installed bases ahead of EU IVDR compliance deadlines. The EU MDR and IVDR transition timelines force manufacturers to renew technical documentation and clinical evidence packages for European market access. Frankfurt and Munich host concentrated service infrastructure supporting Central European laboratory automation deployments.
Japan
Academic medical centers in Tokyo and Osaka are piloting hybrid electromechanical-optical platforms for whole-blood hemostasis assessment in trauma settings. METI industrial standards shape domestic validation requirements for coagulation instrumentation. The Kobe-Osaka medical device manufacturing corridor supplies precision optical components for regional coagulometer production.
India
Tier-2 and Tier-3 cities present whitespace as CDSCO streamlined approval pathways and PLI scheme incentives attract automation vendors to establish localized service infrastructure. The country's national pharmaceutical regulator has simplified import licensing for diagnostic instruments, reducing time-to-market for foreign manufacturers. Maharashtra and Karnataka clusters are emerging as diagnostic service hubs supporting hospital network expansion.
Brazil
ANVISA regulatory harmonization with FDA standards is accelerating market access for US and European coagulometer manufacturers. São Paulo and Rio de Janeiro hospital networks drive demand for high-throughput automation as private healthcare consolidation proceeds. Import dependence for precision diagnostic equipment creates pricing pressure from currency volatility and logistics costs.
Fully Automated Coagulometer Market Competitive Landscape
On the supply side, the industry is consolidating around platform-scale vendors with integrated reagent ecosystems and multi-discipline automation portfolios. Three archetypes dominate: hematology-automation heritage players extending into coagulation workflows, specialized hemostasis pure-plays with deep clinical expertise, and diversified medtech conglomerates embedding coagulation modules within broader laboratory lines. Competitive moves center on enterprise contract bundling across diagnostic disciplines and AI-enabled assay interpretation differentiation.
Within the specialized hemostasis tier, Werfen and Diagnostica Stago exemplify deep clinical expertise and channel control in European hospital networks. Sysmex Corporation occupies a position leveraging hematology automation heritage to extend coagulation workflows into consolidated laboratory lines. Siemens Healthineers anchors the diversified conglomerate archetype, embedding coagulation capabilities within integrated laboratory instrument platforms.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Werfen |
| HORIBA |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Sysmex Corporation |
| Haemonetics Corporation |
| Diagnostica Stago |
| Maccura Biotechnology Co. Ltd |
| Others |
Supply & Pricing Matrix
Frankfurt-Mumbai air freight corridors carry precision optical components for coagulometer manufacturing, with per-kilogram cost volatility directly compressing margin structures for mid-tier systems while enabling premium pricing for vendors with captive component stocks in Germany and Japan.
Pricing Analysis
Current-generation optical platforms command 40-60% premiums over prior-generation mechanical systems, while next-generation AI-enabled hybrid architectures stratify pricing further through software licensing tiers. Pricing stratifies across premium, standard, and economy tiers based on throughput capacity and reagent ecosystem breadth, with FDA predicate device status and ISO 15189 pre-validation certificates serving as key differentiation drivers. Pricing pressure stems from point-of-care device commoditization in emergency department settings, eroding central laboratory test economics. Independent diagnostic centers exhibit highest price sensitivity, while United States integrated delivery networks prioritize total-cost-of-ownership over unit pricing.
Supply Chain Analysis
Export control restrictions on precision photonics and semiconductor-grade sensors constrain component flows from Germany, Japan, and the United States to emerging manufacturing hubs. Optical detection modules draw from specialized glass foundries in Schott AG's supply network, precision motors from Japanese automation component specialists, and application-specific integrated circuits from Taiwanese foundries. Single-source vulnerability concentrates in high-numerical-aperture objective lenses, where two German suppliers dominate global capacity. Distribution runs through manufacturer-direct service organizations in primary markets and independent service organizations in secondary geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States integrated delivery networks consolidate procurement authority, fragmenting vendor diversity and elevating platform-scale contract negotiations over point-product competition.
For Market Incumbents: Build reagent ecosystem lock-in moats through exclusive assay menu development and middleware integration investments that elevate switching costs for hospital laboratory customers. Defend against point-of-care substitution by embedding coagulation modules within broader hematology-chemistry automation tracks that health networks standardize across enterprise footprints. Prioritize backward integration into precision optical component supply to insulate margins from freight volatility and export licensing delays. For New Entrants and Emerging Players: Build out localized service infrastructure in Indian tier-2 and tier-3 cities ahead of CDSCO approval pathway maturation, capturing whitespace before established vendors establish field presence. Target diagnostic center deployments with compact standalone systems that bypass integrated delivery network procurement gatekeepers. Pursue channel partnerships with independent service organizations to achieve response time parity without manufacturer-direct field investment. For Investors and Strategic Acquirers: Specialized hemostasis pure-plays with deep European hospital channel control and ISO 15189 pre-validated platforms represent attractive acquisition targets as regulatory complexity elevates barriers to organic market entry. Long-term viability hinges on AI-enabled assay interpretation capabilities that reshape competitive differentiation beyond hardware specifications. Watch FDA guidance finalization on software-as-medical-device classification as an inflection indicator for algorithm-centric valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Assay Interpretation Development | Machine learning endpoint detection creates differentiation beyond optical throughput specifications for fibrinogen and D-dimer quantification. |
| EU IVDR Technical Documentation Renewal | Clinical evidence package upgrades secure European market access for aging installed base replacement cycles in German and French networks. |
| Hospital System Partnership Expansion | Enterprise automation contracts spanning coagulation, hematology, and chemistry disciplines compress vendor diversity within integrated delivery networks. |
| Point-of-Care Device Portfolio Launch | Emergency department and catheterization lab deployment captures volume fragmenting from central laboratory economics. |
| Reimbursement Strategy Alignment | DOAC monitoring test codes and coverage determinations shape addressable patient population expansion for surveillance applications. |
Research Methodology
A standing panel of hospital laboratory directors, GPO contracts managers, biomedical engineers, and IVD regulatory affairs specialists provided ongoing calibration against primary fieldwork and secondary validation sources. Interview data triangulated against FDA 510(k) premarket notification filings, EU IVDR technical documentation databases, hospital procurement contract repositories, and ISO 15189 accreditation records. Bottom-up instrument shipment modeling and top-down health system capital expenditure analysis converged on volume and value estimates.
Scenario bracketing around EU IVDR compliance deadlines, DOAC prescribing trajectories, and point-of-care substitution rates bounded projection uncertainty across the analysis window. Segmentation modeling incorporated detection architecture, application intensity, end-user procurement authority, and deployment configuration dimensions. CAGRs derived from instrument replacement cycle analysis, reagent annuity per installed base, and test volume elasticity to anticoagulant therapy expansion.
Stress conditions across freight cost volatility, export licensing delays, and health system consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology substitution thresholds. Material shifts in FDA software-as-medical-device classification or EU IVDR notified body capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market