
 Metabolomics Services Market | 2026-2036
Metabolomics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Metabolomics Services Market Outlook
Academic core facility networks is fragmenting as commercial metabolomics service providers build direct-to-biopharma relationships outside traditional institutional channels. Thermo Fisher Scientific leverages its installed base of mass spectrometry instruments to bundle instrument service contracts with metabolomics analysis packages. Agilent Technologies competes through specialized chromatography-mass spectrometry workflows tailored to lipidomics and exposome profiling. Metabolon anchors its position with proprietary metabolite reference libraries that standardize output across multi-site clinical studies.
Metabolomics services encompass the systematic identification and quantification of small-molecule metabolites in biological samples, typically employing mass spectrometry platforms achieving detection thresholds below nanomolar concentrations to map metabolic pathway perturbations. These services support pharmaceutical development by revealing drug mechanism-of-action, toxicity biomarkers, and patient stratification signatures before clinical trials advance. Metabolic profiling leads service type demand as sponsors require longitudinal metabolite tracking across preclinical and phase-one studies. Drug development applications command the strongest growth trajectory among application categories, driven by regulatory pressure for mechanistic toxicology data. Mass spectrometry technology dominates analytical throughput where speed and sensitivity determine contract competitiveness.
FDA biomarker qualification programs and EPA metabolomics guidelines for chemical safety assessment shape service validation standards and data submission requirements for US-based providers. EMA's qualification opinion pathway for novel methodologies and REACH substance testing mandates in Europe create parallel compliance architectures that multinational service laboratories must maintain. ISO 17025 accreditation and OECD test guideline harmonization further constrain market entry for laboratories lacking documented quality management systems. Stakeholders must monitor evolving regulatory acceptance of metabolite-based surrogate endpoints as this determines which service offerings transition from exploratory research to registrational support.
Market Dynamics
Precision medicine pipelines are forcing pharmaceutical sponsors to demand longitudinal metabolite tracking across preclinical and phase-one studies, compressing contract timelines and elevating analytical sensitivity requirements for service providers.
Growth Catalysts
- FDA Biomarker Qualification Programs:These pathways accelerate regulatory acceptance of metabolite-based surrogate endpoints, enabling service providers to transition exploratory research into registrational support contracts.
- Pharmaceutical Development Pipelines:Mechanistic toxicology data requirements now mandate metabolic profiling before clinical trial advancement, embedding metabolomics services into standard drug development workflows.
- Mass Spectrometry Platform Sensitivity:Detection thresholds below nanomolar concentrations allow mapping of subtle metabolic pathway perturbations, expanding addressable study designs for biopharma sponsors.
Market Restraints
- ISO 17025 Accreditation Burden:Documented quality management systems require substantial upfront investment, constraining market entry for laboratories lacking established compliance infrastructure.
- Specialized Talent Scarcity:Shortages of mass spectrometry operators and metabolite annotation specialists limit service expansion velocity for commercial providers.
- Instrument Capital Intensity:High-resolution mass spectrometry platforms and chromatography systems demand significant fixed capital deployment, pressuring margin structures for mid-scale laboratories.
Strategic Opportunities
- EU AI Act Clinical Decision Support:Compliance requirements for AI-enabled metabolite interpretation create demand for validated analytical workflows and qualified algorithmic tools.
- Exposome Profiling Applications:Environmental health agencies and toxicology programs are expanding contract scopes beyond pharmaceutical applications into chemical safety assessment.
- Academic-Industrial Consortia:Large-scale metabolic profiling initiatives in Germany and Japan offer multi-year funding vehicles for service providers with multi-site standardization capabilities.
Industry Challenges
- Multi-Site Data Harmonization:Proprietary metabolite reference libraries and inconsistent annotation protocols complicate cross-laboratory comparability for multi-center clinical studies.
- OECD Test Guideline Alignment:Evolving harmonization requirements demand continuous method revalidation, extending certification timelines and increasing operational overhead.
- Legacy LIMS Integration:Electronic data capture systems at established pharmaceutical sponsors require custom middleware development, delaying contract startup and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metabolomics Services Market |
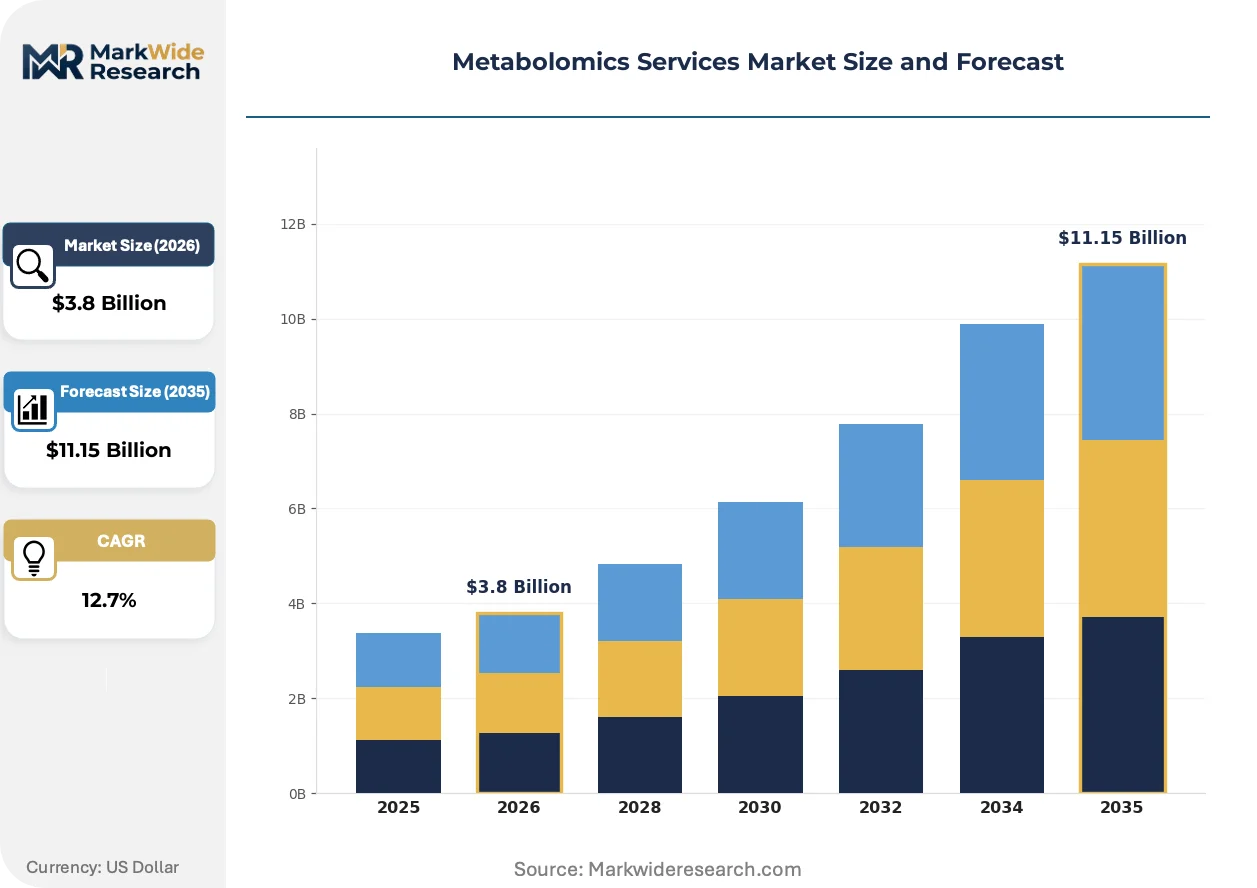
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analysis, Sample Preparation, Metabolic Profiling, Biomarker Discovery Application: Clinical Diagnostics, Drug Development, Nutritional Analysis, Environmental Monitoring End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Clinical Laboratories Technology: Mass Spectrometry, Nuclear Magnetic Resonance, Chromatography, Spectroscopy |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Waters Corporation, Metabolon, Bruker Corporation, Biocrates Life Sciences, PerkinElmer, SCIEX, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metabolomics Services Market Strategic Shifts
Artificial intelligence is penetrating metabolite identification workflows, compressing annotation timelines while regulatory bodies simultaneously tighten algorithmic validation requirements for clinical decision support.
High-resolution mass spectrometry combined with ion mobility separation is rendering obsolete traditional quadrupole-based screening methods in toxicology biomarker discovery. Pharmaceutical toxicology groups are adopting these platforms within eighteen-month equipment refresh cycles. The structural consequence is a bifurcation between laboratories capable of untargeted profiling and those restricted to targeted panels.
REACH substance testing mandates in Europe now explicitly reference metabolomics readouts for chemical safety dossiers. ECHA guidance documents are pressuring contract research organizations to adopt standardized reporting formats. German industrial chemical manufacturers are consolidating vendor relationships with laboratories holding dual EPA and ECHA method qualifications.
Biopharma sponsors are unbundling analytical services from full-service clinical research contracts, establishing direct procurement relationships with specialized metabolomics providers. This disintermediation bypasses traditional core facility networks and consolidates spending with vendors offering proprietary reference libraries. The United States exhibits the most pronounced channel shift, with Boston and San Francisco biotech clusters leading the transition.
Metabolomics Services Market Segmentation
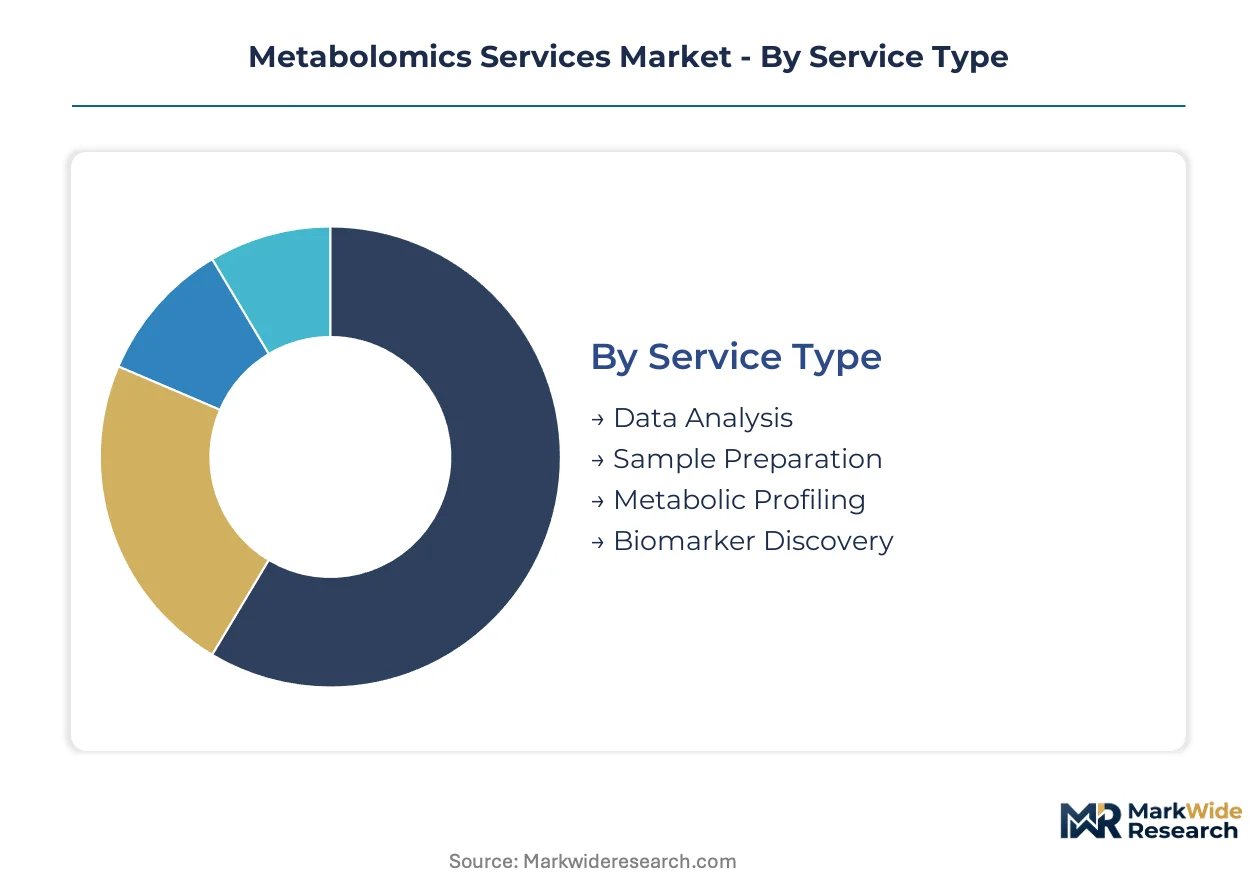
Metabolomics services fragment across technical capabilities, regulatory compliance tiers, and sponsor integration depth. Each segment commands distinct pricing structures and renewal economics based on analytical complexity and data deliverable formats.
Service Type:
After-sales service intensity varies dramatically across service types, with longitudinal data interpretation contracts requiring multi-year scientific support versus one-time sample processing engagements.
- Metabolic Profiling:Systematic identification and quantification of small-molecule metabolites using mass spectrometry platforms achieving nanomolar detection thresholds. Demand concentrates in United States biotech clusters where FDA biomarker qualification programs require longitudinal metabolite tracking across preclinical phases. Sponsors prioritize vendors with documented multi-site standardization protocols.
- Biomarker Discovery:Untargeted screening workflows to identify novel metabolic signatures for patient stratification or toxicity prediction. German and Japanese academic-industrial consortia fund large-scale initiatives, creating multi-year contract vehicles for providers with proprietary reference libraries.
- Data Analysis:Computational pipelines for metabolite annotation, pathway mapping, and statistical interpretation of complex datasets.
- Sample Preparation:Extraction, derivatization, and quality-controlled processing of biological specimens prior to instrumental analysis.
Metabolic profiling holds the largest share; momentum sits with biomarker discovery.
Application:
Cost tier differentiation separates exploratory research contracts from registrational support engagements requiring ISO 17025 accreditation and OECD guideline alignment.
- Drug Development:Mechanistic toxicology studies, pharmacokinetic profiling, and patient stratification for clinical trial design. Pharmaceutical sponsors in Boston and San Francisco clusters unbundle these services from full-service CRO contracts, establishing direct procurement with specialized metabolomics providers. Regulatory pressure for mechanistic data embeds metabolic profiling into standard development workflows.
- Clinical Diagnostics:Metabolite-based assays for disease screening, treatment monitoring, and personalized medicine applications. EU AI Act compliance requirements for clinical decision support algorithms reshape validation standards for AI-enabled interpretation tools.
- Environmental Monitoring:Exposome profiling and chemical safety assessment under EPA and ECHA guidelines.
- Nutritional Analysis:Metabolic phenotyping for diet intervention studies and functional food development.
Drug development commands premium pricing; clinical diagnostics is expanding most quickly.
End User:
Customer type determines contract structure, with pharmaceutical sponsors demanding dedicated scientific liaisons versus academic clients accepting standardized service catalogs.
- Pharmaceutical Companies:Precision medicine pipelines drive adoption as sponsors require mechanistic toxicology data before clinical trial advancement. Direct-to-biopharma relationships now bypass traditional academic core facility networks, consolidating spending with vendors offering bundled instrument service contracts.
- Academic Institutions:Core facility networks face fragmentation as commercial providers build external relationships. Research grants from NIH and European consortia fund exploratory metabolic profiling without registrational compliance requirements.
- Research Organizations:Contract research organizations serving chemical and agricultural sectors.
- Clinical Laboratories:Hospital-affiliated and independent diagnostic facilities seeking validated metabolite assays.
Pharmaceutical companies hold the largest share; clinical laboratories are gaining share fastest.
Technology:
Platform maturity separates laboratories capable of untargeted profiling from those restricted to targeted panels, with capital intensity determining competitive viability.
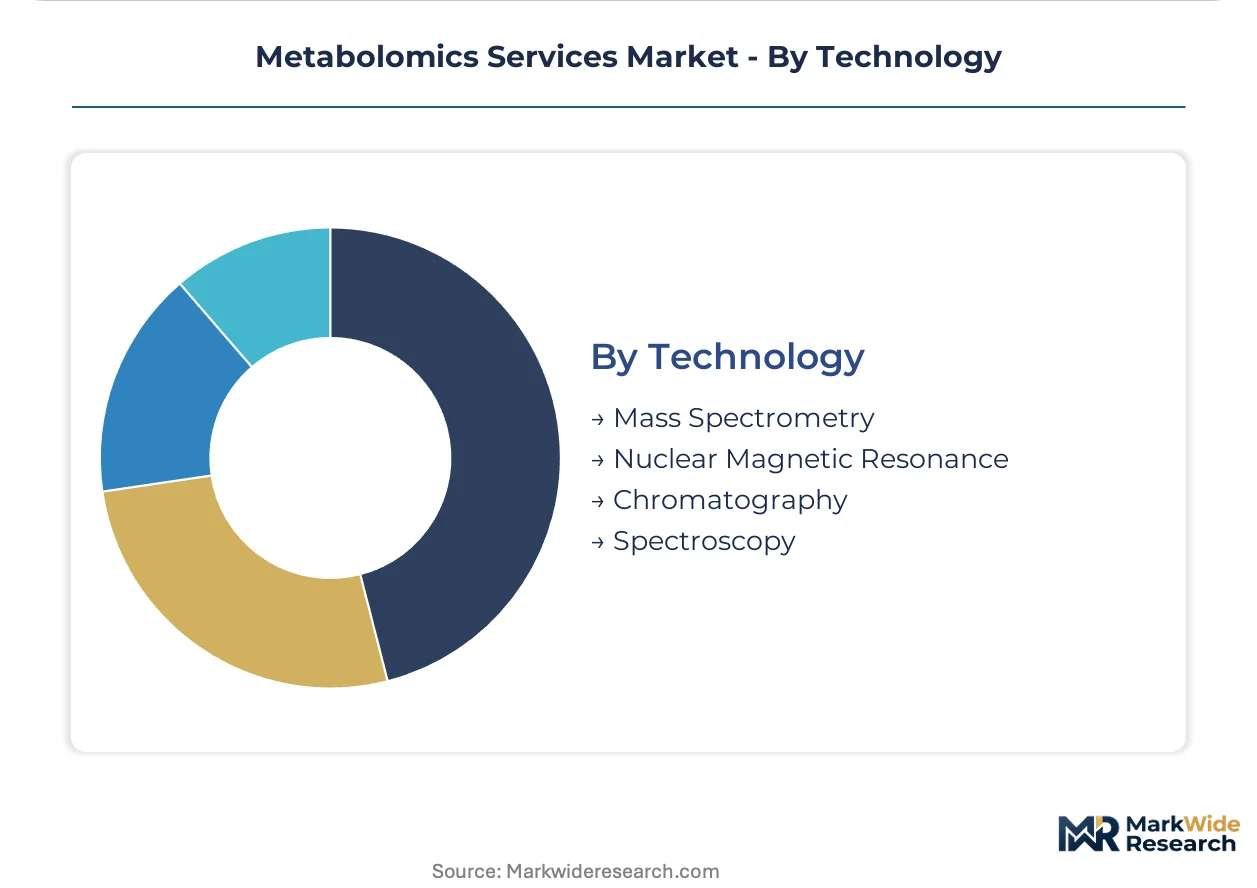
- Mass Spectrometry:High-resolution platforms with ion mobility separation render obsolete traditional quadrupole methods in toxicology biomarker discovery. Detection thresholds below nanomolar concentrations determine contract competitiveness for subtle pathway perturbation mapping. Equipment refresh cycles compress to eighteen months in pharmaceutical toxicology groups.
- Chromatography:Gas and liquid chromatography systems coupled to mass detection for metabolite separation. Specialized workflows for lipidomics and exposome profiling differentiate Agilent Technologies' competitive positioning in Germany and Japan.
- Nuclear Magnetic Resonance:Non-destructive structural confirmation and quantitative metabolite analysis.
- Spectroscopy:Infrared and Raman methods for rapid screening applications.
Mass spectrometry holds the largest share; chromatography shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where FDA and EMA biomarker qualification programs command premium contract rates, while Japanese laboratories compete on multi-site standardization capabilities rather than margin expansion.
United States
Biotech clusters in Boston and San Francisco unbundle metabolomics services from full-service CRO contracts, establishing direct procurement relationships with specialized providers. FDA biomarker qualification programs accelerate regulatory acceptance of metabolite-based surrogate endpoints. Pharmaceutical sponsors in these coastal hubs embed longitudinal metabolite tracking into standard preclinical development workflows.
Germany
Industrial chemical manufacturers consolidate vendor relationships with laboratories holding dual EPA and ECHA method qualifications for REACH substance testing dossiers. ECHA guidance documents pressure contract research organizations to adopt standardized reporting formats. Academic-industrial consortia in Bavaria and North Rhine-Westphalia fund large-scale metabolic profiling initiatives with multi-year contract vehicles.
Japan
METI-funded precision medicine initiatives drive demand for multi-site standardization capabilities across pharmaceutical development pipelines. PMDA consultation frameworks shape validation requirements for metabolite-based clinical decision support tools. The Kanto region around Tokyo anchors concentration of mass spectrometry service providers serving domestic and Asia-Pacific biopharma sponsors.
United Kingdom
NIHR and MRC research grants fund exploratory metabolic profiling without registrational compliance requirements, supporting academic core facility networks. MHRA alignment with EMA qualification opinion pathways creates parallel compliance architectures for multinational service laboratories. The Cambridge-Oxford-London golden triangle concentrates contract research activity in mechanistic toxicology applications.
China
NMPA innovation pathways for novel biomarker methodologies expand addressable service scopes for domestic and multinational pharmaceutical sponsors. GB standards harmonization with OECD test guidelines extends certification timelines for laboratories seeking dual qualification. The Yangtze River Delta region around Shanghai hosts emerging metabolomics service capacity serving both domestic biotech and international contract manufacturing organizations.
Metabolomics Services Market Competitive Environment
Instrument-anchored conglomerates and specialized metabolomics boutiques split the market along capital intensity and scientific depth vectors. Thermo Fisher Scientific and Agilent Technologies leverage installed bases of mass spectrometry and chromatography platforms to bundle hardware service contracts with analytical packages. Three strategic archetypes dominate: integrated instrument-service providers, reference library specialists, and clinical CRO-embedded laboratories. Consolidation pressures concentrate among mid-scale laboratories lacking ISO 17025 accreditation, while technology licensing partnerships proliferate between AI-enabled interpretation software developers and established analytical service providers.
Within the instrument-anchored tier, Thermo Fisher Scientific exemplifies bundling strategies that combine mass spectrometry hardware maintenance with metabolomics analysis packages. Agilent Technologies occupies a position emphasizing specialized chromatography-mass spectrometry workflows for lipidomics and exposome profiling applications. Metabolon anchors the reference library specialist archetype, with proprietary metabolite libraries that standardize output across multi-site clinical studies. These three representatives illustrate divergent competitive vectors: hardware ecosystem lock-in, workflow specialization, and data standardization infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Waters Corporation |
| Metabolon |
| Bruker Corporation |
| Biocrates Life Sciences |
| PerkinElmer |
| SCIEX |
| Charles River Laboratories |
| Others |
Value Chain & Pricing Dynamics
The Boston biotech cluster anchors North American metabolomics service capacity, with its concentration of mass spectrometry platforms and specialized annotation talent creating downstream pricing leverage for registrational support contracts. This geographic density allows providers to command premium rates for FDA biomarker qualification programs while mid-scale laboratories in secondary markets face margin compression from capital intensity and ISO 17025 compliance overhead.
Pricing Analysis
Configured-to-order pricing for longitudinal clinical studies commands spreads of 40-60% above standard sample processing rates. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and analytical complexity. Pricing pressure stems from eighteen-month equipment refresh cycles in pharmaceutical toxicology groups, which force depreciation costs into contract rates. Academic institutions exhibit highest price sensitivity, while Boston and San Francisco biotech sponsors prioritize multi-site standardization over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for chromatography consumables and specialized reagents. Manufacturing concentration centers on Germany, Japan, and the United States for high-resolution mass spectrometry platforms. The supply chain draws from proprietary metabolite reference libraries, certified reference standards, and ion mobility separation technologies. Single-source vulnerability persists for advanced mass spectrometry detectors from Japanese suppliers. Distribution runs through direct procurement relationships with pharmaceutical sponsors, bypassing traditional core facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as pharmaceutical development pipelines rebound from prior retrenchment, with precision medicine investments driving longitudinal metabolite tracking demand.
For Market Incumbents: Entrench position through backward integration into proprietary metabolite reference libraries, mirroring Metabolon's standardization infrastructure. Lock in multi-year instrument service contracts with Thermo Fisher Scientific and Agilent Technologies to create switching costs. Defend against AI-enabled interpretation startups by accelerating OECD test guideline alignment before algorithmic validation requirements tighten.
For New Entrants and Emerging Players: Build out capacity in exposome profiling applications where EPA and ECHA guidelines are expanding contract scopes beyond pharmaceutical verticals. White-space exists in clinical laboratory partnerships for validated metabolite assays, as hospital-affiliated facilities seek ISO 17025-accredited providers. Target German industrial chemical manufacturers consolidating vendor relationships for REACH substance testing dossiers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because biomarker qualification pathways and AI Act compliance create durable moats for accredited providers. Acquisition targets should display dual EPA-ECHA method qualifications and documented multi-site standardization protocols. The signal to watch is PMDA consultation framework expansions for metabolite-based clinical decision support tools in Japan.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | Unlocks registrational support contracts requiring FDA biomarker qualification program compliance. |
| Proprietary Reference Library Development | Standardizes output across multi-site clinical studies, creating data harmonization lock-in with sponsors. |
| AI-Enabled Interpretation Partnership | Addresses EU AI Act clinical decision support requirements while compressing metabolite annotation timelines. |
| Academic-Industrial Consortium Engagement | Captures multi-year funding vehicles in Germany and Japan for large-scale metabolic profiling initiatives. |
| Dual EPA-ECHA Method Qualification | Qualifies providers for consolidated vendor relationships with industrial chemical manufacturers under REACH mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA biomarker qualification guidance documents, EMA qualification opinion pathways, and OECD test guideline harmonization records. Interviews with drug development executives, regulatory affairs leads at contract research organizations, mass spectrometry platform engineers, and hospital procurement managers informed demand-side dynamics. Secondary validation drew from EPA metabolomics guidelines, ECHA guidance documents for REACH substance testing, METI precision medicine initiative disclosures, and SEC filings from instrument-anchored conglomerates. Bottom-up service provider capacity modeling triangulated against top-down pharmaceutical R&D spending allocation analysis.
Forecast inputs include mass spectrometry platform refresh cycle timing, biomarker qualification program expansion trajectories, and academic-industrial consortium funding patterns across the analysis window. Segmentation modeling incorporated service type complexity tiers, application regulatory compliance requirements, end-user contract structure preferences, and technology platform sensitivity thresholds. CAGRs derived from longitudinal tracking of contract value per study phase and sponsor unbundling behavior from full-service CRO relationships. Industry-specific inputs encompass PMDA consultation framework evolution and NMPA innovation pathway adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-enabled interpretation software developers or instrument manufacturers into direct service provision would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Spa Services Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Funeral Products and Services Market