
 Minimally Invasive Cosmetic Procedures Market | 2026-2036
Minimally Invasive Cosmetic Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Cosmetic Procedures Market Outlook
Single-source supply agreements for neurotoxin raw materials is pivoting toward multi-source contracts as manufacturers seek supply resilience. AbbVie Inc. leverages captive fermentation capacity to anchor its Botox franchise against emerging biosimilar threats. Galderma S.A. sustains global dermal filler leadership through integrated hyaluronic acid polymer science and direct-to-physician training academies. Merz Pharma competes on incobotulinumtoxinA purity positioning and differentiated Radiesse calcium hydroxylapatite formulation.
Minimally invasive cosmetic procedures encompass needle-based or energy-based interventions that alter superficial anatomy without excisional surgery, typically employing injectable neuromodulators, dermal fillers, or selective photothermolysis at wavelengths between 755 nm and 1064 nm to achieve temporary aesthetic modification. Botox and dermal fillers command the largest revenue pools due to repeat treatment cycles and high physician familiarity, while laser hair removal occupies a mature position with slower growth but stable clinic throughput. Chemical peels retain niche status in physician offices but face compression from at-home acid formulations and patient preference for zero-downtime alternatives.
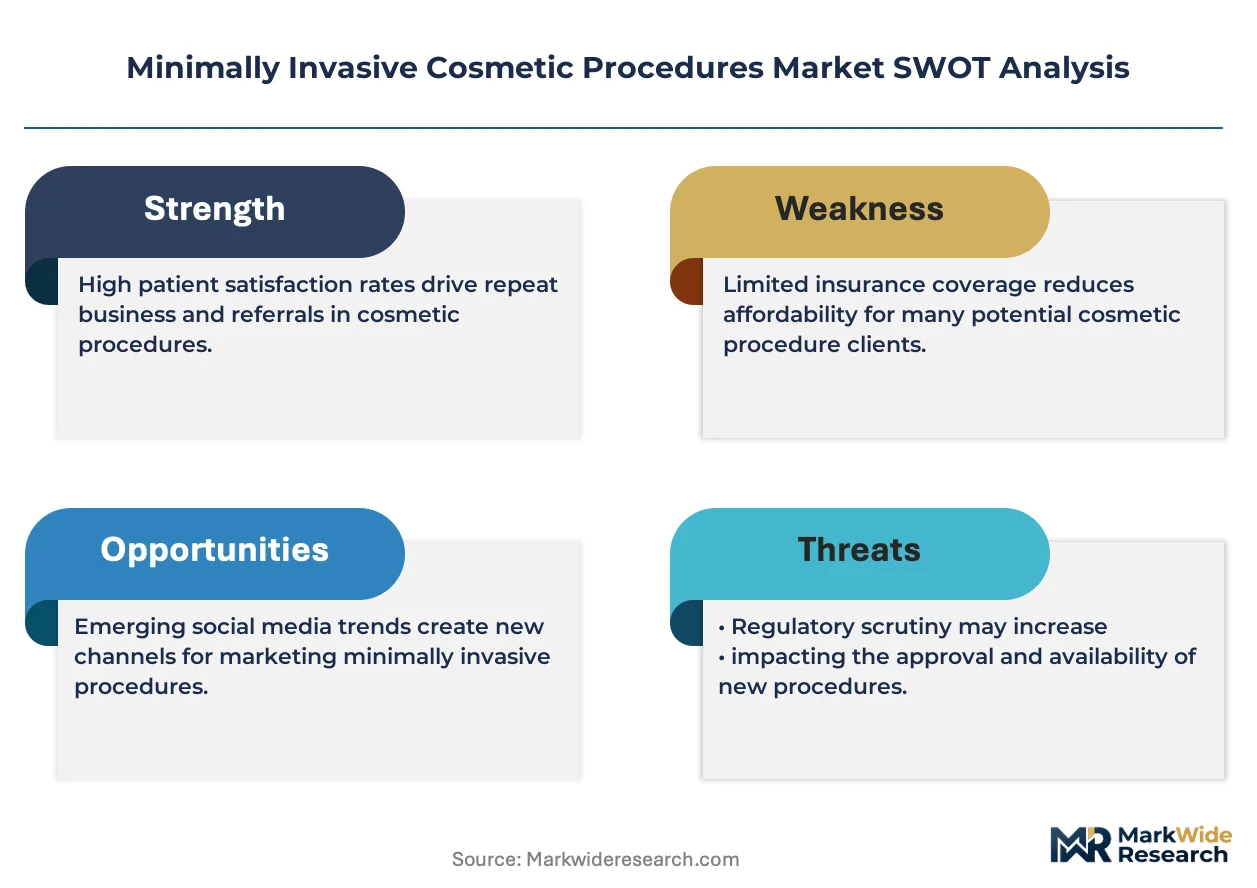
FDA 510(k) and PMA pathways govern device-based treatments in the United States, while the EU Medical Device Regulation and CE marking requirements impose clinical evidence standards that filter out lower-quality laser and radiofrequency platforms. HIPAA compliance shapes how virtual consultation delivery methods collect and store patient imaging data, creating infrastructure costs that favor scaled telehealth platforms over independent practitioners. Stakeholders must monitor how FDA draft guidance on compounded biologics intersects with state-level scope-of-practice expansions for non-physician injectors, as this regulatory boundary will determine addressable market breadth and liability exposure.
Market Dynamics
Supply chain reconfiguration around neurotoxin raw materials is forcing manufacturers to abandon single-source dependencies, with multi-source fermentation contracts now dominating procurement strategy across the injectables segment.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter clinical evidence requirements for laser and radiofrequency platforms filter out low-quality competitors, concentrating revenue among compliant device manufacturers with robust technical files.
- Med-spa chains:Scaled clinic networks achieve operational density that reduces per-treatment overhead while standardizing injection protocols across multiple metropolitan markets.
- Hyaluronic acid polymer science:Cross-linking innovations extend dermal filler duration from six to eighteen months, compressing treatment frequency and improving lifetime patient value metrics.
Market Restraints
- Clostridium botulinum strain concentration:Fermentation capacity for neurotoxin raw material concentrates among three specialized biologics suppliers, creating input bottlenecks during demand surges.
- FDA 510(k) clinical evidence thresholds:Device manufacturers face extended timelines for laser platform clearances as the agency demands larger safety datasets for novel wavelength combinations.
- At-home acid formulations:Consumer-grade chemical peel alternatives capture price-sensitive patients seeking zero-downtime options, compressing physician-office peel volumes.
Strategic Opportunities
- Brazil's interior cities:Physician density expansion beyond São Paulo and Rio de Janeiro creates addressable market growth in tertiary aesthetic clinics with limited competitor saturation.
- Telehealth consultation platforms:HIPAA-compliant virtual pre-screening reduces patient acquisition costs while capturing geographic markets beyond clinic catchment radii.
- MFDS fast-track pathways:South Korea's abbreviated review for innovative biologics accelerates market entry timelines for next-generation neuromodulator formulations.
Industry Challenges
- Injector certification standardization:State-level scope-of-practice expansions for non-physician nurse practitioners create liability exposure variations that complicate national training academy deployment.
- Compounded biologics compliance:FDA draft guidance on 503A pharmacy compounding intersects with state medical board enforcement, generating uncertainty around off-label neurotoxin sourcing legality.
- Legacy laser platform obsolescence:Practices face capital replacement cycles for 755 nm alexandrite systems as dual-wavelength platforms with integrated cooling demand upfront investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Cosmetic Procedures Market |
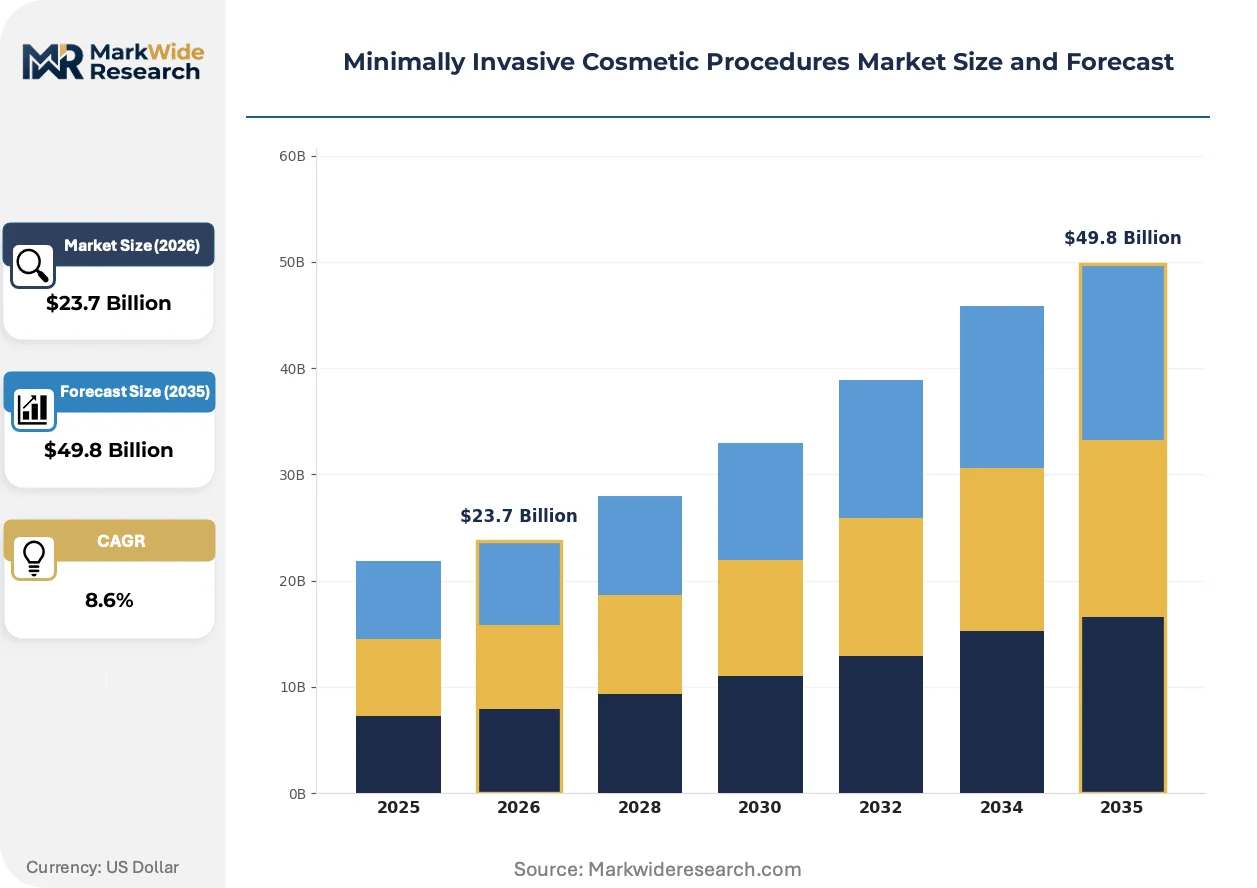
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Botox, Dermal Fillers, Laser Hair Removal, Chemical Peels Target Demographic: Women, Men, Young Adults, Seniors Treatment Area: Face, Neck, Hands, Body Delivery Method: In-office, At-home Kits, Mobile Clinics, Virtual Consultations |
| Companies Covered | AbbVie Inc., Galderma S.A., Merz Pharma, Cutera Inc., Hologic Inc., Bausch Health Companies Inc., Candela Medical, Alma Lasers, InMode Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Cosmetic Procedures Market Strategic Shifts
Energy-based modalities and biologics manufacturing are converging to reshape treatment protocols, with wavelength engineering and fermentation optimization driving the next wave of competitive differentiation.
Microfocused ultrasound with visualization (MFU-V) is electrifying facial lifting protocols by enabling practitioners to target specific tissue planes at depths of 1.5 mm to 4.5 mm with real-time imaging feedback. Dermatology clinics in Seoul and Los Angeles adopt MFU-V at replacement pace for older radiofrequency-only platforms. The technology is electrifying premium service tier creation, with per-treatment pricing separating high-precision ultrasound guidance from conventional energy delivery.
FDA draft guidance on compounded biologics is tightening documentation requirements for 503A pharmacies sourcing neurotoxins, forcing clinic procurement officers to verify supply chain provenance through manufacturer direct purchasing agreements. State medical boards in Texas and Florida align inspection protocols with federal standards, creating compliance cost advantages for scaled clinic groups with dedicated regulatory staff. The guidance most affects independent med-spa operators without pharmacy benefit management infrastructure.
Direct-to-physician training academies are displacing third-party continuing medical education providers as manufacturers embed device-specific certification into purchase contracts. Galderma's injection technique certification and Merz's Radiesse placement workshops now precede product account activation, locking in supply relationships before competitors reach prospects. This channel consolidation is most visible in the United States, where manufacturer-sponsored education credits satisfy state licensure renewal requirements.
Minimally Invasive Cosmetic Procedures Market Segmentation
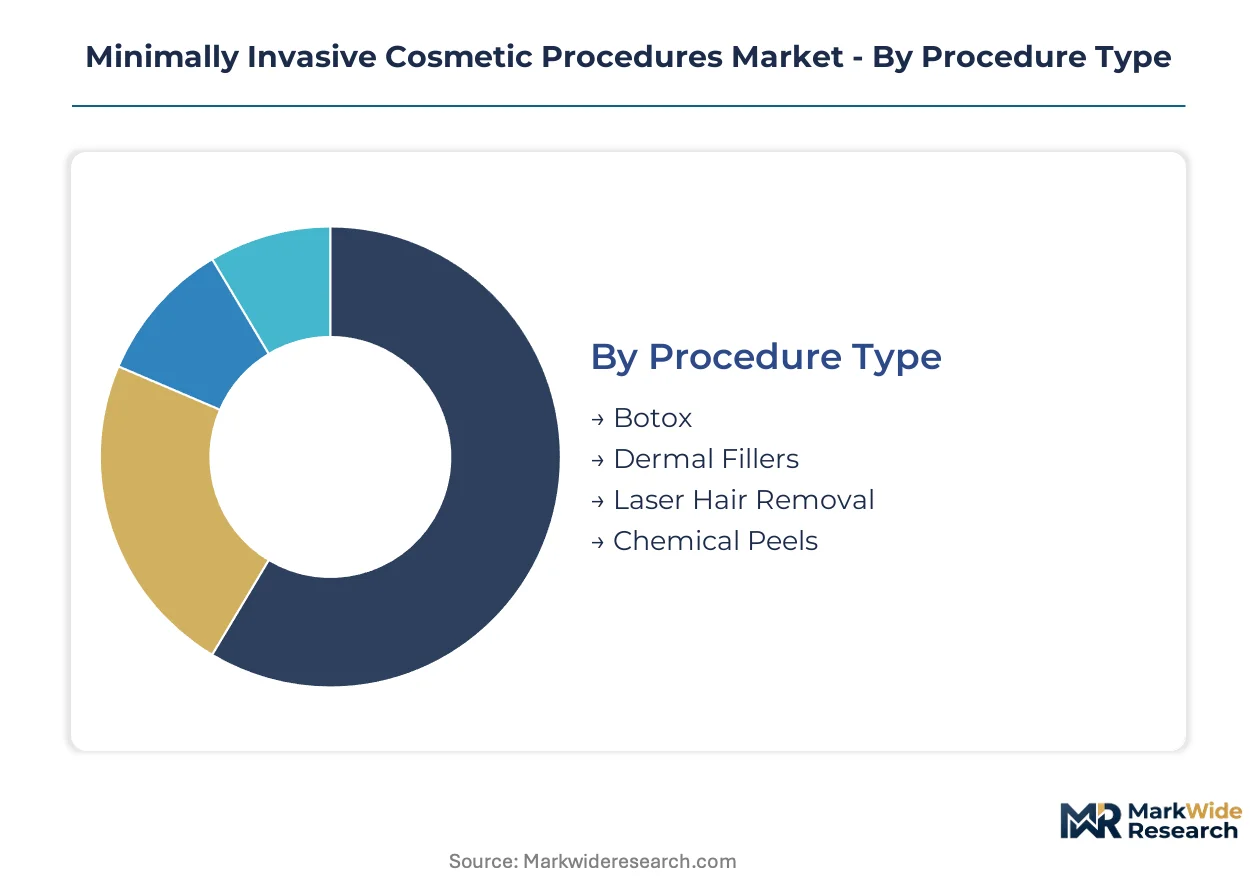
Segmentation in minimally invasive cosmetic procedures reveals how treatment protocols, patient profiles, and delivery infrastructure fragment into distinct commercial battlegrounds. Each dimension carries unique margin structures, regulatory exposure, and capital requirements that shape competitive entry decisions.
Procedure Type:
Customization intensity spans from standardized neurotoxin units to fully individualized laser parameter sets across this category.
- Botox:Purified botulinum toxin type A delivered via intramuscular injection to temporarily paralyze targeted facial muscles. Demand concentrates in the United States where physician density and repeat treatment culture sustain the highest injection frequency per capita. FDA clearance pathways create formulation-specific moats that protect incumbent franchises.
- Dermal Fillers:Cross-linked hyaluronic acid or calcium hydroxylapatite formulations injected subdermally to restore volume or contour. South Korea drives fastest adoption through MFDS fast-track pathways that accelerate next-generation polymer launches. Treatment duration extension from six to eighteen months compresses visit frequency while raising per-session value.
- Laser Hair Removal:Selective photothermolysis at 755 nm to 1064 nm wavelengths targeting melanin in hair follicles.
- Chemical Peels:Acid-based exfoliation protocols ranging from superficial glycolic to deep phenol formulations.
Most installed capacity flows through Botox. Expansion is steepest in Dermal Fillers.
Target Demographic:
Price sensitivity and treatment motivation diverge sharply across life-stage and gender lines in this category.
- Women:Historical core patient base driving volume across all procedure categories with established treatment-seeking behavior and referral networks.
- Men:Fastest-growing patient segment as workplace aesthetic expectations and social media visibility reshape male grooming norms. Brazil and South Korea show highest male penetration rates where cultural stigma around cosmetic intervention has eroded most quickly.
- Young Adults:Preventive neurotoxin use beginning in mid-twenties as "prejuvenation" philosophy spreads through social media channels.
- Seniors:Volume restoration and skin laxity correction demand with higher per-treatment spending but lower visit frequency.
Women still account for the majority of procedures performed. Men are expanding most quickly as a share of new patient acquisitions.
Treatment Area:
Anatomical complexity and complication risk escalate from flat surfaces to mobile expressive regions in this category.
- Face:Highest procedure density across all modalities with greatest practitioner specialization and premium pricing power.
- Neck:Emerging high-growth zone as platysmal banding and submental fat treatments gain protocol standardization.
- Hands:Volume restoration demand concentrated among senior demographics seeking to address visible aging markers.
- Body:Contouring and fat reduction applications with lower visit frequency but higher per-session revenue.
Face procedures dominate current installed base. Neck treatments are climbing the fastest as technique refinement expands safe treatment zones.
Delivery Method:
Capital intensity and regulatory burden separate physical infrastructure from digital-first models in this category.
- In-office:Physician-supervised procedures in dedicated clinical settings with full device and biologic portfolios available.
- At-home Kits:Consumer-grade chemical peel and microcurrent devices capturing price-sensitive segments with zero-downtime preference. FDA oversight of device claims shapes permissible marketing language.
- Mobile Clinics:Van-based or pop-up delivery models expanding access in Brazil's interior cities beyond São Paulo and Rio de Janeiro catchment areas.
- Virtual Consultations:HIPAA-compliant telehealth pre-screening reducing patient acquisition costs and extending geographic reach beyond physical clinic radii.
In-office delivery commands the largest revenue pool. Virtual Consultations are gaining share fastest as telehealth infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors global demand for minimally invasive cosmetic procedures, with South Korea's physician density and cultural normalization of aesthetic treatments establishing the benchmark for per-capita injection frequency and technology adoption velocity.
United States
Med-spa chains drive volume expansion through standardized protocols and operational density across metropolitan markets. FDA 510(k) and PMA pathways govern device clearances, with extended timelines for novel wavelength combinations. Los Angeles and Miami concentrate premium service tiers where MFU-V platforms replace legacy radiofrequency systems.
South Korea
MFDS fast-track pathways accelerate next-generation neuromodulator and dermal filler launches, compressing market entry timelines versus Western regulators. Seoul's Gangnam district clusters over 500 aesthetic clinics within a single municipality, creating intense price competition and rapid technique diffusion.
Brazil
Physician density expansion beyond São Paulo and Rio de Janeiro opens tertiary markets with limited competitor saturation. ANVISA registration requirements align with international standards while mobile clinic models penetrate interior cities. Campinas and Curitiba emerge as secondary hubs for procedure volume growth.
Germany
EU Medical Device Regulation clinical evidence standards filter lower-quality laser platforms, concentrating revenue among compliant manufacturers with robust technical files. Munich and Düsseldorf host specialized dermatology networks that integrate manufacturer training academies into procurement relationships.
United Arab Emirates
Dubai's medical tourism infrastructure attracts cross-border patients seeking premium aesthetic services unavailable in home markets. MOHAP licensing requirements for injectable procedures create compliance barriers that favor scaled clinic groups with dedicated regulatory staff over independent operators.
Minimally Invasive Cosmetic Procedures Market Competitive Environment
Global majors compete with regional champions across biologics manufacturing and energy-based device platforms, with market structure consolidating around three specialized fermentation suppliers for neurotoxin raw materials and a tiered device landscape separating premium laser manufacturers from commoditized radiofrequency alternatives. Strategic archetypes include captive biologics producers with backward-integrated fermentation capacity, integrated dermal filler specialists with polymer science capabilities, and pure-play energy device manufacturers with wavelength engineering expertise. Dominant competitive moves encompass multi-source supply contract reconfiguration for input resilience and direct-to-physician training academy deployment to lock in supply relationships.
Within the captive biologics tier, AbbVie Inc. exemplifies fermentation-backed market anchoring, while Galderma S.A. and Merz Pharma occupy positions as integrated specialists spanning both biologics and device adjacencies. These three entities represent distinct strategic postures: fermentation-scale defense against biosimilar threats, hyaluronic acid polymer science leadership with embedded education infrastructure, and purity-positioned neurotoxin differentiation alongside calcium hydroxylapatite formulation expertise.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Galderma S.A. |
| Merz Pharma |
| Cutera Inc. |
| Hologic Inc. |
| Bausch Health Companies Inc. |
| Candela Medical |
| Alma Lasers |
| InMode Ltd. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up med-spa chains anchor pricing discipline through volume-based procurement leverage while simultaneously reshaping supply contracting toward multi-source fermentation agreements. Their capital structure demands margin protection that filters down to input sourcing decisions, compressing single-source premiums while elevating compliance documentation costs across clinic networks.
Pricing Analysis
Input-cost pass-through from neurotoxin fermentation runs strongest in premium-tier Botox formulations where AbbVie's captive capacity insulates pricing from raw material volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biologics from compounded alternatives and at-home devices. Pricing pressure stems from South Korea's Gangnam district oversupply where 500-plus clinics compress per-treatment margins. Price-sensitive patients in Brazil's interior cities gravitate toward mobile clinic economy tiers, while Los Angeles and Miami premium segments absorb MFU-V platform premiums with minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Clostridium botulinum strain suppliers concentrated in the United States, Ireland, and Germany where three specialized biologics manufacturers control global fermentation capacity. Neurotoxin raw material, cross-linked hyaluronic acid polymers, and alexandrite laser crystals constitute critical input dependencies. Tariff exposure on EU-sourced laser components threatens device manufacturer margins under evolving transatlantic trade frameworks. Distribution runs through manufacturer-direct training academies that precondition clinic procurement relationships on certification completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where patient demand shifts toward MFU-V precision platforms and extended-duration dermal fillers with demonstrable safety profiles. Premium specification preference elevates compliant manufacturers while filtering commoditized alternatives.
For Market Incumbents: Lock in supply relationships through embedded training academy contracts that precede product account activation. Secure multi-source fermentation agreements to neutralize biosimilar threats from Korean challengers leveraging MFDS fast-track pathways. Backward integration into hyaluronic acid polymer production defends margin position against specialty chemical suppliers. For New Entrants and Emerging Players: The price-point gap between premium MFU-V platforms and conventional radiofrequency devices creates white-space opportunity for mid-tier ultrasound-guided systems with simplified operator interfaces. Brazil's tertiary cities beyond São Paulo offer penetrable geography with limited competitor saturation. Direct-to-physician telehealth pre-screening reduces patient acquisition costs below incumbent clinic network overhead. For Investors and Strategic Acquirers: Valuations sit cheapest among independent med-spa operators lacking pharmacy benefit management infrastructure to navigate FDA compounded biologics guidance. Five-to-ten-year viability hinges on regulatory compliance scalability rather than procedure volume alone. Monitor state medical board alignment with federal 503A enforcement as inflection signal for addressable market breadth expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Fermentation Contracting | Supply resilience against Clostridium botulinum input bottlenecks protects manufacturing continuity. |
| Direct-to-Physician Training Academy Deployment | Galderma's certification model locks clinic procurement relationships before competitor reach. |
| MFDS Fast-Track Regulatory Pathway Utilization | Abbreviated South Korean review accelerates next-generation neuromodulator market entry timelines. |
| HIPAA-Compliant Telehealth Platform Buildout | Virtual pre-screening extends geographic capture beyond physical clinic catchment radii. |
| EU MDR Technical File Investment | Robust clinical evidence standards filter low-quality laser competitors from CE-marked revenue pools. |
Study Parameters
Multiple input streams — primary interviews with dermatology clinic directors, med-spa chain procurement officers, and biomedical device regulatory consultants; secondary validation through FDA 510(k) filings, MFDS approval databases, and EU MDR technical file registries; plus customs data on laser platform imports — were reconciled through bottom-up procedure volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across procedure type, target demographic, treatment area, and delivery method dimensions generated consistent value estimates throughout the projection horizon. CAGRs were derived from patient visit frequency trends, treatment duration extension patterns, and geographic penetration rate differentials. Forecast inputs incorporated physician density expansion trajectories in Brazil's interior cities and telehealth adoption curves in U.S. metropolitan markets.
Caveats apply where FDA final guidance on compounded biologics or state-level scope-of-practice expansions could materially shift the outlook for clinic addressable market breadth. Forecasts reflect assumptions about regulatory enforcement continuity and cultural normalization velocity for male aesthetic treatments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market