
 Global Contract Sterilization Market | 2026-2036
Global Contract Sterilization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contract Sterilization Market Foresight
Validation-as-a-service is decoupling sterilization assurance from in-house quality departments. Sterigenics International LLC leverages its global facility network to anchor ethylene oxide capacity across North America and Europe. STERIS competes through integrated sterile processing solutions that extend beyond irradiation into equipment and consumables. Sotera Health specializes in multi-modal platforms, positioning gamma, electron beam, and EtO services as substitutable options under unified quality agreements.
Contract sterilization encompasses third-party terminal treatment of medical products, pharmaceutical components, and packaging materials using validated cycles of ionizing radiation, moist heat, or gaseous agents to achieve specified sterility assurance levels, typically SAL 10^-6 for invasive devices. Ethylene oxide and gamma radiation dominate service revenue due to compatibility with temperature-sensitive polymers and established regulatory dossiers, while electron beam and vaporized hydrogen peroxide segments attract fastest growth from reduced cycle times and elimination of toxic residuals. Application demand concentrates in medical devices and pharmaceuticals where sterilization validation directly gates market access, with packaging materials representing an emerging margin pool as sterile barrier integrity becomes a design-critical specification.
FDA enforces 21 CFR Part 820 quality system regulations and ISO 11135 ethylene oxide validation standards that shape sterilization process documentation and facility audit frequency. EMA implements EU MDR Annex I general safety and performance requirements alongside REACH chemical restrictions that constrain residual gas limits and drive validation protocol complexity. Stakeholders must monitor evolving MDR notified body capacity and FDA alternative sterilization guidance to determine capital allocation between established EtO infrastructure and emerging low-temperature modalities.
Market Dynamics
Medical device manufacturers are decoupling sterilization assurance from captive operations as FDA and EU MDR validation requirements tighten, creating structural pull toward third-party terminal treatment providers with established regulatory dossiers.
Growth Catalysts
- EU MDR Annex I Requirements:General safety and performance mandates for reusable and single-use instruments are accelerating outsourcing decisions among European manufacturers seeking notified body alignment.
- Gamma Radiation Compatibility:Temperature-sensitive polymer medical devices require validated low-heat sterilization cycles that contract providers can deliver at scale.
- China NMPA Centralization:Regional sterilization hubs in Jiangsu and Guangdong provinces are consolidating service demand from domestic device manufacturers.
Market Restraints
- Ethylene Oxide Residual Limits:EPA air emissions standards and REACH chemical restrictions are constraining EtO capacity expansion and extending facility permitting timelines.
- Gamma Source Concentration:Cobalt-60 supply chains concentrate among a limited set of radioisotope processors, creating input vulnerability for radiation-dependent service providers.
- Electron Beam Penetration Thresholds:Density limitations for high-density medical device loads restrict substitutability with gamma radiation for certain polymer configurations.
Strategic Opportunities
- India CDSCO Alignment:Domestic medical device manufacturing incentives under PLI schemes are creating demand for validated sterilization infrastructure near Mumbai and Bangalore clusters.
- Vaporized Hydrogen Peroxide Adoption:Reduced cycle times and elimination of toxic residuals are opening pharmaceutical packaging applications previously locked into ethylene oxide.
- ISO 11135 Validation Services:Documentation and protocol development for EtO cycles represents a margin pool separate from terminal treatment execution.
Industry Challenges
- Sterilization Process Engineer Scarcity:Expertise in dose mapping, biological indicator validation, and regulatory submission preparation remains concentrated among experienced practitioners.
- EtO Facility Capex Intensity:Abatement systems, environmental monitoring infrastructure, and containment architecture require substantial capital deployment per treatment volume.
- Legacy Quality System Integration:Medical device manufacturers must reconcile 21 CFR Part 820 documentation with third-party sterilization provider protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contract Sterilization Market |
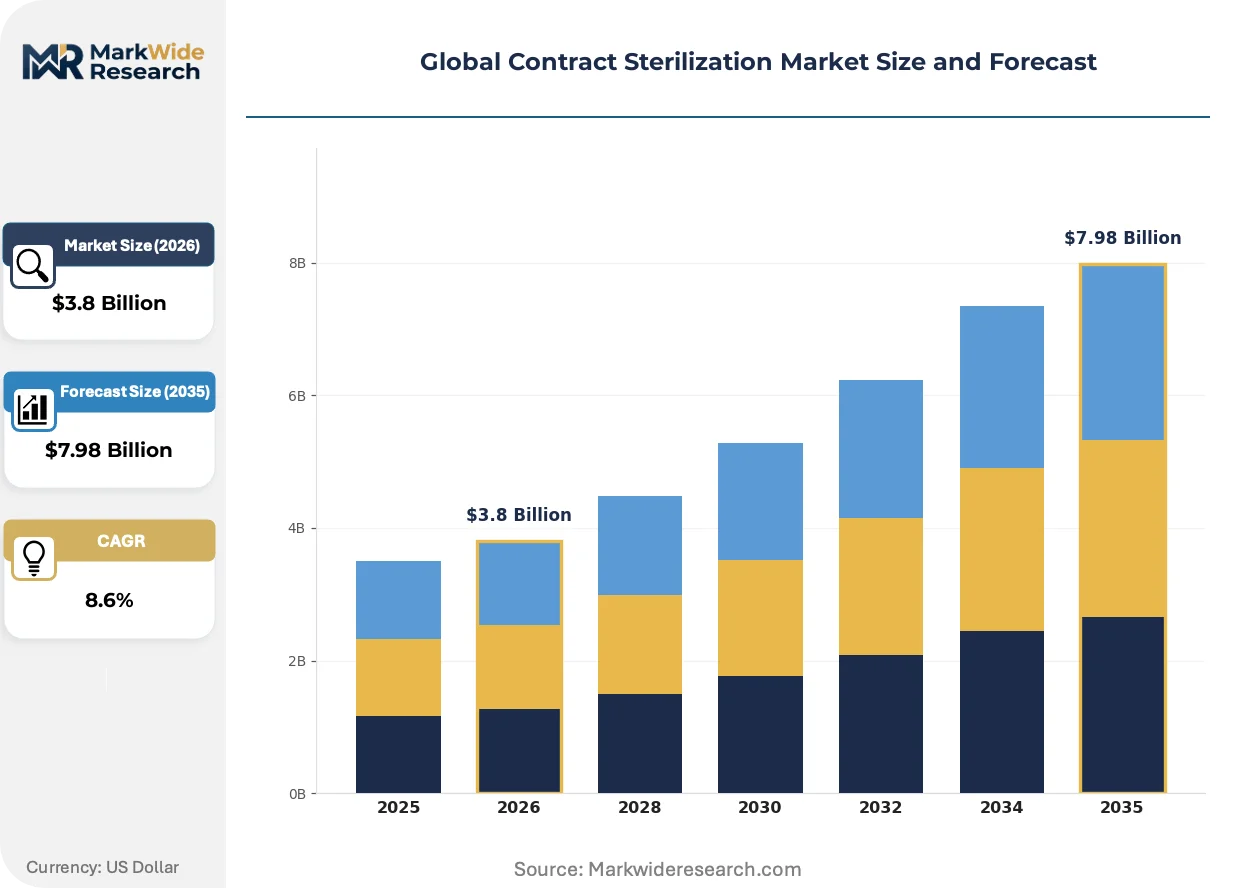
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ethylene Oxide, Gamma Radiation, Steam Sterilization, Electron Beam, Vaporized Hydrogen Peroxide Application: Medical Devices, Pharmaceuticals, Biotechnology Products, Packaging Materials, Laboratory Instruments End User: Hospitals, Diagnostic Centers, Research Institutes, Pharmaceutical Manufacturers, Biotech Firms Packaging Type: Plastic Trays, Tyvek Pouches, Paperboard Boxes, Aluminum Foil Packs, Blister Packs |
| Companies Covered | Sterigenics International LLC, E-BEAM Services Inc., STERIS, Getinge AB, Medistri SA, Sotera Health, BGS Beta-Gamma-Service GmbH & Co. KG, Noxilizer Inc., Servizi Italia S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contract Sterilization Market Shifts & Advancements
Electron beam sterilization is compressing treatment cycles from days to hours while eliminating toxic residual concerns, rewriting competitive positioning between radiation modalities.
X-ray irradiation is rewriting the radiation sterilization landscape by penetrating dense medical device loads without cobalt-60 dependency. Contract providers in Germany and the United States are piloting converted accelerator facilities for pharmaceutical and biologics applications. The technology is compressing the gamma-electron beam capability gap for high-density polymer devices.
EMA's EU MDR notified body capacity constraints are extending sterilization validation timelines for European market access. Medical device manufacturers are front-loading documentation requirements and dual-sourcing contract providers to mitigate approval delays. Germany, Ireland, and Switzerland-based manufacturers are most affected, with some relocating dossier preparation to FDA-aligned facilities.
Device manufacturers are unbundling sterile barrier validation from terminal sterilization contracts, treating packaging integrity as a separate design-critical specification. This procurement pattern is fragmenting supplier relationships and creating margin pressure on pure-play irradiation providers. The shift is most visible among orthopedic and cardiovascular device manufacturers in the United States.
Global Contract Sterilization Market Segmentation
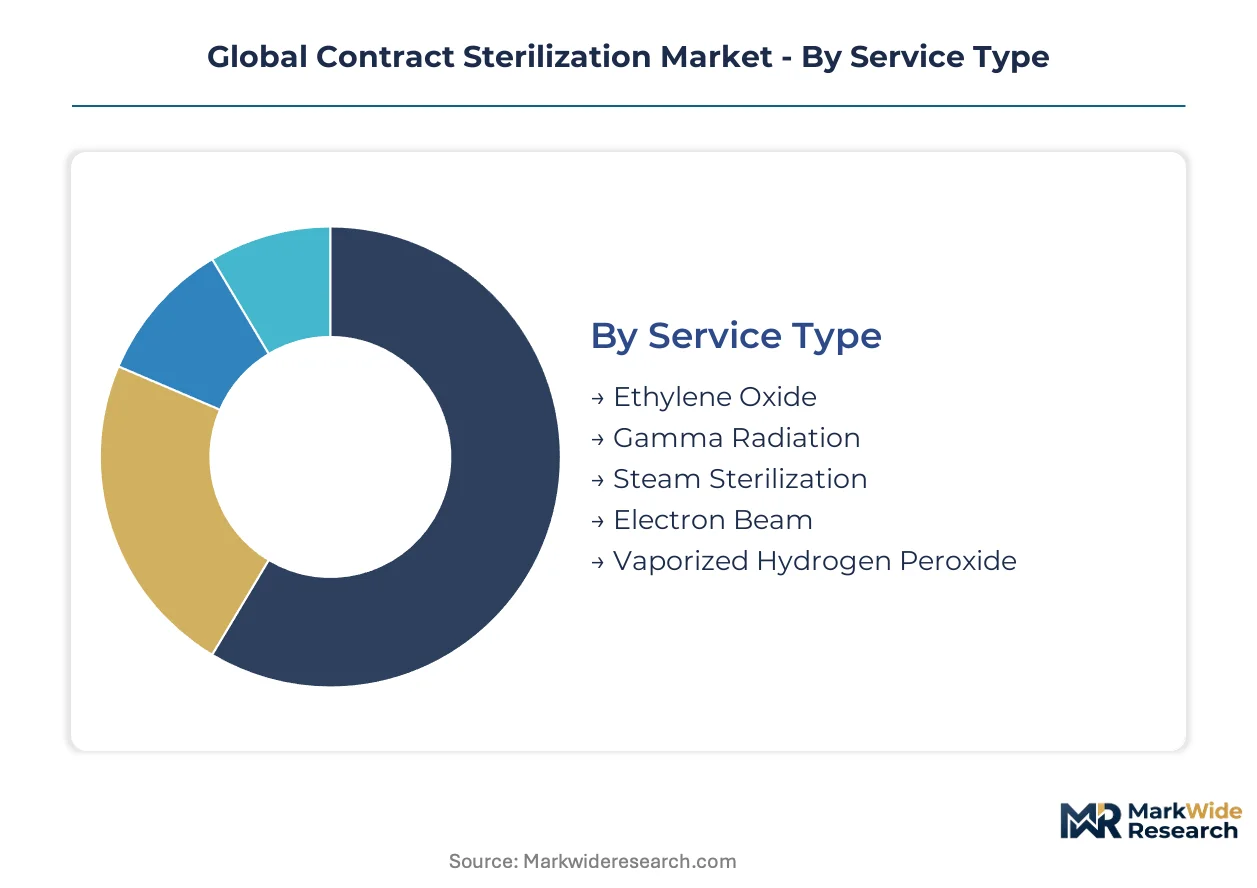
Contract sterilization procurement patterns fragment across modality compatibility, regulatory validation requirements, and sterile barrier specifications. Manufacturers select service providers based on polymer thermal tolerance, dose penetration needs, and residual toxicity limits rather than commodity pricing alone.
Service Type:
Supply concentration for validated sterilization cycles clusters around established modalities with extensive regulatory dossiers.
- Ethylene Oxide:Gaseous diffusion penetrates complex device lumens and porous packaging materials at ambient temperatures. FDA 21 CFR Part 820 compliance and ISO 11135 validation protocols make EtO capacity scarce in the United States and Germany where EPA emissions restrictions constrain facility expansion.
- Gamma Radiation:Cobalt-60 isotope decay delivers penetrating ionization suitable for dense polymer pallets and temperature-sensitive biologics. Demand concentrates in Belgium and Canada where Nordion and Bruce Power anchor radioisotope supply chains; cobalt-60 concentration among three primary processors creates input vulnerability.
- Steam Sterilization:Saturated vapor at 121-134°C suits metal instruments and glassware with thermal tolerance.
- Electron Beam:High-energy electrons from linear accelerators eliminate radioactive source dependency while compressing cycle duration.
- Vaporized Hydrogen Peroxide:Low-temperature oxidative process targets pharmaceutical packaging and electronics with residual elimination advantages.
Ethylene oxide absorbs the bulk of installed capacity; vaporized hydrogen peroxide is expanding most quickly.
Application:
Application demand stratifies by regulatory gatekeeping intensity and sterile barrier criticality.
- Medical Devices:Terminal sterilization validates market access for invasive instruments under FDA quality system regulations and EU MDR Annex I requirements. Orthopedic implants and cardiovascular catheters in the United States, Germany, and Switzerland drive outsourcing decisions as notified body capacity tightens.
- Pharmaceuticals:Parenteral drug packaging and biologic container closure integrity demand SAL 10^-6 assurance with extractables testing. European sterile injectable manufacturers in Ireland and Denmark front-load validation documentation to preempt EMA approval delays.
- Biotechnology Products:Cell therapy containers and gene therapy delivery systems require low-temperature modalities preserving protein integrity.
- Packaging Materials:Sterile barrier validation is decoupling from terminal sterilization contracts as design-critical specifications.
- Laboratory Instruments:Cell culture consumables and diagnostic reagents need validated cycles preventing nucleic acid degradation.
Medical devices command the dominant revenue share; packaging materials are climbing the fastest as barrier integrity specifications tighten.
End User:
Customer procurement scale determines validation protocol burden and contract structure.
- Pharmaceutical Manufacturers:Large-volume parenteral producers in the United States and Germany negotiate multi-year master service agreements covering gamma, electron beam, and EtO alternatives under unified quality systems. Serialization requirements and EU MDR Annex VI traceability mandates extend documentation obligations.
- Hospitals:Central sterile processing departments outsource terminal treatment for complex instruments exceeding in-house autoclave capacity. Academic medical centers in Massachusetts and California contract irradiation for research device prototypes.
- Diagnostic Centers:Molecular testing laboratories require sterile collection devices and reagent packaging.
- Research Institutes:Preclinical device development generates small-batch validation needs.
- Biotech Firms:Cell therapy developers demand modality flexibility for novel container systems.
Pharmaceutical manufacturers absorb the bulk of contract value; biotech firms are gaining share fastest as advanced therapy pipelines mature.
Packaging Type:
Material sterilization compatibility and seal integrity specifications shape modality selection.
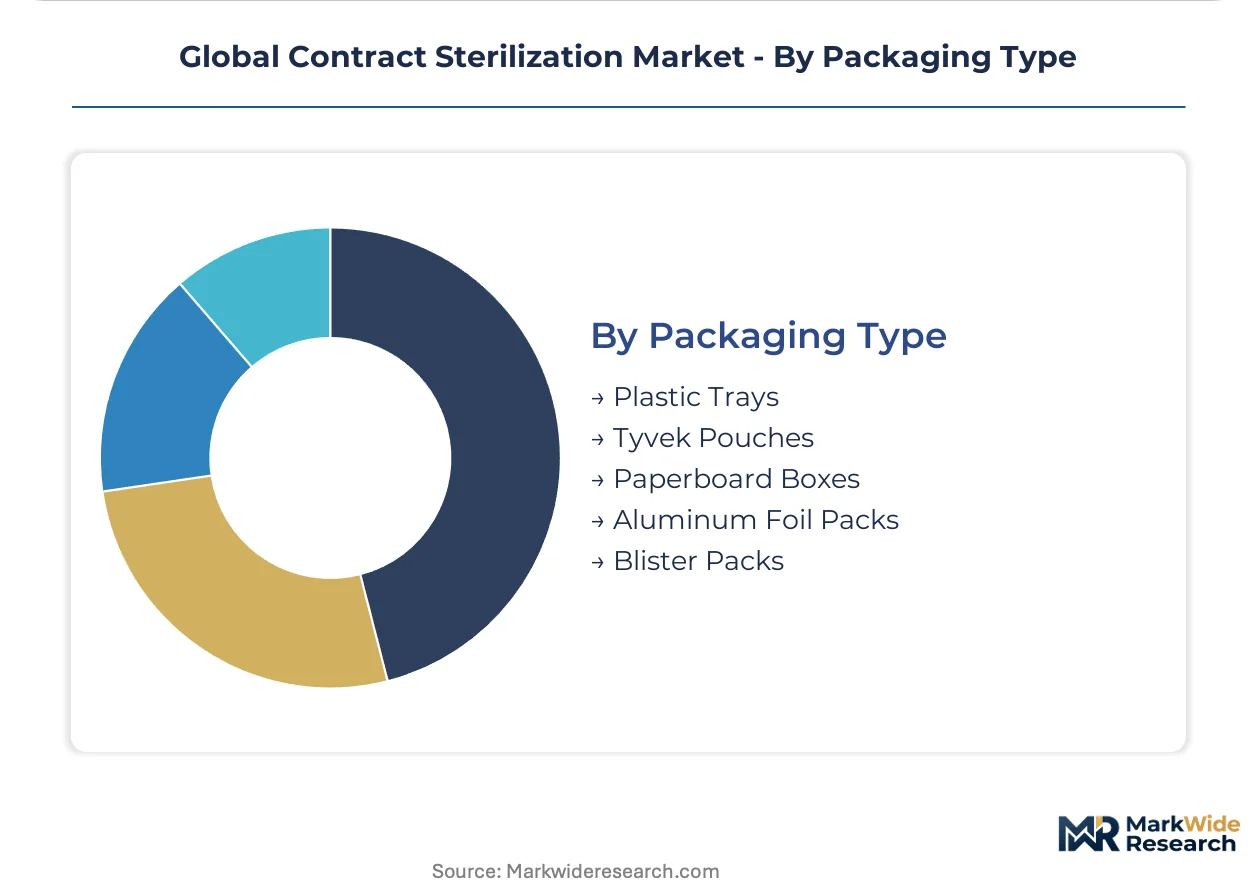
- Tyvek Pouches:Spun-bonded high-density polyethylene permits ethylene oxide and gamma penetration while maintaining sterile barrier integrity. Cardiovascular device manufacturers in Minnesota and Massachusetts specify Tyvek for implantable product portfolios.
- Plastic Trays:PETG and HIPS thermoforms accommodate gamma and electron beam irradiation with dose mapping validation for thick-walled configurations.
- Blister Packs:PVC-PVDC laminates require residual gas testing for EtO cycles.
- Paperboard Boxes:Cellulose-based secondary packaging suits steam or vaporized hydrogen peroxide.
- Aluminum Foil Packs:Impermeable barriers exclude gaseous sterilants, restricting modality choice.
Tyvek pouches absorb the bulk of sterilization service volume; plastic trays are expanding most quickly as device form factors diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American sterilization infrastructure through Sterigenics International LLC's ethylene oxide network, while centralized hubs in Germany and China serve regional medical device manufacturing clusters under tightening FDA and EU MDR validation requirements.
United States
Medical device manufacturers in Minnesota and Massachusetts outsource terminal sterilization as FDA 21 CFR Part 820 quality system regulations tighten validation documentation. EPA air emissions standards constrain ethylene oxide capacity expansion, extending facility permitting timelines in Illinois and Georgia. Sterigenics International LLC operates ethylene oxide hubs near Minneapolis and Atlanta to serve orthopedic and cardiovascular device clusters.
Germany
EMA's EU MDR Annex I general safety and performance requirements accelerate outsourcing decisions among Baden-Württemberg and Bavaria manufacturers seeking notified body alignment. REACH chemical restrictions drive residual gas limit compliance and validation protocol complexity. BGS Beta-Gamma-Service GmbH & Co. KG anchors gamma radiation capacity near Wiehl to serve pharmaceutical packaging and medical device producers in the Rhine-Ruhr industrial corridor.
China
NMPA centralization consolidates sterilization demand from domestic device manufacturers in Jiangsu and Guangdong provinces. Regional hubs in Suzhou and Shenzhen serve export-oriented medical technology producers under dual carbon goals and MIIT industrial upgrading mandates. Gamma and electron beam capacity concentrates near Shanghai to supply pharmaceutical and biologics packaging manufacturers.
Switzerland
Swissmedic regulations for sterile medical devices and parenteral pharmaceuticals drive validation requirements among Basel and Zurich-area manufacturers. Medistri SA operates multi-modal sterilization platforms serving orthopedic implant and drug delivery device producers. Contract providers near Geneva and Lausanne specialize in low-temperature cycles for temperature-sensitive polymer instruments.
India
CDSCO alignment requirements under PLI scheme incentives create demand for validated sterilization infrastructure near Mumbai and Bangalore medical device clusters. Domestic manufacturers in Maharashtra and Karnataka outsource terminal treatment as quality system regulations mature. Gamma and ethylene oxide capacity concentrates in Gujarat and Telangana to supply export-oriented pharmaceutical packaging producers.
Global Contract Sterilization Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across modality specialization and geographic coverage. The market structures around three tiers: integrated sterile processing conglomerates with equipment and consumables portfolios; multi-modal radiation specialists offering substitutable gamma, electron beam, and EtO alternatives; and single-technology pure-plays dominating regional density markets. Consolidation concentrates ethylene oxide capacity among EPA-permitted operators, while electron beam and vaporized hydrogen peroxide segments attract greenfield investment from pharmaceutical packaging demand. Strategic moves center on M&A for regulatory dossier accumulation and capacity expansion in India and China manufacturing corridors.
Among North American sterilization providers, Sterigenics International LLC exemplifies the ethylene oxide-dominant archetype through its EPA-permitted facility network, while STERIS occupies a position bridging terminal treatment with sterile processing equipment. Sotera Health represents the multi-modal platform strategy, positioning gamma, electron beam, and EtO services as substitutable options under unified quality agreements. European specialists including BGS Beta-Gamma-Service GmbH & Co. KG and Medistri SA anchor regional capacity for pharmaceutical and medical device manufacturers facing EMA validation timelines.
| Leading Market Players |
|---|
| Sterigenics International LLC |
| E-BEAM Services Inc. |
| STERIS |
| Getinge AB |
| Medistri SA |
| Sotera Health |
| BGS Beta-Gamma-Service GmbH & Co. KG |
| Noxilizer Inc. |
| Servizi Italia S.p.A |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up sterilization specialists anchor pricing discipline through consolidated ethylene oxide capacity in EPA-constrained markets, while sovereign-backed radioisotope processors in Belgium and Canada tether gamma service pricing to cobalt-60 supply security. This ownership fragmentation creates divergent pricing power across modalities.
Pricing Analysis
Throughput-based pricing anchors contract sterilization economics, with pharmaceutical manufacturers negotiating multi-year master service agreements covering modality substitutability under unified quality systems. Price differentiation separates ISO 11135-validated EtO cycles from standard gamma irradiation, with FDA-aligned documentation commanding premiums. Cost compression in electron beam services is intensifying because pharmaceutical packaging demand accelerates capacity deployment. Academic medical centers and research institutes exhibit highest price sensitivity, while orthopedic device manufacturers in Minnesota and Massachusetts absorb premiums for regulatory dossier completeness.
Supply Chain Analysis
Certification gating concentrates sterilization capacity among EPA-permitted EtO operators in the United States and notified body-aligned gamma facilities in Germany and Belgium. Cobalt-60 supply chains draw from Nordion and Bruce Power radioisotope processors, creating single-source vulnerability for radiation-dependent service providers. Distribution runs through regional sterilization hubs serving medical device manufacturing clusters in Jiangsu, Guangdong, and Bavaria. Tariff exposure on cobalt-60 transport logistics compounds input cost volatility for European contract providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene oxide capacity scarcity under EPA emissions restrictions props pricing power for permitted operators, creating a supply-constrained market structure favoring incumbents with regulatory dossier depth.
For Market Incumbents: Deploy multi-modal platform integration to anchor customer relationships against electron beam substitution threats. Expand gamma and vaporized hydrogen peroxide capacity in India and China manufacturing corridors to capture CDSCO and NMPA alignment demand. Backward integration into cobalt-60 logistics partnerships mitigates radioisotope supply concentration risk. For New Entrants and Emerging Players: Begin with pharmaceutical packaging applications where reduced cycle times and toxic residual elimination open white-space opportunities. Target vaporized hydrogen peroxide validation services for Irish and Danish sterile injectable manufacturers front-loading EMA documentation. Lead with ISO 11135 protocol development as a margin pool separate from terminal treatment execution. For Investors and Strategic Acquirers: Distressed-cycle entries favor electron beam pure-plays in Germany and the United States with converted accelerator infrastructure. Long-term viability hinges on modality flexibility across gamma, electron beam, and low-temperature alternatives. Watch FDA alternative sterilization guidance as the inflection signal for capital reallocation between established EtO infrastructure and emerging modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Platform Integration | STERIS and Sotera Health anchor customer relationships through substitutable gamma, electron beam, and EtO alternatives. |
| Capacity Expansion in India and China | CDSCO alignment requirements and NMPA centralization drive sterilization hub deployment near Mumbai and Suzhou clusters. |
| ISO 11135 Validation Services | Documentation protocol development represents a separate margin pool from terminal treatment execution for EtO cycles. |
| Electron Beam Accelerator Conversion | X-ray irradiation pilots in Germany and the United States compress the gamma-electron beam capability gap for dense polymer devices. |
| Regulatory Dossier Accumulation via M&A | Consolidation concentrates EPA-permitted EtO capacity among operators with established FDA and EU MDR validation histories. |
Research Methodology
Document review covered FDA 21 CFR Part 820 filings, EMA EU MDR Annex I submissions, and EPA emissions compliance records, complemented by interviews with sterilization process engineers, biomedical device quality directors, and GPO contracts managers. Secondary validation drew from ISO 11135 implementation databases, hospital procurement systems, and medical device registration filings. Bottom-up facility capacity modeling and top-down pharmaceutical outsourcing expenditure analysis provided cross-referenced triangulation.
Historical throughput data from gamma and electron beam facilities cross-referenced against panel input from contract provider operations directors shaped the analytical framework. Segmentation modeling covered sterilization modality, application intensity, regulatory validation tier, and regional manufacturing cluster. CAGRs were derived from facility utilization trajectories and outsourcing penetration curves across the analysis window. Forecast inputs incorporated EU MDR notified body capacity constraints and NMPA centralization timelines.
Underlying measurement precision varies by segment; ethylene oxide and gamma radiation services carry tighter precision than emerging vaporized hydrogen peroxide modalities due to established regulatory dossier density. Forecasts reflect assumptions regarding EPA permitting velocity and cobalt-60 supply continuity. A model refresh is warranted upon material change in FDA alternative sterilization guidance or EU MDR notified body accreditation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Long Term Care Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Prescription Delivery Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market