
 US Biopharmaceutical Third-Party Logistics Market | 2026-2036
US Biopharmaceutical Third-Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Biopharmaceutical Third-Party Logistics Market Intelligence
The gap between premium validated cold chain services and commodity pharmaceutical distribution is broadening as temperature-sensitive biologics claim larger share of pipeline value. UPS Healthcare leverages its healthcare-dedicated network infrastructure to sustain temperature integrity across multi-modal lanes. Cardinal Health anchors its position through centralized distribution centers serving hospital systems and specialty pharmacies. McKesson Corporation differentiates via direct-to-patient distribution capabilities for limited-distribution drugs.
US biopharmaceutical third-party logistics encompasses the outsourced planning, execution, and control of pharmaceutical product movement, requiring validated temperature ranges between minus eighty degrees Celsius and controlled room temperature, plus chain-of-custody documentation for investigational compounds. Cold chain services command premium positioning as cell therapies, mRNA platforms, and personalized medicines expand manufacturing volumes. Warehousing functions concentrate margin pools in specialized facilities with redundant backup power and real-time environmental monitoring systems. Transportation segments split between parcel carriers handling direct-to-patient deliveries and freight operators managing bulk API movements.
FDA enforces current Good Distribution Practice standards through facility inspections and supply chain security directives, while the Drug Supply Chain Security Act mandates unit-level traceability that forces logistics providers to upgrade serialization infrastructure. The Department of Transportation and Pipeline and Hazardous Materials Safety Administration jointly regulate hazardous biological substance transport classifications. Stakeholders must weigh capital deployment toward cryogenic infrastructure against partnership models with specialized cold chain operators as therapy modalities diversify.
Market Dynamics
Cell and gene therapy commercialization is forcing logistics providers to deploy cryogenic infrastructure at scale, as autologous treatments require uninterrupted minus eighty degrees Celsius custody chains from manufacturing through patient administration.
Growth Catalysts
- FDA DSCSA Mandate:The Drug Supply Chain Security Act compels wholesale distributors and 3PLs to implement unit-level serialization, driving infrastructure investment and vendor consolidation among compliance-capable operators.
- mRNA Platform Expansion:Thermostable lipid nanoparticle formulations and booster campaign residual demand sustain cold chain capacity utilization across specialized freight networks.
- Massachusetts-New Jersey Corridor Density:Concentrated biopharma manufacturing in Cambridge and the I-95 pharmaceutical belt generates route economics that justify dedicated temperature-controlled fleet deployment.
Market Restraints
- Liquid Nitrogen Supply Concentration:Cryogenic infrastructure depends on regional industrial gas production clusters, creating vulnerability to energy price volatility and localized shortages.
- Specialized Facility Scarcity:Validated warehouse capacity with redundant backup power and real-time environmental monitoring remains concentrated in legacy pharmaceutical hubs, constraining geographic expansion.
- DOT Hazmat Classification Friction:The Pipeline and Hazardous Materials Safety Administration's biological substance transport categories impose route restrictions and packaging requirements that limit modal flexibility.
Strategic Opportunities
- Direct-to-Patient Channel Development:Specialty pharmacy and home infusion expansion enables logistics providers to capture margin pools previously retained by traditional wholesale distribution.
- Cell Therapy Regional Manufacturing:Distributed production models for CAR-T and gene therapies create demand for point-of-care cryogenic logistics in secondary US markets.
- HIPAA-Compliant Data Integration:Chain-of-custody documentation systems that interface with provider electronic health records offer differentiation beyond physical distribution capabilities.
Industry Challenges
- Cryogenic Technician Shortage:Qualified personnel for liquid nitrogen handling and ultra-low temperature equipment maintenance remain scarce, constraining facility expansion timelines.
- Multi-Modal Temperature Integrity:Maintaining validated cold chains across air freight, ground transport, and last-mile delivery requires seamless data handoffs that legacy systems struggle to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Biopharmaceutical Third-Party Logistics Market |
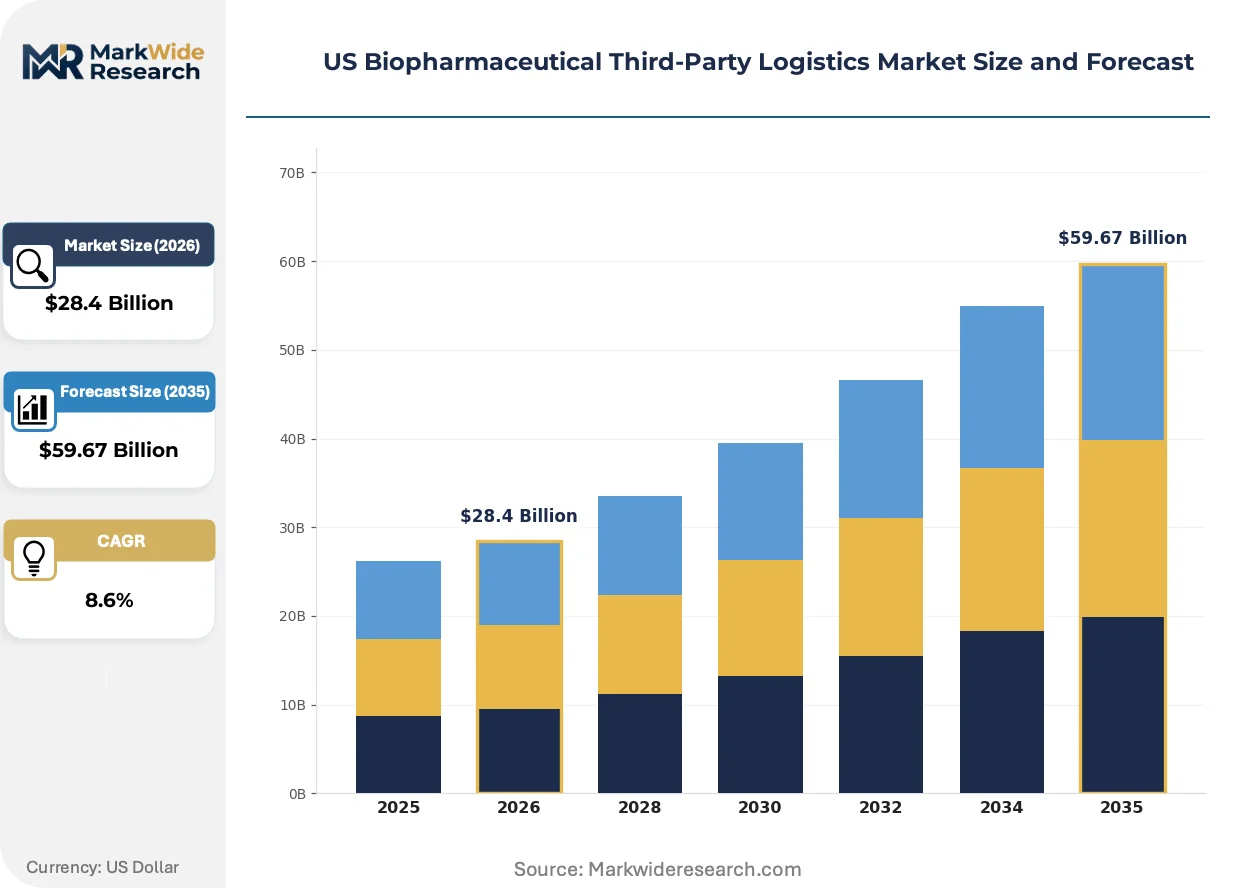
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Distribution, Cold Chain, Transportation End User: Pharmaceutical Manufacturers, Biotechnology Companies, Research Institutions, Hospitals Delivery Model: Direct Delivery, Freight Forwarding, White Glove Services, Cross-Docking Packaging Type: Temperature-Controlled Packaging, Tamper-Evident Packaging, Secure Packaging, Customized Packaging |
| Companies Covered | UPS Healthcare, Cardinal Health, Kuehne + Nagel, AmerisourceBergen Corp., McKesson Corporation, DHL International GmbH, DB Schenker, Cencora, Inc., Thermo Fisher Scientific, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Biopharmaceutical Third-Party Logistics Market Strategic Shifts & Innovations
Digital integration of physical infrastructure with real-time visibility platforms is compressing response windows for temperature excursions and custody breaches across pharmaceutical supply networks.
Passive thermal packaging with phase-change materials is rewriting cold chain economics for cell therapies. Gene therapy manufacturers are adopting these systems for clinical trial distribution to reduce dry ice dependency. The technology is compressing cost structures for mid-volume shipments that previously required active refrigeration units.
FDA's intensified inspectional focus on current Good Distribution Practice compliance is elevating documentation standards across the 3PL sector. Warning letter trends targeting temperature excursion investigations are forcing providers to upgrade environmental monitoring systems. Small and mid-size distributors face disproportionate compliance burdens relative to scale economies.
Hospital systems and specialty pharmacies are consolidating procurement decisions for limited-distribution drugs under centralized pharmacy benefit managers. This concentration is displacing fragmented purchasing patterns that historically supported regional distributor fragmentation. The shift is most visible in oncology and rare disease therapeutic categories where exclusive distribution agreements predominate.
US Biopharmaceutical Third-Party Logistics Market Segmentation
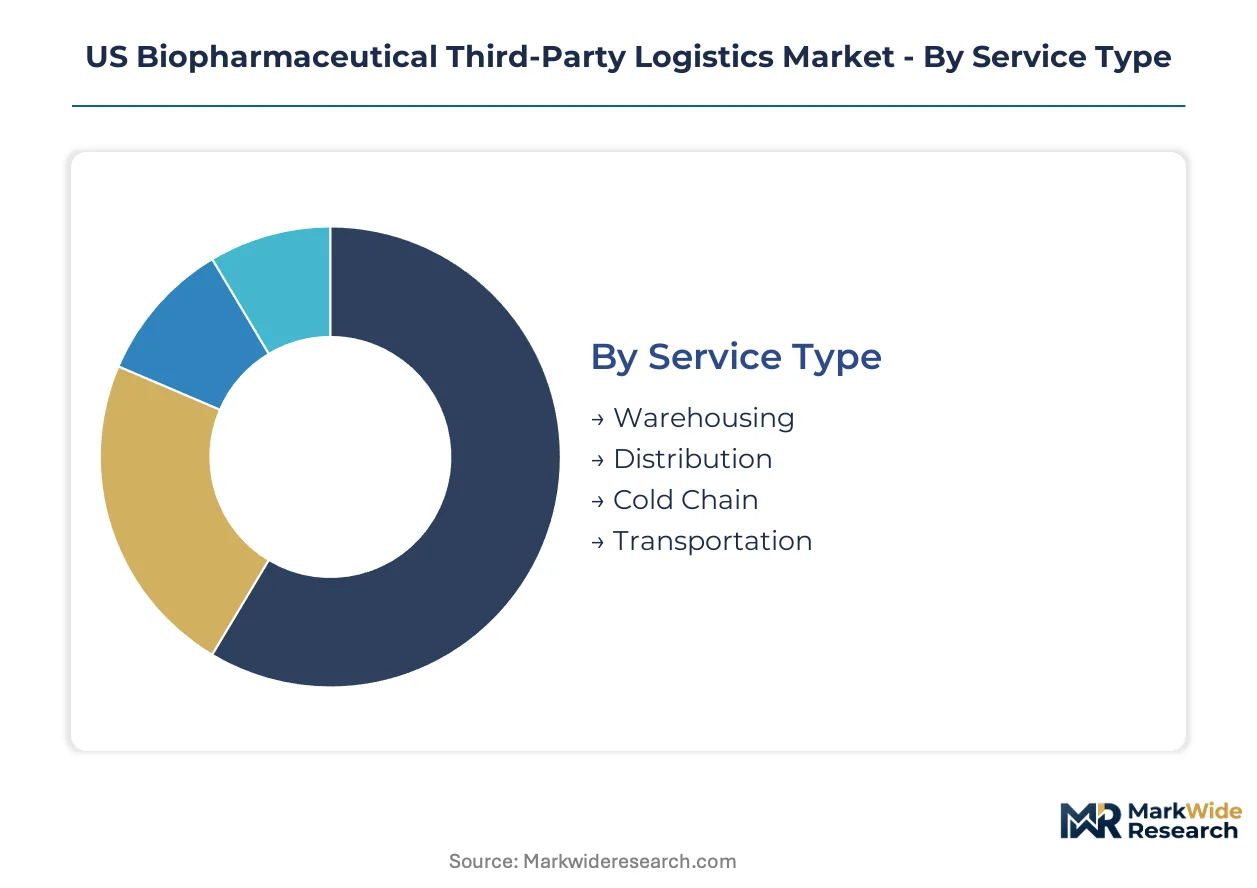
Service differentiation in US biopharmaceutical logistics hinges on temperature validation depth and custody documentation rigor. Segment boundaries blur as providers bundle warehousing with specialized transport to capture premium pricing for cell therapy workflows.
Service Type:
Standalone cold chain infrastructure commands the highest capital deployment, while integrated distribution services embed temperature control within broader logistics contracts.
- Cold Chain:Validated infrastructure maintains minus eighty degrees Celsius through redundant backup power and real-time environmental monitoring. CAR-T manufacturers in the Massachusetts-New Jersey corridor drive capacity expansion for autologous therapy custody chains.
- Warehousing:Specialized facilities with cGMP compliance and serialization infrastructure anchor margin pools for high-value biologics. FDA inspection intensity elevates documentation standards that favor operators with centralized quality systems.
- Distribution:Unit-level traceability compliance under DSCSA mandates drives vendor consolidation toward serialization-capable providers.
- Transportation:Modal flexibility constraints from DOT hazmat classifications limit route optimization for biological substance movements.
Cold Chain leads volumes today; Warehousing is gaining share fastest.
End User:
Customer procurement concentration reshapes service packaging, with hospital system centralization displacing fragmented purchasing patterns.
- Pharmaceutical Manufacturers:Large-scale biologics producers require integrated global distribution networks with serialization backbone infrastructure. Massachusetts and New Jersey hubs generate route density that justifies dedicated fleet deployment.
- Biotechnology Companies:Cell and gene therapy developers demand point-of-care cryogenic logistics for distributed manufacturing models. Clinical-to-commercial transition complexity favors providers with regulatory submission support capabilities.
- Research Institutions:Investigational compound custody chains require chain-of-documentation protocols interfacing with institutional review boards.
- Hospitals:Specialty pharmacy and home infusion expansion enables direct-to-patient channel capture previously retained by wholesale distribution.
Pharmaceutical Manufacturers anchor revenue concentration; Biotechnology Companies show the steepest expansion trajectory.
Delivery Model:
Cost-to-service tiering separates high-touch patient-facing logistics from commodity freight movements.
- White Glove Services:Hand-delivered, appointment-scheduled distribution for limited-distribution drugs with patient identity verification protocols. Oncology and rare disease therapeutic categories concentrate demand for this premium tier.
- Direct Delivery:Parcel carrier networks handle last-mile distribution for specialty pharmacies with temperature integrity validation.
- Freight Forwarding:Bulk API movements across international lanes require customs brokerage integration with cold chain handoffs.
- Cross-Docking:Inventory velocity optimization for high-turn generic pharmaceuticals with minimal dwell time requirements.
Direct Delivery dominates transaction volumes; White Glove Services is climbing the fastest.
Packaging Type:
Passive thermal systems are displacing active refrigeration for mid-volume cell therapy shipments.
- Temperature-Controlled Packaging:Phase-change materials and vacuum-insulated panels maintain validated ranges without dry ice dependency. Gene therapy clinical trial distribution adopts these systems to reduce cryogenic infrastructure costs.
- Tamper-Evident Packaging:DSCSA-mandated unit-level identifiers require packaging integration with serialization infrastructure at the secondary and tertiary levels.
- Secure Packaging:Controlled substance distribution demands dual-lock mechanisms and GPS-tracked custody documentation.
- Customized Packaging:Patient-specific kitting for personalized medicine workflows with variable dosing configurations.
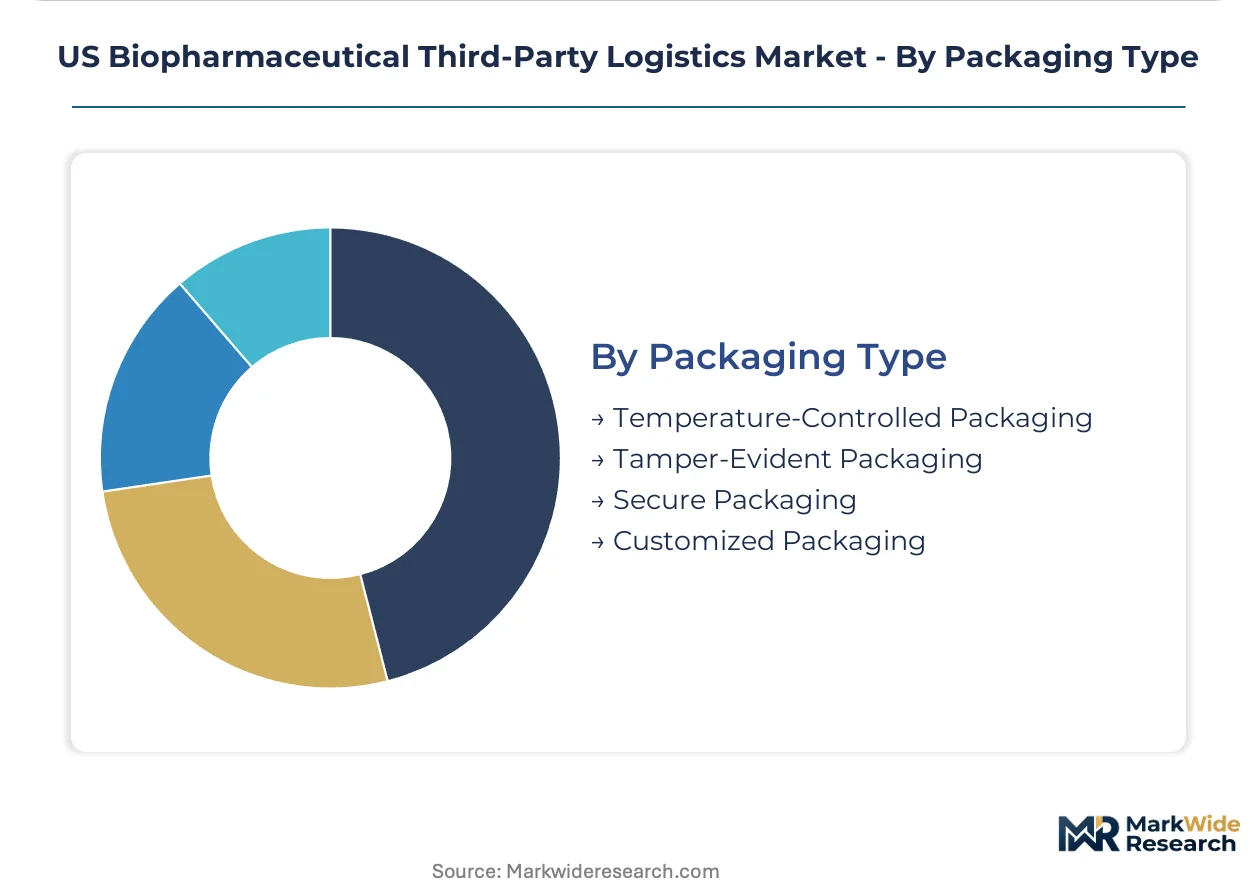
Temperature-Controlled Packaging leads segment value; Customized Packaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentration in pharmaceutical supply chain management anchors the US biopharmaceutical 3PL geography. The Northeast corridor commands disproportionate infrastructure investment due to proximity between manufacturing clusters and specialized logistics expertise.
Massachusetts
Cambridge and Greater Boston biotech clusters generate dense demand for cryogenic logistics supporting cell therapy clinical trials. FDA's current Good Distribution Practice inspections enforce documentation standards that favor established 3PL operators with centralized quality systems. Kendall Square and the Seaport Innovation District concentrate autologous therapy manufacturing facilities requiring minus eighty degrees Celsius custody chains.
New Jersey
The I-95 pharmaceutical belt sustains route economics justifying dedicated temperature-controlled fleet deployment. The Drug Supply Chain Security Act mandates unit-level serialization infrastructure that wholesale distributors must maintain across New Brunswick and Princeton logistics hubs. Middlesex County warehousing corridors anchor high-value biologics distribution serving hospital systems and specialty pharmacies.
Pennsylvania
Philadelphia's cell and gene therapy manufacturing expansion drives demand for point-of-care cryogenic logistics in secondary markets. DOT and Pipeline and Hazardous Materials Safety Administration hazmat classifications impose packaging requirements limiting modal flexibility for biological substance movements. Montgomery County and Chester County facilities concentrate serialization-capable distribution capacity.
California
San Francisco Bay Area biotech development generates specialized cold chain requirements for mRNA platform distribution. The state's hazardous materials transport regulations layer additional compliance burdens on biological substance movements beyond federal DOT standards. South San Francisco and San Diego biotech clusters sustain demand for clinical-to-commercial logistics transition support.
North Carolina
Research Triangle Park pharmaceutical manufacturing anchors demand for investigational compound custody chains with chain-of-documentation protocols. HIPAA compliance requirements for patient data integration shape logistics provider selection for direct-to-patient distribution models. Durham and Raleigh facilities concentrate capacity for limited-distribution drug handling.
US Biopharmaceutical Third-Party Logistics Market Key Industry Players
Capital-heavy infrastructure operators compete with asset-light platform coordinators across the US biopharmaceutical 3PL sector. The vendor base concentrates among healthcare-dedicated networks with redundant cold chain capabilities and serialization infrastructure. Three archetypes dominate: integrated healthcare distributors with hospital system relationships, global freight forwarders with pharmaceutical certification, and specialized cryogenic logistics operators. Consolidation pressure intensifies through DSCSA compliance requirements, while partnership models expand between manufacturers and regional cold chain specialists.
Within the integrated healthcare tier, Cardinal Health and McKesson Corporation exemplify distributors leveraging centralized pharmacy benefit manager relationships. UPS Healthcare and DHL International GmbH occupy positions among global operators with multi-modal pharmaceutical networks. These named entities represent archetype anchors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| UPS Healthcare |
| Cardinal Health |
| Kuehne + Nagel |
| AmerisourceBergen Corp. |
| McKesson Corporation |
| DHL International GmbH |
| DB Schenker |
| Cencora, Inc. |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
The premium-validated versus commodity-distribution split in US biopharmaceutical logistics manifests in divergent pricing power and supply chain footprints. Cryogenic custody chains for CAR-T therapies command three-to-five-fold rate premiums over standard cold chain distribution, while DSCSA serialization infrastructure requirements force vendor consolidation toward compliance-capable operators with centralized quality systems.
Pricing Analysis
Bundled service contracts integrating warehousing, transportation, and serialization compliance dominate enterprise pharmaceutical manufacturer procurement, while unbundled spot pricing persists for clinical trial logistics and emerging biotechnology companies. Price differentiation hinges on FDA cGMP certification tier and redundant backup power infrastructure, with Massachusetts-New Jersey corridor providers capturing geographic delivery cost premiums. Cost compression in standard cold chain services is intensifying because parcel carriers are expanding temperature-controlled networks, though margins remain protected in cryogenic logistics due to liquid nitrogen supply concentration and qualified technician scarcity. Biotechnology companies show highest price sensitivity due to clinical-to-commercial transition uncertainty, while large pharmaceutical manufacturers prioritize reliability over rate negotiation.
Supply Chain Analysis
Direct-to-patient channels handle hyperscale demand from specialty pharmacy expansion, displacing traditional wholesale distribution for limited-distribution drugs. Geographic supply concentration centers on the Massachusetts-New Jersey pharmaceutical belt, with secondary clusters in Pennsylvania, California, and North Carolina anchoring regional capacity. Raw material dependencies include liquid nitrogen for cryogenic infrastructure, phase-change materials for passive thermal packaging, and serialization hardware for DSCSA compliance. Single-source vulnerability runs through regional industrial gas production clusters, where energy price volatility propagates into cryogenic logistics cost structures. Distribution runs through hospital system procurement centralization under pharmacy benefit managers, consolidating previously fragmented purchasing patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US biopharmaceutical 3PL market functions as a geographic-arbitrage play where Massachusetts-New Jersey corridor density justifies premium infrastructure deployment unavailable in secondary markets with equivalent regulatory stringency but lower route economics.
For Market Incumbents: Deepen cryogenic infrastructure lock-in through exclusive liquid nitrogen supply agreements and qualified technician training pipelines, defending against emerging platform coordinators with asset-light models. Anchor position by acquiring regional cold chain specialists in Pennsylvania and North Carolina before DSCSA compliance deadlines force vendor consolidation. Vertical integration into patient data systems interfacing with provider electronic health records creates switching costs beyond physical distribution capabilities.
For New Entrants and Emerging Players: The mid-market price-point gap between premium white-glove services and commodity parcel distribution offers entry space for hybrid models targeting biotechnology companies in clinical-to-commercial transition. Point-of-care cryogenic logistics in secondary US markets—particularly Philadelphia and Research Triangle Park—represents the most penetrable geography with distributed CAR-T manufacturing expansion. A go-to-market angle emphasizing HIPAA-compliant data integration with institutional review board documentation protocols differentiates beyond temperature validation alone.
For Investors and Strategic Acquirers: Consolidation pressure builds where DSCSA serialization infrastructure requirements disproportionately burden small and mid-size distributors lacking centralized quality systems. Long-term viability over the next decade favors operators with healthcare-dedicated networks and redundant cold chain capabilities over commodity logistics platforms. Acquisition target archetypes include regional cryogenic specialists with FDA inspection histories and established biotechnology company relationships. The signal to watch is warning letter trends targeting temperature excursion investigation protocols, which accelerate vendor consolidation toward compliance-capable operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Expansion | Liquid nitrogen supply agreements in Massachusetts and New Jersey secure CAR-T custody chain capacity. |
| DSCSA Serialization Deployment | Unit-level traceability infrastructure anchors wholesale distributor compliance capability. |
| Direct-to-Patient Channel Development | Specialty pharmacy partnerships capture margin pools from traditional wholesale distribution. |
| HIPAA-Compliant Data Integration | Electronic health record interfaces differentiate beyond physical cold chain capabilities. |
| Regional Manufacturing Proximity | Distributed cell therapy production in secondary markets demands point-of-care cryogenic logistics. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, DSCSA implementation guidance, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up service provider capacity modeling and top-down pharmaceutical pipeline value triangulation anchored market sizing across temperature-controlled infrastructure segments.
Comparable historical reference periods spanning pre-pandemic baseline, mRNA platform surge, and cell therapy commercialization transition informed projection anchor points across the analysis window. Segmentation modeling incorporated service type, end-user archetype, delivery model tier, and packaging technology, with treatment modality and regional regulatory cluster as industry-specific dimensions. CAGRs derived from capacity utilization trends, pipeline value concentration, and compliance infrastructure deployment curves, with liquid nitrogen supply elasticity and qualified technician pipeline constraints as forecast sensitivity inputs.
Caveats apply where FDA inspection intensity shifts, liquid nitrogen supply disruptions, or DOT hazmat classification revisions could materially shift the outlook beyond modeled scenarios. Forecasts reflect documented assumptions regarding therapy modality mix and serialization infrastructure deployment timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Retail Clinics Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
US Hospice Care Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market