
 Patient Transportation Market | 2026-2036
Patient Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Transportation Market Outlook
The capital-intensity divergence between fleet-heavy incumbents and technology-enabled brokers is redrawing competitive boundaries in patient transportation. Global Medical Response leverages its owned ambulance infrastructure to sustain cost advantages in emergency response markets. ModivCare Solutions competes through centralized dispatch technology that anchors its position in Medicaid-managed non-emergency transport.
Patient transportation encompasses the organized movement of individuals requiring medical oversight between care settings, utilizing ground vehicles, rotary-wing aircraft, and watercraft equipped with stretchers, oxygen delivery, and cardiac monitoring capability. The primary purpose is ensuring timely access to definitive care while maintaining clinical stability during transit. Ambulance services command the largest revenue share due to irreplaceable emergency infrastructure, while non-emergency medical transport generates expanding margin pools as payors prioritize cost-efficient alternatives to emergency department utilization. Air ambulance operations occupy a premium tier driven by rural access gaps and inter-facility critical care transfers.
CMS reimbursement rules, FAA Part 135 operational certificates, and state-level EMS licensing frameworks collectively shape fleet investment requirements and service territory definitions. FAA mandates on pilot rest cycles and aircraft maintenance intervals directly constrain air ambulance capacity expansion and route economics. Stakeholders must monitor evolving Medicare Advantage transport benefit designs and state Medicaid broker procurements to anticipate contract migration patterns.
Market Dynamics
The Patient Transportation Market confronts a fundamental restructuring as Medicare Advantage plans and state Medicaid agencies consolidate transportation benefit management under specialized brokers, compressing margins for traditional fleet operators while elevating data-analytics capabilities as the primary competitive differentiator.
Growth Catalysts
- CMS Hospital Readmissions Reduction Program:Penalty exposure under this framework compels health systems to contract scheduled non-emergency transport, converting previously ad-hoc patient mobility into recurring revenue streams for qualified providers.
- Telehealth integration:Remote patient monitoring platforms now trigger automated transport dispatch when biometric thresholds breach, embedding mobility services into virtual care workflows.
- Aging demographic concentration in Sun Belt states:Florida, Arizona, and Texas exhibit the fastest Medicare enrollment growth, concentrating demand for wheelchair-accessible vehicle fleets in these corridors.
Market Restraints
- FAA Part 135 operational constraints:Mandatory pilot rest cycles and aircraft maintenance intervals restrict air ambulance fleet utilization rates below 65%, capping revenue per airframe.
- Diesel price volatility:Ground ambulance operators face margin compression when fuel costs exceed 18% of trip revenue, with limited pass-through mechanisms under fixed Medicaid rates.
- Ride-share substitution in non-emergency segments:Uber Health and Lyft Healthcare erode volume for basic ambulatory transport, particularly in urban markets with sufficient driver supply.
Strategic Opportunities
- Rural hospital closure zones:Inter-facility transfer volume expands where obstetric and intensive care units shutter, creating dedicated air ambulance route opportunities across Kansas, Oklahoma, and Missouri.
- Artificial intelligence and predictive dispatch:Machine learning models that forecast no-show probabilities enable dynamic fleet positioning, reducing deadhead mileage by 12-15% in pilot deployments.
- State Medicaid broker consolidations:Procurements in California, New York, and Ohio favor vendors with integrated call center and mobile app platforms, advantaging technology-enabled entrants over legacy operators.
Industry Challenges
- Paramedic staffing shortages:National Registry certification pipelines produce insufficient graduates to replace attrition, forcing overtime reliance that elevates labor costs and burnout rates.
- Electronic health record interoperability:Transport providers struggle to integrate trip data with Epic and Cerner systems, delaying care coordination and reimbursement verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Transportation Market |
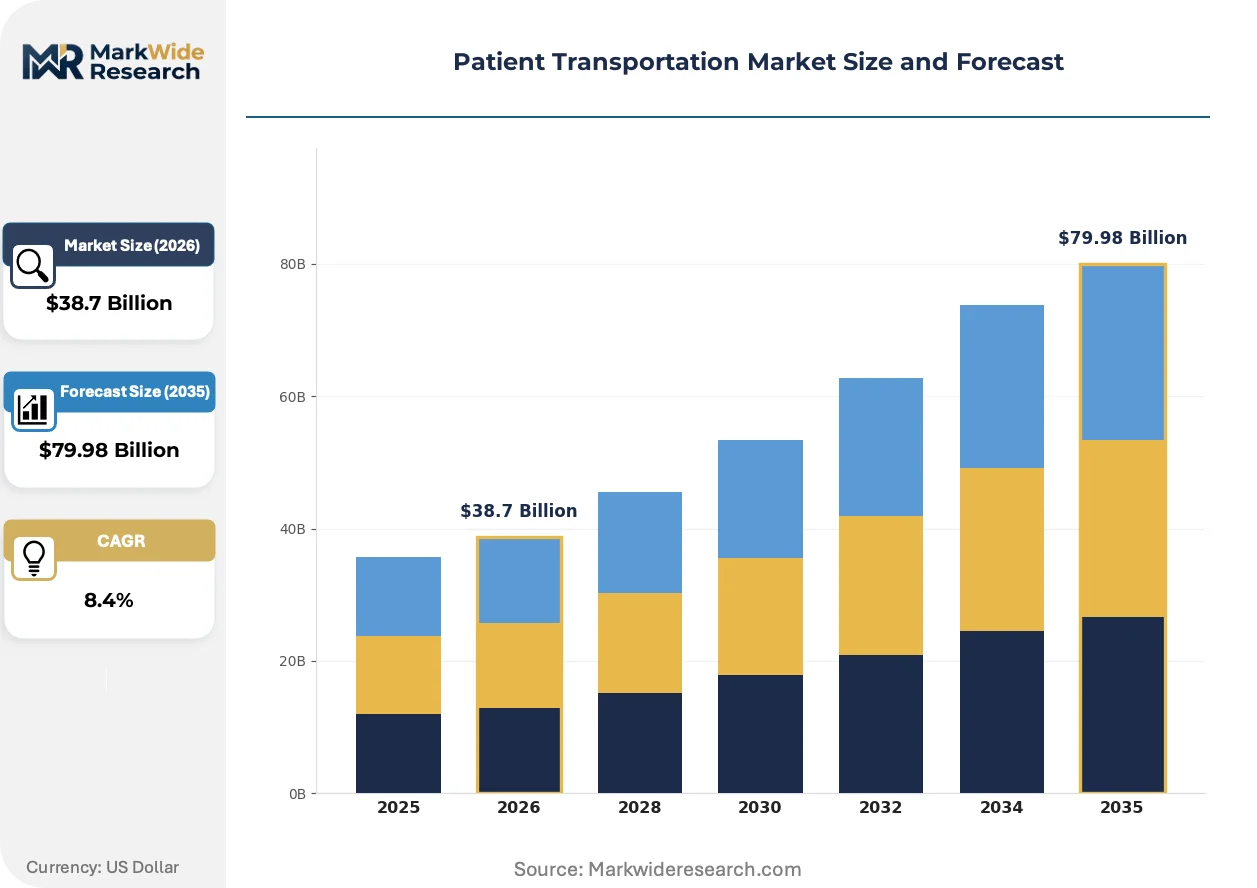
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ambulance Services, Non-Emergency Medical Transport, Air Ambulance, Medical Taxi End User: Hospitals, Home Care Providers, Rehabilitation Facilities, Nursing Homes Vehicle Type: Ground Vehicles, Air Transport, Specialty Vehicles, Wheelchairs Transportation Mode: Road, Air, Water, Rail |
| Companies Covered | Global Medical Response, ModivCare Solutions, American Medical Response, Falck, Acadian Ambulance Service, MTM, Logisticare, Air Methods Corporation, ATS Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Transportation Market Strategic Shifts
Digitization is reconfiguring competitive advantage away from asset ownership toward network orchestration capabilities, with three developments commanding strategic attention from operators and investors.
Telemedicine-equipped ambulances are fragmenting the traditional emergency response model. These mobile units carry two-way video diagnostic equipment enabling remote physician consultation during transport. Rural EMS agencies in Montana and North Dakota deploy them to extend specialist access without fixed clinic investment. The technology is compressing the addressable market for non-urgent emergency department transfers by resolving cases in transit.
California's Office of Statewide Health Planning and Development now mandates real-time data reporting from all licensed ambulance providers. The regulation forces capital expenditure on GPS tracking and electronic patient care reporting systems. Small municipal fire departments struggle with compliance costs, accelerating consolidation into regional authority structures.
Health plan procurement departments now require transport vendors to assume full risk for member satisfaction scores and on-time performance. This reverses decades of fee-for-service contracting. Medicaid managed care organizations in Michigan and Pennsylvania lead this transition, with penalties attaching to providers falling below 95% on-time arrival thresholds.
Patient Transportation Market Segmentation
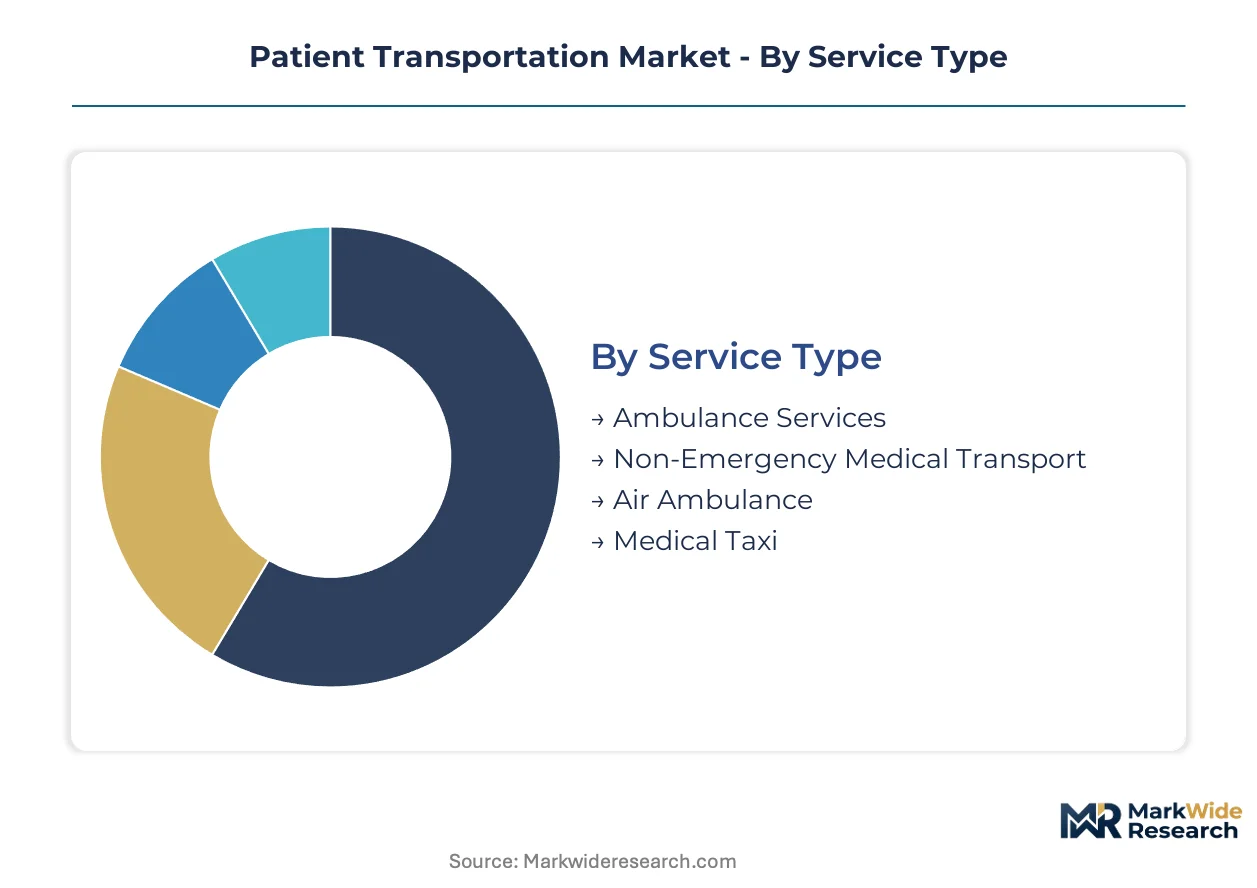
Patient transportation segmentation reveals divergent margin structures across service tiers. Emergency infrastructure commands premium pricing while scheduled mobility services generate volume through Medicaid and Medicare Advantage contracts.
Service Type:
Margin pools concentrate in emergency response networks with irreplaceable infrastructure, while non-emergency segments expand through value-based care contracts.
- Ambulance Services:Ground and air emergency units equipped with cardiac monitoring, oxygen delivery, and stretcher systems maintain the highest per-trip revenue. CMS reimbursement frameworks and state EMS licensing create defensible territory positions for established fleet operators.
- Non-Emergency Medical Transport:Scheduled wheelchair and stretcher van services for dialysis, chemotherapy, and post-acute appointments generate recurring volume. Medicaid managed care organizations in Michigan and Pennsylvania now impose 95% on-time performance penalties, elevating dispatch technology as the critical capability.
- Air Ambulance:FAA Part 135 rotary-wing and fixed-wing operations serve rural access gaps and inter-facility critical care transfers. Pilot rest cycle mandates cap fleet utilization below 65%, constraining revenue per airframe.
- Medical Taxi:Basic ambulatory transport for mobile patients faces substitution pressure from Uber Health and Lyft Healthcare in urban corridors with sufficient driver density.
Ambulance services hold installed capacity. Non-emergency medical transport is rotating up the share rankings.
End User:
Contract concentration follows CMS penalty exposure and readmission risk profiles across care settings.
- Hospitals:Health systems under Hospital Readmissions Reduction Program penalties contract scheduled transport to reduce emergency department utilization. Florida, Arizona, and Texas systems exhibit fastest contract expansion alongside Medicare enrollment growth.
- Home Care Providers:Post-acute mobility services connect discharged patients to follow-up appointments. Demand concentrates where telehealth platforms trigger automated dispatch when remote monitoring thresholds breach.
- Rehabilitation Facilities:Scheduled van services for physical and occupational therapy appointments generate predictable routing density.
- Nursing Homes:Skilled nursing facilities require stretcher-equipped vehicles for specialist consultations and acute transfers.
Hospitals anchor contract volume. Home care providers are climbing the fastest as virtual care workflows embed mobility services.
Vehicle Type:
Capital deployment intensity separates fleet owners from technology-enabled network orchestrators.
- Ground Vehicles:Type II and Type III ambulances plus wheelchair-accessible vans constitute the dominant installed base. Diesel price volatility above 18% of trip revenue compresses margins under fixed Medicaid rates.
- Air Transport:Rotary-wing and fixed-wing aircraft with pressurized cabins and ventilator support serve inter-facility transfers exceeding 150 miles.
- Specialty Vehicles:Bariatric stretcher units and neonatal transport incubators address clinical sub-specialties with limited fleet availability.
- Wheelchairs:Patient-owned and provider-supplied mobility devices reduce vehicle modification requirements for ambulatory segments.
Ground vehicles hold installed capacity. Air transport maintains premium positioning despite utilization constraints.
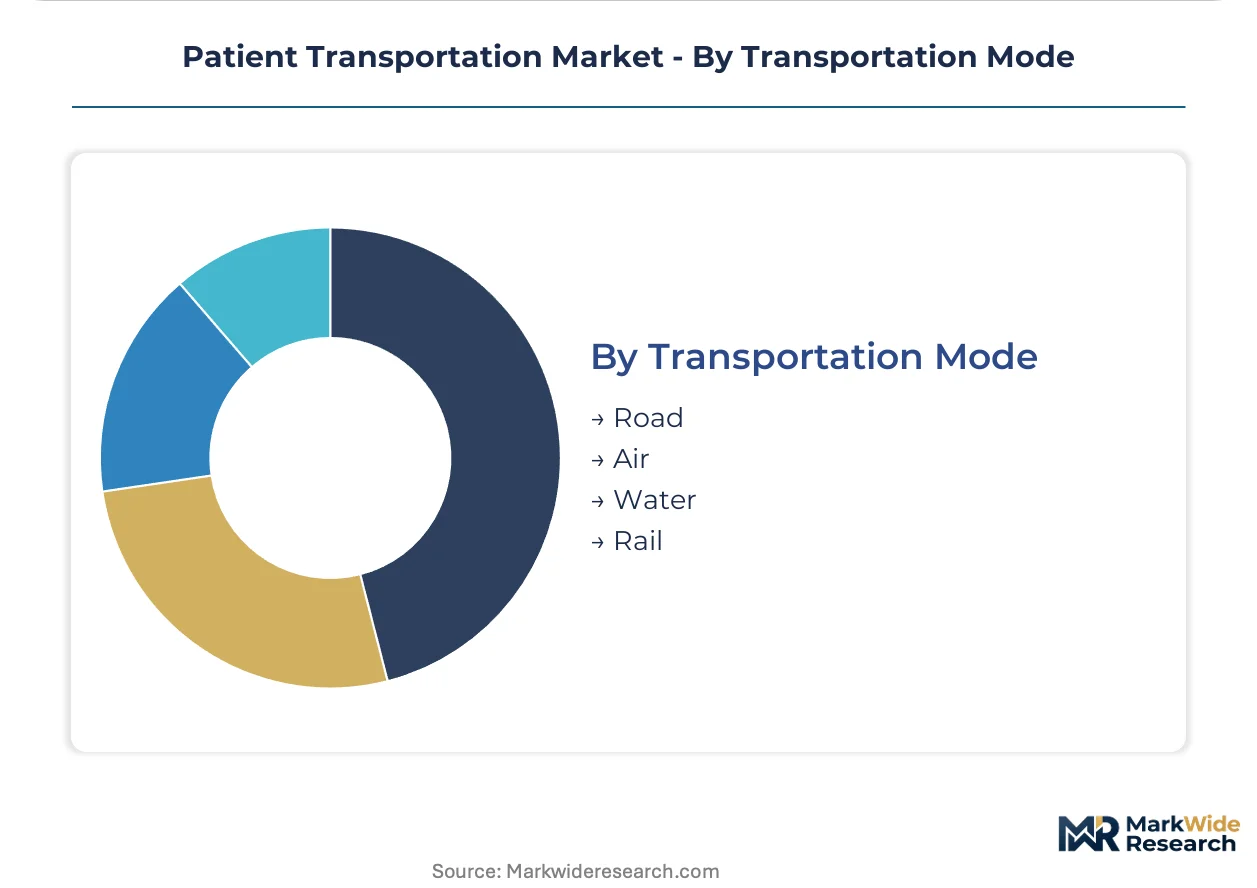
Transportation Mode:
Route economics and regulatory jurisdiction determine competitive entry barriers across mobility infrastructure.
- Road:Paved surface networks enable 90% of patient movements through ground ambulance and medical van services. State-level EMS licensing and municipal franchise agreements structure territory allocation.
- Air:Helicopter and fixed-wing operations bypass ground distance constraints for rural hospital closures and trauma center access. FAA operational certificates and pilot rest regulations constrain capacity expansion.
- Water:Marine ambulance services serve island communities and coastal regions with limited bridge infrastructure.
- Rail:Dedicated medical cars on intercity routes address long-distance transfers where air transport is contraindicated or unavailable.
Road infrastructure holds installed capacity. Air transport is expanding most quickly where rural hospital closures widen access gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Medicaid-dependent markets exhibit elastic demand where transport brokers compete on unit cost. Medicare Advantage corridors show inelastic demand where health systems prioritize network reliability over trip pricing.
United States
Medicare Advantage enrollment growth in Florida, Arizona, and Texas concentrates contract volume for wheelchair-accessible fleets. CMS Hospital Readmissions Reduction Program penalties compel health systems to purchase scheduled non-emergency transport. Miami-Dade and Houston medical corridors exhibit fastest broker procurement activity.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia expand demand for inter-facility transfer services. The country's national healthcare regulator enforces strict vehicle equipment standards for patient transport providers. Berlin-Brandenburg clusters host technology-enabled dispatch platforms serving statutory insurance contracts.
United Kingdom
NHS England's patient transport frameworks prioritize cost efficiency over asset ownership. The Care Quality Commission inspects and licenses ambulance operators against clinical governance standards. London and Southeast England concentrate demand for neonatal and bariatric specialty vehicle services.
Japan
Super-aging prefectures in rural Tohoku and Hokkaido widen air ambulance access gaps. METI guidelines on emergency medical service digitization mandate GPS tracking and electronic patient care reporting. Kanto region around Tokyo hosts consolidated dispatch technology vendors serving metropolitan fire departments.
Canada
Provincial health authorities in Ontario and Quebec consolidate non-emergency transport under centralized brokerage models. Health Canada regulates air ambulance operations through aviation medical standards. Prairie Provinces face rural hospital closure patterns that expand inter-facility rotary-wing transfer volume.
Patient Transportation Market Competitive Environment
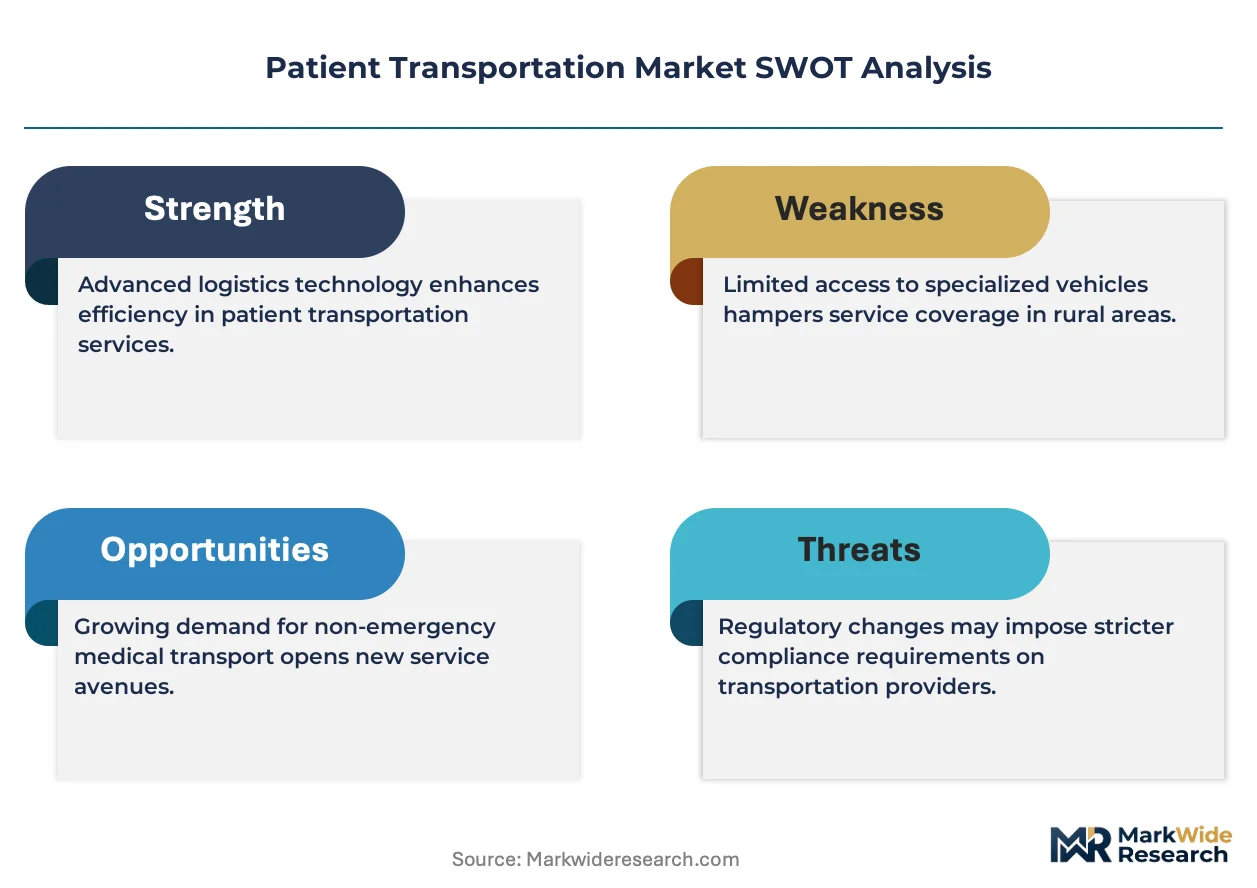
Technology leadership and cost leadership are held by different player archetypes in patient transportation. Fleet-heavy operators sustain cost advantages through owned ambulance infrastructure and municipal franchise agreements. Technology-enabled brokers capture margin through centralized dispatch platforms and data-analytics capabilities. Two strategic moves dominate: state Medicaid procurement consolidations favoring integrated technology platforms, and telehealth partnerships embedding transport into virtual care workflows.
Within the fleet-owning tier, Global Medical Response and American Medical Response occupy positions anchored by emergency infrastructure and territory licenses. ModivCare Solutions exemplifies the technology-enabled archetype, competing through Medicaid brokerage platforms rather than vehicle assets. Air Methods Corporation represents the premium air ambulance segment where FAA operational constraints limit competitive entry.
| Leading Market Players |
|---|
| Global Medical Response |
| ModivCare Solutions |
| American Medical Response |
| Falck |
| Acadian Ambulance Service |
| MTM |
| Logisticare |
| Air Methods Corporation |
| ATS Healthcare Solutions |
| Others |
Value Chain & Pricing Dynamics
Air ambulance fleet utilization caps below 65% under FAA Part 135 pilot rest mandates concentrate pricing power among certificate holders while elevating fixed cost recovery thresholds across rotary-wing and fixed-wing operations. This capacity constraint cascades through inter-facility transfer markets, where rural hospital closure zones in Kansas, Oklahoma, and Missouri generate route premiums that ground-based competitors cannot replicate.
Pricing Analysis
After-sales revenue from maintenance contracts and pilot training certifications drives lifetime value for air ambulance operators facing utilization ceilings. Three-tier pricing structure across emergency response, scheduled non-emergency transport, and basic medical taxi services reflects CMS reimbursement tiers and Medicaid managed care rate schedules. Cost compression in non-emergency segments intensifies because ride-share substitution and broker consolidation compress per-trip margins. Medicaid-dependent markets exhibit highest price sensitivity, while Medicare Advantage corridors prioritize network reliability over unit pricing.
Supply Chain Analysis
Inbound logistics costs for specialized airframe components and avionics systems concentrate through FAA-certified maintenance facilities in the United States, Germany, and Canada. Fleet operators draw from single-source dependencies on rotary-wing manufacturers and stretcher-mounted cardiac monitoring equipment. Supply chain risk centers on tariff exposure for imported medical devices and aircraft parts. Distribution runs through regional EMS authority structures and state Medicaid brokerage platforms rather than direct hospital contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient transportation functions as a regulatory entrenchment market where FAA operational certificates and state EMS licensing create switching costs that protect incumbent positions. Municipal franchise agreements and territory licenses compound this defensive moat.
For Market Incumbents: Shield dispatch technology investments from margin erosion by embedding AI-driven predictive positioning into Medicaid broker contracts in California, New York, and Ohio. Consolidate regional fire department authorities facing California's real-time data reporting mandates to capture compliance-driven consolidation volume. Paramedic staffing shortages present acquisition opportunities for credential pipelines.
For New Entrants and Emerging Players: Rural hospital closure zones in Kansas, Oklahoma, and Missouri present under-served inter-facility transfer demand where air ambulance incumbents lack route density. Telemedicine-equipped ambulance deployment in Montana and North Dakota offers white-space entry with lower capital requirements than full emergency infrastructure. Target state Medicaid broker procurements favoring integrated call center and mobile app platforms.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dispatch platform vendors over fleet-heavy operators as Medicare Advantage and Medicaid consolidation elevates data-analytics capabilities. Long-term viability hinges on regulatory entrenchment depth and broker contract tenure. Watch FAA certificate transfer activity and state-level EMS licensing relaxation as inflection indicators for competitive entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Medicaid Brokerage Platform Integration | Consolidated procurement in Michigan and Pennsylvania favors vendors with 95% on-time performance guarantees. |
| Telemedicine-Equipped Ambulance Deployment | Montana and North Dakota rural EMS agencies extend specialist access without fixed clinic investment. |
| AI-Driven Predictive Dispatch | Machine learning models reduce deadhead mileage by 12-15% in pilot deployments. |
| Regional Fire Department Consolidation | California's real-time data reporting mandates accelerate municipal authority mergers. |
| Air Ambulance Route Expansion | Rural hospital closures in Kansas, Oklahoma, and Missouri create dedicated inter-facility transfer corridors. |
Study Parameters
Operator-level perspectives from EMS dispatch directors, Medicaid managed care procurement officers, FAA certificate holders, and hospital system logistics managers anchored the qualitative base. Primary interviews combined with secondary validation from CMS Medicare data, state EMS licensing databases, and GPO contracts. Triangulation employed bottom-up fleet capacity modeling and top-down reimbursement flow analysis.
Sensitivity analysis tested forecast outputs across diesel price volatility thresholds, Medicare Advantage enrollment trajectories, and paramedic graduation pipeline assumptions. Segmentation dimensions modeled include service type, end-user setting, vehicle category, and transportation mode. CAGRs derived from contracted trip volume growth and reimbursement rate indexing. Industry-specific inputs incorporated FAA Part 135 utilization constraints and state Medicaid broker procurement schedules.
Forecasts assume regulatory continuity in FAA operational mandates and CMS reimbursement frameworks; material policy shifts would require re-modeling. Specific risk factors include pilot rest cycle regulation changes, Medicare Advantage transport benefit redesigns, and state-level EMS licensing reciprocity agreements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Long Term Care Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Blood Bank Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Spa Services Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
US Healthcare Staffing Market