
 Faecal Extraction System Market | 2026-2036
Faecal Extraction System Market Size, Share, and Industry Trends Forecast 2026-2036
Faecal Extraction System Market Foresight
Polypropylene is restructuring cost profiles across disposable kit manufacturing as suppliers shift away from polystyrene for improved chemical resistance and lower per-unit weight. Thermo Fisher Scientific leverages its diagnostic consumables infrastructure to sustain volume leadership in North American hospital supply chains. QIAGEN N.V. anchors its position through integrated nucleic acid extraction workflows that bundle faecal sample prep with downstream sequencing protocols. bioMérieux SA differentiates via automated pathogen detection systems that incorporate pre-analytical extraction modules for enteric disease panels.
A faecal extraction system is a laboratory or clinical device engineered to isolate, concentrate, and prepare stool-derived biological material—typically operating with pore filtration thresholds between 0.22 and 5.0 micrometers and temperature-controlled processing chambers—for subsequent diagnostic or analytical procedures. Automated extractors command premium positioning due to throughput advantages and reduced technician exposure to biohazardous specimens, while manual extractors retain share in resource-constrained settings and field-deployable research contexts. Vacuum-based technology leads installation base owing to reproducible yield consistency, though filtration systems are gaining traction in environmental microbiome studies requiring particle-size selectivity. Disposable kits generate recurring revenue streams that deepen vendor-customer relationships across diagnostic laboratory accounts.
FDA enforcement of 21 CFR Part 820 quality system regulations shapes device design controls and post-market surveillance obligations for manufacturers distributing in the United States. EMA Medical Device Regulation requirements and ISO 13485 certification standards govern European market access, with notified bodies scrutinizing biocompatibility and sterility assurance for patient-contact components. Stakeholders must monitor evolving reimbursement codes for stool-based colorectal cancer screening and microbiome diagnostics, as coverage decisions will directly influence hospital capital allocation for extraction platform upgrades.
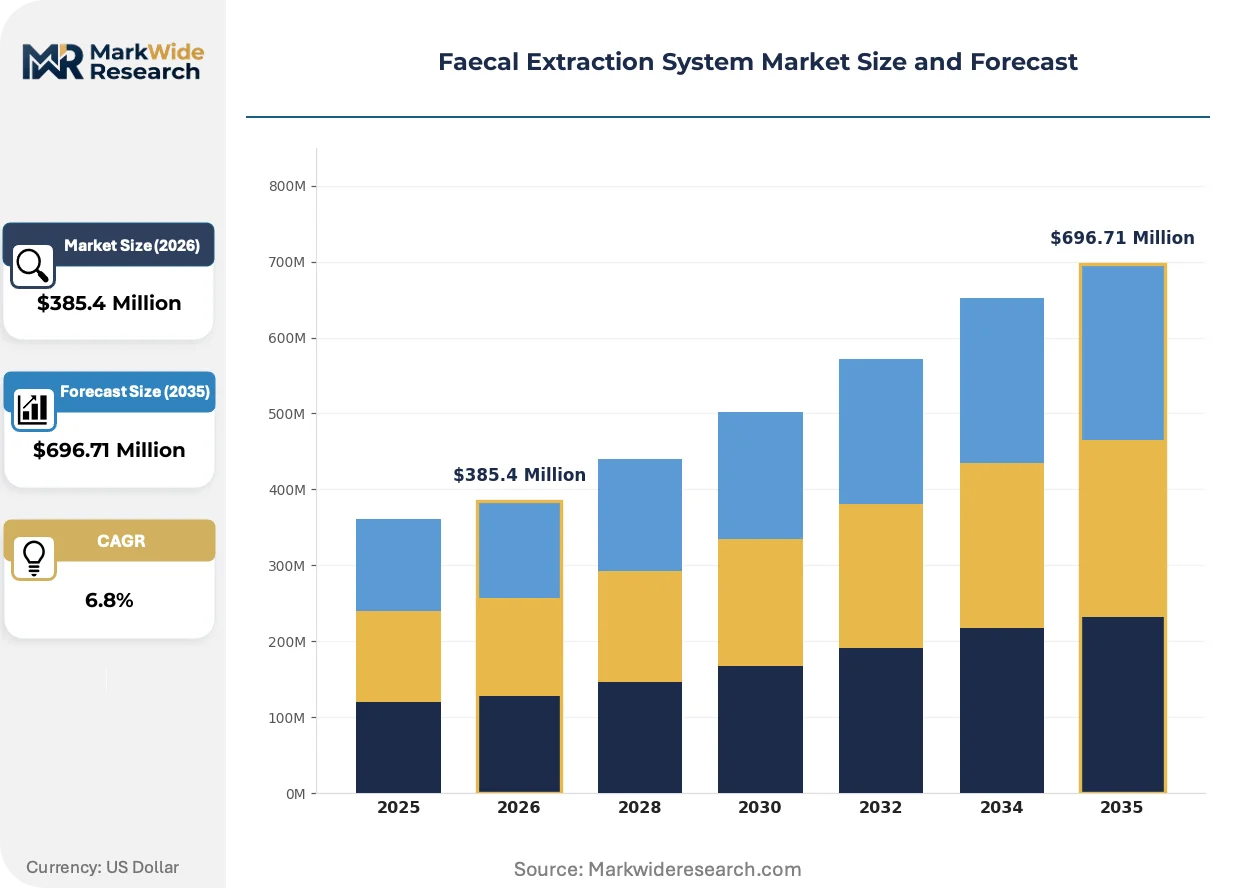
Market Dynamics
Automated faecal extraction platforms are compressing technician labor requirements while tightening FDA quality benchmarks for stool-based colorectal cancer screening reshape hospital capital allocation cycles.
Growth Catalysts
- Stool-based colorectal cancer screening mandates:Medicare reimbursement expansion for faecal immunochemical testing in the United States accelerates automated extractor procurement in hospital laboratories.
- Microbiome therapeutics pipeline maturation:Pharmaceutical sponsors require standardized nucleic acid extraction protocols for Phase II/III trials, pulling demand for integrated sample prep systems.
- Polypropylene resin substitution:Chemical resistance advantages over polystyrene reduce per-unit kit weight and shipping costs for disposable consumables manufacturers.
Market Restraints
- Capital intensity of automated platforms:Mid-sized diagnostic laboratories face constrained budgets for vacuum-based extractor installations exceeding $150,000 per unit.
- Specialized technician training requirements:Biohazard handling certification and nucleic acid contamination protocols limit workforce scalability in resource-constrained settings.
- EMA Medical Device Regulation compliance timelines:Extended notified body review periods for sterility assurance documentation delay European commercialization schedules.
Strategic Opportunities
- Point-of-care decentralization:Portable manual extraction kits address rural clinic demand for field-deployable enteric pathogen detection in India and Brazil.
- Environmental microbiome research expansion:Filtration-based systems with particle-size selectivity capture soil and water sample processing workflows beyond clinical applications.
- ISO 13485 certification arbitrage:Contract manufacturers in South Korea and Singapore offer accelerated quality system implementation for Western device sponsors seeking dual-market clearance.
Industry Challenges
- Integration complexity with legacy laboratory information systems:Automated extractors require middleware development for bidirectional data exchange with hospital electronic health record platforms.
- Reimbursement code fragmentation:Inconsistent CPT coding for stool-based microbiome diagnostics across US commercial payers creates revenue recognition uncertainty for laboratory service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faecal Extraction System Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Extractors, Automated Extractors, Disposable Kits, Reusable Kits End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Providers Technology: Mechanical Systems, Vacuum Systems, Gravity Systems, Filtration Systems Application: Medical Diagnostics, Research Studies, Environmental Testing, Waste Management |
| Companies Covered | Thermo Fisher Scientific Inc., QIAGEN N.V., Abbott Laboratories, Roche Diagnostics Corporation, bioMérieux SA, Bühlmann Laboratories AG, Arbor Assays, DRG Instruments GmbH, Calpro AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faecal Extraction System Market Shifts & Advancements
Sample integrity preservation during pre-analytical processing is commanding R&D priority as multi-omics analysis expands downstream analytical requirements for stool-derived material.
Lyophilized stabilization chemistry is rewriting transport logistics for faecal specimens. Ambient-temperature shipping eliminates cold-chain dependency for reference laboratories collecting from distributed collection sites. Diagnostic service providers in Germany and Japan are adopting stabilized collection tubes to consolidate testing volumes into centralized high-throughput facilities.
EMA Medical Device Regulation Annex I general safety and performance requirements are tightening biocompatibility documentation for patient-contact collection components. Manufacturers must submit cytotoxicity and sensitization test reports for polypropylene and silicone materials used in kit assemblies. European notified bodies are prioritizing sterilization validation for single-use extraction columns, extending technical file review timelines for new product registrations.
Consolidated procurement through group purchasing organizations is compressing vendor negotiation cycles for hospital laboratory systems. Multi-year supply agreements with penalty clauses for delivery failures are displacing spot-market purchasing for disposable extraction consumables. Academic medical centers in the United States are bundling extractor platform selection with exclusive reagent supply commitments to secure volume-based pricing tiers.
Faecal Extraction System Market Segmentation
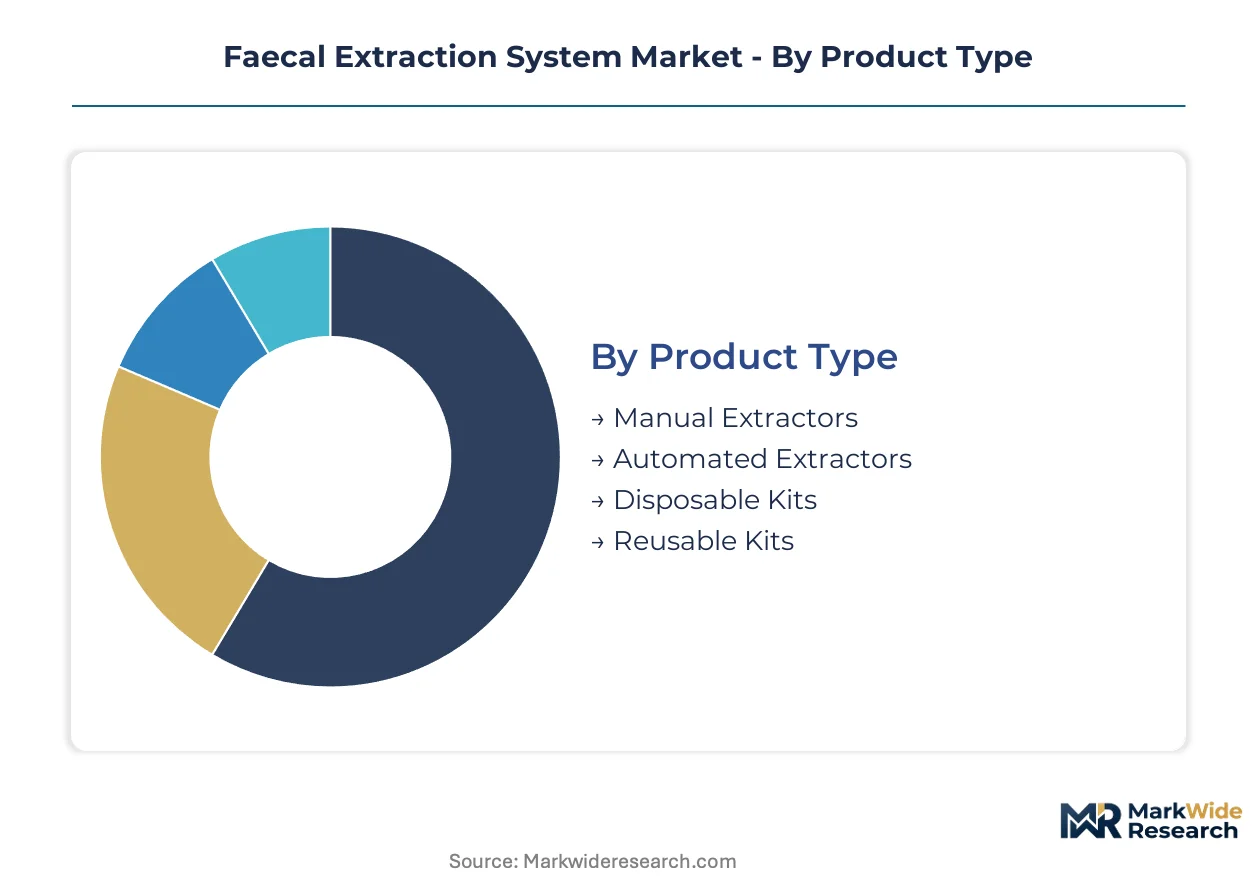
Segmentation in the faecal extraction system market reveals distinct procurement patterns across product tiers and end-use settings. Supply concentration varies sharply by category, with automated platforms consolidating around diagnostic laboratory chains while manual systems fragment across decentralized research networks.
Product Type:
Supply concentration clusters around automated platforms in North American hospital systems, while manual extractors distribute across smaller diagnostic networks.
- Manual Extractors:Hand-operated devices requiring technician intervention for specimen processing, typically deployed in field research contexts and resource-limited settings. Demand concentrates in rural Brazilian clinics and Indian primary health centers where capital constraints exclude automated alternatives. Cold-chain independence and minimal maintenance requirements sustain procurement despite throughput limitations.
- Automated Extractors:Programmable systems with vacuum-driven or mechanical processing chambers achieving 50-200 samples per hour. German hospital laboratories and Japanese academic medical centers dominate procurement volumes, driven by FDA-cleared colorectal cancer screening protocols and EMA microbiome diagnostic workflows. Thermo Fisher Scientific and QIAGEN N.V. anchor supply relationships through multi-year service contracts.
- Disposable Kits:Single-use polypropylene assemblies with pre-loaded buffers and collection vessels. Recurring revenue streams deepen vendor lock-in across US reference laboratory networks.
- Reusable Kits:Stainless steel or autoclavable plastic components for high-volume processing facilities. Cost-per-test economics favor centralized European diagnostic hubs with validated sterilization infrastructure.
Today's leader: Automated Extractors. Tomorrow's challenger: Disposable Kits.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean research institute procurement.
- Hospitals:Integrated health systems with centralized laboratory medicine departments. US academic medical centers and German university hospitals drive premium extractor platform adoption through bundled capital equipment budgets.
- Diagnostic Laboratories:Independent reference laboratories and hospital-affiliated testing facilities. Japanese commercial labs and US specialty gastrointestinal pathology providers concentrate demand for high-throughput automated systems.
- Research Institutes:Academic and government-funded microbiome research centers. Filtration-based manual systems dominate European environmental microbiology programs and US National Institutes of Health-funded gut-brain axis studies.
- Home Care Providers:Direct-to-consumer collection services and remote patient monitoring platforms. Emerging demand in UK NHS pilot programs for stool-based screening decentralization.
Diagnostic Laboratories command current volume leadership. Home Care Providers are gaining share fastest through screening decentralization pilots.
Technology:
Application-specific performance requirements segment technology adoption across clinical precision and environmental throughput needs.
- Mechanical Systems:Centrifugal or agitation-based separation devices with programmable cycle parameters. US hospital laboratories specify these for standardized colorectal cancer screening workflows requiring reproducible nucleic acid yields.
- Vacuum Systems:Negative-pressure-driven extraction with membrane filtration or solid-phase binding matrices. German diagnostic chains and Japanese commercial laboratories anchor the installed base due to yield consistency advantages.
- Gravity Systems:Passive sedimentation and density-gradient separation without powered components. Field-deployable research in Brazilian environmental monitoring and Indian rural health screening sustains niche demand.
- Filtration Systems:Pore-size-selective membranes ranging from 0.22 to 5.0 micrometers. European soil microbiome research programs and US environmental protection agency water quality monitoring drive specialized procurement.
Vacuum Systems hold established dominance. Filtration Systems are climbing the fastest through environmental microbiome expansion.
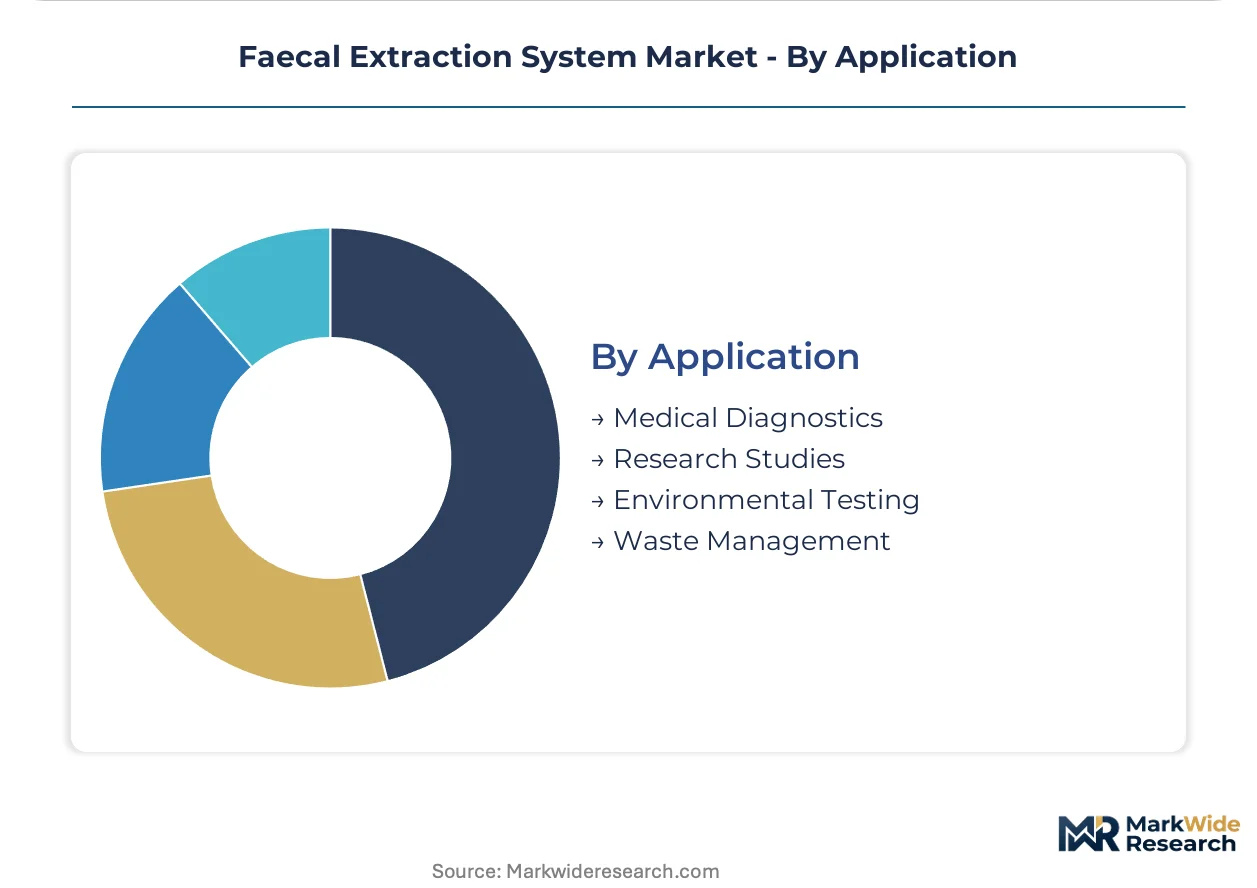
Application:
Customer type differentiation separates regulated diagnostic workflows from exploratory research procurement with divergent compliance burdens.
- Medical Diagnostics:FDA-cleared and EMA-authorized clinical testing for colorectal cancer screening, enteric pathogen detection, and microbiome dysbiosis assessment. US Medicare reimbursement codes and German statutory health insurance coverage decisions directly influence capital allocation.
- Research Studies:Academic and pharmaceutical-sponsored investigations into gut-brain axis mechanisms, therapeutic microbiome modulation, and host-pathogen interactions. QIAGEN N.V. and bioMérieux SA bundle extraction platforms with sequencing workflows for Phase II/III trial standardization.
- Environmental Testing:Soil, water, and wildlife specimen processing for ecosystem health monitoring. German federal environment agency contracts and US environmental protection agency protocols specify filtration-based systems with particle-size validation.
- Waste Management:Biosafety containment and pathogen inactivation for clinical and research specimen disposal. Japanese infectious disease research facilities and US biocontainment laboratories drive specialized containment extractor procurement.
Medical Diagnostics anchors revenue concentration. Research Studies present the steepest expansion trajectory through pharmaceutical pipeline maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital laboratories anchor procurement volumes for automated faecal extraction platforms, driven by statutory health insurance coverage for colorectal cancer screening and microbiome diagnostic workflows. FDA-cleared stool-based testing protocols and EMA Medical Device Regulation compliance requirements reshape capital allocation cycles across major diagnostic hubs.
United States
Medicare reimbursement expansion for faecal immunochemical testing accelerates automated extractor procurement in academic medical centers. FDA enforcement of 21 CFR Part 820 quality system regulations tightens device design controls for manufacturers distributing domestically. Boston and San Diego biotech clusters drive demand for integrated nucleic acid extraction workflows in pharmaceutical-sponsored microbiome trials.
Germany
Statutory health insurance coverage decisions directly influence hospital laboratory capital budgets for vacuum-based extraction systems. EMA Medical Device Regulation Annex I general safety and performance requirements extend notified body review timelines for sterility assurance documentation. The Rhine-Ruhr metropolitan region concentrates diagnostic laboratory chains retrofitting workflows for gut microbiota research.
Japan
PMDA clearance pathways for microbiome-based diagnostics tighten quality benchmarks for sample integrity in commercial testing facilities. METI industrial standards govern biocompatibility documentation for patient-contact collection components. Tokyo and Osaka academic medical centers dominate procurement of high-throughput automated systems for enteric disease panel standardization.
United Kingdom
NHS pilot programs for stool-based screening decentralization generate emerging demand for portable manual extraction kits in primary care networks. MHRA post-market surveillance obligations align with EMA regulatory frameworks for single-use extraction column sterilization validation. The Cambridge-Oxford-London biotech corridor anchors pharmaceutical-sponsored gut-brain axis research requiring standardized sample prep protocols.
India
CDSCO medical device registration requirements for in-vitro diagnostics create compliance entry barriers for imported automated platforms. Ayushman Bharat health coverage expansion drives demand for cost-optimized manual extractors in rural primary health centers. Hyderabad and Bengaluru diagnostic laboratory networks concentrate procurement for field-deployable enteric pathogen detection in resource-constrained settings.
Faecal Extraction System Market Competitive Landscape
Global majors compete with regional champions across diagnostic consumables infrastructure and integrated workflow bundling. The supplier base consolidates around multi-year service contracts with hospital laboratory systems while fragmenting across decentralized research procurement. Three archetypes dominate: diversified life science conglomerates with diagnostic consumables scale, nucleic acid extraction specialists with sequencing integration capabilities, and automated pathogen detection system providers with pre-analytical module integration. Competitive moves center on exclusive reagent supply commitments for volume-based pricing and middleware development for bidirectional laboratory information system connectivity.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. anchors North American hospital supply chain relationships through diagnostic consumables infrastructure. QIAGEN N.V. occupies a position within the nucleic acid extraction specialist tier, representing integrated workflow bundling that combines faecal sample preparation with downstream sequencing protocols. bioMérieux SA exemplifies the automated pathogen detection archetype, sitting within European commercial laboratory networks through pre-analytical extraction module integration for enteric disease panels.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Abbott Laboratories |
| Roche Diagnostics Corporation |
| bioMérieux SA |
| Bühlmann Laboratories AG |
| Arbor Assays |
| DRG Instruments GmbH |
| Calpro AS |
| Others |
Supply & Pricing Matrix
Polypropylene resin substitution simultaneously compresses per-unit kit manufacturing costs and consolidates supplier leverage among German and South Korean polymer compounders serving diagnostic consumables producers. This materials transition feeds directly into pricing power redistribution across automated platform vendors and disposable kit manufacturers.
Pricing Analysis
Input-cost pass-through from polypropylene resin contracts shapes three-tier pricing structure across premium, standard, and economy levels for disposable extraction kits. Price differentiation rests on ISO 13485 certification tier and volume scale commitments from hospital laboratory networks. Pricing pressure stems from group purchasing organization consolidation in US academic medical centers. Diagnostic laboratories exhibit highest price sensitivity, while pharmaceutical sponsors in microbiome trials show lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polystyrene resin suppliers that US and European kit manufacturers are rapidly displacing. Raw material dependencies center on polypropylene pellets, silicone collection vessel seals, and lyophilized buffer chemistries. Supply chain risk manifests as tariff exposure on Chinese-sourced laboratory plastics. Distribution runs through diagnostic consumables distributors with exclusive territory agreements and direct-to-laboratory service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on polypropylene-driven cost-down capture and premium-tier automated platform positioning in German and Japanese hospital systems.
For Market Incumbents: To counter mid-sized diagnostic laboratory budget constraints, Thermo Fisher Scientific and QIAGEN N.V. should deepen backward integration into polypropylene kit molding in South Korea and accelerate ISO 13485 certification arbitrage services for dual-market clearance seekers. Exclusive reagent supply commitments bundled with extractor platform selection defend installed base relationships against emerging automated pathogen detection specialists. For New Entrants and Emerging Players: Rural Indian primary health centers present the most penetrable buyer archetype for portable manual extraction kits addressing Ayushman Bharat coverage expansion. Field-deployable enteric pathogen detection in Brazilian environmental monitoring programs offers secondary white-space. A go-to-market angle through CDSCO-registered contract manufacturers enables compliance-light entry before automated platform competition intensifies. For Investors and Strategic Acquirers: Valuations sit cheapest among nucleic acid extraction specialists lacking sequencing workflow integration. Long-term viability over the next decade favors automated platform vendors with hospital system service contracts and recurring disposable kit revenue streams. The signal to watch is EMA Medical Device Regulation clearance timeline compression for sterility assurance documentation, indicating regulatory capacity expansion that accelerates European commercialization schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Stabilization Chemistry Expansion | Ambient-temperature shipping eliminates cold-chain dependency for German reference laboratories consolidating distributed collection volumes. |
| ISO 13485 Certification Arbitrage Services | South Korean and Singaporean contract manufacturers accelerate quality system implementation for Western device sponsors seeking dual-market clearance. |
| Middleware Development for LIS Integration | Bidirectional data exchange with hospital electronic health record platforms reduces automated extractor installation friction in US academic medical centers. |
| Point-of-Care Manual Kit Localization | Field-deployable extraction systems address rural clinic demand in India and Brazil where capital constraints exclude automated alternatives. |
| Environmental Filtration System Diversification | Particle-size selectivity captures soil and water sample processing workflows beyond clinical applications in European microbiome research programs. |
Research Methodology
Multiple input streams — hospital laboratory procurement managers, diagnostic consumables distributors, biomedical engineers at academic medical centers, and regulatory affairs specialists at notified bodies — were reconciled against FDA 510(k) filings, EMA technical documentation databases, CMS Medicare reimbursement code updates, and ISO 13485 certification registries. Primary interviews with GPO contracts managers and secondary validation through hospital capital equipment budgets enabled bottom-up and top-down triangulation across the faecal extraction system value chain.
Historical automated extractor installation data cross-referenced against panel input from German statutory health insurance coverage decision-makers and Japanese PMDA quality benchmark specialists shaped the analytical framework. Segmentation dimensions modeled include product type, end-user setting, technology platform, and application workflow across the projection horizon. CAGRs derived from instrument replacement cycles, disposable kit consumption rates, and microbiome diagnostic protocol adoption curves.
Underlying measurement precision varies by segment; automated extractor volumes in US and German hospital systems carry tighter precision than manual kit deployment in Indian rural health settings. Forecasts reflect assumptions about EMA Medical Device Regulation review period stabilization and Medicare reimbursement code consolidation for stool-based screening. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Operating Light Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Cath Lab Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
MRI Transport Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Life Support Systems Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Blood Bank Refrigerators Market