
 US Retail Clinics Market | 2026-2036
US Retail Clinics Market Size, Share, and Industry Trends Forecast 2026-2036
US Retail Clinics Market Analysis
CMS reimbursement expansion for remote patient monitoring is rebalancing the cost-of-entry calculus for retail clinic operators seeking federal program participation. CVS Health leverages its pharmacy footprint to sustain high patient throughput at MinuteClinic locations across 33 states. Walmart anchors rural access through its standalone clinic model, while Amazon One Medical competes on digital-first primary care integration with physical retail touchpoints.
US Retail Clinics are ambulatory care facilities embedded within retail environments, typically staffed by nurse practitioners or physician assistants and equipped to deliver episodic care for low-acuity conditions, chronic disease monitoring, and preventive services with average visit durations under 30 minutes. Their primary commercial purpose is reducing total cost of care by diverting non-emergency demand from emergency departments and traditional physician offices while capturing pharmaceutical and ancillary service revenue through co-location. Minute Clinics within pharmacy chains represent the most mature segment with established payer contracts, while Occupational Health Centers are gaining structural importance as employers directly contract for workforce health services. Diagnostic Testing as a service offering carries disproportionate margin contribution due to lab referral economics and in-clinic rapid test capabilities.
FDA oversight of point-of-care diagnostic devices, CMS conditions of participation for clinic-based services, and state-level scope-of-practice regulations governing nurse practitioner independence collectively determine operational feasibility and reimbursement eligibility across jurisdictions. OSHA workplace health standards further shape service design for employer-sponsored clinic programs. Stakeholders must monitor evolving state legislation on independent practice authority and telehealth parity laws to assess geographic expansion viability and labor model economics.
Market Dynamics
Employer-sponsored clinic contracts are consolidating purchasing power across regional health systems, forcing retail operators to restructure service bundles around occupational health metrics rather than fee-for-service volumes. This shift compresses margin structures while locking in multi-year revenue commitments.
Growth Catalysts
- CMS Chronic Care Management Reimbursement:Federal payment codes now cover remote monitoring and care coordination delivered at retail sites, expanding billable service scope beyond acute episodic visits.
- Texas Medicaid Expansion Momentum:Legislative pressure in the largest uninsured state is creating enrollment pipelines that direct newly covered populations toward pharmacy-based primary care access points.
- Point-of-Care Diagnostics:Rapid molecular testing platforms are compressing lab turnaround times, enabling same-day prescribing decisions that differentiate retail channels from traditional office-based workflows.
Market Restraints
- Nurse Practitioner Scope Limitations:Restrictive practice authority in Florida and California forces physician oversight costs that erode unit economics in high-volume markets.
- Real Estate Concentration:Prime retail footprints in metropolitan Texas corridors command lease premiums that consume 18-22% of clinic operating budgets, constraining rural expansion.
- Telehealth Substitution:Virtual primary care platforms are capturing low-acuity demand that previously defaulted to walk-in clinic visits, particularly among commercially insured urban populations.
Strategic Opportunities
- CMS Accountable Care Organization Alignment:Risk-bearing health systems in California are contracting retail clinics as downstream referral nodes for attributed Medicare beneficiaries, creating shared savings participation.
- Chronic Disease Management Bundles:Hypertension and diabetes monitoring protocols are migrating from specialist offices to retail settings, enabled by connected device integration and pharmacy fulfillment adjacency.
- Rural Health Clinic Certification:Federal designation programs are opening cost-based reimbursement pathways for retail operators locating in designated shortage areas across the Mountain West and Deep South.
Industry Challenges
- Credentialing Velocity:Payer enrollment timelines for new nurse practitioners stretch 90-120 days in Florida, creating staffing gaps that throttle patient throughput during peak demand periods.
- EHR Interoperability Friction:Retail clinic platforms lack bidirectional data exchange with dominant hospital system records in Texas and California, forcing manual reconciliation that degrades care continuity metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Retail Clinics Market |
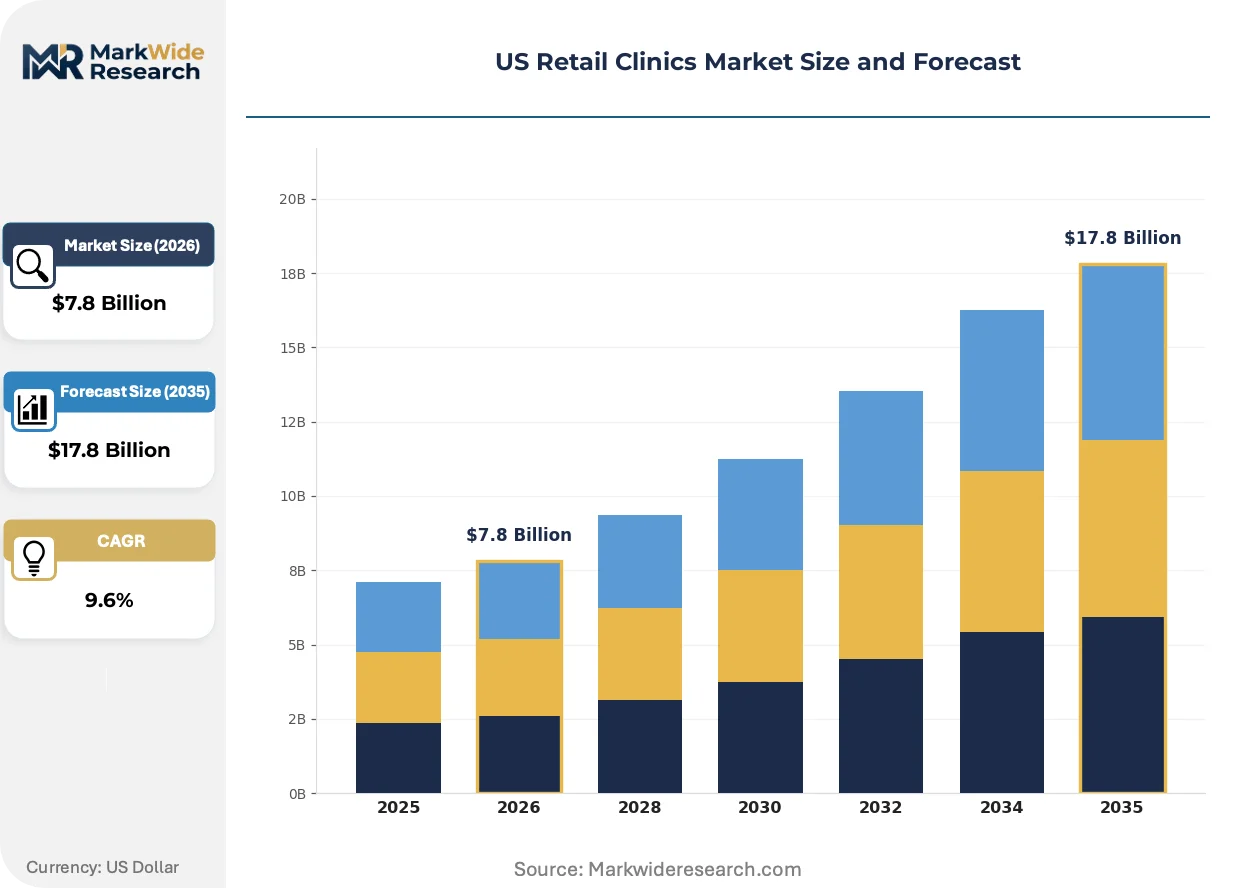
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Clinic Type: Urgent Care, Minute Clinics, Specialty Clinics, Occupational Health Centers, Wellness Centers Service Offering: Immunizations, Physical Exams, Chronic Disease Management, Preventive Screenings, Diagnostic Testing Customer Segment: Working Professionals, Students, Elderly, Families, Insured Individuals Distribution Channel: Pharmacy Chains, Supermarkets, Standalone Clinics, Employer-Sponsored Programs, Telehealth Platforms |
| Companies Covered | Kroger, Bellin Health, CVS Health, Rite Aid, Aurora Health Care, Walgreens, Amazon One Medical, Concentra Inc., Walmart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Retail Clinics Market Emerging Trajectories
Clinical workflow automation and regulatory recalibration are converging to redefine service delivery economics. Operators are racing to embed diagnostic and digital capabilities that justify premium reimbursement rates while compressing labor dependency.
Artificial intelligence triage protocols are automating intake documentation and symptom stratification at kiosk-based check-in stations. Large retail operators are deploying these systems across high-throughput Florida locations to reduce nurse practitioner documentation burden. The technology is automating eligibility verification and prior authorization submission, compressing administrative labor hours per encounter by approximately one-third.
OSHA workplace health standards are mandating audiometric testing and respiratory surveillance for manufacturing employers with 500-plus headcount. These compliance requirements are generating contracted clinic volumes that stabilize utilization during seasonal demand troughs. Construction and logistics employers in Texas are responding by negotiating direct primary care arrangements that bundle occupational and non-occupational services.
Patients are abandoning appointment-based primary care for on-demand access models that align with pharmacy pickup patterns. This behavioral pivot is concentrating volume in evening and weekend windows that traditional physician offices do not serve. California markets exhibit the most pronounced shift, with walk-in traffic spiking 40% above baseline during 6-9 PM weekday slots.
US Retail Clinics Market Segmentation
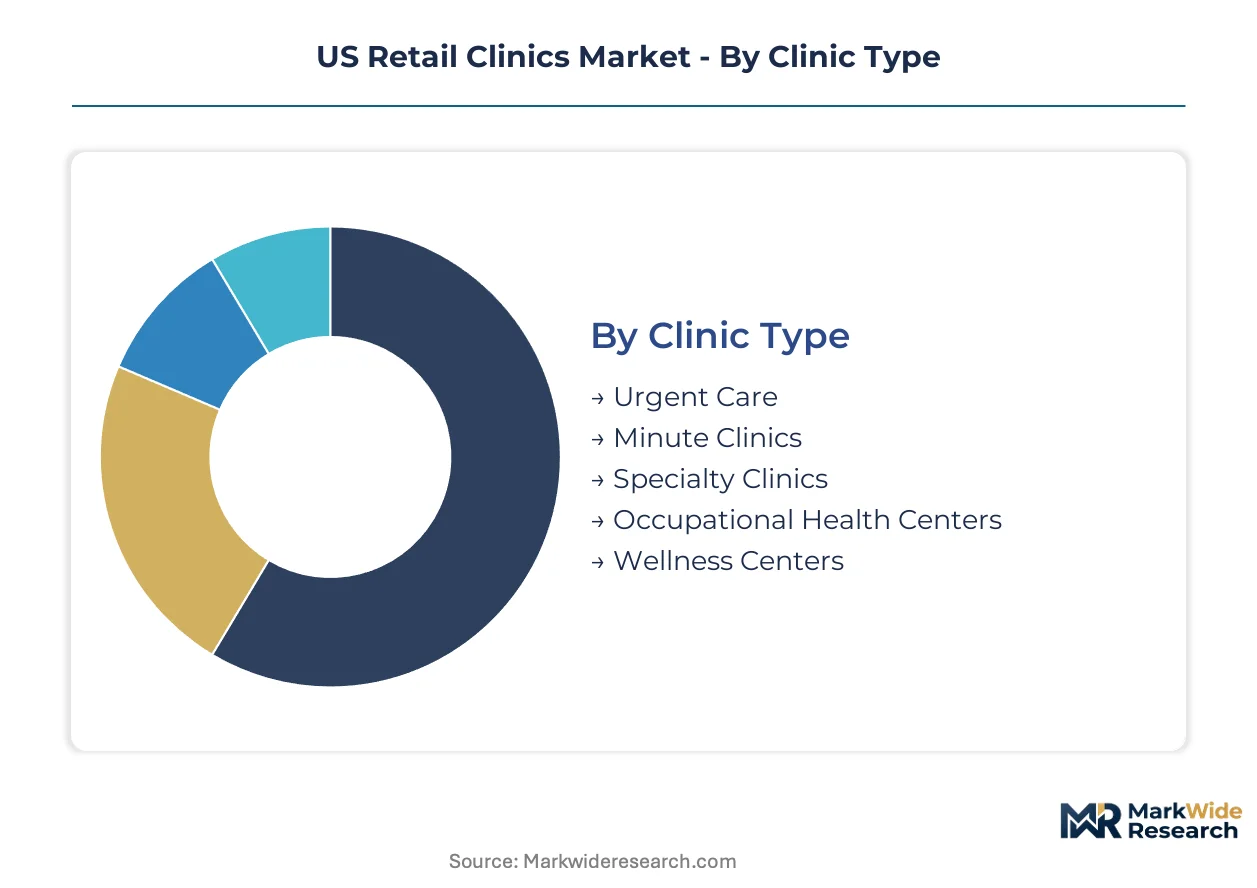
Segmentation in US retail clinics reveals how service configuration, patient demographics, and site economics interact to determine profitability. Each dimension shapes staffing models, payer mix, and regulatory exposure differently across operating environments.
Clinic Type:
Volume concentration and reimbursement structure separate profitable formats from marginal operations in this category.
- Minute Clinics:Nurse practitioner-staffed sites embedded in pharmacy footprints deliver episodic care for URI, strep, and minor injuries with 15-minute visit cycles. Texas and Florida drive volume concentration where pharmacy adjacency enables prescription capture and reduces no-show rates.
- Urgent Care:Physician-supervised facilities equipped for X-ray, suturing, and fracture management operate extended hours beyond traditional primary care. California corridor locations absorb emergency department diversion demand from commercially insured populations seeking cost-contained alternatives.
- Specialty Clinics:Dermatology and behavioral health focused formats leverage retail convenience for condition-specific follow-up protocols.
- Occupational Health Centers:Employer-contracted sites prioritize OSHA compliance workflows and return-to-work examinations over walk-in consumer volume.
- Wellness Centers:Prevention-focused formats emphasizing biometric screening and lifestyle counseling serve self-insured employer populations.
Minute Clinics lead volumes today; Occupational Health Centers are gaining share fastest.
Service Offering:
Margin profile and labor intensity diverge sharply based on whether services require diagnostic equipment, longitudinal tracking, or simple administration.
- Diagnostic Testing:Rapid molecular platforms and CLIA-waived assays generate lab referral economics with 48-hour turnaround compression. Demand clusters in metropolitan Texas where same-day result delivery differentiates retail channels from hospital outpatient labs.
- Chronic Disease Management:Hypertension and diabetes protocols integrate connected devices with pharmacy fulfillment for medication adherence. CMS reimbursement expansion for remote patient monitoring is rebalancing cost structures in California ACO arrangements.
- Immunizations:High-throughput vaccine administration leverages standing orders and minimal clinical oversight for seasonal volume spikes.
- Physical Exams:Pre-employment and school-mandated examinations generate predictable scheduling patterns with limited follow-up obligation.
- Preventive Screenings:Colorectal and cardiovascular risk assessments attract value-based contract participation from Medicare Advantage plans.
Diagnostic Testing commands premium margins; Chronic Disease Management shows steepest expansion trajectory.
Customer Segment:
Insurance status and care-seeking behavior determine visit frequency, price sensitivity, and payer negotiation leverage.
- Working Professionals:Commercially employed adults aged 25-54 demand evening and weekend access windows that align with pharmacy pickup patterns. Florida markets exhibit 40% traffic spikes during 6-9 PM weekday slots as this segment abandons appointment-based primary care.
- Families:Multi-patient households with children generate cross-selling opportunities for pediatric immunizations and acute illness management. California family volumes concentrate in suburban corridors with dual-income household density.
- Students:University-affiliated populations seek low-cost alternatives to campus health centers for confidential services.
- Elderly:Medicare beneficiaries require chronic condition monitoring and medication reconciliation services with higher clinical complexity.
- Insured Individuals:Narrow network participation and deductible exposure drive site selection based on copay transparency rather than proximity alone.
Working Professionals generate highest visit frequency; Families are expanding most quickly as pediatric service lines mature.
Distribution Channel:
Real estate economics and patient acquisition cost vary dramatically based on host environment and referral dependency.
- Pharmacy Chains:CVS and Walgreens embed clinics within existing prescription fulfillment footprints to capture medication revenue and reduce standalone marketing spend. Texas pharmacy-based locations sustain throughput through uninsured walk-in volume attracted by transparent cash pricing.
- Employer-Sponsored Programs:On-site and near-site clinics contract directly with self-insured employers for workforce health services. Construction and logistics employers in Texas negotiate bundled occupational and primary care arrangements.
- Supermarkets:Grocery-anchored sites leverage weekly shopping frequency for routine care access but face space constraints for diagnostic equipment.
- Standalone Clinics:Walmart's rural model sacrifices pharmacy adjacency for parking accessibility and extended service menus in underserved counties.
- Telehealth Platforms:Amazon One Medical integrates digital-first triage with physical touchpoints for hybrid care delivery.
Pharmacy Chains dominate location count; Employer-Sponsored Programs are climbing the fastest as direct contracting accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nurse practitioner workforce density and state-level scope-of-practice autonomy anchor geographic expansion feasibility across the United States.
Texas
Uninsured population concentration in Houston and Dallas-Fort Worth drives walk-in volume at pharmacy-based locations. Full practice authority for nurse practitioners eliminates physician oversight costs and accelerates clinic deployment timelines. The Rio Grande Valley corridor exhibits the steepest Medicaid enrollment growth, redirecting newly covered patients toward retail primary care access points.
California
ACO risk-bearing health systems in Los Angeles and San Francisco Bay Area contract retail clinics as downstream referral nodes for attributed Medicare beneficiaries. State telehealth parity laws mandate reimbursement equivalence with in-person visits, enabling hybrid care models. Central Valley agricultural counties attract Rural Health Clinic certification seekers pursuing cost-based federal reimbursement pathways.
Florida
Restrictive nurse practitioner practice authority forces physician supervision requirements that erode unit economics in Miami and Tampa markets. Evening traffic spikes 40% above baseline during 6-9 PM weekday windows as working professionals abandon appointment-based primary care. CMS conditions of participation for clinic-based services create compliance complexity for operators seeking Medicare Advantage contract participation.
Illinois
Chicago metropolitan employer-sponsored clinic contracts consolidate purchasing power across manufacturing and logistics sectors. OSHA workplace health standards mandate audiometric testing for industrial employers with 500-plus headcount, generating contracted occupational health volumes. Downstate rural counties exhibit pharmacy desert conditions that favor standalone clinic models over embedded formats.
New York
Scope-of-practice reform momentum in Albany legislative sessions threatens incumbent health system control over primary care referral pipelines. New York City boroughs concentrate narrow-network commercial insurance participation that drives site selection based on copay transparency. Hudson Valley and Long Island suburban corridors attract pediatric service line expansion targeting dual-income family demographics.
US Retail Clinics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Pharmacy-anchored operators leverage prescription fulfillment adjacency to capture medication revenue and reduce patient acquisition costs. Three archetypes dominate: retail-embedded clinic networks, standalone rural access providers, and digital-first hybrid platforms. Consolidation through strategic partnerships and geographic expansion into underserved counties represent the dominant competitive vectors reshaping market structure.
Among diversified retail-embedded operators, CVS Health and Walgreens occupy positions exemplifying pharmacy-footprint leverage, while Amazon One Medical anchors the digital-first hybrid archetype. These entities represent contrasting strategic postures—incumbent prescription volume capture versus technology-enabled care delivery integration—without implying specific performance outcomes or strategic timelines.
| Leading Market Players |
|---|
| Kroger |
| Bellin Health |
| CVS Health |
| Rite Aid |
| Aurora Health Care |
| Walgreens |
| Amazon One Medical |
| Concentra Inc. |
| Walmart |
| Others |
Supply Flow & Price Mechanics
Medical device procurement indices and pharmaceutical wholesale benchmarks cascade through retail clinic economics, compressing margin structures when generic substitution accelerates while enabling premium capture for rapid diagnostic platforms that justify higher visit fees through same-day prescribing workflows.
Pricing Analysis
The bundled-vs-unbundled service split separates employer-sponsored occupational health contracts from walk-in episodic care, with subscription-based workforce health arrangements locking in multi-year revenue commitments while per-visit cash pricing attracts uninsured populations in Texas and Florida corridors. Price differentiation hinges on diagnostic capability tier and pharmacy fulfillment integration, with rapid molecular testing platforms commanding visit premiums against basic URI assessments. Cost compression in standard episodic services is intensifying because telehealth substitution erodes low-acuity volume, forcing operators to absorb lease premiums in metropolitan footprints. Self-insured employers exhibit lowest price sensitivity due to bundled OSHA compliance mandates, while uninsured walk-in patients drive aggressive cash-price competition.
Supply Chain Analysis
Dual-sourcing requirements for point-of-care diagnostic devices mandate FDA-cleared platform qualification across multiple manufacturers, preventing single-supplier dependency for CLIA-waived assay cartridges and rapid molecular testing consumables. Geographic supply concentration centers on domestic US manufacturing for regulated medical devices, with secondary sourcing from Ireland and Singapore for specialized diagnostic components. Raw material dependencies include plastic consumables, electronic sensors, and reagent chemicals subject to pharmaceutical-grade purity standards. Tariff exposure on Chinese-sourced electronic components creates margin vulnerability for high-volume testing platforms. Distribution runs through pharmaceutical wholesale networks and direct manufacturer agreements with retail clinic operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Retail Clinics Market functions as a regulatory compounder where CMS reimbursement expansion for chronic care management codes creates structural demand acceleration beyond episodic visit economics.
For Market Incumbents: Deploy scope-of-practice expansion lobbying as the primary lever to unlock nurse practitioner independence in Florida and California, reducing physician oversight costs that currently erode unit economics. Pursue backward integration into rapid diagnostic manufacturing to capture lab referral margins currently flowing to third-party platforms. Consolidate through targeted acquisition of occupational health specialists in Texas logistics corridors to defend against Amazon One Medical's employer-contracting momentum.
For New Entrants and Emerging Players: The premium-economy price-point gap in chronic disease management creates white-space opportunity for mid-tier operators offering connected device integration without full ACO risk-bearing complexity. Target Central Valley agricultural counties in California pursuing Rural Health Clinic certification, where federal cost-based reimbursement pathways offset startup operational losses. Penetrate through direct primary care arrangements with mid-size construction employers seeking bundled occupational and non-occupational services.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional occupational health specialists possessing established OSHA compliance workflows and multi-year employer contracts in manufacturing-dense Illinois and Texas corridors. Long-term viability favors operators with demonstrated credentialing velocity and EHR interoperability capabilities that satisfy ACO care continuity requirements. Watch Texas Medicaid expansion legislative momentum as the signal indicating enrollment pipeline acceleration toward pharmacy-based primary care access points.
| Strategic Initiative | Industry Significance |
|---|---|
| Rural Health Clinic Certification Pursuit | Federal cost-based reimbursement pathways in designated shortage areas unlock sustainable economics for underserved county expansion. |
| ACO Risk-Bearing Partnership Formation | Shared savings participation with California Medicare Advantage plans creates downstream referral node positioning for attributed beneficiaries. |
| Point-of-Care Diagnostic Platform Integration | Same-day prescribing capabilities from rapid molecular testing differentiate retail channels from traditional office-based workflows. |
| Occupational Health Service Line Expansion | OSHA-mandated audiometric testing and respiratory surveillance contracts stabilize utilization during seasonal consumer demand troughs. |
| Telehealth Parity Compliance Investment | California-mandated reimbursement equivalence enables hybrid care models capturing both virtual triage and physical touchpoint revenue. |
Methodological Framework
Bottom-up employer contracting and patient volume modeling reconciled against top-down pharmacy footprint and reimbursement policy tracking forms the analytical core of this study. Primary interviews with nurse practitioner staffing directors, health system ACO executives, self-insured employer benefits managers, and retail clinic operations leaders combined with secondary validation from FDA 510(k) filings, CMS Medicare cost reports, state scope-of-practice legislation databases, and pharmaceutical wholesale distribution records. Triangulation across these sources ensures supply-side capacity estimates align with demand-side utilization patterns.
Historical trendline analysis of visit volume growth, reimbursement rate evolution, and clinic deployment timelines established baseline momentum indicators across the projection horizon. Segmentation modeling incorporated clinic type, service offering complexity, customer insurance status, and distribution channel economics as core dimensions. CAGRs were derived from regression analysis of volume and value trajectories, with specific inputs including Texas Medicaid enrollment projections, California ACO attribution growth, and Florida telehealth substitution rates.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled triage automation would alter the outlook if regulatory clearance timelines accelerate or stall. Forecasts reflect assumptions about nurse practitioner workforce expansion, CMS reimbursement stability, and state-level scope-of-practice reform momentum. Deviation in Texas Medicaid expansion legislative outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Acute Care Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
US Post-Acute Care (PAC) Market