
 Australia and New Zealand Healthcare Logistics Market | 2026-2036
Australia and New Zealand Healthcare Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Healthcare Logistics Market Outlook
The premium biopharmaceutical cold chain is shifting away from standard ambient freight in concrete operational terms. DSV differentiates through its dedicated healthcare vertical with temperature-validated infrastructure across both countries. Toll Holdings Limited anchors its position through deep last-mile penetration into regional hospital networks. EBOS Group Limited leverages its pharmaceutical wholesale heritage to sustain channel control over pharmacy distribution.
Australia and New Zealand Healthcare Logistics encompasses the specialized movement, storage, and inventory management of pharmaceuticals, medical devices, clinical specimens, and temperature-sensitive biologics through validated cold chain and ambient distribution networks. Cold chain infrastructure demands continuous temperature monitoring between two and eight degrees Celsius for vaccines and biologics, with real-time telematics tracking required for regulatory compliance. Transportation and cold chain delivery modes command structural priority due to biopharmaceutical volume growth, while warehouse management systems represent the fastest-expanding technology segment as operators automate compliance documentation. RFID adoption remains concentrated among large hospital networks where batch-level traceability supports patient safety protocols.
TGA enforces Good Distribution Practice requirements that mandate temperature mapping and qualification across all pharmaceutical storage facilities in Australia. Medsafe and the New Zealand Ministry of Health align closely with PIC/S standards, creating a trans-Tasman regulatory baseline that shapes third-party logistics provider certification requirements. Stakeholders must monitor how evolving pharmacovigilance reporting obligations and serialization mandates will reshape inventory management system specifications across both jurisdictions.
Market Dynamics
TGA and Medsafe GDP convergence is compressing third-party logistics certification timelines while biopharmaceutical cold chain volume concentrates procurement power among metropolitan hospital networks in Victoria and New South Wales.
Growth Catalysts
- TGA Good Distribution Practice mandates:Temperature mapping requirements across Australian pharmaceutical storage facilities are accelerating validated infrastructure investment.
- Biologics pipeline expansion:mRNA and cell therapy manufacturing growth in Melbourne and Sydney is generating specialized last-mile distribution demand.
- Medsafe PIC/S alignment:New Zealand's regulatory harmonization with Australian standards is enabling trans-Tasman logistics network consolidation.
Market Restraints
- Refrigerant input volatility:Synthetic refrigerant cost fluctuations and phase-down schedules under the Montreal Protocol are compressing cold chain operating margins.
- Specialized fleet concentration:Temperature-validated vehicle availability remains concentrated among three national operators, limiting price competition for regional routes.
- Regional infrastructure gaps:Northern Queensland and South Island New Zealand lack redundant cold storage capacity, creating single-point-of-failure risk for biopharmaceutical distribution.
Strategic Opportunities
- Tasmanian bioprocessing cluster:Emerging cell therapy manufacturing in Hobart is creating demand for specialized clinical trial logistics services with direct airfreight connectivity.
- RFID-telematics convergence:Real-time temperature and location tracking integration is opening subscription-based compliance-as-a-service revenue models for mid-sized hospital networks.
- Home infusion therapy expansion:Direct-to-patient cold chain delivery for biologics is penetrating suburban Melbourne and Auckland metropolitan corridors.
Industry Challenges
- Qualified personnel scarcity:GDP-certified warehouse supervisors and cold chain validation engineers command premium wages in Sydney and Melbourne labor markets.
- Legacy WMS integration:Hospital procurement systems require custom API development to connect with third-party logistics visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Healthcare Logistics Market |
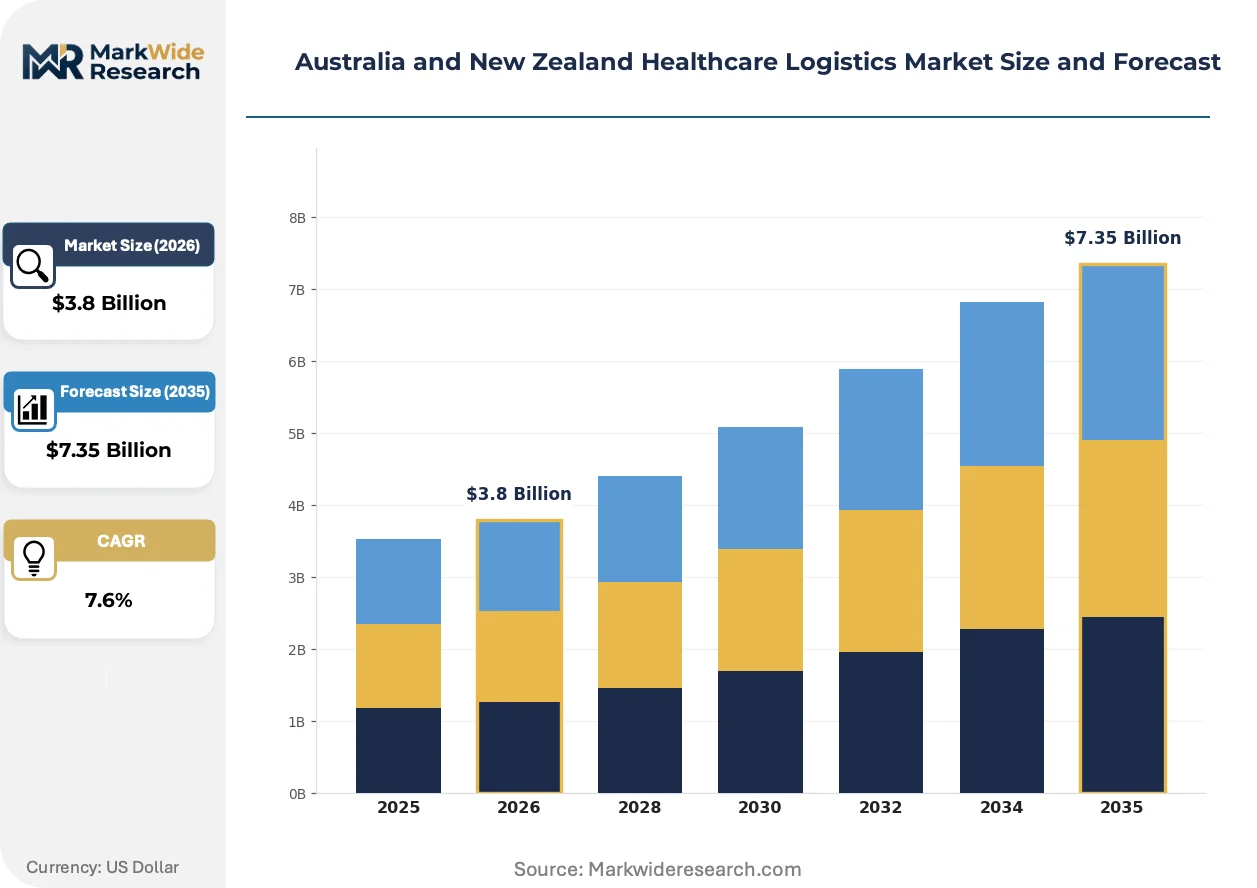
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Inventory Management, Distribution Technology: Telematics, Warehouse Management Systems, Blockchain, RFID End User: Pharmacies, Hospitals, Clinics, Laboratories Delivery Mode: Cold Chain, Land Transport, Air Freight, Sea Freight |
| Companies Covered | ACFS Port Logistics Pty Ltd, DSV, EBOS Group Limited, FedEx, CEVA Logistics, Toll Holdings Limited, Kuehne+Nagel, DB Schenker, Linfox Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Healthcare Logistics Market Strategic Shifts
Telematics-enabled temperature monitoring is displacing manual logging across Australian and New Zealand pharmaceutical distribution, while regulatory serialization mandates reshape inventory system specifications.
IoT sensor networks with cellular connectivity are expanding into ambient and cold chain freight lanes between Melbourne, Sydney, and Auckland. Regional hospital networks in Queensland and Western Australia are adopting these platforms fastest due to distance from validation laboratories. Real-time alert systems are expanding into quality assurance workflows, compressing deviation response times from hours to minutes.
TGA's impending serialization requirements for high-risk medicines are forcing warehouse management system upgrades across Australian pharmaceutical wholesalers. The industrial consequence is accelerated cloud-based WMS replacement of on-premise legacy installations. Hospital pharmacy networks in New South Wales are most affected, with procurement teams demanding vendor pre-certification against forthcoming data exchange standards.
Consolidated buying by metropolitan health districts is compressing logistics contract durations and unbundling transportation from warehousing services. Pharmaceutical distributors in Victoria and Queensland are responding with modular service offerings. This pattern is most visible across the four major Sydney hospital networks, where separate RFPs for cold chain transport and ambient storage have replaced bundled agreements.
Australia and New Zealand Healthcare Logistics Market Segmentation
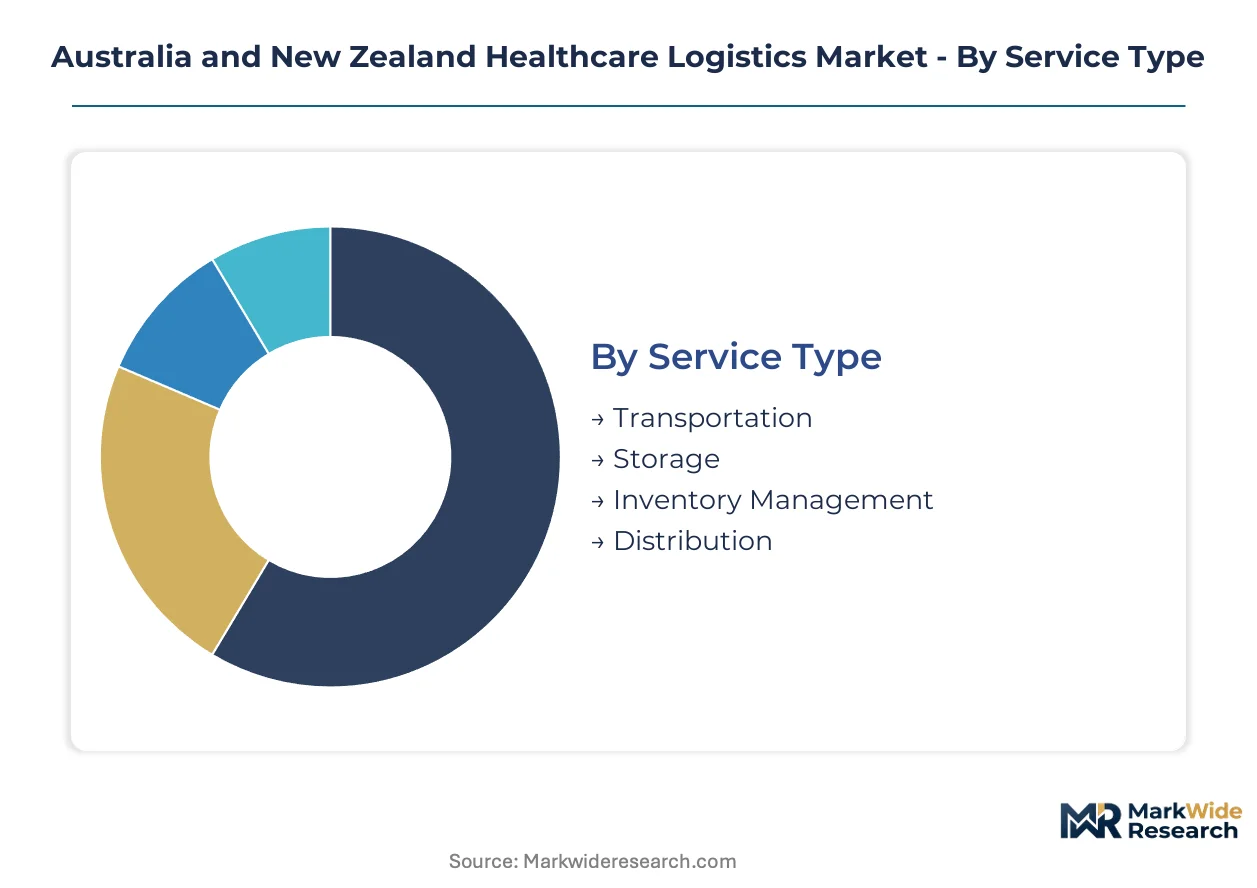
Healthcare logistics segmentation in Australia and New Zealand reflects the bifurcation between GDP-regulated pharmaceutical flows and non-regulated medical device distribution. TGA and Medsafe compliance requirements create divergent operational specifications across service categories, with cold chain infrastructure commanding distinct certification tiers.
Service Type:
TGA Good Distribution Practice mandates impose tiered validation burdens across service categories, with temperature-controlled transportation requiring continuous qualification documentation.
- Transportation:Temperature-validated vehicle fleets with real-time telematics monitoring satisfy TGA GDP requirements for pharmaceutical distribution between Melbourne, Sydney, and Auckland. Metropolitan hospital networks in Victoria and New South Wales concentrate procurement for dedicated healthcare lanes.
- Storage:Warehouse facilities require temperature mapping studies and equipment qualification under PIC/S standards, with cold storage capacity concentrated among three national operators. Regional gaps in Northern Queensland and South Island New Zealand create single-point-of-failure exposure for biopharmaceutical inventory.
- Inventory Management:Cloud-based WMS platforms with serialization readiness address TGA's impending high-risk medicine tracking mandates.
- Distribution:Last-mile networks into regional hospital systems leverage Toll Holdings' infrastructure density across both countries.
Transportation sits at the top of the volume ranking, with Inventory Management climbing the fastest.
Technology:
Technology adoption stratifies by customer scale, with RFID and telematics penetration concentrated among large hospital networks while mid-tier operators lag in sensor deployment.
- Telematics:Cellular-connected temperature sensors with real-time alert capabilities compress deviation response times from hours to minutes across trans-Tasman freight lanes. Queensland and Western Australia regional networks adopt these platforms fastest due to distance from validation laboratories.
- Warehouse Management Systems:Cloud-based replacements of on-premise legacy installations accelerate as New South Wales hospital pharmacy networks demand vendor pre-certification against forthcoming data exchange standards.
- Blockchain:Pilot implementations target serialization compliance for high-risk medicine traceability.
- RFID:Batch-level traceability supports patient safety protocols in metropolitan hospital networks.
Warehouse Management Systems capture the largest technology spend, with Telematics expanding most quickly.
End User:
End-user segments diverge in cold chain intensity, with biologics-heavy hospital procurement demanding validated infrastructure that pharmacy and clinic distribution can bypass.
- Hospitals:Metropolitan health districts in Sydney and Melbourne unbundle transportation from warehousing contracts, driving modular service offerings from pharmaceutical distributors. Cell therapy manufacturing in Melbourne and Sydney generates specialized last-mile distribution demand.
- Pharmacies:EBOS Group's wholesale heritage sustains channel control over ambient distribution networks across both countries.
- Clinics:Home infusion therapy penetration in suburban Melbourne and Auckland corridors creates direct-to-patient cold chain requirements.
- Laboratories:Clinical specimen logistics demand continuous two-to-eight-degree Celsius monitoring with real-time telematics tracking.
Hospitals command the highest logistics spend per site, with Clinics gaining share fastest on home therapy expansion.
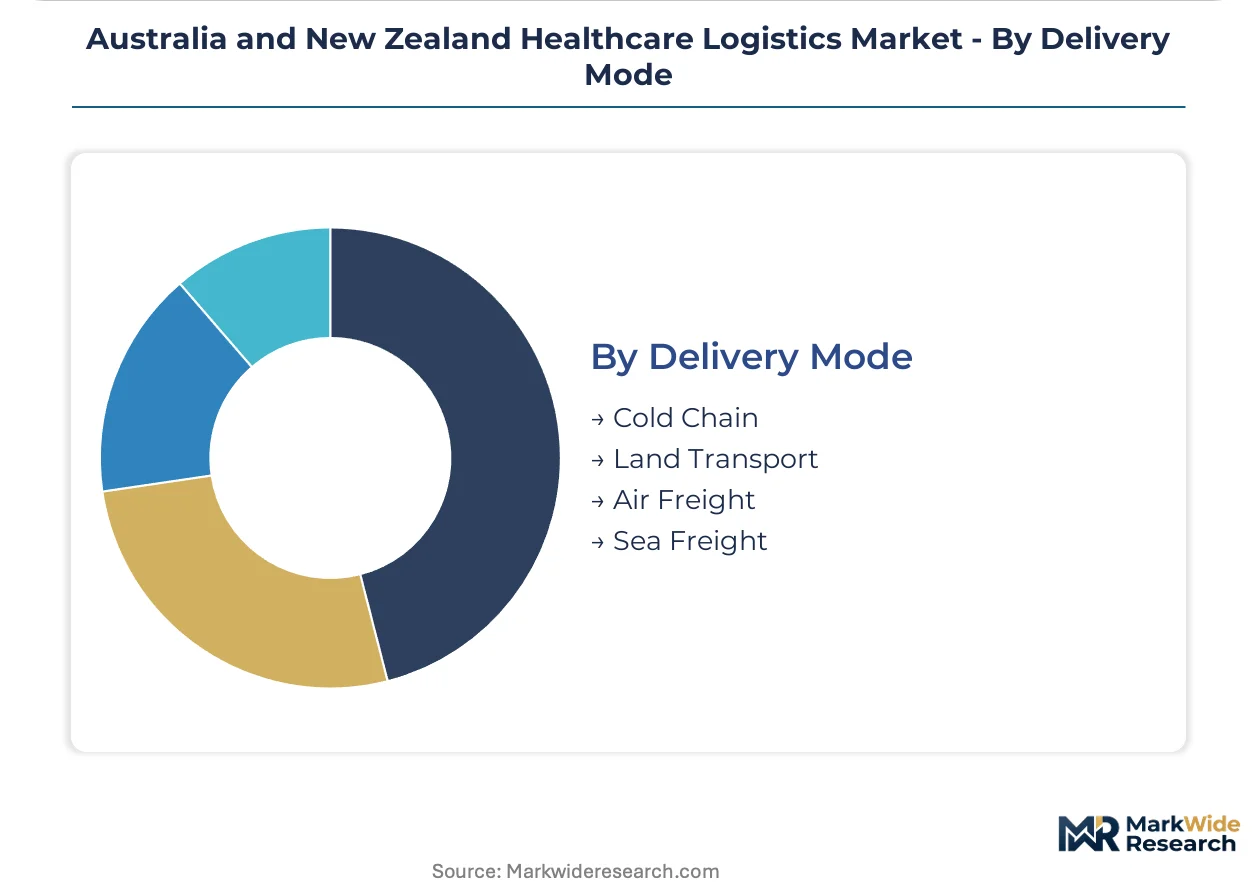
Delivery Mode:
Delivery mode selection hinges on product temperature sensitivity and transit distance, with cold chain infrastructure availability constraining route options.
- Cold Chain:Validated two-to-eight-degree Celsius distribution anchors biopharmaceutical volume growth, with synthetic refrigerant cost volatility compressing operating margins under Montreal Protocol phase-down schedules. DSV's dedicated healthcare vertical differentiates through temperature-validated infrastructure.
- Land Transport:Temperature-validated vehicle availability concentrates among three national operators, limiting price competition for regional routes into Northern Queensland and South Island New Zealand.
- Air Freight:Direct connectivity supports Tasmanian bioprocessing cluster logistics for clinical trial materials.
- Sea Freight:Ambient containerized movement serves non-temperature-sensitive medical devices with longer lead time tolerance.
Cold Chain dominates value contribution, with Air Freight climbing fastest on cell therapy manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDP-certified warehouse supervisors and cold chain validation engineers concentrate in Sydney and Melbourne labor markets, commanding premium wages that reshape regional network economics. This talent geography steers infrastructure investment toward southeastern corridors while creating operational constraints elsewhere.
New South Wales
Metropolitan Sydney hospital networks unbundle transportation from warehousing contracts, driving modular service offerings from pharmaceutical distributors. TGA serialization mandates for high-risk medicines force warehouse management system upgrades across NSW pharmaceutical wholesalers. The Sydney health district cluster generates concentrated procurement power for validated cold chain infrastructure.
Victoria
Cell therapy manufacturing growth in Melbourne creates specialized last-mile distribution demand for clinical trial materials and biologics. TGA Good Distribution Practice temperature mapping requirements accelerate validated infrastructure investment across Melbourne storage facilities. The Melbourne bioprocessing corridor anchors trans-Tasman pharmaceutical freight volumes.
Queensland
Regional hospital networks in Queensland adopt IoT telematics platforms fastest due to distance from validation laboratories. Northern Queensland lacks redundant cold storage capacity, creating single-point-of-failure risk for biopharmaceutical distribution. Brisbane anchors ambient pharmaceutical distribution while cold chain gaps persist in northern corridors.
Western Australia
Distance from southeastern validation laboratories drives rapid telematics adoption across WA regional hospital networks. Synthetic refrigerant cost volatility under Montreal Protocol phase-down schedules compresses cold chain operating margins in Perth-based operations. The Perth metropolitan corridor concentrates limited healthcare logistics infrastructure for the vast state geography.
New Zealand
Medsafe PIC/S alignment with Australian standards enables trans-Tasman logistics network consolidation for pharmaceutical flows. South Island lacks redundant cold storage capacity, creating distribution vulnerability for biopharmaceutical inventory. Auckland metropolitan corridors penetrate with direct-to-patient cold chain delivery for home infusion therapy expansion.
Australia and New Zealand Healthcare Logistics Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light coordination specialists for contract control across trans-Tasman pharmaceutical flows. Three national operators concentrate temperature-validated vehicle availability, limiting price competition for regional routes. Strategic archetypes separate into dedicated healthcare verticals, pharmaceutical wholesale heritage players, and global freight forwarders with healthcare certifications. Competitive moves center on modular service unbundling and cloud-based visibility platform integration.
Within the dedicated healthcare vertical tier, DSV exemplifies temperature-validated infrastructure investment across both countries. Toll Holdings Limited occupies a position anchored in last-mile penetration density. EBOS Group Limited represents pharmaceutical wholesale heritage sustaining channel control. These three entities sit within distinct competitive positions shaped by their operational origins and infrastructure commitments.
| Leading Market Players |
|---|
| ACFS Port Logistics Pty Ltd |
| DSV |
| EBOS Group Limited |
| FedEx |
| CEVA Logistics |
| Toll Holdings Limited |
| Kuehne+Nagel |
| DB Schenker |
| Linfox Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive cold chain infrastructure investment across Melbourne and Sydney anchors both supply security and pricing power for biopharmaceutical distribution. Three national operators concentrate temperature-validated fleet capacity, compressing competitive tension on regional routes while metropolitan hospital networks extract unbundled service pricing through consolidated procurement.
Pricing Analysis
The bundled-to-unbundled service split defines pricing architecture across Australian and New Zealand healthcare logistics. Metropolitan health districts in Sydney and Melbourne now tender transportation and warehousing separately, forcing modular pricing from pharmaceutical distributors. Price differentiation rests on GDP certification tier and geographic delivery density, with regional Queensland routes commanding premiums due to fleet scarcity. Cost compression in ambient storage is intensifying because cloud-based WMS commoditization erodes software margins. Pharmacy networks exhibit highest price sensitivity, while cell therapy manufacturers accept premium pricing for validated clinical trial logistics.
Supply Chain Analysis
GDP-certified warehouse supervisors and cold chain validation engineers concentrate in Sydney and Melbourne labor markets, steering infrastructure investment toward southeastern Australia. Supply draws from specialized refrigerant manufacturing in China and Japan, pharmaceutical packaging from Germany, and telematics hardware from Taiwan and South Korea. Single-source vulnerability runs through synthetic refrigerant supply chains facing Montreal Protocol phase-down restrictions. Distribution feeds from hub-and-spoke networks anchored in Melbourne and Sydney, with regional spokes into Queensland and Western Australia dependent on limited validated fleet availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia and New Zealand healthcare logistics functions as a stable compounder, with biopharmaceutical cold chain volume growth generating predictable infrastructure utilization. TGA and Medsafe regulatory convergence locks in compliance spending that sustains incumbent positions.
For Market Incumbents: Deepen temperature-validated infrastructure density across regional corridors before synthetic refrigerant phase-downs accelerate fleet replacement cycles. Consolidate procurement relationships with Melbourne and Sydney cell therapy manufacturers through dedicated clinical trial logistics offerings. Defend against modular unbundling by embedding cloud-based visibility platforms directly into hospital pharmacy workflows, raising switching costs for metropolitan health districts.
For New Entrants and Emerging Players: The mid-market pricing gap between DSV's premium healthcare vertical and standard freight forwarders creates entry space for GDP-certified regional specialists. Target Northern Queensland and South Island New Zealand where redundant cold storage absence generates single-point-of-failure risk that buyers will pay to eliminate. Penetrate through compliance-as-a-service subscriptions bundling telematics monitoring with deviation response protocols.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap cold chain specialists because TGA certification timelines and specialized workforce scarcity create durable moats against rapid competitive entry. Focus acquisition screening on operators with existing PIC/S qualification and established relationships with Victorian or New South Wales hospital networks. Monitor Tasmanian bioprocessing cluster development as inflection signal for specialized clinical trial logistics demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | TGA temperature mapping mandates force warehouse infrastructure upgrades across Australian pharmaceutical storage facilities. |
| Telematics Platform Integration | Real-time cellular sensor networks compress deviation response times for Queensland and Western Australia regional networks. |
| Modular Service Unbundling | Separate RFPs for cold chain transport and ambient storage reshape contract structures across Sydney hospital networks. |
| Regional Fleet Expansion | Temperature-validated vehicle additions into Northern Queensland address single-point-of-failure exposure for biopharmaceutical distribution. |
| Cloud WMS Replacement | Serialization readiness requirements accelerate displacement of on-premise legacy installations across New South Wales wholesalers. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down cold chain capacity tracking forms the analytical core of this study. Primary interviews with logistics operations directors, TGA compliance officers, hospital pharmacy procurement managers, and cold chain validation engineers combined with secondary validation against TGA GDP guidance documents, Medsafe PIC/S implementation notices, customs pharmaceutical trade data, and hospital network contract disclosure registers. Triangulation between demand-side procurement patterns and supply-side infrastructure deployment ensures coverage of both service unbundling trends and fleet concentration dynamics.
Input-output matrices map biopharmaceutical volume flows across service type, delivery mode, technology tier, and end-user segment throughout the forecast period. Modeled dimensions include transportation versus storage versus inventory management services, cold chain versus ambient delivery modes, telematics versus WMS versus RFID technology tiers, and hospital versus pharmacy versus clinic end-user channels. CAGRs derive from regression analysis linking pharmaceutical manufacturing growth, regulatory compliance cost trajectories, and infrastructure investment cycles. Industry-specific forecast inputs incorporate mRNA manufacturing capacity expansion in Melbourne and Sydney and Montreal Protocol refrigerant phase-down schedules.
Caveats apply where TGA serialization mandate timing or synthetic refrigerant supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding continued regulatory harmonization between Australian and New Zealand standards, stable biopharmaceutical pipeline growth, and workforce availability for GDP-certified roles. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Medical Spa Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market