
 Europe Medical Affairs Outsourcing Market | 2026-2036
Europe Medical Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Affairs Outsourcing Market Intelligence
Mid-sized biotechnology firms are reorganizing their medical affairs spend toward outsourced models as internal team scaling lags pipeline acceleration. IQVIA leverages its integrated data-execution footprint to anchor large-account relationships across Northern Europe. Ashfield Healthcare competes through therapy-area specialization in oncology and rare disease medical communications. Syneos Health extends its presence via embedded field medical teams that operate inside client governance frameworks.
Europe Medical Affairs Outsourcing denotes the transfer of scientific stakeholder engagement, medical information services, pharmacovigilance support, and regulatory medical writing from pharmaceutical and device developers to third-party specialist organizations, typically governed by service-level agreements specifying response-time thresholds, compliance audit cadence, and scientific quality benchmarks. Medical Information and Pharmacovigilance together occupy the largest share of contract value, reflecting mandatory adverse-event reporting obligations and the 24/7 operational infrastructure required to satisfy EMA and national competent authority timelines. Cloud-Based Solutions within the technology segment represent the fastest-expanding allocation, as distributed medical science liaison teams require real-time CRM-integrated evidence platforms.
EMA's Medical Device Regulation implementation and the EU AI Act's risk-classification framework for algorithmic pharmacovigilance tools are reshaping vendor qualification criteria and data governance standards for outsourced medical affairs delivery. France's ANSM and Germany's BfArM enforce national-layer compliance that adds jurisdictional complexity to cross-border service contracts. Stakeholders must evaluate whether their outsourcing partners maintain parallel regulatory intelligence capabilities for each member state where products hold active marketing authorization.
Market Dynamics
Biotechnology pipeline acceleration outpaces internal medical affairs scaling, forcing mid-sized developers to externalize scientific engagement capabilities while EMA's Medical Device Regulation tightens vendor qualification thresholds.
Growth Catalysts
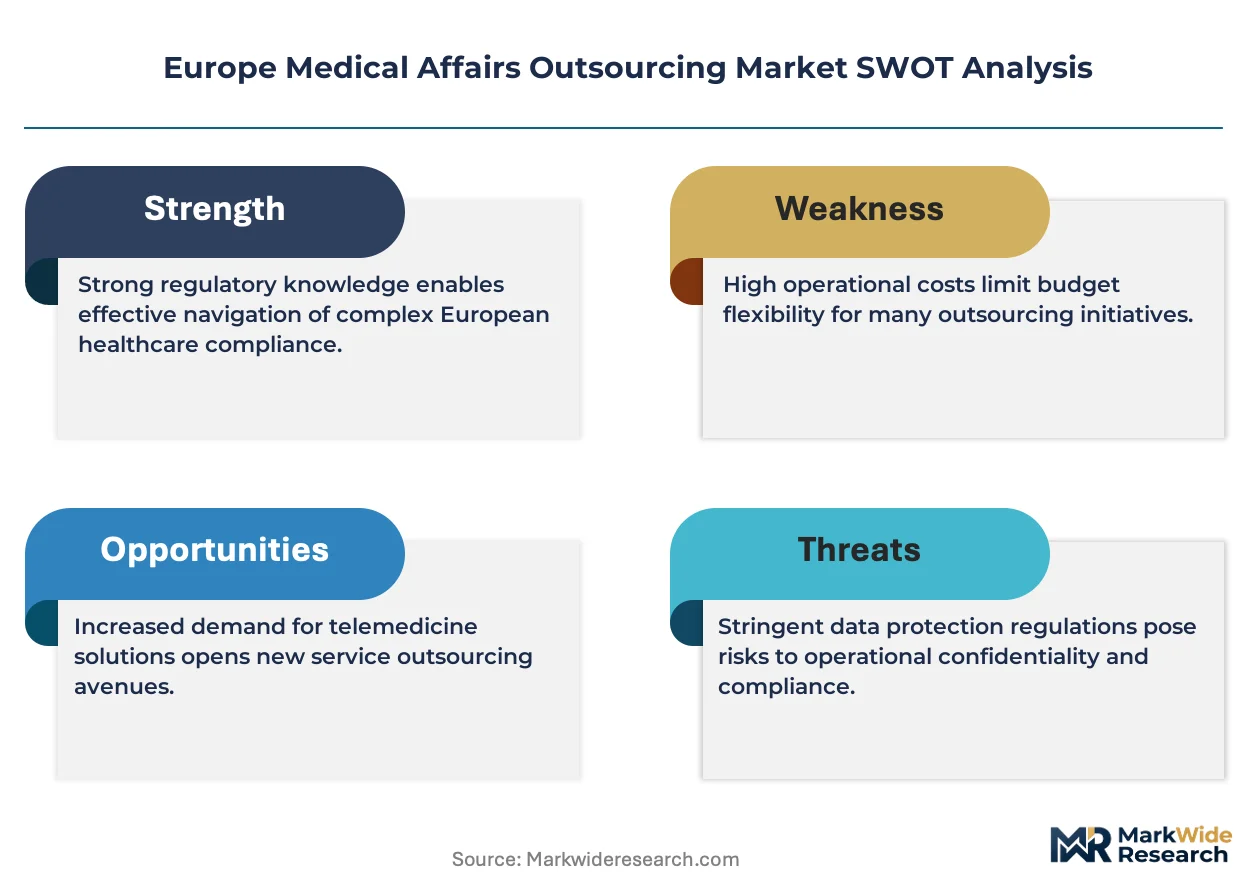
- EU MDR Implementation:The EU Medical Device Regulation mandates enhanced post-market surveillance and clinical evidence requirements, compelling device manufacturers to outsource medical information and vigilance operations to specialists with established 24/7 infrastructure.
- Real-World Evidence Integration:EMA's evolving guidance on real-world data utilization for regulatory submissions drives demand for external medical science liaison networks capable of generating publication-grade evidence from healthcare databases.
- German Pharmaceutical Clustering:Dense concentration of biopharma headquarters and clinical trial sites around Frankfurt, Munich, and Berlin creates localized demand spikes for embedded field medical teams operating under client governance frameworks.
Market Restraints
- Cross-Border Compliance Friction:France's ANSM and Germany's BfArM enforce divergent national-layer requirements atop EMA harmonization, adding jurisdictional complexity and contract fragmentation for pan-European service delivery.
- Specialized Talent Scarcity:Shortage of medical affairs professionals with dual competencies in scientific communication and regulatory intelligence constrains vendor capacity expansion and inflates personnel costs.
- Data Sovereignty Requirements:GDPR's restrictions on cross-border patient data transfer limit cloud-based pharmacovigilance platform architectures and force redundant infrastructure investments per member state.
Strategic Opportunities
- AI-Act Algorithmic Vigilance:The EU AI Act's risk-classification framework for automated pharmacovigilance tools creates first-mover advantage for vendors developing compliant machine-learning adverse-event detection systems.
- Eastern European Expansion:Underpenetrated markets in Poland, Czech Republic, and Hungary offer growth vectors as multinational sponsors seek cost-efficient medical information hubs with multilingual capabilities.
- Oncology Specialization:Cell and gene therapy pipelines require therapy-area-specific medical science liaisons with immuno-oncology expertise, opening premium service tiers for qualified providers.
Industry Challenges
- Legacy System Integration:Client CRM and safety databases often operate on incompatible architectures, forcing costly middleware development and delaying field team deployment timelines.
- Certification Timeline Compression:EMA's accelerated assessment pathways for breakthrough therapies compress medical affairs readiness windows, requiring vendors to staff scientific teams before formal marketing authorization.
- Scientific Quality Auditing:Maintaining consistent response accuracy across distributed medical information centers demands continuous competency validation that strains operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Affairs Outsourcing Market |
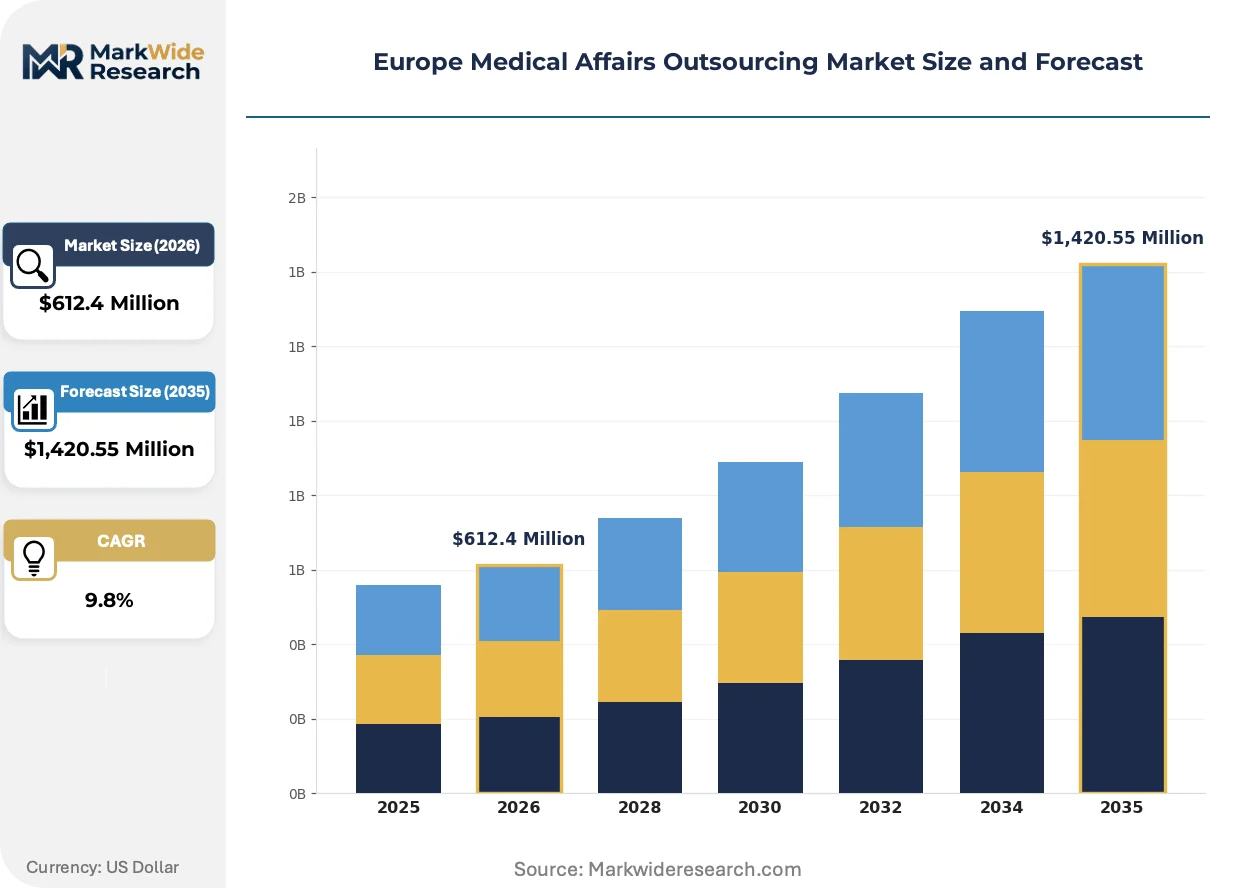
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,420.55 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Regulatory Affairs, Medical Writing, Pharmacovigilance, Medical Information End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Medical Device Manufacturers Engagement Type: Full-Service Outsourcing, Functional Outsourcing, Strategic Partnerships, Consulting Services Technology: Cloud-Based Solutions, Analytics Tools, AI Platforms, Collaboration Software |
| Companies Covered | THE MEDICAL AFFAIRS COMPANY, Ashfield Healthcare, ZEINCRO Group, Indegene, ICON plc, IQVIA, Syneos Health, PPD Inc, Parexel International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Affairs Outsourcing Market Strategic Shifts & Innovations
Cloud-native evidence platforms are reconfiguring how distributed medical science liaison teams access and deploy scientific content, while regulatory automation tools reshape compliance workflows across the outsourcing value chain.
Integrated CRM-evidence platforms is supplanting fragmented document management systems as the infrastructure backbone for field medical operations. Mid-sized biotechnology sponsors are adopting these unified systems within 12-18 month procurement cycles. This convergence is compressing vendor switching costs and anchoring long-term platform relationships through data migration friction.
EMA's Medical Device Regulation recasts post-market clinical follow-up obligations, requiring device sponsors to maintain active safety surveillance that many lack internal capacity to execute. Outsourced medical affairs providers with established vigilance infrastructure capture incremental contract value from this compliance expansion. Cardiovascular and orthopedic device categories show highest externalization rates as legacy manufacturers adapt to strengthened evidence requirements.
Biotechnology procurement teams are consolidating vendor relationships around integrated data-execution partners rather than fragmenting contracts across specialized point-solution providers. This concentration favors vendors offering combined medical information, pharmacovigilance, and medical writing capabilities under unified service-level agreements. German and Swiss sponsors demonstrate earliest consolidation behavior, driven by procurement efficiency mandates from parent-company headquarters.
Europe Medical Affairs Outsourcing Market Segmentation
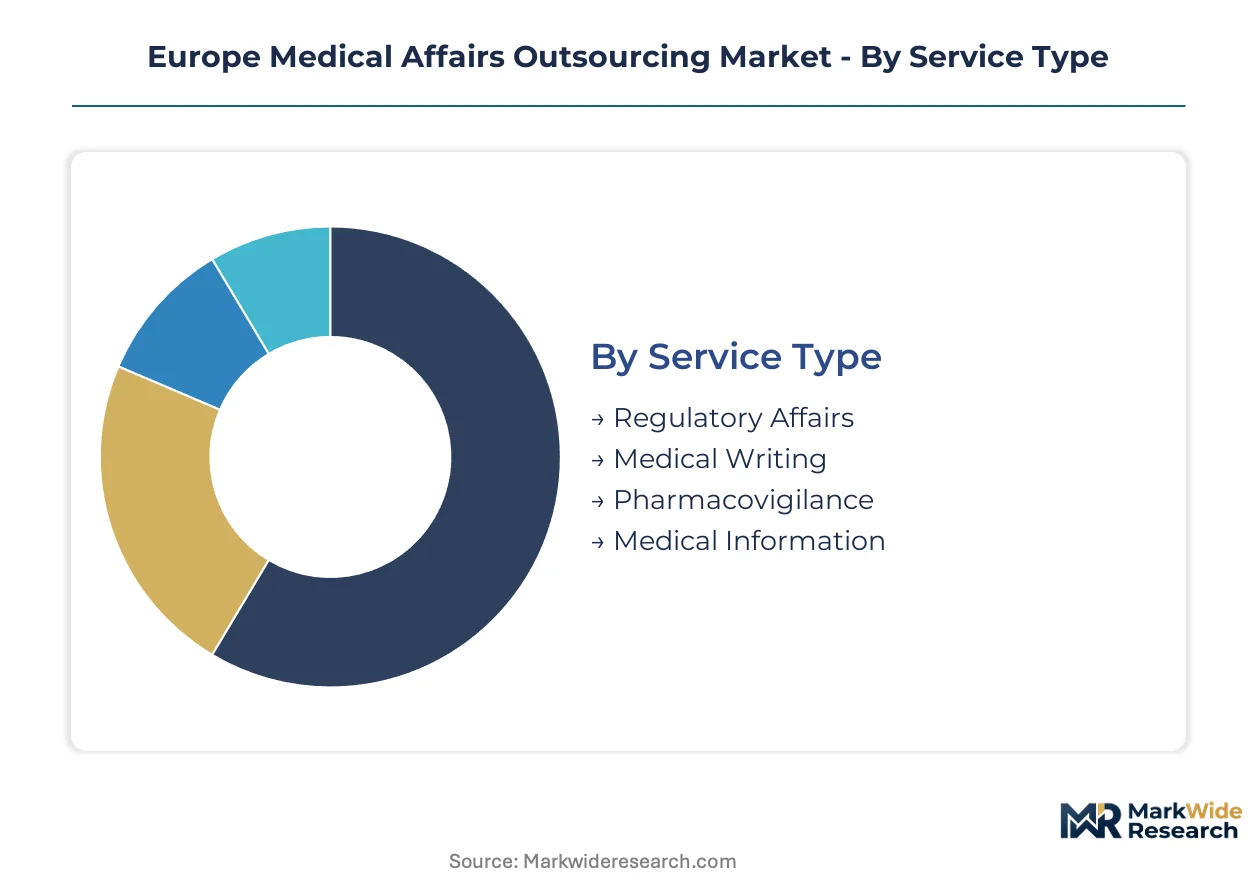
Medical affairs outsourcing contracts fragment across service modalities, end-user sophistication, and technology infrastructure, with margin concentration shifting toward integrated pharmacovigilance and cloud-enabled field medical deployments. Biotechnology procurement teams now prioritize unified service-level agreements over point-solution fragmentation, reshaping how vendors structure pricing and capability bundles.
Service Type:
Pharmacovigilance and medical information capture the deepest margin pools, driven by mandatory adverse-event reporting infrastructure and 24/7 operational requirements that lock sponsors into long-term contracts.
- Pharmacovigilance:Encompasses case processing, signal detection, and periodic safety update report preparation for EMA and national competent authorities. Demand concentrates among German and Swiss biotechnology firms scaling pipeline portfolios without internal safety infrastructure, constrained by BfArM's strict inspection timelines and shortage of qualified safety physicians.
- Medical Information:Provides scientific response services to healthcare professionals and patients through call centers and digital channels. German pharmaceutical clustering around Frankfurt and Munich generates localized demand spikes for multilingual medical information officers capable of handling complex oncology inquiries under compressed response-time thresholds.
- Medical Writing:Delivers regulatory submission documents, clinical study reports, and publication manuscripts. French and Italian sponsors leverage external medical writers to navigate divergent national-layer requirements atop EMA harmonization.
- Regulatory Affairs:Covers marketing authorization applications, variation management, and compliance auditing. Medical device manufacturers externalize regulatory medical writing to specialists with EU MDR transition expertise.
The dominant share belongs to Pharmacovigilance, while Medical Information is closing the gap fastest as real-world evidence integration demands expand field medical infrastructure.
End User:
Cost tier stratification separates large pharmaceutical sponsors with captive capabilities from resource-constrained mid-market players driving externalization.
- Biotechnology Firms:Mid-sized developers with accelerated pipelines but immature medical affairs infrastructure represent the fastest-expanding contract source. These sponsors prioritize functional outsourcing models that preserve strategic control while accessing specialist scientific engagement capabilities.
- Pharmaceutical Companies:Large sponsors consolidate vendor relationships around integrated data-execution partners, reducing point-solution fragmentation through unified procurement mandates from headquarters in Germany and Switzerland.
- Medical Device Manufacturers:Legacy cardiovascular and orthopedic device makers externalize post-market clinical follow-up obligations under EU MDR's strengthened evidence requirements.
- Contract Research Organizations:CROs themselves subcontract specialized medical affairs capabilities to extend service portfolios without building captive scientific teams.
Biotechnology Firms command the steepest expansion trajectory, though Pharmaceutical Companies retain the largest absolute contract value.
Engagement Type:
Volume concentration favors full-service arrangements as procurement efficiency mandates override best-of-breed fragmentation.
- Full-Service Outsourcing:Transfers complete medical affairs functions to vendor governance frameworks. German sponsors adopt this model most aggressively, embedding field medical teams inside client organizations with dedicated scientific leadership.
- Functional Outsourcing:Targets specific capabilities like pharmacovigilance case processing or medical information response services. French biotechnology firms prefer this selective approach to retain strategic scientific engagement internally.
- Strategic Partnerships:Multi-year alliances with shared risk-reward structures for pipeline-specific medical affairs support. Rare disease sponsors in the Netherlands and Belgium negotiate these arrangements to secure dedicated therapy-area expertise.
- Consulting Services:Project-based advisory for regulatory strategy, launch readiness, or organizational design. Medical device manufacturers leverage consulting engagements during EU MDR transition periods.
Full-Service Outsourcing holds the largest share, with Strategic Partnerships gaining ground fastest among cell and gene therapy developers.
Technology:
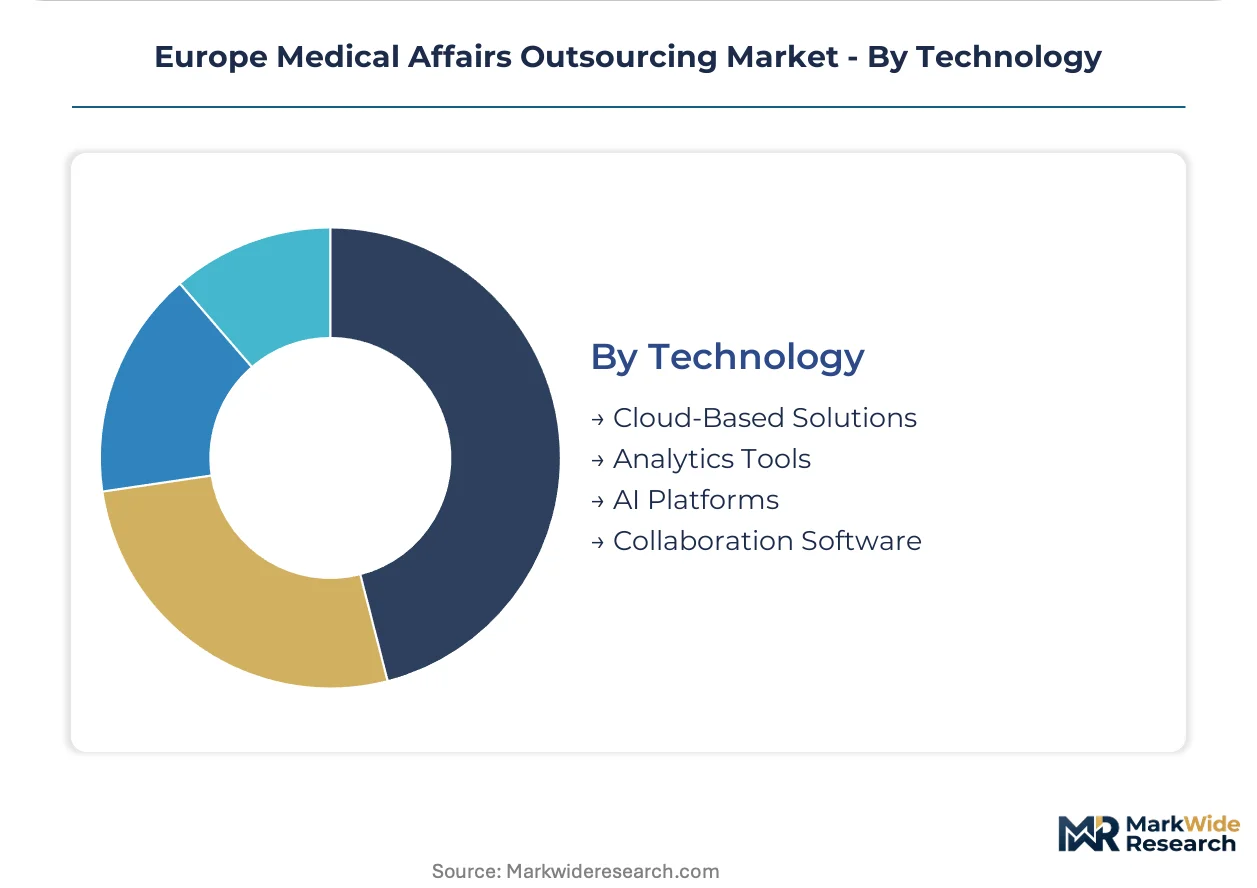
Application maturity separates established collaboration platforms from emerging AI deployments still navigating EU AI Act risk classification.
- Cloud-Based Solutions:CRM-integrated evidence platforms enable distributed medical science liaison teams to access real-time scientific content across European territories. GDPR's cross-border data transfer restrictions force redundant infrastructure investments per member state, inflating deployment costs.
- AI Platforms:Algorithmic tools for adverse-event detection and medical literature monitoring face evolving vendor qualification criteria under EMA guidance and EU AI Act implementation. First-mover vendors with compliant machine-learning systems capture premium positioning.
- Analytics Tools:Real-world evidence platforms aggregate healthcare database outputs for regulatory submission support. EMA's evolving guidance on real-world data utilization drives demand for external analytics capabilities.
- Collaboration Software:Document management and virtual engagement platforms support remote scientific stakeholder interactions. These tools face replacement pressure from integrated cloud-native alternatives.
Cloud-Based Solutions dominate current allocation, while AI Platforms are expanding most quickly as regulatory frameworks crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main logistics corridor anchors Germany's dominance in European medical affairs outsourcing, with high-speed rail links and proximity to EMA headquarters enabling rapid regulatory response cycles across the continent.
Germany
Dense pharmaceutical clustering around Frankfurt, Munich, and Berlin generates concentrated demand for embedded field medical teams and pharmacovigilance infrastructure. BfArM enforces strict inspection timelines that favor established vendors with German operational presence. The Rhine-Main metropolitan region hosts the highest concentration of biotechnology headquarters outsourcing scientific engagement capabilities.
France
Paris-based pharmaceutical sponsors drive demand for regulatory medical writing and medical information services through ANSM's divergent national-layer requirements. The Île-de-France region concentrates contract value for French-language scientific communication and compliance auditing. Lyon and Strasbourg emerge as secondary hubs for device manufacturers navigating EU MDR transition.
United Kingdom
London's regulatory intelligence capabilities retain relevance post-Brexit through MHRA's continued EMA alignment negotiations and parallel marketing authorization pathways. The Cambridge-London corridor sustains demand for cell and gene therapy medical affairs support. Manchester and Birmingham host expanding medical information call center operations serving pan-European sponsors.
Switzerland
Basel's pharmaceutical headquarters cluster generates premium demand for integrated pharmacovigilance and medical writing under Swissmedic's distinct regulatory framework. Zurich anchors real-world evidence platform development for multilingual European deployment. The country's bilateral EU agreements create specialized compliance requirements that favor vendors with Swiss operational entities.
Netherlands
Amsterdam-Leiden biotechnology clustering drives demand for rare disease medical affairs specialization and strategic partnership structures. The Dutch Medicines Evaluation Board's pragmatic regulatory approach attracts sponsors seeking accelerated assessment pathway support. Rotterdam's logistics infrastructure supports distributed medical science liaison team coordination across Benelux territories.
Europe Medical Affairs Outsourcing Market Key Industry Players
Concentration sits with integrated data-execution specialists capable of anchoring unified service-level agreements across pharmacovigilance, medical information, and regulatory medical writing. The vendor base stratifies into three tiers: global contract research organizations with embedded medical affairs divisions, specialized healthcare communications agencies with therapy-area depth, and regional pharmacovigilance boutiques with national regulatory intimacy. Dominant competitive moves include portfolio consolidation around cloud-native evidence platforms and geographic expansion into Eastern European cost arbitrage markets.
Among the integrated platform providers, IQVIA anchors large-account relationships through combined data analytics and field medical execution, while Syneos Health occupies a position emphasizing embedded governance frameworks for distributed medical science liaison teams. Ashfield Healthcare exemplifies the therapy-area specialization archetype, with documented concentration in oncology and rare disease medical communications. These three entities represent distinct strategic postures: data-execution integration, embedded operational models, and scientific depth respectively.
| Leading Market Players |
|---|
| THE MEDICAL AFFAIRS COMPANY |
| Ashfield Healthcare |
| ZEINCRO Group |
| Indegene |
| ICON plc |
| IQVIA |
| Syneos Health |
| PPD Inc |
| Parexel International |
| Others |
Cost & Logistics Intelligence
EMA's Medical Device Regulation gates vendor qualification and price differentiation simultaneously, as compliance certification tiers separate premium field medical providers from economy-tier call center operators while BfArM inspection timelines lock sponsors into long-term contracts with established German infrastructure holders.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations, with three-tier pricing separating embedded field medical teams from functional outsourcing arrangements and project-based consulting engagements. Price differentiation rests on BfArM inspection readiness and EU MDR certification depth, with German sponsors least sensitive due to procurement efficiency mandates while mid-sized biotechnology firms in Eastern Europe face acute cost compression. Pricing pressure stems from GDPR-mandated redundant infrastructure investments per member state.
Supply Chain Analysis
Qualified medical affairs talent concentration in Germany, Switzerland, and the Netherlands underwrites service delivery capacity across the continent. Vendor capability draws from pharmacovigilance case processing infrastructure, CRM-integrated evidence platforms, and therapy-area-specific scientific personnel. Single-source vulnerability runs through specialized safety physician pools in the Rhine-Main corridor. Distribution runs through embedded governance frameworks with client organizations rather than arm's-length service provision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with biotechnology pipeline acceleration outpacing internal medical affairs scaling, as mid-sized developers create niches for specialized providers capable of navigating EMA's evolving real-world evidence guidance without captive infrastructure.
For Market Incumbents: Consolidate around cloud-native evidence platforms to anchor unified procurement relationships against IQVIA's data-execution integration threat. Acquire Eastern European pharmacovigilance boutiques to capture cost arbitrage demand from Swiss headquarters mandates. Certification investment in EU AI Act-compliant algorithmic vigilance tools defends premium positioning.
For New Entrants and Emerging Players: Cell and gene therapy medical science liaison gaps in the Netherlands and Belgium offer white-space entry where incumbents under-serve rare disease sponsors. Poland and Czech Republic medical information hubs present the most penetrable geography due to multilingual capability shortages. Go-to-market through strategic partnership structures with shared risk-reward mechanisms accelerates referenceability.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled pharmacovigilance platforms as regulatory compliance costs escalate. Long-term viability favors vendors with integrated data-execution footprints spanning medical information, pharmacovigilance, and regulatory medical writing. Acquisition target archetype: German pharmacovigilance boutiques with BfArM inspection track records. Signal to watch: EMA accelerated assessment pathway volume as medical affairs readiness compression indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | BfArM inspection readiness separates premium vendors from compliance-lagged competitors in device outsourcing. |
| Cloud-Native Evidence Platform Deployment | CRM-integrated systems anchor long-term biotechnology sponsor relationships through data migration friction. |
| Eastern European Medical Information Hub Establishment | Poland and Czech Republic cost arbitrage captures multinational sponsor procurement efficiency mandates. |
| AI Act-Compliant Algorithmic Vigilance Development | Machine-learning adverse-event detection captures first-mover premium under evolving EMA guidance. |
| Strategic Partnership Structuring | Shared risk-reward mechanisms secure dedicated therapy-area expertise for rare disease sponsors in Benelux. |
Research Approach
Initial hypotheses were tested against primary input from medical affairs directors, pharmacovigilance heads, biotechnology procurement leads, and regulatory intelligence officers and refined through secondary validation across EMA guidance documents, BfArM inspection reports, ClinicalTrials.gov postings, and EU MDR transition filings. Bottom-up service provider capacity assessments triangulated with top-down biotechnology sponsor spend analysis.
Variance-decomposition framing isolated segment-specific growth contributions across service type, end-user sophistication, engagement model, and technology infrastructure dimensions throughout the forecast period. CAGRs derived from pipeline acceleration rates, regulatory timeline compression, and vendor capacity expansion trajectories. Industry-specific inputs included EMA accelerated assessment pathway volumes and GDPR infrastructure cost pass-through coefficients.
Forecasts assume regulatory continuity in EMA Medical Device Regulation implementation and EU AI Act risk-classification frameworks; material policy shifts would require re-modeling. Specific risks include cross-border compliance friction from ANSM-BfArM divergence and specialized talent scarcity constraining vendor scale. Practitioners should keep alternative scenarios live as real-world evidence integration demands and algorithmic vigilance qualification criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Patient Transportation Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Healthcare CMO Market