
 Global Healthcare Provider Network Management Market | 2026-2036
Global Healthcare Provider Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Provider Network Management Market Foresight
Multi-source vendor strategies is realigning how payers and health systems procure network management capabilities. Optum, Inc. leverages its integrated payer-provider data assets to dominate large-scale implementations. McKesson Corporation anchors its position through extensive channel control across pharmaceutical and clinical networks. Cognizant (Trizetto) specializes in modular SaaS deployments that extend legacy system functionality without full replacement.
Healthcare provider network management encompasses the technologies, processes, and governance frameworks that maintain accurate provider directories, verify credentials, manage contracts, and monitor network performance across contracted care delivery organizations. The discipline relies on real-time data synchronization, automated primary source verification, and interoperability standards such as FHIR to ensure that directory accuracy exceeds regulatory thresholds while supporting patient steerage and out-of-network cost containment. Provider data management and credentialing solutions represent mature, high-margin segments where incumbents occupy entrenched positions with long contract cycles. Cloud-based and SaaS deployment models represent the fastest-growing structural category as health systems shed capital-intensive on-premises infrastructure in favor of elastic, API-first architectures that reduce total cost of ownership.
FDA oversight of clinical decision support tools, HIPAA interoperability mandates from the US Department of Health and Human Services, and the EU AI Act's risk-classification requirements for automated credentialing algorithms collectively elevate compliance tooling from optional to essential procurement criteria. These frameworks force vendors to embed audit trails, explainability modules, and cross-border data governance into core platform architecture. Stakeholders must monitor how emerging AI disclosure requirements in the European Union and state-level network adequacy rules in the United States reshape product roadmaps and competitive differentiation.
Market Dynamics
Cloud migration and API-first architectures are compressing contract cycles as health systems abandon on-premises credentialing infrastructure, forcing vendors to reprice SaaS offerings and embed real-time FHIR synchronization as table stakes rather than premium features.
Growth Catalysts
- HIPAA Interoperability Mandates:The US Department of Health and Human Services requires standardized provider directory APIs by 2026, compelling payers to upgrade legacy credentialing stacks or face enrollment penalties.
- EU AI Act Risk Classification:Automated credentialing algorithms in Europe now face mandatory audit trails and explainability modules, creating procurement urgency for compliant tooling among multinational insurers.
- Managed Care Expansion:Value-based contracting models in Medicare Advantage and Medicaid managed care are multiplying the number of provider relationships requiring active network monitoring and performance scoring.
Market Restraints
- Primary Source Verification Bottlenecks:State medical boards and hospital privileging offices maintain inconsistent digital interfaces, creating manual reconciliation workarounds that inflate operational costs.
- Cloud Concentration Risk:AWS, Azure, and Google Cloud host over 80 percent of healthcare SaaS workloads, exposing credentialing platforms to single-provider outage vulnerabilities and egress fee volatility.
- Legacy System Entrenchment:Cerner and Epic EHR deployments embed proprietary provider data models that resist external API integration, extending implementation timelines.
Strategic Opportunities
- India Provider Data Infrastructure:The country's National Health Stack and Ayushman Bharat expansion are digitizing 1.5 million accredited facilities, opening greenfield SaaS deployments without legacy migration burdens.
- Blockchain-Enabled Credentialing:Immutable provider identity verification across state lines and international borders addresses cross-border telehealth licensing complexity.
- Channel Innovation Through PEO Partnerships:Professional employer organizations serving mid-market medical practices are emerging as aggregated procurement channels for bundled credentialing and compliance services.
Industry Challenges
- Interoperability Engineer Scarcity:Health systems compete for FHIR implementation specialists and RIM (Reference Information Model) architects who can bridge HL7 v2 and modern API standards.
- Multi-State Licensing Synchronization:Interstate Medical Licensure Compact participation varies by specialty, forcing platforms to maintain parallel verification workflows for compact and non-compact states.
- AI Explainability Documentation:Credentialing algorithms using machine learning for fraud detection or network adequacy scoring must generate human-interpretable decision trails for regulatory examination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Provider Network Management Market |
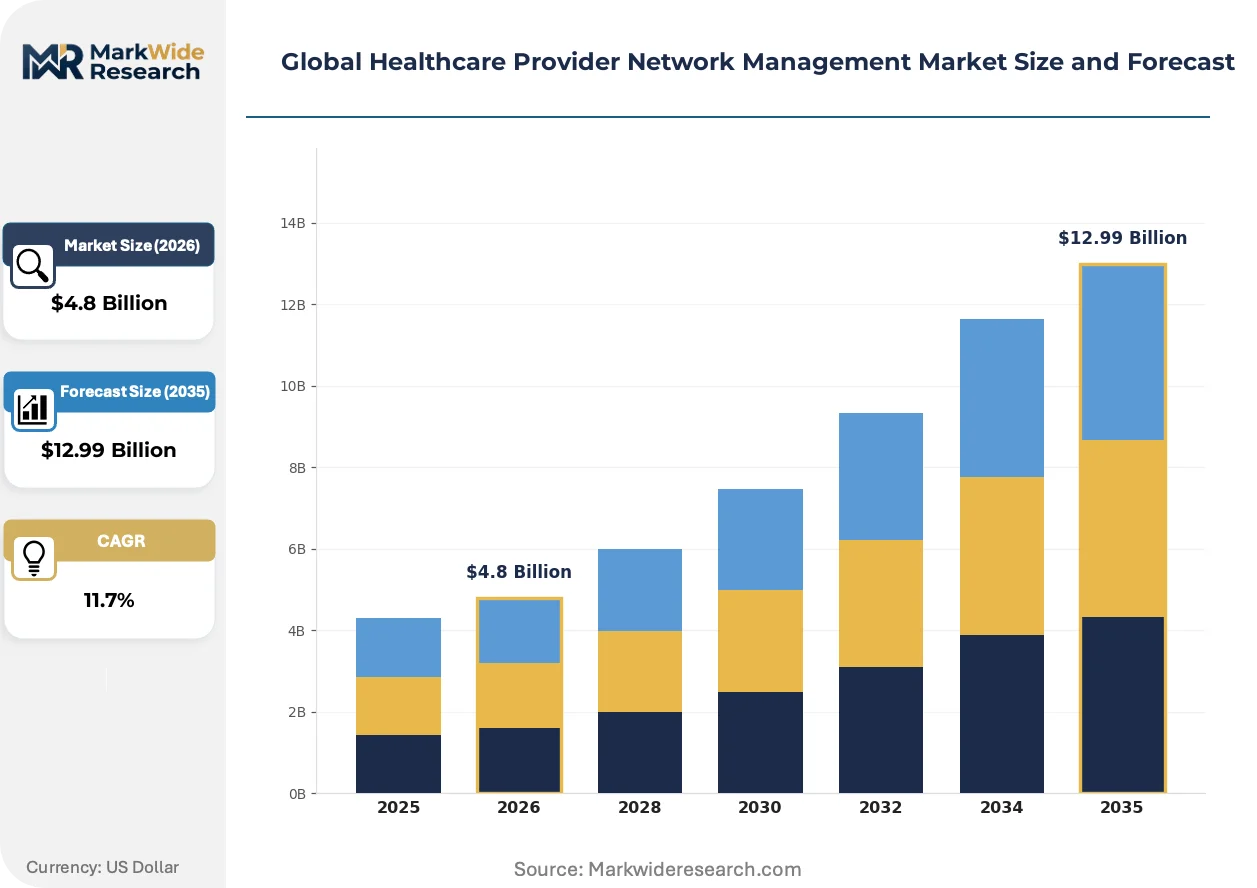
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Provider Data Management, Credentialing Solutions, Contract Management, Claims Adjudication, Analytics Platforms, Compliance Tools Application: Patient Referral Management, Provider Directory Services, Quality Assurance, Network Performance Monitoring, Risk Assessment, Cost Control End User: Hospitals, Ambulatory Care Centers, Managed Care Organizations, Specialty Clinics, Diagnostic Laboratories, Telehealth Services Deployment: Cloud-Based, On-Premises, Hybrid Models, SaaS Platforms, Private Cloud, Virtualized Environments |
| Companies Covered | Infosys Limited, McKesson Corporation, Optum, Inc., Mphasis Limited, Change Healthcare, Cognizant (Trizetto), Centene Corporation, Appian, Atos SE (Syntel Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Provider Network Management Market Shifts & Advancements
Real-time data synchronization and automated verification pipelines are replacing batch-processed credentialing cycles, compressing provider onboarding from months to days while embedding continuous monitoring for sanctions or malpractice events.
API-first credentialing platforms are consolidating point solutions for directory management, primary source verification, and contract lifecycle management into unified data layers. Mid-market health plans and independent practice associations are adopting these consolidated stacks fastest, drawn by per-provider pricing that scales with network size rather than capital expenditure. Vendor consolidation is accelerating as standalone directory vendors lose standalone procurement cycles to integrated suites.
The EU AI Act's high-risk system classification for automated credentialing decisions is forcing algorithmic transparency into product roadmaps. European health insurers must now document training data provenance and model drift for any automated privileging or exclusion recommendations. Vendors serving German and French markets are embedding model cards and bias audit modules as default architecture rather than compliance add-ons.
Subscription-based procurement is displacing perpetual license models across payer technology budgets. Chief information officers now favor annual contracts with usage-based tiers that align costs to active provider counts rather than total licensed seats. This shift is most pronounced among Medicaid managed care organizations in the United States, where membership volatility makes fixed-cost infrastructure commitments untenable.
Global Healthcare Provider Network Management Market Segmentation
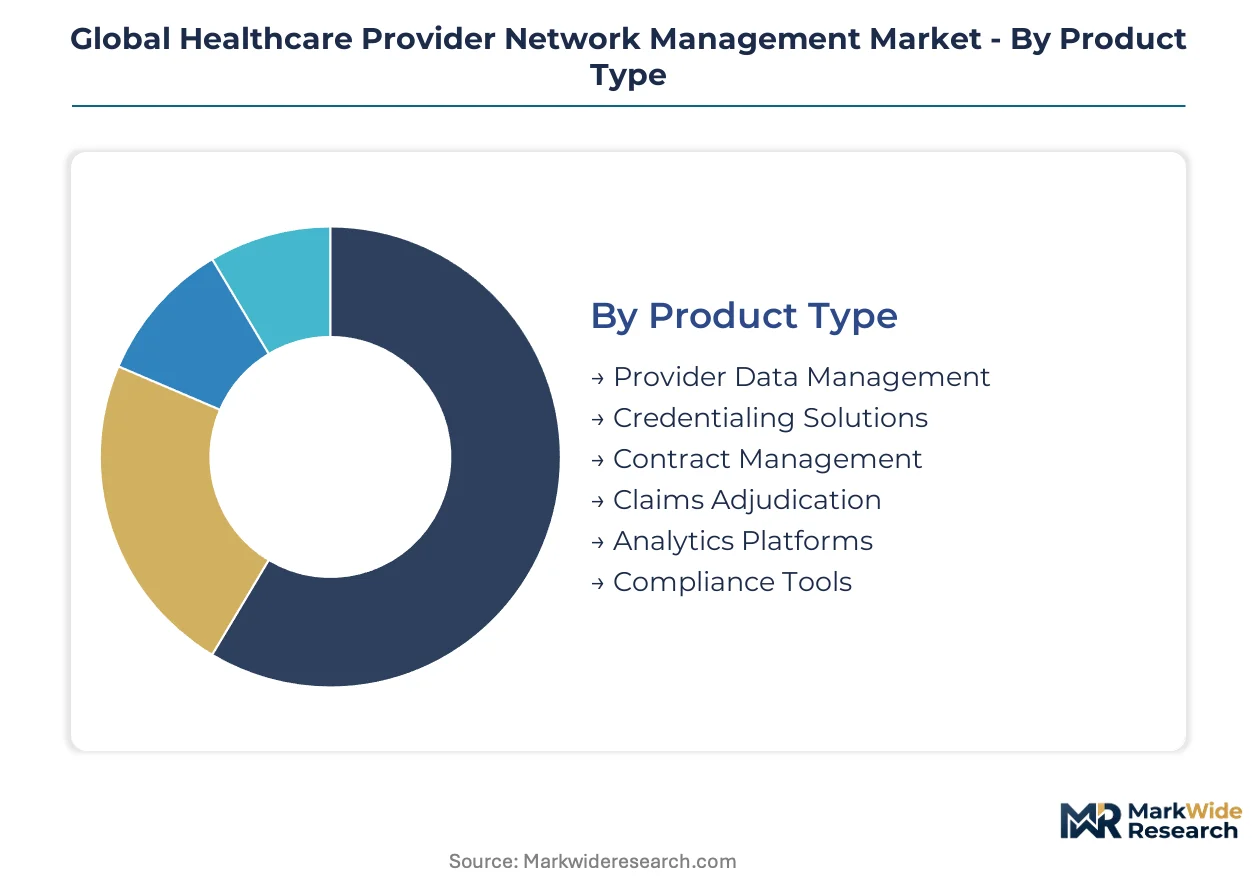
Healthcare provider network management solutions fragment across functional layers, with procurement patterns diverging sharply between capital-intensive health systems and lean managed care organizations. Understanding these segment boundaries clarifies where vendors must bundle capabilities versus where modular point solutions retain viability.
Product Type:
Volume concentrates in core data infrastructure, while premium pricing attaches to specialized compliance and analytics modules.
- Provider Data Management:Centralized repositories maintaining provider demographics, practice locations, and network participation status with real-time FHIR synchronization. Demand clusters among United States payers modernizing directories to meet HIPAA interoperability mandates. Legacy on-premises deployments dominate, though cloud migrations are accelerating among mid-market plans.
- Credentialing Solutions:Automated primary source verification pipelines for medical licensure, board certifications, and malpractice history. German and French insurers are procuring compliant tooling under EU AI Act risk-classification requirements. The segment commands sustained pricing power due to regulatory non-negotiability.
- Contract Management:Lifecycle tools for provider agreement negotiation, amendment tracking, and rate schedule maintenance.
- Claims Adjudication:Real-time eligibility verification and out-of-network cost containment engines.
- Analytics Platforms:Network adequacy scoring, provider performance benchmarking, and patient steerage optimization.
- Compliance Tools:Audit trail generation, regulatory reporting automation, and cross-border data governance enforcement.
Mature deployment sits with Provider Data Management. Newer deployment is concentrated in Compliance Tools.
Application:
Operational priorities split between patient-facing directory accuracy and back-office financial control.
- Patient Referral Management:Intelligent routing systems matching patients to in-network specialists based on proximity, availability, and quality metrics. United States health systems are embedding these tools within Epic and Cerner EHR workflows to reduce out-of-network leakage. The application requires tight integration with payer directory APIs.
- Provider Directory Services:Public-facing and internal directory maintenance with real-time accuracy monitoring. India's Ayushman Bharat expansion is driving greenfield implementations without legacy data migration burdens. Accuracy thresholds now carry enrollment penalties under US regulations.
- Quality Assurance:Credentialing verification, privileging oversight, and continuous competence monitoring.
- Network Performance Monitoring:Utilization pattern analysis, access time measurement, and care gap identification.
- Risk Assessment:Provider-level fraud detection, malpractice exposure quantification, and sanctions screening.
- Cost Control:Out-of-network claim prevention, prior authorization automation, and rate negotiation support.
Long-standing investment characterizes Provider Directory Services. Steepest expansion trajectory belongs to Patient Referral Management.
End User:
Procurement authority concentrates in integrated delivery networks, while specialty providers represent fragmented, price-sensitive demand.
- Hospitals:Multi-facility health systems requiring enterprise-grade credentialing across employed and affiliated physicians. United States academic medical centers are consolidating point solutions into unified platforms to reduce vendor management overhead. Implementation timelines extend due to Epic and Cerner EHR integration complexity.
- Managed Care Organizations:Payers with the most acute regulatory pressure under HIPAA interoperability mandates and network adequacy rules. Medicaid managed care plans in the United States favor subscription pricing that scales with membership volatility. These organizations are displacing perpetual licenses fastest.
- Ambulatory Care Centers:Freestanding surgical and urgent care facilities with lighter compliance requirements.
- Specialty Clinics:Cardiology, oncology, and orthopedics practices with niche credentialing workflows.
- Diagnostic Laboratories:High-volume testing facilities requiring network participation verification.
- Telehealth Services:Cross-border licensing complexity is driving interest in blockchain-enabled credentialing for interstate and international practice authority.
Established infrastructure dominates Hospitals. Emerging demand concentrates in Telehealth Services.
Deployment:
Cost structure and control requirements determine architecture selection, with elasticity trading against data sovereignty concerns.
- Cloud-Based:Multi-tenant SaaS architectures hosted on AWS, Azure, or Google Cloud with API-first integration. United States payers are migrating here to shed capital-intensive infrastructure and enable real-time FHIR synchronization. Concentration risk in hyperscaler infrastructure creates outage vulnerability and egress fee volatility.
- SaaS Platforms:Purpose-built credentialing applications with per-provider subscription pricing and rapid deployment cycles. Cognizant's Trizetto unit specializes in modular deployments that extend legacy functionality without full replacement. This model is gaining share fastest among Medicaid managed care organizations.
- On-Premises:Self-hosted infrastructure retaining full data control for security-sensitive environments.
- Hybrid Models:Split architectures with sensitive credentialing data on-premises and directory services in cloud.
- Private Cloud:Single-tenant hosted environments for large health systems with customization requirements.
- Virtualized Environments:Containerized deployments enabling portability across infrastructure substrates.
Legacy entrenchment persists in On-Premises. Gaining share fastest is SaaS Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States payers and health systems drive the largest share of procurement volume, though Germany, India, and the United Kingdom are generating disproportionate growth as regulatory mandates force technology replacements.
United States
HIPAA interoperability deadlines and Medicare Advantage expansion are compelling payers to modernize credentialing stacks. The Department of Health and Human Services requires standardized provider directory APIs by 2026, with enrollment penalties for non-compliance. Nashville and Minneapolis health plan clusters are consolidating vendor relationships into unified platforms.
Germany
Statutory health insurers are procuring compliant tooling under EU AI Act risk-classification requirements for automated privileging decisions. The BfArM and federal data protection authorities mandate audit trails for algorithmic credentialing. Berlin and Munich technology corridors are hosting vendor development centers for explainability modules.
India
Ayushman Bharat expansion and the National Health Stack are digitizing 1.5 million accredited facilities without legacy migration burdens. The Ministry of Health and Family Welfare is standardizing provider registries across states. Hyderabad and Bengaluru SaaS clusters are deploying greenfield credentialing infrastructure for regional insurers.
United Kingdom
NHS England procurement frameworks are embedding real-time directory synchronization requirements into vendor contracts. The MHRA and NHS Digital are aligning credentialing standards with international interoperability protocols. London health technology procurement hubs are selecting API-first platforms for integrated care systems.
France
CNIL oversight of automated health decisions is accelerating explainable AI adoption among mutual insurers. The ANSM and HAS are tightening privileging verification standards for telehealth expansion. Paris and Lyon insurance technology centers are piloting blockchain-enabled cross-border credentialing for European practice authority.
Global Healthcare Provider Network Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle credentialing, directory management, and compliance modules into unified suites. The vendor base organizes into three tiers: integrated payer-provider conglomerates with captive data assets, specialized health IT consultancies with modular SaaS architectures, and legacy infrastructure incumbents defending long-cycle contracts. Competitive positioning depends on FHIR implementation speed and regulatory compliance depth rather than price alone.
Within the integrated data asset tier, Optum, Inc. and McKesson Corporation exemplify scale-driven consolidation of payer and provider network intelligence. Cognizant (Trizetto) occupies a distinct position among modular specialists, extending legacy system functionality without requiring full replacement. These three anchors represent divergent strategic bets: vertical data integration versus API-first extensibility versus hybrid deployment flexibility.
| Leading Market Players |
|---|
| Infosys Limited |
| McKesson Corporation |
| Optum, Inc. |
| Mphasis Limited |
| Change Healthcare |
| Cognizant (Trizetto) |
| Centene Corporation |
| Appian |
| Atos SE (Syntel Inc.) |
| Others |
Supply & Pricing Matrix
Medicaid managed care organizations concentrated in the United States are driving subscription-based pricing models that scale per-provider counts rather than fixed infrastructure commitments. This buyer concentration has compressed contract cycles and forced vendors to unbundle implementation services from recurring platform fees.
Pricing Analysis
Warranty and service-level guarantees differentiate premium SaaS tiers from stripped-down economy offerings in this market. Three-tier pricing structure across premium, standard, and economy levels anchors on FHIR implementation speed, audit trail depth, and dedicated support availability. Cost compression in the economy tier is intensifying because hyperscaler egress fees and interoperability engineer scarcity inflate operational overhead. Medicaid managed care plans exhibit the highest price sensitivity due to membership volatility, while academic medical centers with Epic and Cerner integration demands accept premium pricing for customization.
Supply Chain Analysis
Direct-to-payer channels handle large health plan procurement, while professional employer organizations aggregate mid-market medical practice demand. Software development concentrates in the United States, India, and Germany, with Hyderabad and Bengaluru SaaS clusters feeding greenfield deployments. Cloud infrastructure draws from AWS, Azure, and Google Cloud hyperscalers, creating single-provider outage vulnerability for credentialing platforms. Distribution runs through vendor-direct sales teams, health IT consultancies, and GPO contracts with limited channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based credentialing platforms are displacing capital-intensive on-premises infrastructure as health systems prioritize API-first architectures over legacy system replacement. This technology transition compresses implementation timelines from months to days while embedding continuous compliance monitoring.
For Market Incumbents: Deepen FHIR implementation capabilities to defend against modular SaaS specialists extending legacy functionality without full replacement. Invest in explainability modules for EU AI Act compliance before risk-classification deadlines force reactive procurement. Prioritize channel control through professional employer organization partnerships that aggregate mid-market demand.
For New Entrants and Emerging Players: API-first integration partnerships with Epic and Cerner EHR ecosystems offer the most penetrable route into hospital procurement cycles. Target India's Ayushman Bharat expansion for greenfield deployments without legacy migration burdens. Position blockchain-enabled credentialing for telehealth cross-border licensing complexity as a differentiated entry angle.
For Investors and Strategic Acquirers: The window for entry favors modular SaaS vendors with proven FHIR synchronization and Medicaid managed care customer bases. Long-term viability hinges on regulatory compliance depth rather than price competition alone. Watch for state-level network adequacy rule expansions as inflection indicators for compliance tooling procurement urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Synchronization Investment | Real-time directory accuracy now carries HIPAA enrollment penalties from HHS. |
| EU AI Act Compliance Module | Audit trails and explainability requirements from BfArM create procurement urgency. |
| PEO Channel Partnership | Aggregated mid-market access reduces customer acquisition costs for SaaS vendors. |
| Blockchain Credentialing Pilot | Immutable verification addresses Interstate Medical Licensure Compact synchronization gaps. |
| Hyperscaler Diversification | Multi-cloud architecture mitigates single-provider outage risk for critical credentialing workloads. |
Research Methodology
Multi-period observation of vendor contract cycles, regulatory filing patterns, and health plan technology budgets anchored the trend analysis, supplemented by interviews with health system CIOs, Medicaid managed care technology officers, interoperability engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare data, hospital procurement databases, EU AI Act implementation guidance, and HHS interoperability mandate documentation. Bottom-up sizing of individual vendor deployments triangulated against top-down health plan IT spending estimates.
Segment-weighting across deployment models, end-user categories, and geographic regulatory clusters structured the analytical framework. Product type splits between provider data management, credentialing solutions, and compliance tools combined with application segmentation across patient referral management and directory services. CAGRs were derived from fitted growth curves against observed adoption rates. Forecast inputs included health plan cloud migration timelines and state-level network adequacy rule expansion schedules.
The model holds under stable regulatory enforcement timelines; deviation in HIPAA interoperability deadline extensions or EU AI Act risk-classification scope changes would shift vendor procurement urgency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Hospice Care Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Long Term Care Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Ambulatory Healthcare Service Market