
 Medical Social Working Services Market | 2026-2036
Medical Social Working Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Social Working Services Market Analysis
Telehealth platform integration is tilting care delivery toward hybrid models that blend remote assessment with in-person follow-through. Kaiser Permanente leverages its captive insurance structure to embed social workers directly within primary care teams. Memorial Sloan Kettering Cancer Center anchors its oncology social work program in psychosocial distress screening protocols. DaVita Inc. specializes in dialysis-specific resource coordination that bridges clinic and community settings.
Medical social working services encompass licensed clinical interventions that address psychosocial barriers to treatment adherence, including care transition planning, benefits navigation, and family systems counseling, typically delivered through structured encounter documentation tied to ICD-10 Z-codes. The service type dimension shows resource coordination commanding the widest deployment footprint as health systems seek to reduce readmission penalties, while telehealth delivery models are capturing the fastest expansion trajectory among delivery modalities. Crisis intervention retains premium reimbursement rates but faces workforce supply constraints that limit geographic scaling.
FDA oversight of digital therapeutic platforms intersects with CMS Conditions of Participation for hospital discharge planning, creating dual compliance pressure that shapes vendor qualification criteria. HIPAA privacy frameworks govern telehealth channel expansion, particularly when services cross state licensure boundaries. State Medicaid agencies are tightening credentialing requirements for community-based social work contractors, tightening market access for non-affiliated providers. Stakeholders must monitor how interstate licensure compacts reshape workforce mobility and competitive positioning in concentrated metropolitan markets.
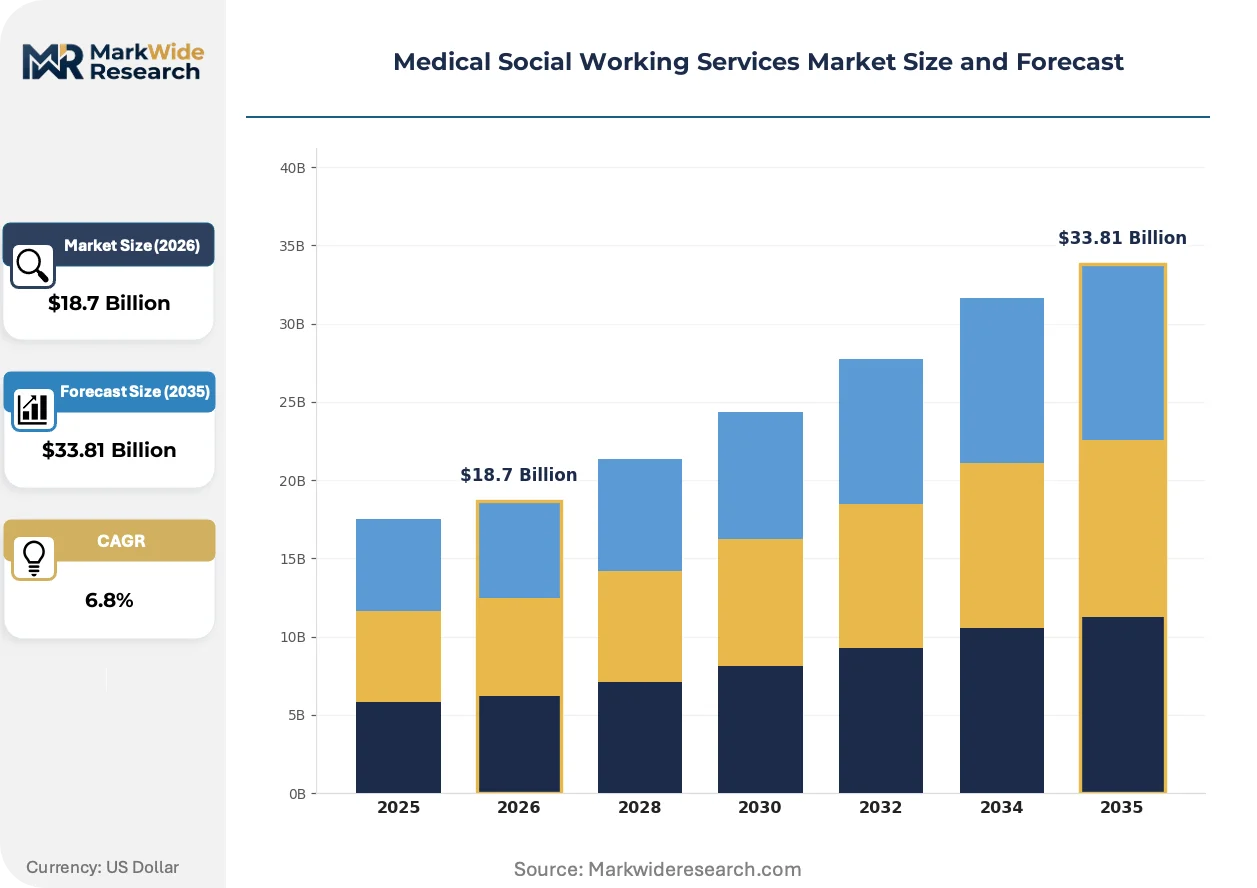
Market Dynamics
CMS discharge planning mandates are forcing hospital systems to embed licensed social workers directly into care teams, transforming medical social work from ancillary support to a regulated operational requirement tied to reimbursement eligibility.
Growth Catalysts
- CMS Conditions of Participation:Hospital systems must now document psychosocial assessments prior to discharge, creating mandatory demand for embedded social work capacity.
- Value-based reimbursement:Medicare ACOs tie provider payments to readmission reductions, making care transition coordination a financial imperative.
- Telehealth parity laws:State-level mandates now reimburse remote behavioral health screening at equivalent rates to in-person encounters.
Market Restraints
- Workforce supply constraints:Master of Social Work programs produce insufficient licensed clinical social workers to meet hospital demand.
- State licensure fragmentation:Interstate practice remains restricted where compacts are not adopted, limiting telehealth workforce mobility.
- Reimbursement rate compression:Medicaid fee schedules in multiple states lag Medicare rates, squeezing margins for community-based providers.
Strategic Opportunities
- Rural health clinic expansion:Federally qualified health centers in underserved counties lack embedded social work capacity.
- Digital therapeutic integration:FDA-cleared apps for depression and anxiety create partnership opportunities between platforms and health systems.
- Specialty pharmacy coordination:High-cost biologics require adherence support that social workers can structure around benefits navigation.
Industry Challenges
- EHR documentation burden:Structured encounter requirements for ICD-10 Z-codes consume clinical time without proportional reimbursement.
- Cross-state credentialing complexity:Hospital systems operating in multiple jurisdictions face redundant licensing verification for telehealth staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Social Working Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Counseling, Home Visit, Resource Coordination, Crisis Intervention End User: Hospitals, Clinics, Rehabilitation Centers, Nursing Homes Therapeutic Area: Mental Health, Substance Abuse, Pediatrics, Geriatrics Delivery Model: Telehealth, In-Person, Group Sessions, Community Outreach |
| Companies Covered | Memorial Sloan Kettering Cancer Center, Kaiser Permanente, DaVita Inc, HCA Healthcare Inc., CommonSpirit Health, Trinity Health, UPMC, Sutter Health, Providence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Social Working Services Market Emerging Trajectories
Service delivery models are compressing around hybrid architectures that blend synchronous telehealth with embedded in-person follow-through, while regulatory pressure hardens documentation requirements.
Artificial intelligence screening tools are migrating from experimental pilots to operational workflows. Natural language processing engines flag psychosocial distress in EHR notes automatically. Kaiser Permanente and similar integrated systems deploy these algorithms to triage patients to social work consults. The technology is migrating from research environments to production clinical decision support.
HIPAA enforcement actions against telehealth platforms are intensifying scrutiny of business associate agreements. The Department of Health and Human Services Office for Civil Rights has prioritized audits of video conferencing vendors serving behavioral health providers. Platforms lacking end-to-end encryption or proper data retention protocols face exclusion from hospital procurement shortlists. Smaller community-based contractors without compliance infrastructure are consolidating into larger affiliated networks.
Health system procurement departments now require social work vendors to demonstrate outcomes metrics tied to readmission reductions. Request-for-proposal documents specify minimum thresholds for thirty-day all-cause readmission improvement. Vendors without claims-data integration capabilities lose competitive positioning. This pattern is most visible in Medicare Advantage plan networks concentrated in Florida and Texas metropolitan markets.
Medical Social Working Services Market Segmentation
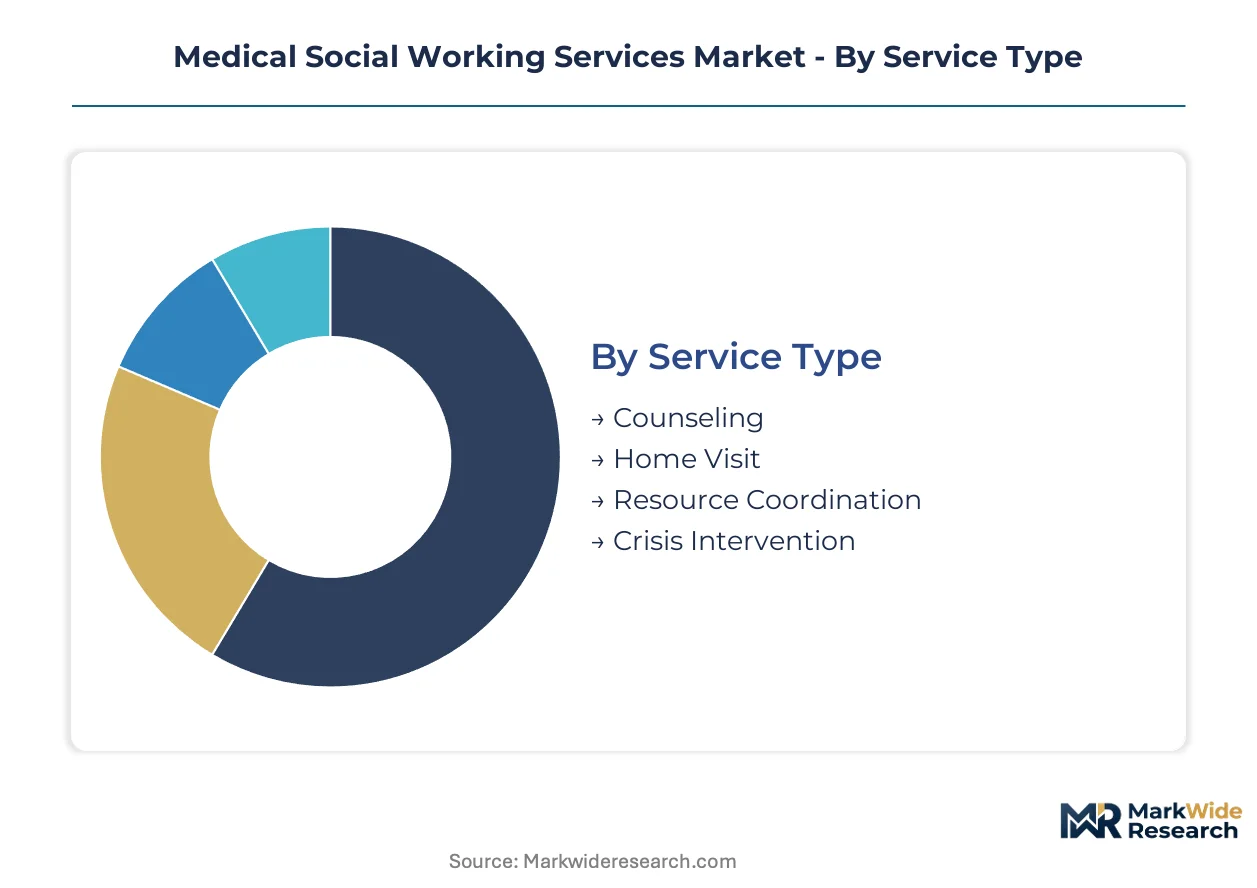
Segmentation in medical social working services reveals how regulatory mandates, reimbursement structures, and care delivery innovations reshape vendor positioning. Understanding these dimensions exposes where capital flows concentrate and which service configurations capture premium rates.
Service Type:
Cost tier differentiation across service types determines reimbursement rates and workforce deployment economics.
- Counseling:Licensed clinical interventions address psychosocial barriers through structured encounter documentation tied to ICD-10 Z-codes. Hospital systems in California and New York embed counselors within primary care teams to meet CMS discharge planning requirements.
- Home Visit:Post-discharge assessments conducted in patient residences reduce thirty-day readmission penalties under Medicare ACO contracts. Demand concentrates in Medicare Advantage networks across Florida metropolitan markets where risk-adjusted payments reward outcome documentation.
- Resource Coordination:Bridges clinic and community settings through benefits navigation and care transition planning.
- Crisis Intervention:Retains premium reimbursement rates but faces workforce supply constraints limiting geographic scaling.
Resource coordination commands the established base. The steepest expansion runs through home visit services.
End User:
Application context shapes documentation requirements, credentialing standards, and procurement pathways for social work vendors.
- Hospitals:CMS Conditions of Participation mandate psychosocial assessments prior to discharge, creating regulated operational demand. Integrated delivery networks in Texas and Pennsylvania embed licensed social workers directly into care teams to maintain reimbursement eligibility.
- Clinics:Federally qualified health centers in underserved counties lack embedded social work capacity, presenting expansion targets for regional contractors.
- Rehabilitation Centers:Post-acute settings require care transition coordination to manage length-of-stay metrics tied to value-based contracts.
- Nursing Homes:Long-term care facilities face state Medicaid agency tightening of credentialing requirements for community-based contractors.
Hospitals anchor the revenue base. Clinics present the most open expansion terrain.
Therapeutic Area:
Customer type segmentation exposes how population health priorities and payment model incentives concentrate vendor specialization.
- Mental Health:Telehealth parity laws in multiple states now reimburse remote behavioral health screening at equivalent rates to in-person encounters. Kaiser Permanente deploys natural language processing algorithms to triage patients to social work consults based on EHR distress flags.
- Substance Abuse:FDA-cleared digital therapeutic apps for depression and anxiety create partnership opportunities between platforms and health systems.
- Pediatrics:Family systems counseling addresses adherence barriers for complex chronic conditions.
- Geriatrics:Demand concentrates most visibly in geriatric service lines within integrated delivery networks managing Medicare risk contracts.
Geriatrics holds the deepest installed base. Mental health is climbing the fastest.
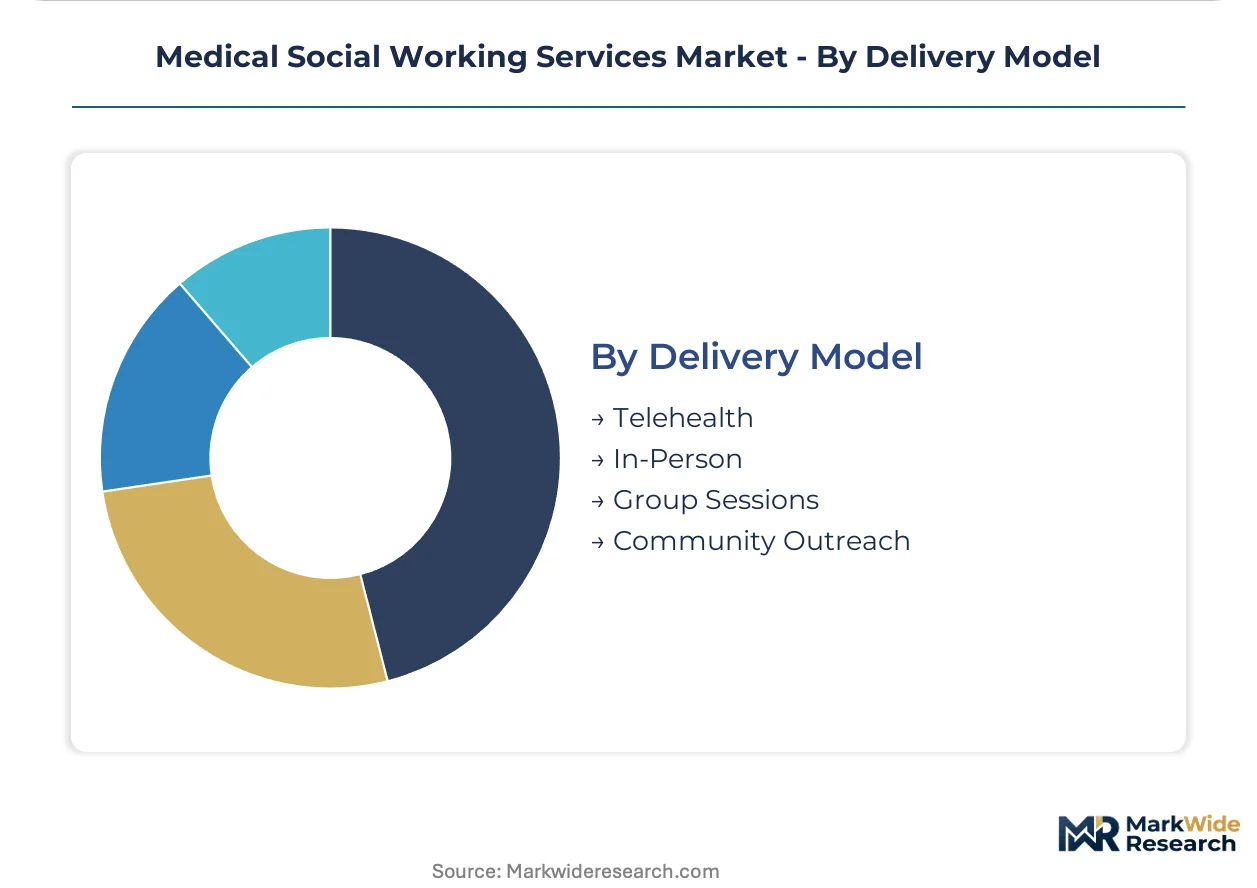
Delivery Model:
Volume distribution across delivery modalities reflects technology adoption curves and regulatory enforcement patterns.
- Telehealth:HIPAA enforcement actions against video conferencing vendors have intensified scrutiny of business associate agreements. Platforms lacking end-to-end encryption face exclusion from hospital procurement shortlists.
- In-Person:Retains dominance for crisis intervention and home visit services where physical presence carries clinical necessity.
- Group Sessions:Efficiency gains through cohort-based delivery attract interest from Medicaid managed care organizations seeking cost containment.
- Community Outreach:Bridges clinical and social service infrastructure in rural health clinic expansion areas.
In-person delivery maintains the volume base. Telehealth is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks and hospital systems concentrate procurement of medical social working services in markets with mature value-based reimbursement infrastructure and stringent discharge planning mandates.
United States
Medicare ACO contracts and CMS Conditions of Participation drive hospital demand for embedded social work capacity. HIPAA enforcement actions against telehealth platforms intensify compliance scrutiny for behavioral health vendors. Kaiser Permanente in California deploys natural language processing algorithms to triage patients to social work consults based on EHR distress flags.
Germany
Statutory health insurance reforms expand psychosocial care coordination benefits for chronic disease management. The EU AI Act shapes deployment of automated screening tools in hospital discharge workflows. Berlin-Brandenburg integrated care networks pilot hybrid telehealth models blending remote assessment with in-person follow-through.
United Kingdom
NHS Long Term Plan targets embed social prescribing link workers within primary care networks. NHS England commissioning frameworks tighten outcomes documentation requirements for community-based providers. Greater Manchester devolved health system contracts regional vendors for care transition coordination.
Japan
Super-aged society policies accelerate geriatric social work integration into long-term care insurance. METI guidelines on digital health platforms govern telehealth channel expansion for behavioral health services. Kansai region hospitals partner with municipal governments to bridge clinic and community resource coordination.
Australia
Medicare Benefits Schedule updates expand telehealth reimbursement for allied mental health services. The Therapeutic Goods Administration intersects with state hospital accreditation standards for digital therapeutic platforms. New South Wales integrated care networks embed social workers within hospital discharge planning teams.
Medical Social Working Services Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated health systems with captive insurance structures. Tier-one positions cluster within hospital systems operating Medicare Advantage networks and federally qualified health center contractors. Strategic archetypes include vertically integrated delivery networks, dialysis-specialized resource coordinators, and oncology-centered psychosocial programs. Dominant competitive moves encompass EHR-embedded workflow integration and outcomes-based procurement contracting tied to readmission reduction metrics.
Among United States-based integrated delivery networks, Kaiser Permanente, Memorial Sloan Kettering Cancer Center, and DaVita Inc. exemplify distinct strategic archetypes. Kaiser Permanente occupies a position representing the captive insurance-embedded model. Memorial Sloan Kettering Cancer Center anchors the oncology-specialized psychosocial screening tier. DaVita Inc. sits within the dialysis-specific resource coordination segment bridging clinic and community settings.
| Leading Market Players |
|---|
| Memorial Sloan Kettering Cancer Center |
| Kaiser Permanente |
| DaVita Inc |
| HCA Healthcare Inc. |
| CommonSpirit Health |
| Trinity Health |
| UPMC |
| Sutter Health |
| Providence |
| Others |
Supply Flow & Price Mechanics
Master of Social Work program capacity in the United States determines licensed clinical social worker availability, concentrating margin capture among hospital systems with captive training pipelines and direct university partnerships. CMS-mandated psychosocial assessment documentation creates fixed-cost structures that favor scaled integrated delivery networks over community-based contractors.
Pricing Analysis
Cost-plus contracts with Medicare Advantage plans index reimbursement to readmission reduction performance metrics rather than encounter volume. Three-tier pricing structure across premium, standard, and economy levels separates crisis intervention rates from resource coordination and telehealth screening. Pricing pressure stems from Medicaid fee schedule compression in states lagging Medicare parity. Federally qualified health centers exhibit highest price sensitivity due to grant-dependent operating models.
Supply Chain Analysis
Contract-manufacturing concentration for telehealth platform infrastructure sits with cloud service providers and HIPAA-compliant video conferencing vendors holding healthcare-specific certifications. Licensed clinical social worker supply draws from United States, Canada, and United Kingdom graduate programs with CSWE accreditation. Single-source vulnerability runs through interstate licensure compact adoption gaps restricting workforce mobility. Distribution runs through hospital procurement departments and Medicare Advantage plan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical social working services represent high-growth disruption as AI-enabled psychosocial distress screening migrates from experimental pilots to operational clinical decision support, forcing workforce restructuring and vendor consolidation.
For Market Incumbents: Pre-empt platform commoditization by embedding natural language processing triage algorithms directly into EHR workflows before standalone vendors achieve hospital procurement lock-in. Acquire community-based contractors in non-compact states to capture telehealth workforce mobility restrictions as a defensive moat. Kaiser Permanente's captive insurance structure offers a template for vertical control over care coordination economics. For New Entrants and Emerging Players: Establish a beachhead in rural health clinic expansion zones where federally qualified health centers lack embedded social work capacity and CMS discharge planning mandates create immediate procurement demand. Target Medicare Advantage networks in Florida metropolitan markets where risk-adjusted payments reward outcome documentation. Lead with digital therapeutic platform partnerships offering FDA-cleared adherence support for high-cost biologics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional social work contractors holding hospital system contracts but lacking EHR-embedded workflow integration or claims-data analytics capabilities. Five-to-ten year viability hinges on successful transition from encounter-based reimbursement to outcomes-based contracting tied to readmission reduction metrics. Monitor quarterly CMS Conditions of Participation enforcement actions as inflection indicators for mandatory demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EHR Workflow Integration | Kaiser Permanente deploys NLP algorithms to triage patients to social work consults automatically. |
| Outcomes-Based Contracting | Hospital procurement departments now specify thirty-day readmission improvement thresholds in RFPs. |
| Telehealth Platform Compliance | HHS Office for Civil Rights audits exclude vendors lacking end-to-end encryption from shortlists. |
| Interstate Licensure Expansion | Social work compact adoption reshapes workforce mobility in concentrated metropolitan markets. |
| Digital Therapeutic Partnership | FDA-cleared apps for depression create alliance opportunities between platforms and health systems. |
Methodological Framework
The analysis maps counseling, home visit, resource coordination, and crisis intervention service types, each validated through hospital discharge planners, Medicare Advantage contracting officers, licensed clinical social workers, and EHR implementation specialists. Primary interviews combined with secondary validation from CMS Medicare data, hospital procurement databases, GPO contracts, and state Medicaid agency fee schedules. Bottom-up service line modeling triangulated against top-down integrated delivery network expenditure analysis.
Assumptions held fixed include CMS Conditions of Participation enforcement intensity and Medicare ACO contract penetration rates, while telehealth parity law adoption and interstate licensure compact expansion were varied across scenarios. Segmentation dimensions modeled encompass service type, end user, therapeutic area, and delivery model. CAGRs derived from regression analysis against Medicare spending trajectories and workforce supply projections, with inputs from behavioral health screening technology adoption curves and value-based reimbursement contract growth.
Sensitivities concentrate around Medicaid fee schedule adjustments and FDA digital therapeutic approval timelines. Forecasts reflect assumptions about CMS mandate continuity and AI screening tool clinical validation progress. Quarterly review of hospital readmission penalty data and state licensure compact ratification status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Medical Spa Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Primary Care Physicians Market