
 Kids Sports Injury Treatment Market | 2026-2036
Kids Sports Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Sports Injury Treatment Market Foresight
Aftermarket service revenue from brace fitting and follow-up physiotherapy is reshaping how orthopedic suppliers capture lifetime value per pediatric patient. Stryker Corporation leverages its hospital channel relationships to dominate inpatient surgical repair procedures. Mueller Sports Medicine, Inc. anchors the retail and direct-to-consumer brace segment through established sports retail partnerships. Össur hf differentiates via pediatric-specific prosthetic and support product lines engineered for growing bodies.
Kids sports injury treatment encompasses the clinical and consumer interventions applied to musculoskeletal trauma, overuse conditions, and acute soft-tissue damage in patients under eighteen years of age, utilizing anatomically scaled devices, age-appropriate rehabilitation protocols, and modified dosing regimens for thermal and electrical modalities. The primary purpose is to restore functional mobility, prevent growth-plate complications, and enable safe return-to-play timelines for youth athletes. Braces and support products command the largest product-type revenue pool due to repeat purchase cycles and seasonal sports turnover, while telehealth delivery is expanding fastest as rural and suburban families gain virtual access to pediatric sports specialists. Cryotherapy technology leads the modality mix for acute injury management, though electrical stimulation is gaining traction in post-surgical rehabilitation protocols for adolescent ACL reconstructions.
The FDA's pediatric device innovation pathway shapes product development priorities by offering expedited review for youth-specific orthopedic devices, while ISO 13485 quality management standards govern manufacturing consistency across international supply chains. State-level concussion protocols and return-to-play laws in jurisdictions such as Texas, California, and New York mandate medical clearance, directly channeling injured athletes into formal clinical evaluation pathways rather than informal home treatment. Stakeholders must monitor how evolving youth sports specialization trends and year-round training intensity alter injury profiles and corresponding treatment modality demand.
Market Dynamics
The FDA's pediatric device innovation pathway compresses regulatory timelines for youth-specific orthopedic devices, accelerating commercialization cycles while state-level concussion mandates in Texas, California, and New York funnel injured athletes into formal clinical channels rather than informal home treatment.
Growth Catalysts
- School-Based Athletic Program Expansion:District-level investment in competitive youth sports across suburban United States sustains consistent injury treatment volume and drives demand for age-appropriate bracing and rehabilitation protocols.
- ISO 13485 Quality Standard Harmonization:Unified manufacturing quality benchmarks across international supply chains reduce regulatory friction for pediatric orthopedic device exporters entering multiple jurisdictions.
- Telehealth Infrastructure Maturation:Virtual care platforms enable rural and suburban families to access pediatric sports medicine specialists without geographic proximity to major metropolitan hospital systems.
Market Restraints
- Pediatric-Specific Device R&D Cost Burden:Smaller addressable patient populations per anatomical variant raise unit economics for orthopedic manufacturers compared to adult-equivalent product development.
- Growth-Plate Sensitivity Technical Constraints:Biomechanical design requirements for skeletally immature patients limit material choices and complicate load-bearing device engineering.
- State-by-State Regulatory Fragmentation:Inconsistent return-to-play law stringency across United States jurisdictions creates compliance complexity for multi-state healthcare provider networks.
Strategic Opportunities
- Aftermarket Service Revenue Capture:Brace fitting, seasonal replacement cycles, and follow-up physiotherapy create recurring revenue streams beyond initial device sale.
- Electrical Stimulation Post-Surgical Protocols:Adolescent ACL reconstruction rehabilitation represents underpenetrated application for neuromuscular electrical stimulation devices.
- Retail Channel Direct-to-Consumer Expansion:Sports retail partnerships bypass traditional hospital procurement for non-prescriptive support products and thermal modalities.
Industry Challenges
- Pediatric Sports Medicine Specialist Shortage:Fellowship-trained clinician scarcity constrains clinic expansion capacity and extends patient wait times in high-demand metropolitan markets.
- Seasonal Demand Volatility Management:Fall football and spring soccer injury peaks create capacity utilization inefficiencies for fixed-cost rehabilitation facility networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Sports Injury Treatment Market |
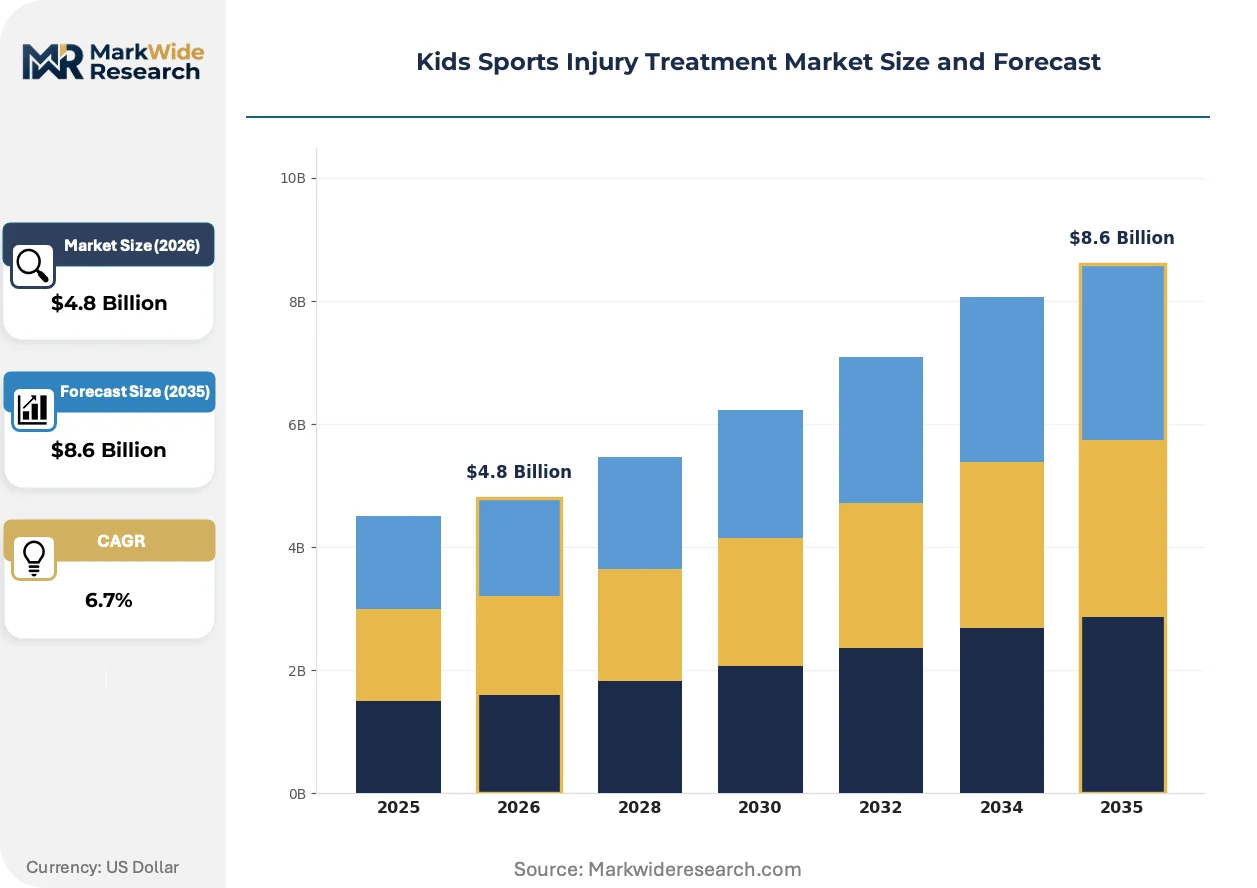
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Physiotherapy, Ice Packs, Compression Sleeves Delivery Mode: Home Care, Clinics, Hospitals, Telehealth End User: Athletes, Coaches, Parents, Trainers Technology: Cryotherapy, Ultrasound Therapy, Hydrotherapy, Electrical Stimulation |
| Companies Covered | Arthrex, Inc., Smith & Nephew plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., CONMED Corporation, Medtronic plc, Johnson & Johnson, Mueller Sports Medicine, Inc., Össur hf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Sports Injury Treatment Market Shifts & Advancements
Digital health integration and biomaterial advances are compressing treatment timelines while reshaping how orthopedic suppliers capture patient lifetime value through connected device ecosystems and predictive analytics platforms.
Wearable cryotherapy systems with embedded temperature sensors and mobile app connectivity are hybridizing acute injury management protocols. Youth athletic trainers in competitive high school programs are deploying these devices for real-time thermal monitoring. This convergence is hybridizing the traditional clinic-based cold therapy model into hybrid home-clinic care pathways that extend provider oversight beyond facility walls.
The FDA's pediatric device innovation pathway is accelerating review timelines for anatomically scaled orthopedic implants and bracing systems. Expedited clearance processes reduce time-to-market for youth-specific designs that address growth-plate proximity constraints. Pediatric sports medicine device manufacturers are prioritizing 510(k) submissions under this framework to outpace standard regulatory timelines.
Parental purchasing behavior is fragmenting across channel types based on injury severity and insurance coverage status. Families with high-deductible health plans increasingly self-direct to retail brace purchases for minor sprains, bypassing formal clinical evaluation. This bifurcation is most pronounced in suburban United States markets with dense sporting goods retail presence and limited pediatric specialist availability.
Kids Sports Injury Treatment Market Segmentation
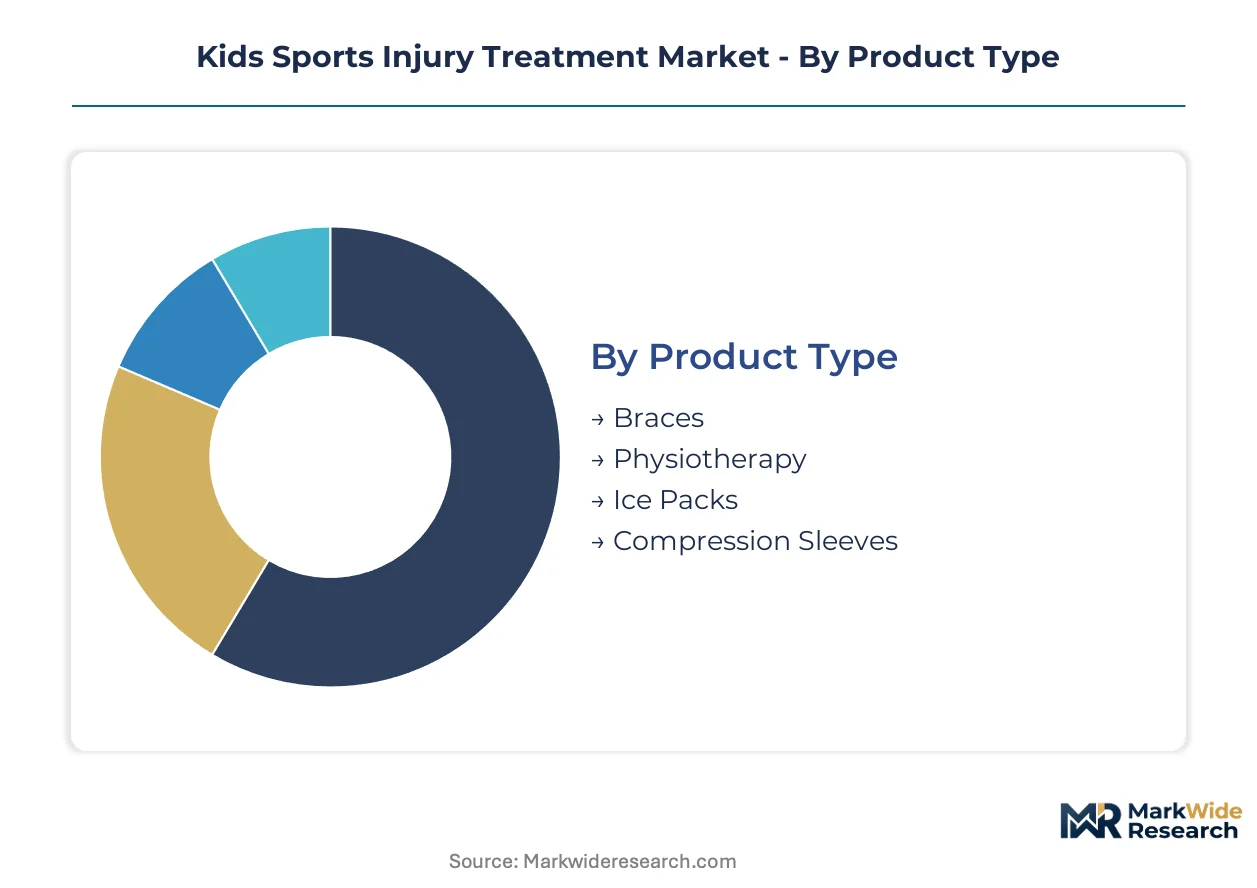
Pediatric sports injury treatment demands precise segmentation due to anatomical growth-plate sensitivity and age-variable rehabilitation protocols. Treatment modality selection varies sharply by injury severity, insurance coverage, and caregiver decision-making authority.
Product Type:
Mature segments dominate revenue concentration while emerging formats reshape purchase pathways.
- Braces:Anatomically scaled rigid and semi-rigid support devices engineered for skeletally immature joints with adjustable sizing systems. Demand concentrates in suburban United States school districts with competitive football and soccer programs, driven by seasonal replacement cycles and state-mandated return-to-play clearance requirements.
- Physiotherapy:Age-appropriate rehabilitation protocols incorporating modified dosing regimens for manual therapy, therapeutic exercise, and neuromuscular re-education. Pediatric sports medicine clinics in Texas and California anchor demand, constrained by fellowship-trained specialist scarcity that extends patient wait times.
- Ice Packs:Gel-based and instant-activation cold therapy products for acute injury management in home and sideline settings.
- Compression Sleeves:Elastic graduated compression garments for soft-tissue support and edema reduction in youth athletic populations.
Braces retain volume leadership; physiotherapy holds the steepest expansion curve.
Delivery Mode:
Channel selection bifurcates sharply by injury severity and parental insurance status.
- Telehealth:Virtual care platforms enabling remote consultation with pediatric sports specialists through synchronous video and asynchronous messaging. Rural and suburban families without geographic proximity to metropolitan hospital systems drive adoption, accelerated by state-level concussion mandate compliance requirements.
- Clinics:Outpatient pediatric sports medicine facilities delivering brace fitting, manual therapy, and return-to-play evaluation. Metropolitan markets in New York and California concentrate capacity, though specialist shortage constrains expansion.
- Home Care:Self-directed thermal modalities, over-the-counter bracing, and caregiver-administered rehabilitation protocols.
- Hospitals:Inpatient surgical repair procedures and post-operative rehabilitation for adolescent ACL reconstructions and growth-plate fractures.
Clinics retain volume leadership; telehealth is climbing the fastest.
End User:
Purchasing authority fragments across stakeholder types with divergent decision criteria.
- Parents:Primary decision-makers for minor injuries and retail product selection, increasingly self-directing to sports retail channels under high-deductible health plans.
- Athletes:Adolescent patients whose treatment adherence and return-to-play compliance determine protocol effectiveness.
- Trainers:Youth athletic trainers deploying wearable cryotherapy systems and acute injury assessment in competitive high school programs.
- Coaches:Authority figures responsible for initial injury recognition and mandatory concussion protocol activation under state law.
Parents retain volume leadership; trainers hold the steepest expansion curve.
Technology:
Modality selection follows acute-versus-chronic injury staging and surgical intervention status.
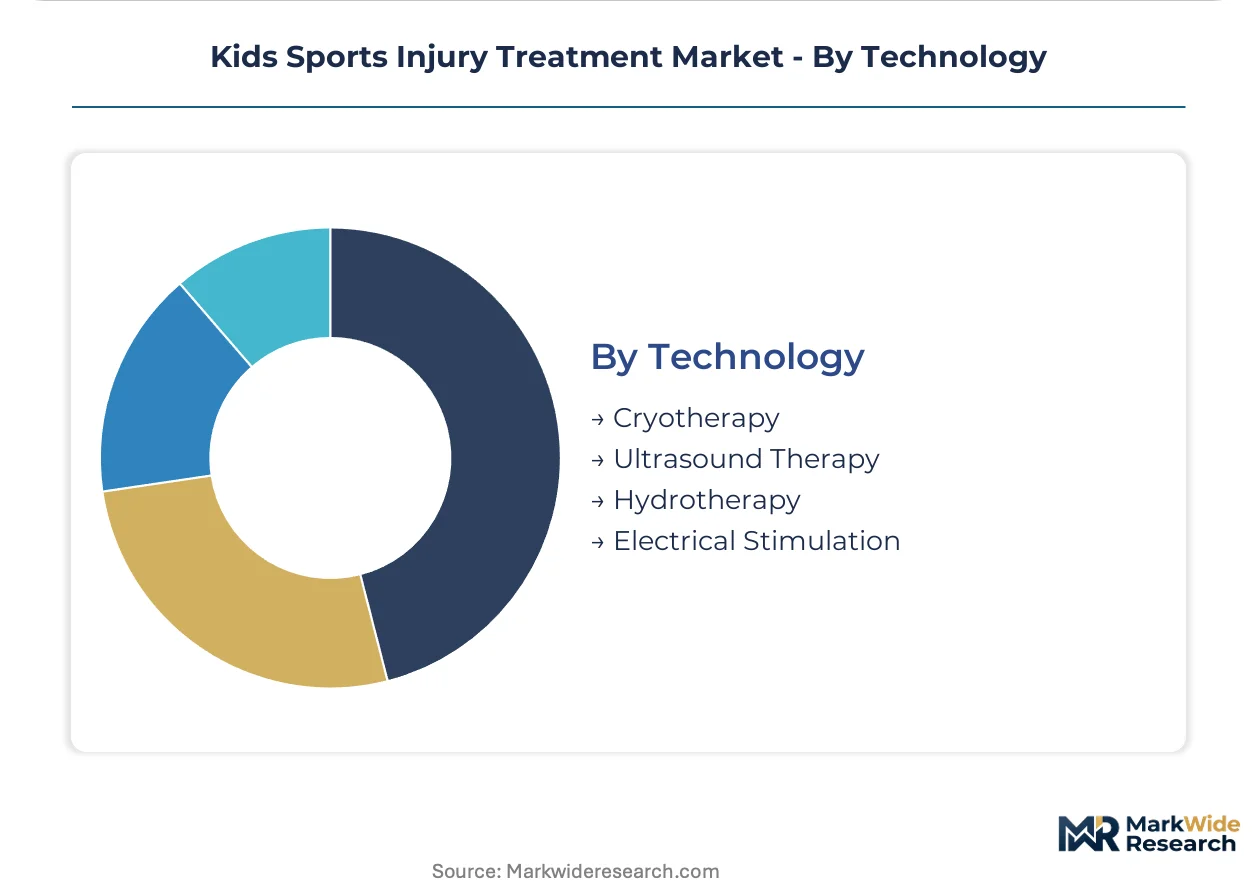
- Cryotherapy:Cold therapy systems including ice packs, cold compression devices, and wearable temperature-monitored wraps for acute inflammation management. Youth athletic trainers in competitive suburban programs deploy sensor-embedded systems with mobile connectivity for real-time thermal monitoring.
- Electrical Stimulation:Neuromuscular and transcutaneous electrical nerve stimulation devices for post-surgical rehabilitation. Adolescent ACL reconstruction protocols represent underpenetrated application, with orthopedic surgeons increasingly prescribing home-use units.
- Ultrasound Therapy:Therapeutic ultrasound for soft-tissue healing and deep thermal effects in clinical settings.
- Hydrotherapy:Aquatic rehabilitation and contrast bath protocols for low-impact conditioning of injured youth athletes.
Cryotherapy retains volume leadership; electrical stimulation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Families in the United States with high-deductible health plans self-direct to retail channels for minor injuries, while Germany's statutory insurance system channels virtually all cases through formal clinical pathways regardless of severity.
United States
School-based athletic programs in Texas and California sustain consistent injury treatment volume through mandated return-to-play protocols. The FDA's pediatric device innovation pathway accelerates 510(k) clearances for youth-specific orthopedic implants. Pediatric sports medicine clinics cluster in suburban Dallas-Fort Worth and Orange County, where fellowship-trained specialist scarcity extends patient wait times.
Germany
Statutory health insurance coverage eliminates out-of-pocket barriers to formal clinical evaluation for youth athletes. The country's national pharmaceutical regulator enforces MDR compliance for all pediatric orthopedic devices distributed across EU member states. Munich and Hamburg concentrate specialized pediatric sports medicine capacity within university hospital networks.
United Kingdom
NHS referral pathways channel adolescent athletes into formal physiotherapy and surgical evaluation for moderate-to-severe injuries. MHRA oversight aligns with EU MDR standards for pediatric device market authorization. London's Great Ormond Street Hospital and Birmingham Children's Hospital anchor specialized treatment capacity for complex growth-plate trauma.
Japan
Club-based youth sports systems in baseball and soccer generate predictable seasonal injury patterns for device manufacturers. PMDA review timelines for pediatric orthopedic products run longer than FDA equivalents, delaying market entry for foreign suppliers. Tokyo and Osaka metropolitan areas concentrate pediatric orthopedic surgical expertise within university-affiliated medical centers.
Australia
Private health insurance penetration in suburban markets drives demand for premium brace products and accelerated rehabilitation protocols. TGA classification rules for pediatric orthopedic devices mirror FDA risk-based frameworks with additional emphasis on biocompatibility testing. Sydney and Melbourne anchor specialized pediatric sports medicine networks serving competitive youth rugby and Australian rules football programs.
Kids Sports Injury Treatment Market Competitive Landscape
Hospital-system suppliers and retail-channel specialists split the market into distinct competitive arenas with minimal direct overlap. Large orthopedic conglomerates dominate inpatient surgical repair through integrated hospital procurement relationships, while consumer-facing brands capture outpatient brace and support product demand through sporting goods retail networks. Three archetypes define competitive positioning: integrated hospital suppliers, retail-channel consumer brands, and specialized pediatric device engineers. Dominant competitive moves include portfolio diversification into adjacent anatomical segments and strategic partnerships with youth athletic league organizations.
Among integrated hospital suppliers, Stryker Corporation and Zimmer Biomet Holdings occupy positions defined by scale-driven procurement relationships with metropolitan medical centers. Within the retail-channel tier, Mueller Sports Medicine exemplifies consumer-facing distribution through established sporting goods partnerships. Össur hf represents the specialized pediatric engineering archetype, with product development frameworks explicitly addressing growth-plate proximity constraints in skeletally immature patients.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Smith & Nephew plc |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| CONMED Corporation |
| Medtronic plc |
| Johnson & Johnson |
| Mueller Sports Medicine, Inc. |
| Össur hf |
| Others |
Supply & Pricing Matrix
Seasonal capacity utilization swings across suburban United States rehabilitation networks drive supplier pricing power and inventory positioning. Fall football and spring soccer injury peaks create underutilized fixed-cost infrastructure during off-seasons, forcing brace manufacturers and clinic operators to extract premium margins during high-demand windows to offset capacity inefficiencies.
Pricing Analysis
Aftermarket service revenue from brace fitting, seasonal replacement cycles, and follow-up physiotherapy drives lifetime value capture beyond initial device sales. Three-tier pricing structure across premium, standard, and economy levels segments buyers by insurance coverage status and injury severity, with high-deductible plan families self-directing to retail economy tiers. Pricing pressure stems from parental price sensitivity in suburban markets with dense sporting goods retail presence. Families with commercial insurance show lowest price sensitivity for clinic-based physiotherapy, while uninsured and high-deductible segments drive retail channel volume.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material cost volatility for neoprene, aluminum alloys, and injection-molded plastics used in brace manufacturing. Component sourcing concentrates in China, Mexico, and domestic United States facilities, with final assembly distributed across regional hubs to minimize logistics costs. Single-source vulnerability for pediatric-specific sizing mechanisms and adjustable strap systems creates supply continuity risk. Distribution runs through hospital procurement networks for surgical implants and sporting goods retail partnerships for consumer-facing support products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates on a cyclical recovery pattern tied to school-based athletic program enrollment and seasonal sports participation rates. District-level investment in competitive youth sports sustains injury treatment volume through economic fluctuations.
For Market Incumbents: Build regulatory moat through FDA pediatric device innovation pathway submissions for growth-plate-proximal implant designs. Secure exclusive hospital system partnerships in metropolitan markets with specialist scarcity to lock out competitors. Expand backward integration into adjustable sizing mechanism production to reduce single-source dependency. Prioritize telehealth platform development to capture rural patient volume before regional competitors establish virtual care infrastructure. For New Entrants and Emerging Players: Pursue white-space opportunity in electrical stimulation devices for adolescent ACL reconstruction rehabilitation, the fastest-expanding underpenetrated modality. Target suburban United States markets with limited pediatric sports medicine specialist availability where telehealth delivery can bypass geographic barriers. Establish direct-to-consumer sporting goods retail partnerships for thermal modalities and compression products, bypassing hospital procurement complexity entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telehealth infrastructure and connected cryotherapy device segments as platform economics mature. Long-term viability favors companies with recurring revenue streams from brace replacement cycles and physiotherapy protocols rather than one-time surgical implant sales. Acquisition targets should demonstrate established youth athletic league partnerships and FDA pediatric pathway clearance track records. Watch for inflection signals in state-level concussion mandate expansion beyond Texas, California, and New York into Midwestern jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric-Specific FDA 510(k) Submission | Expedited review under pediatric device innovation pathway accelerates commercialization timelines for growth-plate-proximal designs. |
| Youth Athletic League Partnership | Exclusive supplier agreements with competitive high school programs create captive demand for brace and cryotherapy products. |
| Telehealth Platform Integration | Virtual care infrastructure enables specialist access for rural families without metropolitan hospital proximity. |
| Retail Channel Expansion | Sporting goods partnerships bypass hospital procurement for non-prescriptive support products and thermal modalities. |
| Aftermarket Service Development | Brace fitting and follow-up physiotherapy protocols generate recurring revenue beyond initial device sale. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric sports medicine specialists, orthopedic device product managers, hospital purchasing committee members, and youth athletic trainers, and refined through secondary validation. Primary interviews with fellowship-trained clinicians in Texas, California, and New York captured treatment protocol evolution and return-to-play clearance practices. Secondary sources included FDA 510(k) clearance databases, state-level concussion mandate legislation records, hospital procurement contract filings, and GPO pricing benchmarks. Bottom-up demand modeling by product type and delivery mode was triangulated against top-down market sizing from manufacturer revenue disclosures.
Demand-supply balance across the projection horizon was assessed through capacity utilization analysis of pediatric sports medicine clinics and brace manufacturing throughput. Segmentation dimensions modeled include product type, delivery mode, end user, and technology modality, with geographic clustering by state-level regulatory environment. CAGRs were derived from historical volume trajectories and forward-looking enrollment projections for school-based athletic programs. Forecast inputs incorporated youth sports specialization trend data and telehealth reimbursement policy evolution.
Sensitivities concentrate around state-level mandate expansion timing, pediatric specialist fellowship graduation rates, and FDA pediatric pathway review pace. Forecasts reflect assumptions regarding sustained district-level athletic program investment and stable commercial insurance coverage patterns. Material shifts in youth sports participation rates, concussion litigation outcomes, or telehealth reimbursement parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Long Term Care Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Assisted Living Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
India Senior Living Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Aged Care Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Global Operating Room Management Market