
 US Surgical Staplers Market | 2026-2036
US Surgical Staplers Market Size, Share, and Industry Trends Forecast 2026-2036
US Surgical Staplers Market Analysis
Domestic instrument manufacturing capacity is restructuring as US-based producers scale automated assembly lines for disposable stapler cartridges. Medtronic leverages its broad hospital contracting network to sustain volume leadership in powered stapling platforms. Johnson & Johnson anchors its position through Ethicon's specialized focus on advanced polymer staple materials. Stryker competes by extending its surgical instruments portfolio into integrated stapling-shaver combinations for orthopedic applications.
Surgical staplers are mechanical devices that deploy rows of metal or polymer staples to approximate tissue or close surgical incisions, typically firing staples at depths between 1.0 mm and 2.5 mm depending on tissue thickness and application. These instruments serve the primary commercial purpose of reducing operative time and minimizing tissue trauma relative to conventional suturing in open and minimally invasive procedures. Powered staplers now lead capital expenditure decisions among US hospital procurement committees due to their ergonomic advantages in laparoscopic settings. Linear stapling technology dominates general surgery applications while circular stapling technology commands premium positioning in gastrointestinal anastomosis procedures.
FDA 510(k) premarket notification requirements and NHTSA-adjacent quality system regulations shape product development timelines and clinical validation burdens for US manufacturers. OSHA bloodborne pathogen standards and Joint Commission surgical safety protocols further influence disposable versus reusable stapler purchasing patterns. Stakeholders must monitor reimbursement coding shifts for outpatient stapling procedures and FDA guidance on biocompatible staple materials.
Market Dynamics
FDA 510(k) clearance pathways are compressing product development timelines while simultaneously elevating clinical validation burdens, forcing manufacturers to restructure R&D spend toward powered stapling platforms and disposable cartridge automation.
Growth Catalysts
- Minimally invasive surgery expansion:Laparoscopic and robotic-assisted procedures now dominate general surgery training curricula, creating pull-through demand for articulating staplers with enhanced maneuverability in confined anatomical spaces.
- OSHA bloodborne pathogen standards:Stringent workplace safety protocols are accelerating hospital conversions from reusable to disposable stapling systems, particularly in high-volume trauma centers.
- Texas hospital system consolidation:Integrated delivery networks across Dallas-Fort Worth and Houston are standardizing on single-vendor powered stapling platforms to secure volume pricing and simplify supply chain management.
Market Restraints
- Titanium staple raw material volatility:Price fluctuations in medical-grade titanium sponge are compressing margins on metal staple cartridges, particularly for manufacturers without long-term supply contracts.
- FDA 510(k) predicate device dependencies:Substantial equivalence requirements create regulatory friction for novel staple line reinforcement materials, extending time-to-market for polymer-based innovations.
- Advanced polymer substitution threat:Bioabsorbable tissue sealants and energy-based vessel sealing devices are capturing select use cases in bariatric and thoracic procedures.
Strategic Opportunities
- Florida ambulatory surgery center penetration:Outpatient facilities in Miami-Dade and Orange County remain underpenetrated for powered stapling platforms, presenting white space for leasing models.
- Integrated stapling-imaging convergence:Real-time tissue perfusion sensing combined with staple firing feedback loops represents an emerging premium tier distinct from commodity staplers.
- Joint Commission surgical safety mandates:New perioperative protocol requirements are creating procurement tailwinds for disposable systems with built-in staple line integrity indicators.
Industry Challenges
- Biocompatibility certification timelines:Novel staple materials face extended FDA biocompatibility testing protocols, stretching product development cycles beyond typical capital equipment planning horizons.
- Laparoscopic technique skill gaps:Community hospitals in secondary California markets report insufficient trained surgical staff to justify powered stapler capital expenditure, limiting addressable market expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Surgical Staplers Market |
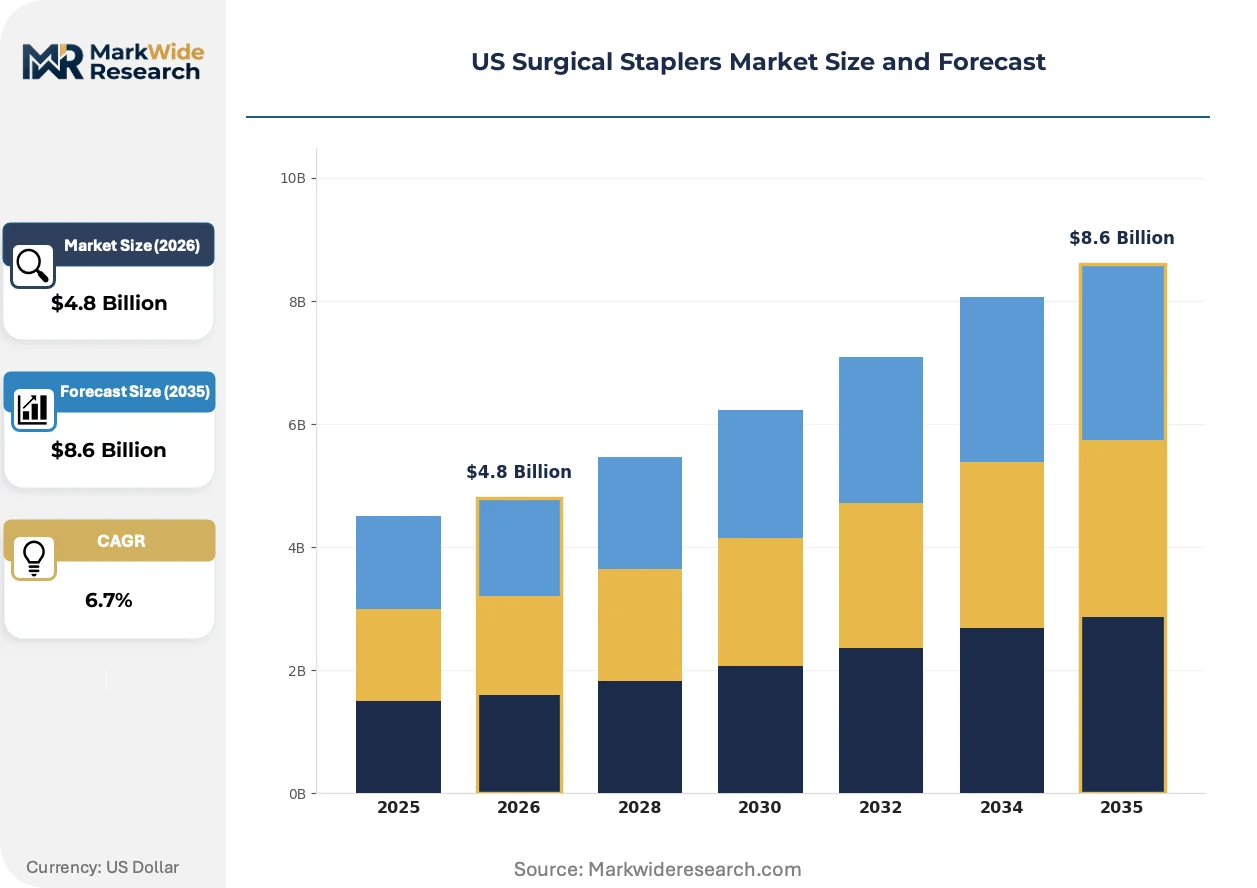
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Staplers, Powered Staplers, Circular Staplers, Skin Staplers Application: General Surgery, Cardiovascular Surgery, Gastrointestinal Surgery, Orthopedic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Gluing Technology, Linear Stapling Technology, Circular Stapling Technology, Endoscopic Techniques |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun, 3M, Smith & Nephew, CONMED Corporation, Intuitive Surgical, Stryker, Lexington Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Surgical Staplers Market Emerging Trajectories
Powered stapling technology is displacing manual platforms as the default specification in US hospital procurement, while regulatory pressure on staple line integrity and supply chain automation reshape competitive requirements.
Smart stapling systems with integrated tissue thickness sensing and adjustable firing speed are integrating machine learning algorithms to optimize staple formation across variable tissue densities. Academic medical centers in California and Massachusetts are piloting these platforms for complex colorectal resections. The technology is integrating predictive analytics to reduce leak rates and enable outcome-based contracting with payers.
FDA guidance on biocompatible staple materials is tightening validation requirements for polymer-based alternatives to conventional metal staples. Manufacturers must now submit extended wear testing data for implantable staple components. Orthopedic stapling applications face the most significant documentation burden, delaying product launches by twelve to eighteen months relative to general surgery platforms.
Hospital procurement committees are consolidating vendor relationships through multi-year enterprise agreements that bundle stapler hardware, disposable cartridges, and preventive maintenance. Ambulatory surgical centers in Texas and Florida are driving demand for flexible leasing structures with per-procedure consumable minimums. California integrated delivery networks are most advanced in negotiating outcome-based clauses tied to readmission rates for stapled anastomosis procedures.
US Surgical Staplers Market Segmentation
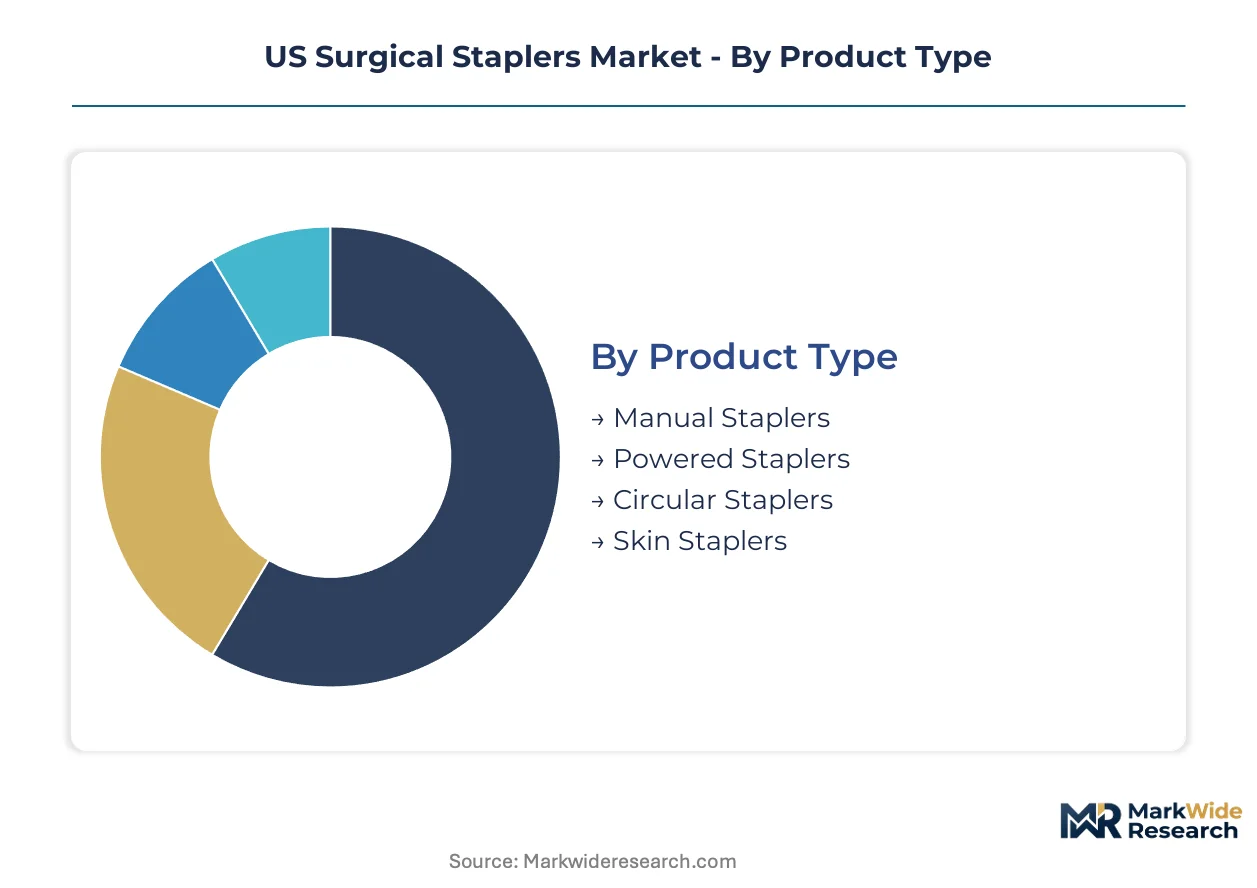
Product architecture in the US Surgical Staplers Market fragments across four distinct categories, each commanding separate procurement workflows and clinical validation requirements. Hospital systems and ambulatory facilities evaluate segments through divergent lenses: capital expenditure committees prioritize powered platforms while supply chain managers optimize disposable cartridge economics across manual alternatives.
Product Type:
Volume concentration favors manual platforms, yet premium positioning and procurement committee attention flow toward powered alternatives.
- Manual Staplers:Hand-actuated mechanical devices deliver staples through spring-loaded firing mechanisms without external power sources. Demand concentrates in ambulatory surgical centers across Florida and secondary California markets where capital budgets constrain powered platform acquisition. OSHA bloodborne pathogen compliance costs drive conversion to disposable manual cartridges in high-volume trauma settings.
- Powered Staplers:Battery or pneumatically actuated systems reduce hand fatigue and improve staple line consistency in laparoscopic procedures. Texas hospital systems in Dallas-Fort Worth and Houston standardize on these platforms through enterprise contracting, prioritizing ergonomic advantages during extended robotic-assisted cases. FDA 510(k) clearance pathways favor predicate device references from this established category.
- Circular Staplers:Anastomosis-specific instruments deploy rings of staples for gastrointestinal reconstruction procedures.
- Skin Staplers:Superficial wound closure devices utilizing simplified staple geometries for dermatological and trauma applications.
Today's leader: Powered Staplers. Tomorrow's challenger: Circular Staplers.
Application:
Procedure reimbursement rates and operative complexity determine segment profitability, with cardiovascular commanding premium positioning despite lower case volumes.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures generate the highest stapler utilization frequency across US hospital systems. Linear stapling technology dominates this segment, with demand clustering in California academic medical centers training residents on minimally invasive techniques. Joint Commission surgical safety protocols mandate disposable system adoption in teaching hospitals.
- Gastrointestinal Surgery:Colectomy, gastrectomy, and bariatric procedures require anastomosis integrity with leak rate minimization. Circular stapling technology commands premium positioning here, with Florida specialty centers driving adoption of integrated stapling-imaging convergence platforms. Outcome-based contracting with Medicare Advantage plans concentrates in this segment.
- Cardiovascular Surgery:Vessel anastomosis and sternal closure procedures utilize specialized staple geometries.
- Orthopedic Surgery:Soft tissue approximation in joint reconstruction and trauma fixation applications.
General Surgery delivers current volume dominance. Gastrointestinal Surgery offers the steepest expansion trajectory as bariatric procedure volumes climb.
End User:
Capital availability and procurement autonomy separate institutional buyers, with integrated delivery networks consolidating vendor relationships differently than independent facilities.
- Hospitals:Inpatient surgical departments with comprehensive service lines and capital equipment committees. Texas and California systems leverage volume pricing through multi-year enterprise agreements bundling hardware and consumables.
- Ambulatory Surgical Centers:Outpatient-focused facilities in Miami-Dade and Orange County present underpenetrated demand for powered platform leasing models with per-procedure minimums.
- Specialty Clinics:Procedure-focused settings with limited surgical volume and constrained capital budgets.
- Research Institutions:Academic medical centers piloting smart stapling systems with tissue perfusion sensing and machine learning feedback loops.
Hospitals anchor current purchasing power. Ambulatory Surgical Centers represent the fastest-climbing expansion opportunity as case migration accelerates.
Technology:
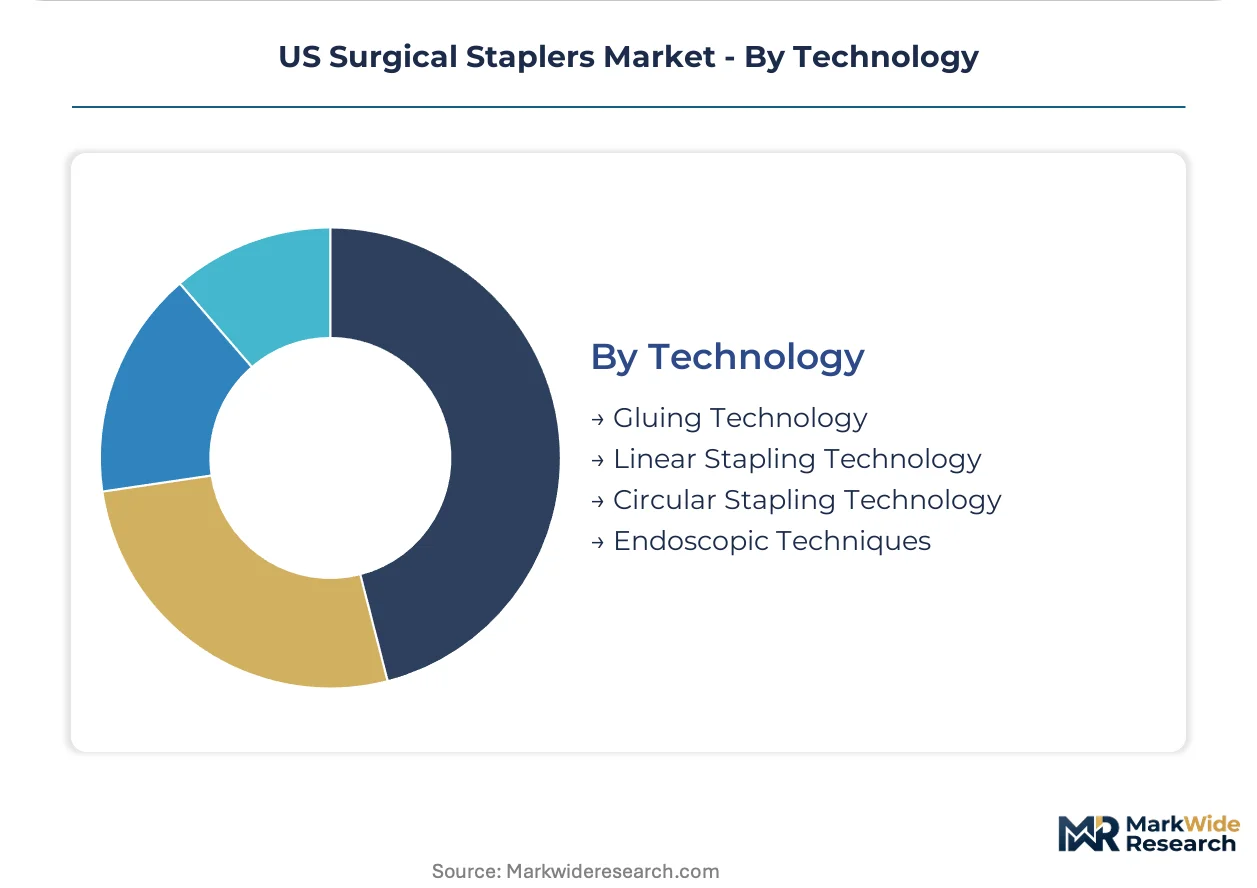
Staple formation mechanics and tissue interaction methods differentiate technical approaches, with linear platforms benefiting from standardization and circular systems from procedure-specific optimization.
- Linear Stapling Technology:Parallel staple rows for tissue transection and closure in general surgery applications. This mature platform dominates hospital procurement specifications, with automated cartridge assembly lines reducing per-unit costs for high-volume manufacturers.
- Circular Stapling Technology:Concentric staple deployment for anastomosis creation in gastrointestinal procedures. FDA biocompatibility testing requirements for implantable components extend validation timelines relative to linear alternatives.
- Endoscopic Techniques:Articulating delivery systems enabling stapler access through minimally invasive ports.
- Gluing Technology:Adjunctive tissue sealants competing for select use cases in vessel closure and staple line reinforcement.
Linear Stapling Technology holds installed base dominance. Endoscopic Techniques gain share fastest as laparoscopic training curricula expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in this market since FDA 510(k) pathways apply uniformly across domestic production, yet state-level Medicaid reimbursement variations and hospital system consolidation patterns create distinct demand clusters that reward localized supply chain positioning.
Texas
Dallas-Fort Worth and Houston integrated delivery networks are standardizing on single-vendor powered stapling platforms through enterprise agreements bundling hardware and consumables. OSHA bloodborne pathogen compliance costs accelerate disposable system conversions in high-volume trauma centers. San Antonio medical device distributors report strongest leasing model uptake for ambulatory surgery center penetration.
California
Academic medical centers in Los Angeles and the Bay Area pilot smart stapling systems with tissue perfusion sensing and machine learning feedback loops. FDA biocompatibility testing requirements for polymer-based alternatives extend validation timelines for Stanford and UCSF research partnerships. Central Valley community hospitals face capital constraints limiting powered platform adoption.
Florida
Miami-Dade and Orange County ambulatory surgical centers present underpenetrated demand for powered platform leasing with per-procedure minimums. Joint Commission surgical safety protocols drive disposable system procurement in Tampa and Jacksonville hospital systems. Orlando specialty centers lead adoption of integrated stapling-imaging convergence platforms for bariatric procedures.
Illinois
Chicago metropolitan hospital procurement committees prioritize ergonomic advantages of powered staplers during extended robotic-assisted cases. Medicare Advantage outcome-based contracting concentrates in gastrointestinal anastomosis procedures at Northwestern and University of Chicago facilities. Downstate secondary markets report insufficient trained surgical staff to justify capital expenditure.
Massachusetts
Greater Boston research institutions anchor pilot programs for predictive analytics reducing leak rates in complex colorectal resections. Massachusetts General and Brigham and Women's negotiate outcome-based clauses tied to readmission rates. FDA 510(k) predicate device dependencies create regulatory friction for novel staple line reinforcement materials emerging from local biomedical startups.
US Surgical Staplers Market Vendor Landscape
US producers anchor the premium tier through hospital contracting networks; European specialists hold positions in advanced materials. The market exhibits consolidated structure with three dominant platform providers controlling procurement committee specifications. Strategic archetypes include diversified medical technology conglomerates, specialized surgical instrument manufacturers, and robotic surgery platform integrators. Competitive moves center on multi-year enterprise agreements bundling hardware and consumables, plus backward integration into automated cartridge assembly.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson exemplify scale-driven positioning through broad hospital contracting networks and specialized polymer material focus respectively. Stryker occupies a position bridging orthopedic instrument portfolios with integrated stapling applications. Among specialized manufacturers, Intuitive Surgical represents the robotic surgery platform archetype, while CONMED Corporation and Smith & Nephew sit within the surgical instrument specialist tier. Lexington Medical anchors the mid-market segment with flexible leasing structures targeting ambulatory facility expansion.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun |
| 3M |
| Smith & Nephew |
| CONMED Corporation |
| Intuitive Surgical |
| Stryker |
| Lexington Medical |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up distributors consolidating regional medical device supply chains have tightened working capital discipline across US surgical stapler procurement, translating upstream cost compression into tiered contract structures that reward volume commitments with preferential cartridge pricing.
Pricing Analysis
Distributor margin layers absorb 15-25 points before hospital procurement committees negotiate final landed costs. Three-tier pricing structure across premium, standard, and economy levels separates powered platforms with smart sensing from manual disposable systems and commodity skin staplers. Cost compression in economy-tier manual cartridges is intensifying because automated assembly lines at Mexican maquiladora facilities reduced labor input costs. Ambulatory surgical centers in Florida exhibit highest price sensitivity, while California academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade titanium sponge suppliers concentrated in Kazakhstan, Ukraine, and Japan. Staple cartridge production draws from polymer resin feedstocks anchored in Texas Gulf Coast petrochemical complexes and precision-machined firing mechanisms sourced from Swiss and German toolmakers. Tariff exposure on Chinese-sourced surgical steel components creates margin volatility for manufacturers lacking alternative qualified suppliers. Distribution runs through specialized medical device distributors holding FDA establishment registrations and GPO contracting relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Surgical Staplers Market functions as a stable compounder, with minimally invasive procedure volume expansion providing predictable demand tailwinds regardless of macroeconomic cycles.
For Market Incumbents: Hedge titanium raw material exposure through long-term offtake agreements with Kazakh and Japanese sponge producers before price volatility compresses cartridge margins further. Deepen backward integration into automated polymer injection molding for disposable components to defend against emerging entrants with leaner cost structures. Prioritize R&D spend on staple line integrity sensing to maintain premium positioning as FDA validation requirements tighten. For New Entrants and Emerging Players: Capture ambulatory surgery center leasing opportunities in Miami-Dade and Orange County where incumbent powered platform penetration remains below 40 percent. Target Texas secondary markets outside Dallas-Fort Worth and Houston where hospital system consolidation has not yet locked in single-vendor enterprise agreements. Lead with flexible per-procedure consumable minimums rather than capital purchase models to lower customer acquisition friction. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market manual stapler specialists with underutilized FDA 510(k) predicate device libraries and established GPO relationships. Five-to-ten-year viability hinges on successful navigation of polymer-based staple material transitions as metal alternatives face biocompatibility scrutiny. Watch FDA guidance publication timelines on implantable staple wear testing as the signal for accelerated M&A activity among capital-constrained innovators.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Smart Stapling Platform | Accelerates hospital procurement committee approval for premium-tier powered systems with tissue sensing. |
| Hospital System Partnership with Outcome-Based Contracting | Aligns vendor economics with readmission rate performance for gastrointestinal anastomosis procedures. |
| Backward Integration into Automated Cartridge Assembly | Captures margin compression from titanium volatility while securing supply continuity for high-volume accounts. |
| Reimbursement Strategy for Ambulatory Stapling Procedures | Unlocks Medicare Advantage coverage expansion for outpatient bariatric and colorectal interventions. |
| Software Companion Development for Predictive Analytics | Enables machine learning feedback loops that reduce leak rates and differentiate from commodity staplers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and ambulatory surgery center administrators with secondary validation against FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement records, and OSHA compliance filings. Bottom-up demand modeling triangulated against top-down market sizing from trade association data.
Segment-weighting approaches distributed volume and value across the analysis window according to product type splits, application procedure frequencies, end-user capital availability tiers, and technology adoption curves. CAGRs derived from logistic diffusion modeling of powered platform replacement cycles and procedure volume elasticity to demographic aging patterns. Forecast inputs incorporated titanium price index trajectories and ambulatory surgery center construction permits.
FDA regulatory timeline delays, titanium supply disruption events, and ambulatory reimbursement coding shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about predicate device clearance pathways and hospital capital expenditure cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market