
 Retractable Needles Market | 2026-2036
Retractable Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Retractable Needles Market Outlook
Class II safety-engineered specifications is redrawing competitive boundaries in retractable needles. Becton, Dickinson and Company leverages its integrated manufacturing footprint across multiple continents to sustain supply security for high-volume hospital contracts. Retractable Technologies, Inc. anchors its position through dedicated specialization in automatic retraction mechanisms, while Terumo Corporation differentiates via precision-engineered Japanese manufacturing standards that command premium positioning in developed markets.
Retractable needles incorporate spring-loaded or friction-based mechanisms that withdraw the cannula into a sealed barrel immediately after use, typically constructed from medical-grade stainless steel and polypropylene housings designed to eliminate post-injection sharps exposure. Their primary purpose is preventing needlestick injuries among healthcare workers during blood sampling, vaccination, and drug delivery procedures. Safety needles currently dominate volume shipments due to universal precautions mandates, while auto-injector systems capture disproportionate margin pools as biologics administration expands in home care settings. Electronic retraction technology represents the fastest-growing segment despite higher unit costs, driven by patient self-injection trends and reduced training requirements.
FDA 510(k) clearance pathways and OSHA enforcement of the Bloodborne Pathogens Standard directly shape product development timelines and hospital purchasing criteria in the United States, while the EU Medical Device Regulation imposes additional clinical evidence requirements for safety mechanisms marketed across Europe. Stakeholders must monitor evolving harmonization between ISO 23908 sharps protection standards and national needlestick prevention laws to anticipate certification burdens and procurement specification shifts.
Market Dynamics
Hospital procurement departments now mandate automatic retraction mechanisms as standard equipment, converting what was once premium positioning into baseline compliance. This regulatory-driven specification shift compresses margins for conventional safety needles while rewarding manufacturers with validated 510(k) clearance pathways and ISO 23908 certification.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Enforcement actions against healthcare facilities using non-engineered sharps accelerate replacement cycles across United States hospital systems.
- Home care settings:Patient self-injection of biologics creates demand for single-use auto-retractable devices with intuitive activation mechanisms.
- Medical-grade stainless steel sourcing:Vertically integrated manufacturers in Germany secure cannula supply chains against raw material volatility.
Market Restraints
- Polypropylene resin costs:Housing material price swings compress per-unit margins for high-volume disposable manufacturers.
- Spring mechanism precision:Tolerance requirements below 50 microns limit qualified supplier pools to specialized metal-forming operations in Japan and Switzerland.
- EU MDR clinical evidence:Additional safety mechanism validation studies extend time-to-market by 12-18 months for new retractable designs.
Strategic Opportunities
- Veterinary medicine:Companion animal vaccination protocols represent an underpenetrated channel with lower regulatory barriers than human applications.
- Needle-free jet injector convergence:Hybrid devices combining liquid jet propulsion with retractable shielding address needle phobia in pediatric and cosmetic dermatology segments.
- India PLI scheme:Domestic manufacturing incentives for medical devices reduce import dependency for safety-engineered injection equipment.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies create bottlenecks for material substitutions in housing polymers.
- Legacy sterilization infrastructure:Ethylene oxide capacity constraints force manufacturers to validate gamma or electron beam alternatives for spring-loaded assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retractable Needles Market |
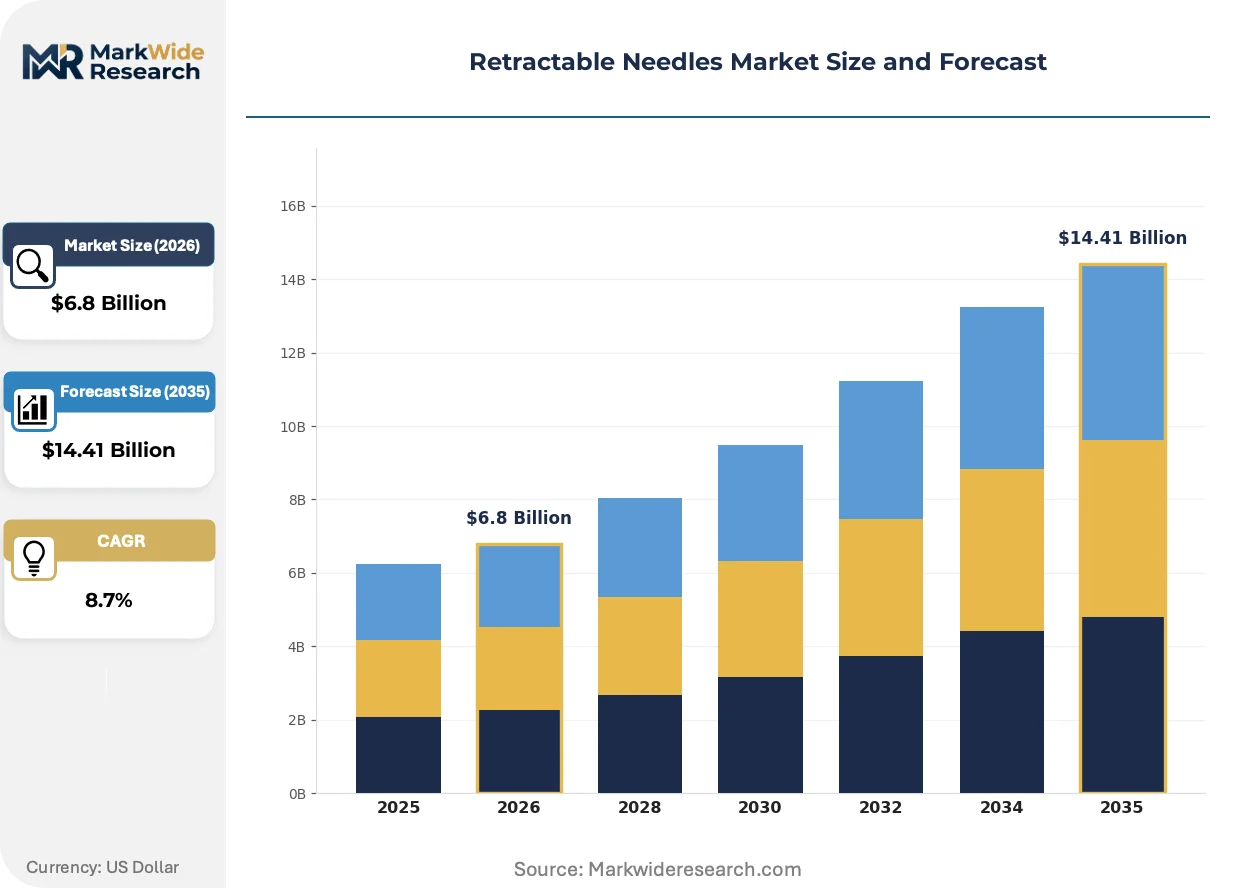
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Needles, Auto-Injectors, Syringe Systems, Catheters End User: Hospitals, Clinics, Home Care, Research Labs Technology: Mechanical, Electronic, Hybrid, Manual Application: Vaccination, Blood Sampling, Drug Delivery, Infusion Therapy |
| Companies Covered | Becton, Dickinson and Company, Retractable Technologies, Inc., Terumo Corporation, Medtronic plc, Nipro Corporation, Smiths Medical, DMC Medical Limited, Numedico Technologies Pty Ltd, SOL-Millennium Medical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retractable Needles Market Strategic Shifts
Electronic activation systems are displacing purely mechanical retraction across premium device tiers, altering how manufacturers allocate R&D resources and which competencies they prioritize in hiring.
Spring-loaded passive retraction is fragmenting the safety needle category into distinct performance tiers. Ambulatory surgery centers adopt mid-range friction-based mechanisms for cost containment, while academic medical centers specify electronic sensors that confirm full cannula withdrawal. This technology divergence forces suppliers to maintain multiple platform architectures rather than consolidating around a single design standard.
The EU Medical Device Regulation imposes post-market surveillance obligations on safety mechanism failures that exceed previous vigilance reporting thresholds. Manufacturers must now fund clinical follow-up studies tracking needlestick injury rates in real-world use, not just simulated testing. German and French notified bodies interpret MDR Annex I general safety requirements most stringently, creating certification friction for devices cleared under earlier directives.
Consolidated purchasing by United States group purchasing organizations concentrates contract awards among suppliers offering standardized safety-engineered portfolios across multiple injection modalities. Independent hospitals and smaller health systems lose negotiating leverage as Premier and Vizient centralize retractable needle specifications into sole-source agreements. This buyer concentration is most visible in the Southeast and Midwest regions where hospital network mergers have accelerated since 2020.
Retractable Needles Market Segmentation
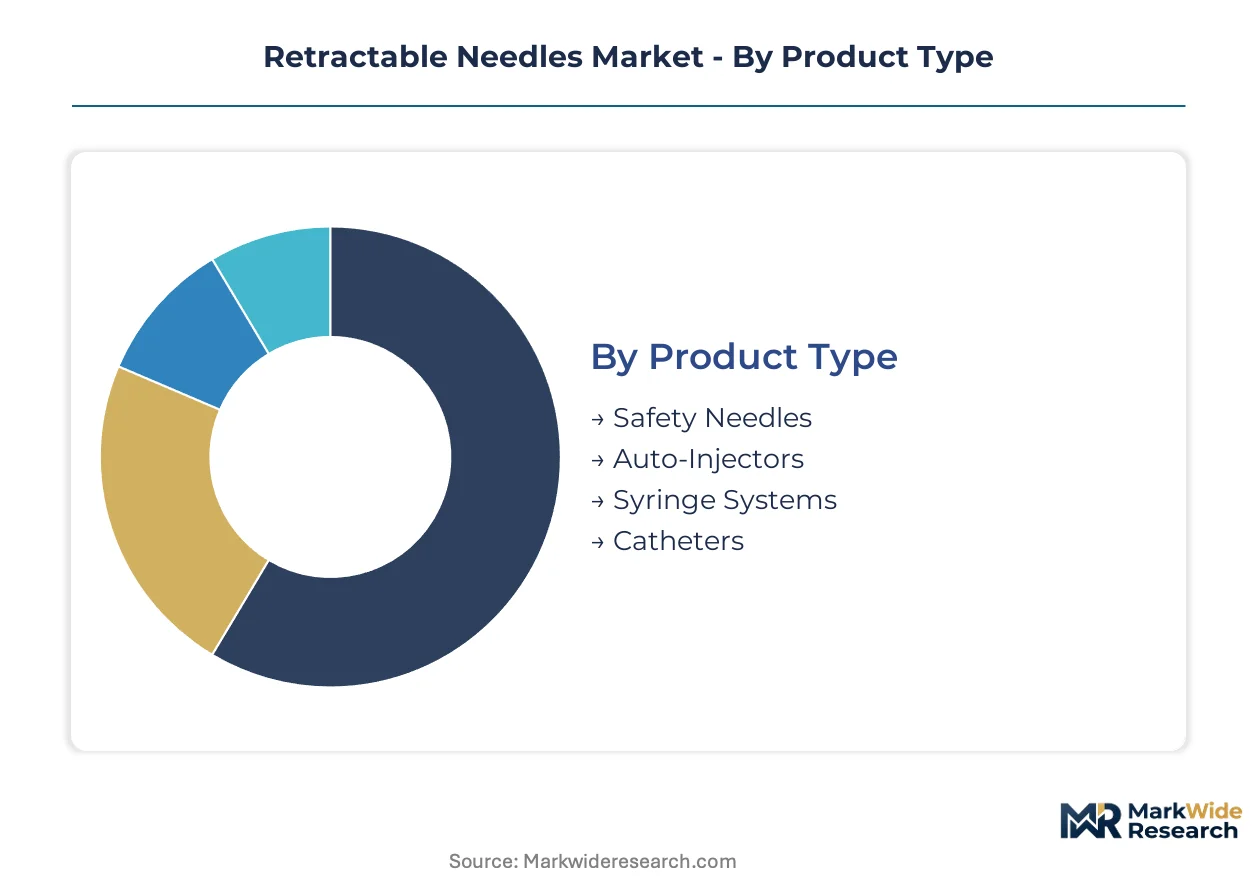
Retractable needles fragment across four distinct classification axes, each carrying different certification burdens and margin profiles. Product type and technology selections determine FDA 510(k) pathway complexity, while end-user and application segments dictate volume scale and pricing power.
Product Type:
FDA Class II designation intensity varies by mechanism complexity, with passive safety features commanding streamlined review versus active electronic systems requiring extended clinical validation.
- Safety Needles:Spring-loaded or friction-based cannula withdrawal mechanisms constructed from medical-grade stainless steel and polypropylene housings. Hospital procurement departments in the United States mandate these as baseline equipment under OSHA Bloodborne Pathogens Standard enforcement, converting premium positioning into compliance-driven volume.
- Auto-Injectors:Pre-filled drug delivery platforms integrating automatic retraction with dose completion sensors. Biologics administration in home care settings drives specification, with patient self-injection protocols requiring intuitive activation mechanisms that reduce training overhead.
- Syringe Systems:Integrated barrel-and-needle configurations with built-in retraction.
- Catheters:Vascular access devices incorporating retractable introducer needles.
Established volume favors Safety Needles; emerging adoption favors Auto-Injectors.
End User:
Procurement concentration shapes margin structure, with consolidated purchasing by United States group purchasing organizations compressing prices for high-volume hospital contracts while fragmented home care channels sustain premium positioning.
- Hospitals:Academic medical centers and integrated delivery networks specifying electronic sensor confirmation of full cannula withdrawal. Premier and Vizient sole-source agreements concentrate contract awards among suppliers offering standardized safety-engineered portfolios.
- Home Care:Patient-directed administration of biologics and chronic disease therapies. Intuitive activation mechanisms reduce training requirements for non-clinical users, with electronic retraction technology climbing the fastest in this channel.
- Clinics:Ambulatory surgery centers adopting mid-range friction-based mechanisms for cost containment.
- Research Labs:Preclinical and clinical trial supply with specialized sterility requirements.
Contract scale favors Hospitals; margin expansion favors Home Care.
Technology:
Manufacturing tolerance requirements stratify supplier qualification, with sub-50-micron precision limiting qualified metal-forming operations to specialized facilities in Japan and Switzerland.
- Electronic:Sensor-activated retraction with dose completion confirmation. Patient self-injection trends and reduced training requirements drive specification, though biocompatibility testing timelines for housing polymers create development bottlenecks.
- Mechanical:Spring-loaded passive withdrawal without electronic components. Mature supply chains and validated sterilization pathways sustain cost competitiveness for high-volume disposable production.
- Hybrid:Combined mechanical backup with electronic monitoring.
- Manual:User-activated retraction requiring deliberate thumb or finger motion.
Cost efficiency favors Mechanical; functionality integration favors Electronic.
Application:
Procedure-specific injury risk profiles determine regulatory scrutiny intensity, with bloodborne pathogen exposure potential driving specification mandates for high-risk interventions.
- Vaccination:Mass immunization campaigns requiring single-use auto-retractable devices. WHO prequalification pathways and national immunization program procurement shape competitive access in developing markets.
- Drug Delivery:Biologics administration with viscosity and volume constraints. Home care migration for chronic disease management creates demand for patient-friendly activation mechanisms.
- Blood Sampling:Phlebotomy procedures with highest needlestick injury incidence.
- Infusion Therapy:Extended dwell vascular access with retractable introducer requirements.
Procurement scale favors Vaccination; complexity premium favors Drug Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered retractable needle assemblies to United States hospital systems under long-term supply agreements, while Japanese fabricators supply cannula components to European safety device assemblers.
United States
OSHA Bloodborne Pathogens Standard enforcement accelerates replacement cycles across hospital systems. The FDA's 510(k) clearance pathway shapes product development timelines for safety-engineered devices. Manufacturing clusters in New Jersey and Illinois concentrate sterile assembly operations for high-volume disposable production.
Germany
Vertically integrated manufacturers secure medical-grade stainless steel cannula supply chains against raw material volatility. The EU Medical Device Regulation imposes additional clinical evidence requirements for safety mechanisms. Industrial concentrations in Baden-Württemberg and Bavaria host precision metal-forming operations serving European hospital procurement networks.
Japan
Sub-50-micron tolerance requirements limit qualified spring mechanism suppliers to specialized metal-forming facilities. METI industrial standards and PMDA device approvals govern domestic manufacturing quality protocols. Nagoya-based fabrication clusters supply precision-engineered components to developed market safety device manufacturers.
India
Domestic manufacturing incentives under the PLI scheme reduce import dependency for safety-engineered injection equipment. CDSCO medical device regulations align with ISO 23908 sharps protection standards for market entry. Gujarat and Maharashtra industrial corridors attract contract manufacturing investments from multinational device companies.
China
NMPA regulatory harmonization with international standards accelerates domestic safety device certification timelines. Provincial manufacturing zones in Jiangsu and Zhejiang scale polypropylene housing production for cost-competitive disposable assemblies. Export flows concentrate toward Southeast Asian and Middle Eastern healthcare procurement markets.
Retractable Needles Market Competitive Environment
Listed leaders compete with private specialists across regulatory clearance capabilities and manufacturing scale. The vendor base stratifies into three performance tiers based on FDA 510(k) validation depth and ISO 23908 certification status. Strategic archetypes include integrated multinationals with captive cannula supply, dedicated safety device specialists, and regional contract manufacturers serving procurement intermediaries. Dominant competitive moves encompass backward integration into medical-grade steel sourcing and technology licensing partnerships for electronic retraction systems.
Among integrated multinationals, Becton, Dickinson and Company and Terumo Corporation occupy positions exemplifying scale-driven supply security for high-volume hospital contracts. Retractable Technologies, Inc. represents the dedicated specialist archetype, anchoring competitive positioning through focused automatic retraction mechanism development. These three entities collectively illustrate how regulatory validation depth and manufacturing geography stratify market access across United States, European, and Japanese procurement channels.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Retractable Technologies, Inc. |
| Terumo Corporation |
| Medtronic plc |
| Nipro Corporation |
| Smiths Medical |
| DMC Medical Limited |
| Numedico Technologies Pty Ltd |
| SOL-Millennium Medical Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day cannula inventory buffers at German stainless steel mills translate directly into pricing leverage for retractable needle assemblers, concentrating margin power among manufacturers with captive medical-grade steel supply while forcing spot-market buyers into volatile polypropylene hedging strategies.
Pricing Analysis
Hospital procurement departments anchor pricing stratification across three performance tiers: electronic sensor-equipped devices command ISO 23908 premium certification, mechanical spring systems occupy standard positioning, and friction-based alternatives serve economy contracts. Price differentiation hinges on FDA 510(k) validation depth and cannula tolerance grade, with sub-50-micron precision commanding substantial premiums. Cost compression in the mechanical tier is intensifying because Premier and Vizient sole-source agreements consolidate volume awards among dual-certified suppliers. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize electronic confirmation features regardless of unit cost.
Supply Chain Analysis
Ninety-day cannula inventory buffers reflect structural concentration across Germany, Japan, and Switzerland, where specialized metal-forming operations control spring mechanism fabrication. Raw material flows draw from medical-grade stainless steel melt shops in Baden-Württemberg, polypropylene resin complexes in the US Gulf Coast, and precision wire drawing facilities in Nagoya. Single-source vulnerability concentrates in Japanese spring component suppliers, with earthquake exposure creating catastrophic disruption risk. Distribution runs through group purchasing organization central warehouses in the United States and regional hospital procurement hubs in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified spring mechanism engineering talent pools have contracted to fewer than a dozen specialized facilities worldwide, creating asymmetric returns for manufacturers that secure backward integration into cannula production or electronic retraction IP.
For Market Incumbents: Secure captive medical-grade stainless steel supply through long-term offtake agreements with German melt shops, insulating margin structures from raw material volatility. Accelerate FDA 510(k) pathway investments for electronic retraction platforms before EU MDR clinical evidence requirements harden certification barriers against late entrants. For New Entrants and Emerging Players: CDSCO fast-track pathways under India's PLI scheme offer expedited market entry for safety-engineered devices targeting domestic immunization programs. Veterinary medicine channels present underpenetrated white space with lower regulatory burden than human applications, enabling revenue base establishment before tackling FDA validation complexity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underutilized retractable needle divisions lacking standalone scale. Five-to-ten year viability favors specialists with validated ISO 23908 certification and existing GPO contract relationships. Monitor OSHA enforcement action intensity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cannula Production | Captive medical-grade stainless steel supply secures margin insulation against German mill pricing volatility. |
| FDA 510(k) Electronic Retraction Submission | Sensor-activated platforms command Premier contract tiering above mechanical safety alternatives. |
| EU MDR Clinical Evidence Investment | Annex I general safety validation enables continued access to German and French hospital procurement networks. |
| Veterinary Medicine Channel Entry | Companion animal vaccination protocols offer lower regulatory barrier path to manufacturing scale validation. |
| India PLI Manufacturing Localization | Domestic production incentives reduce import dependency for CDSCO-registered safety device distribution. |
Study Parameters
Operator-level perspectives from hospital procurement managers, GPO contracts specialists, biomedical engineers, and sterile supply directors anchored the qualitative base. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, OSHA enforcement databases, EU MDR notified body guidance documents, and hospital supply chain expenditure records. Bottom-up shipment estimates by product type and technology tier triangulated against top-down hospital procurement budget allocations across the analysis window.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios, raw material price bands, and GPO contract renewal cycles. Segmentation modeling incorporated product type, technology mechanism, end-user channel, and application procedure dimensions. CAGRs derived from hospital capital equipment replacement cycles, home care biologics administration growth patterns, and vaccination campaign procurement schedules. Spring mechanism precision requirements and sterilization infrastructure capacity constraints fed industry-specific boundary conditions.
Underlying assumptions cover OSHA enforcement continuity, EU MDR harmonization stability, and medical-grade steel supply chain integrity, with deviation risk concentrated in tariff exposure for Japanese precision components and ethylene oxide sterilization capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market