
 Laparoscopic Power Morcellators Market | 2026-2036
Laparoscopic Power Morcellators Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Power Morcellators Market Intelligence
FDA safety communications on tissue dissemination risk is repositioning the competitive landscape for power morcellation devices. Medtronic leverages its integrated surgical ecosystem to sustain premium positioning across hospital procurement channels. Karl Storz GmbH anchors its presence through rigid endoscope-to-morcellator workflow control. Richard Wolf GmbH specializes in compact pneumatic systems that navigate space constraints in ambulatory settings.
Laparoscopic power morcellators are motorized surgical instruments designed to fragment and extract tissue specimens through small abdominal incisions, typically operating at rotational speeds between 800 and 1,500 RPM with integrated aspiration and irrigation ports. These devices serve the primary purpose of enabling minimally invasive removal of large tissue masses—most commonly uterine fibroids or renal specimens—without requiring open laparotomy. Disposable morcellators command expanding share as hospitals prioritize single-use blades and containment systems to mitigate cross-contamination liability. Electric technology leads absolute volume while robotic-assisted morcellation represents the fastest-growing configuration, concentrated in tertiary academic centers with existing da Vinci platform investments. Gynecological surgery remains the dominant application segment, though urological morcellation for nephrectomy specimens is gaining procedural share.
FDA, EMA, and Japan's PMDA each enforce distinct containment and labeling requirements that directly shape product development timelines and market access costs. The FDA's 2014 boxed warning and subsequent containment bag mandate forced redesign cycles across all major manufacturers, while EMA's MDR compliance deadlines are now filtering smaller participants from European tenders. Stakeholders must monitor evolving reimbursement coding for contained morcellation versus open extraction, as payer policy will determine whether premium device costs translate into sustainable margin capture.
Market Dynamics
Containment bag mandates from the FDA and EMA are forcing device redesign cycles that favor disposable configurations over reusable systems, compressing margins for manufacturers while elevating compliance costs across all hospital procurement channels.
Growth Catalysts
- Minimally invasive surgery volumes:Rising laparoscopic hysterectomy and myomectomy procedures in tertiary hospitals drive morcellator utilization. Gynecological surgical suites now specify power morcellation as standard of care for fibroid extraction.
- MDR compliance deadlines:EMA's Medical Device Regulation certification requirements filter smaller competitors from European tenders. Surviving manufacturers capture expanded market access across German, French, and Italian hospital networks.
- Robotic surgical platform proliferation:Academic medical centers with existing da Vinci investments integrate robotic-assisted morcellation into nephrectomy workflows. This convergence expands addressable procedure volumes beyond traditional gynecology.
Market Restraints
- Single-use blade cost inflation:Disposable morcellator tips and containment bags impose per-procedure costs exceeding reusable alternatives. Hospital materials management departments resist premium pricing amid constrained capital budgets.
- Tissue dissemination liability exposure:FDA's 2014 boxed warning on leiomyosarcoma seeding risk elevated malpractice insurance premiums for surgeons performing uncontained morcellation. Defensive practice patterns suppress procedure volumes in community hospitals.
- Specialized technician scarcity:Certified biomedical engineers capable of servicing pneumatic and electric morcellator systems concentrate in metropolitan medical device clusters. Rural facilities face extended equipment downtime.
Strategic Opportunities
- Ambulatory surgical center penetration:Compact pneumatic morcellators suit space-constrained outpatient settings where procedure economics favor same-day discharge. Manufacturers targeting ASCs gain volume outside hospital purchasing committees.
- Urological specimen extraction:Laparoscopic nephrectomy and partial nephrectomy create incremental demand for renal tissue morcellation. Urology service lines represent faster procedure growth than mature gynecological applications.
- Japan PMDA containment pathway:Japan's pharmaceutical and medical device agency advances distinct premarket approval standards for contained morcellation systems. Early entrants secure preferential reimbursement positioning in Tokyo and Osaka academic centers.
Industry Challenges
- Containment bag integration complexity:Surgical teams require extended training to deploy specimen isolation systems without compromising visualization or prolonging operative time. Learning curve variability affects adoption consistency.
- Cross-functional sterile processing coordination:Reusable morcellator components demand specialized cleaning protocols distinct from standard laparoscopic instruments. Central sterile supply departments struggle with workflow segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Power Morcellators Market |
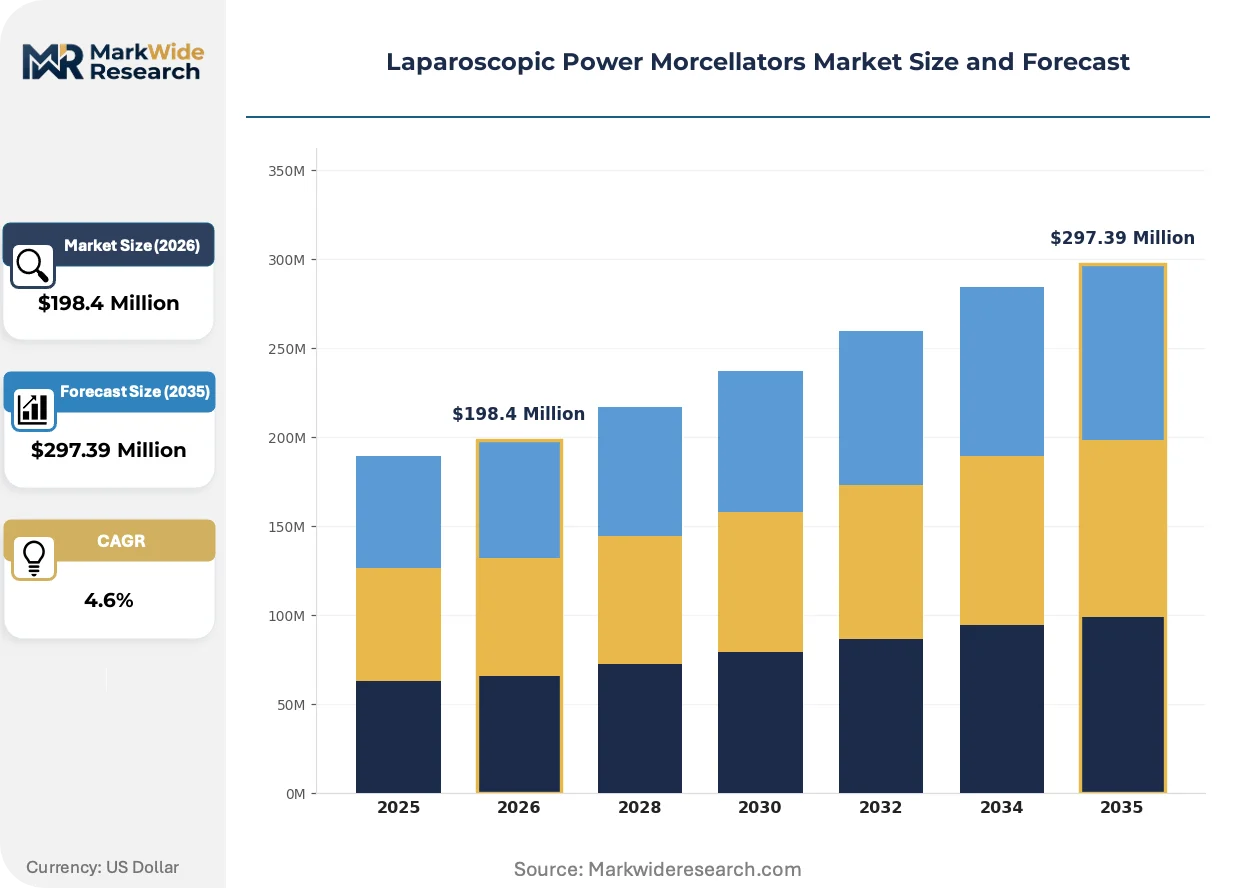
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $297.39 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Morcellators, Single-Port Morcellators, Disposable Morcellators, Battery-Powered Morcellators End User: Hospitals, Ambulatory Surgical Centers, Specialized Clinics, Research Institutions Technology: Electric, Pneumatic, Mechanical, Robotic Application: Gynecological Surgery, Urological Surgery, Gastrointestinal Surgery, Oncological Surgery |
| Companies Covered | Medtronic, Olympus Corporation, Karl Storz GmbH, Richard Wolf GmbH, Johnson & Johnson Services, Inc., Stryker Corporation, LiNA Medical, Lumenis, Nouvag AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Power Morcellators Market Strategic Shifts & Innovations
Device architecture is converging around integrated aspiration-irrigation-morcellation platforms that reduce instrument exchanges and operative time. This unification is compressing the competitive set toward full-procedure ecosystem vendors.
Electric morcellation systems with embedded torque sensors and automatic blade retraction are unifying tissue fragmentation with real-time safety monitoring. Tertiary academic medical centers in the United States and Germany adopt these configurations fastest. The technology is unifying previously separate safety and cutting functions into single-handpiece designs that command premium positioning.
EMA's MDR Annex XVI expansion on reusable surgical instruments is tightening biocompatibility and cleaning validation requirements for morcellator components. Manufacturers face extended notified body review timelines for legacy reusable systems. The regulation is accelerating portfolio pivots toward single-use configurations in European tenders.
Hospital value analysis committees now bundle morcellator procurement with containment system contracts and surgeon training commitments. Traditional device-only purchasing is yielding to integrated service agreements spanning capital equipment, disposables, and competency certification. This restructuring is most visible in United States integrated delivery networks consolidating vendor relationships.
Laparoscopic Power Morcellators Market Segmentation
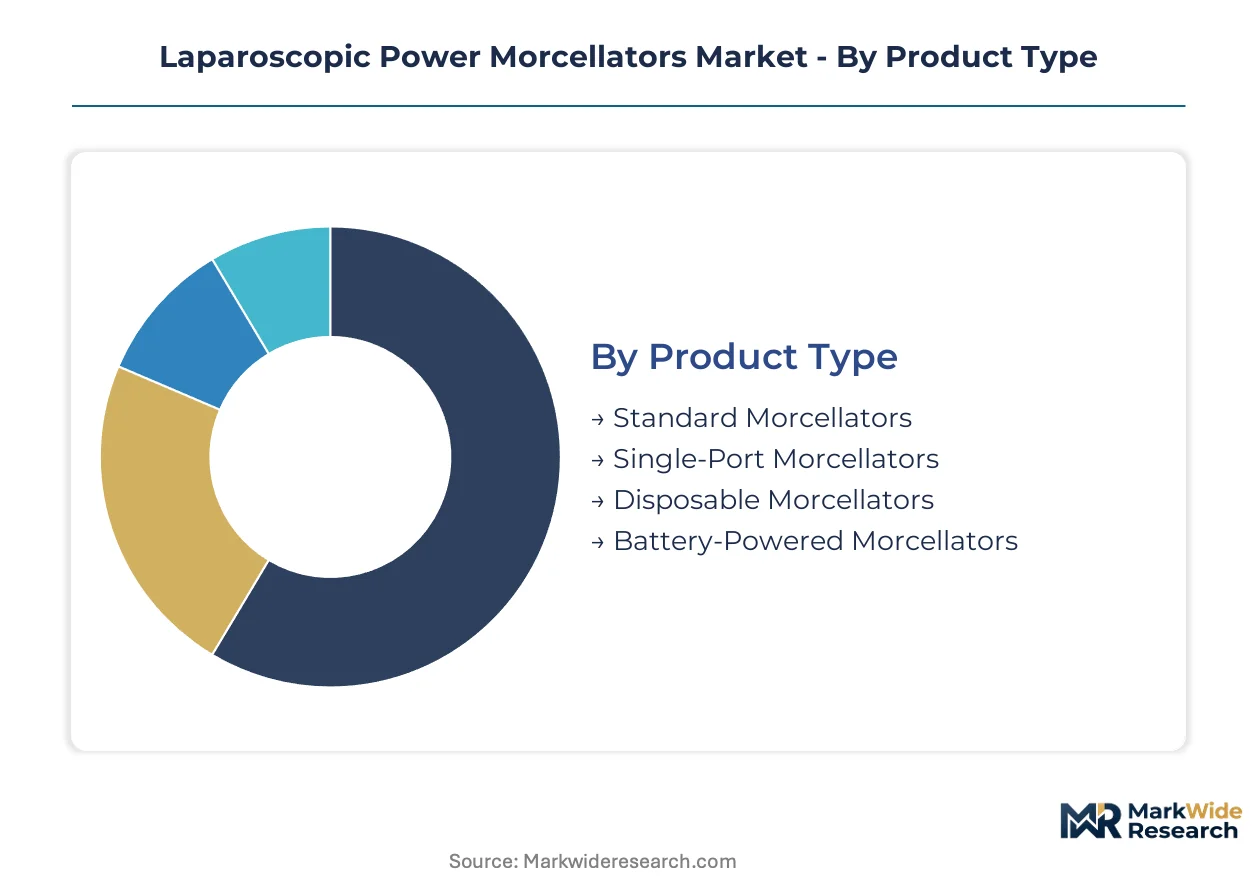
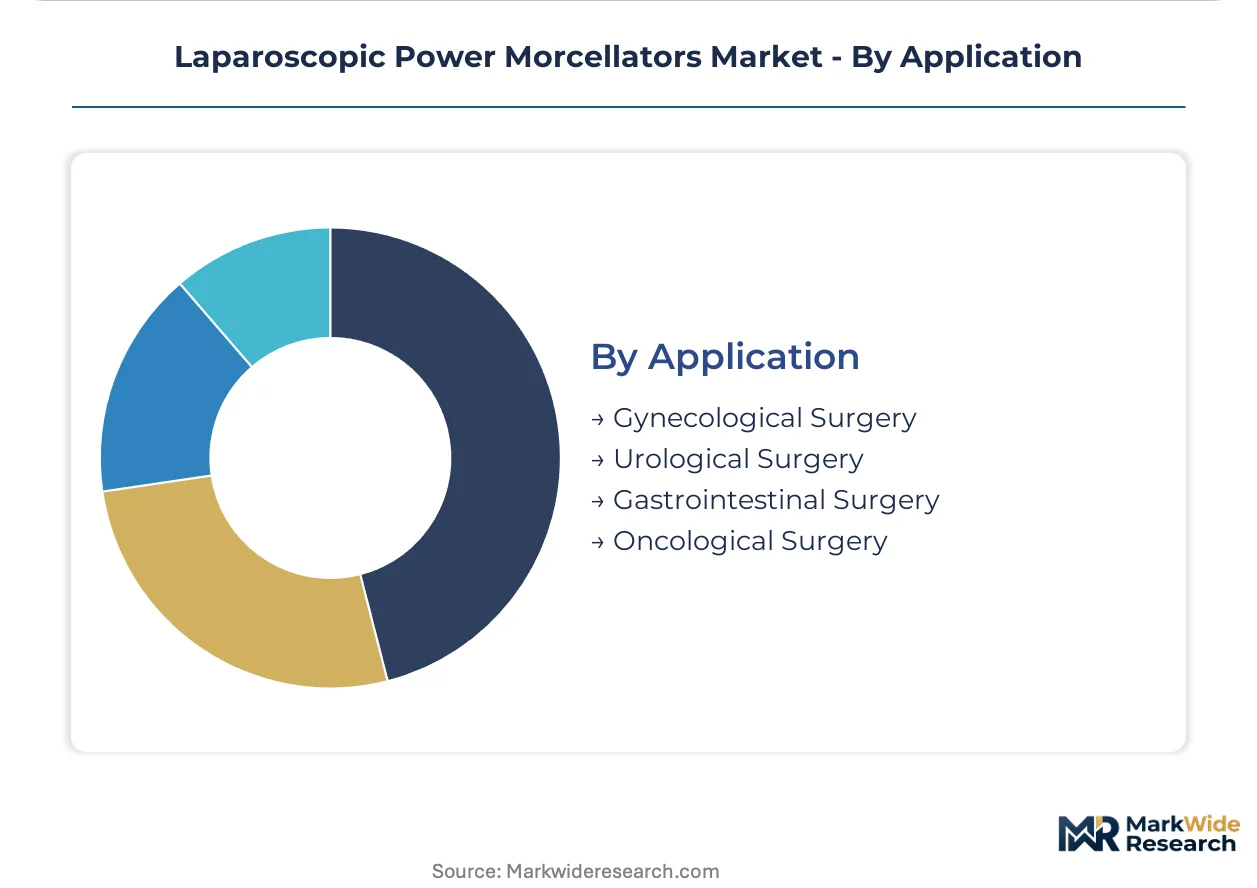
Device architecture and procurement patterns fragment the Laparoscopic Power Morcellators Market across four intersecting dimensions. Each segmentation axis reveals distinct margin structures, regulatory exposure profiles, and competitive entry barriers that determine manufacturer positioning.
Product Type:
Customization intensity varies sharply across this category, from commoditized standard units to highly specialized single-port configurations tailored to narrow procedural workflows.
- Disposable Morcellators:Single-use blade-and-handpiece systems eliminate cross-contamination liability and sterilization validation burdens. Hospital materials management departments in the United States and Germany prioritize these configurations following FDA containment bag mandates, accepting 40-60% per-procedure cost premiums over reusable alternatives.
- Single-Port Morcellators:Compact instruments designed for umbilical or single-incision laparoscopy reduce abdominal wall trauma and improve cosmesis. Demand concentrates in tertiary academic centers performing advanced minimally invasive gynecological procedures where patient-reported outcomes drive technology selection.
- Standard Morcellators:Reusable electric and pneumatic systems with detachable cutting tips serve high-volume hospital surgical suites. These devices require dedicated sterile processing protocols and biomedical engineering support.
- Battery-Powered Morcellators:Cordless handheld units suit ambulatory settings with limited infrastructure. Portability trades off against torque consistency and aspiration integration.
Most installed capacity flows through Standard Morcellators. Expansion is steepest in Disposable Morcellators.
End User:
Procurement authority and reimbursement economics diverge materially across this customer spectrum, from centralized hospital value analysis committees to autonomous ASC physician-owners.
- Hospitals:Integrated delivery networks and academic medical centers command volume pricing leverage and mandate containment system bundling. Capital equipment purchasing cycles extend 18-24 months with extensive clinical evaluation protocols.
- Ambulatory Surgical Centers:Outpatient facilities prioritize compact pneumatic systems and disposable configurations that minimize sterilization infrastructure. Procedure economics favor same-day discharge, driving demand for efficient tissue extraction.
- Specialized Clinics:Gynecology-focused practices perform office-based hysteroscopic and limited laparoscopic procedures. Equipment decisions align with individual surgeon preferences rather than institutional protocols.
- Research Institutions:Academic laboratories and medical device incubators utilize morcellators for preclinical testing and prototype validation. Volume remains minimal but influences early technology adoption curves.
Procurement volume concentrates in Hospitals. Margin capture is highest in Ambulatory Surgical Centers.
Technology:
Power delivery mechanisms segment by precision control, maintenance burden, and integration potential with robotic surgical platforms.
- Electric:Mains-powered systems with variable speed control and integrated aspiration dominate procedural volume. Torque sensors and automatic blade retraction now embed directly into handpiece designs.
- Robotic:da Vinci-compatible morcellation attachments enable tissue extraction through robotic ports. Academic centers with existing platform investments drive adoption, though capital requirements limit penetration.
- Pneumatic:Compressed gas-powered units offer lighter handpieces and simpler maintenance profiles. These systems navigate space constraints in ambulatory settings where electrical infrastructure is limited.
- Mechanical:Manual tissue fragmentation devices without motorized components serve backup and low-resource environments. Clinical utilization has declined sharply with power morcellator standardization.
Installed base dominance rests with Electric systems. Robotic configurations are climbing the fastest.
Application:
Procedural volume and tissue characteristics dictate morcellator specification requirements across surgical specialties.
- Gynecological Surgery:Laparoscopic hysterectomy and myomectomy for uterine fibroids constitute the foundational application segment. Containment system mandates have reshaped device standards specifically for this indication.
- Urological Surgery:Nephrectomy and partial nephrectomy specimen extraction represent the fastest-expanding procedural category. Renal tissue morcellation demands distinct blade geometries and aspiration calibration.
- Gastrointestinal Surgery:Splenectomy and colectomy applications utilize morcellators for specimen extraction through small incisions. Volume remains constrained by open surgery persistence in complex oncological resections.
- Oncological Surgery:Contained morcellation for suspected malignancies operates under heightened regulatory scrutiny. Defensive practice patterns suppress utilization pending definitive histopathology.
Procedure volume concentrates in Gynecological Surgery. Volume expansion is steepest in Urological Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power morcellation technology originated in German surgical instrument workshops during the 1990s, with early pneumatic systems developed for minimally invasive gynecological procedures. The technique subsequently migrated to United States academic medical centers, where electric morcellation became standardized for laparoscopic hysterectomy. Contemporary demand concentrates in three regulatory jurisdictions with divergent containment requirements.
United States
Tertiary academic medical centers in Boston, New York, and Cleveland drive procedural volume for contained morcellation systems. FDA's 2014 boxed warning and subsequent containment bag mandate forced device redesign cycles across all installed equipment. The Cleveland Clinic and Mayo Clinic surgical networks now specify disposable configurations with integrated specimen isolation for all laparoscopic myomectomy procedures.
Germany
Baden-Württemberg and Bavaria host the densest concentration of morcellator manufacturing capability and surgical utilization. EMA's MDR compliance deadlines filter smaller competitors from hospital tenders, consolidating procurement around notified body-certified systems. The Tübingen and Munich university hospital networks anchor European clinical evaluation protocols for next-generation electric morcellators with embedded torque sensing.
Japan
Tokyo and Osaka academic centers generate premium demand for robotic-assisted morcellation integrated with existing da Vinci platform investments. PMDA advances distinct premarket approval standards for contained morcellation systems that exceed FDA equivalence requirements. Keio University Hospital and Osaka University Hospital serve as national reference sites for surgeon training certification.
United Kingdom
London and Manchester integrated care systems negotiate centralized procurement contracts for disposable morcellator configurations. MHRA alignment with EMA MDR requirements compresses timelines for novel device introduction compared to standalone national pathways. The Royal College of Obstetricians and Gynaecologists maintains active surveillance registries tracking contained morcellation outcomes across NHS surgical networks.
France
Paris and Lyon university hospital clusters specialize in urological morcellation applications for nephrectomy specimen extraction. ANSM enforces containment system labeling requirements that parallel EMA standards with additional post-market surveillance obligations. The Assistance Publique-Hôpitaux de Paris network coordinates multicenter studies on operative time reduction with integrated aspiration-morcellation platforms.
Laparoscopic Power Morcellators Market Key Industry Players
The competitive structure tilts toward diversified surgical ecosystem vendors with integrated endoscope-to-morcellator workflow control. Three archetypes occupy distinct positions: full-procedure platform vendors bundling capital equipment with disposable contracts; specialized pneumatic system manufacturers targeting ambulatory constraints; and robotic surgical platform integrators leveraging existing da Vinci installations. Dominant competitive moves include portfolio diversification into containment systems and strategic partnerships with academic medical centers for clinical validation.
Among diversified surgical ecosystem vendors, Medtronic, Karl Storz GmbH, and Johnson & Johnson Services, Inc. represent the archetype of integrated workflow control. Medtronic exemplifies the full-procedure platform approach through its surgical ecosystem bundling. Karl Storz GmbH anchors the German-origin instrument manufacturing tradition with endoscope-to-morcellator integration. Johnson & Johnson Services, Inc. occupies a position spanning disposable suture portfolios through capital equipment linkages. Olympus Corporation and Stryker Corporation sit within adjacent surgical visualization and instrument categories with morcellator adjacencies. Richard Wolf GmbH represents the specialized pneumatic system archetype targeting space-constrained settings. LiNA Medical and Nouvag AG exemplify mid-scale European manufacturers with focused gynecological specialization.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| Karl Storz GmbH |
| Richard Wolf GmbH |
| Johnson & Johnson Services, Inc. |
| Stryker Corporation |
| LiNA Medical |
| Lumenis |
| Nouvag AG |
| Others |
Cost & Logistics Intelligence
Certified biomedical engineers capable of servicing pneumatic and electric morcellator systems concentrate in metropolitan medical device clusters across Baden-Württemberg, Massachusetts, and Tokyo. Labor-cost differentials between these specialized technician pools and general biomedical staff drive pricing-tier spreads of 25-40% across service contract bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with premium tiers capturing integrated containment-morcellation platforms and economy tiers covering standalone reusable handpieces. Price differentiation rests on FDA containment certification status and bundled training commitments. Cost compression in economy tiers is intensifying because hospital materials management departments resist per-procedure disposable premiums amid constrained capital budgets. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with existing robotic platform investments demonstrate lowest sensitivity to capital equipment premiums.
Supply Chain Analysis
Direct-to-hospital contracting channels handle high-volume integrated delivery network demand, while specialty distributors serve ambulatory surgical centers with limited procurement infrastructure. Manufacturing concentration rests on Germany, the United States, and Japan for precision-machined handpiece components and torque sensor assemblies. Component dependencies draw from medical-grade stainless steel forgings, brushless DC motors, and silicone containment bag polymers. Single-source vulnerability concentrates in specialized torque sensor suppliers serving embedded safety monitoring systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA's 2014 boxed warning and subsequent containment bag mandates created structural demand for redesigned device architectures. Compliance-driven replacement cycles now dominate capital equipment purchasing.
For Market Incumbents: Acquire containment system intellectual property to complete integrated platform offerings. Consolidate around notified body-certified manufacturing capabilities ahead of EMA MDR filtering effects. Defensive positioning requires backward integration into disposable blade production to capture margin compression from single-use mandates.
For New Entrants and Emerging Players: Enter via compact pneumatic configurations purpose-built for space-constrained ambulatory surgical centers. Target urological specimen extraction applications where procedure growth outpaces mature gynecological segments. White-space availability concentrates in Japan's PMDA premarket approval pathway for contained systems exceeding FDA equivalence standards.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European manufacturers with focused gynecological specialization and limited MDR transition resources. Long-term viability framing favors platforms with robotic surgical integration capabilities and established academic medical center validation partnerships. The signal to watch is reimbursement coding separation between contained morcellation and open extraction procedures.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) pathway for torque-sensing electric morcellators accelerates hospital procurement in United States academic centers. |
| CE Marking Pathway | MDR Annex XVI compliance for reusable components filters competitor set from European hospital tenders. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic network specifications establish national reference site status for device validation. |
| Software Companion Development | Embedded blade retraction algorithms unify safety monitoring with tissue fragmentation in single-handpiece designs. |
| Reimbursement Strategy | Contained morcellation coding separation from open extraction determines premium device cost recovery sustainability. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee directors, biomedical engineering supervisors, GPO contracts managers, and sterile processing department heads combined with secondary validation from FDA 510(k) filings, EMA notified body certification databases, hospital procurement records, and CMS Medicare procedure coding data. Triangulation across these sources established installed base estimates and replacement cycle timelines.
Input-output matrices map morcellator unit shipments against laparoscopic procedure volumes across gynecological, urological, gastrointestinal, and oncological applications. Segmentation dimensions span product architecture, end-user facility type, power delivery technology, and surgical specialty. CAGRs were derived from procedure volume growth trajectories moderated by regulatory compliance-driven replacement elasticity and containment system adoption curves.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time ambulatory surgical center purchasing records introduce uncertainty bands around outpatient facility penetration estimates. Forecasts reflect assumptions regarding MDR compliance timelines, PMDA premarket approval pacing, and reimbursement coding evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Global Dental Surgical Instruments Market