
 Global Surgical Scalpel Market | 2026-2036
Global Surgical Scalpel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Scalpel Market Foresight
Hospital procurement consortiums is reshaping how surgical scalpel suppliers secure volume contracts in developed markets. B. Braun Melsungen AG leverages its sterilization infrastructure to anchor long-term agreements with integrated delivery networks. Medtronic plc competes through powered and electrosurgical platforms that command premium positioning in cardiac and orthopedic suites. Aspen Surgical Products Inc. specializes in disposable safety-engineered blades that address needlestick prevention mandates.
A surgical scalpel is a precision cutting instrument comprising a detachable blade and handle, manufactured from carbon steel or stainless steel with Rockwell hardness typically exceeding 50 HRC, designed to incise tissue with minimal trauma during operative procedures. Disposable scalpels dominate unit volume due to infection control protocols, while powered and ultrasonic variants capture disproportionate margin pools in specialized applications. Electrosurgical technology leads revenue contribution in cardiovascular procedures, whereas manual blades sustain ubiquity across general surgery and emerging market facilities.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern blade biocompatibility, sterility assurance, and single-use labeling, directly shaping product development timelines and market access costs. ISO 13485 quality management systems and CE marking requirements further stratify competitive capability between multinational manufacturers and regional suppliers. Stakeholders must monitor reimbursement shifts toward outpatient settings and evolving material standards for blade coatings and handle polymers.
Market Dynamics
Hospital procurement consortiums and ambulatory surgical center consolidation are compressing supplier margins while elevating sterility and traceability requirements across disposable and powered scalpel categories.
Growth Catalysts
- EU MDR traceability mandates:Sterility assurance and single-use labeling requirements are accelerating hospital conversion from reusable to disposable blade systems.
- Outpatient migration:Ambulatory surgical centers in Germany and the United States are expanding volume procurement of safety-engineered disposable variants.
- Powered platform adoption:Electrosurgical and ultrasonic technologies are capturing premium positioning in cardiac and orthopedic procedure suites.
Market Restraints
- High-grade steel cost volatility:Carbon and stainless steel input prices fluctuate with energy costs, compressing blade manufacturer margins.
- Supply concentration in German sterilization infrastructure:Integrated delivery networks depend on limited third-party sterilization capacity for reusable handle systems.
- FDA 510(k) pathway friction:Biocompatibility documentation requirements extend product development timelines by 12-18 months for novel coatings.
Strategic Opportunities
- Japan's aging surgical workforce:Ergonomic powered handles and reduced-force incision technologies address repetitive strain injury prevention in extended procedures.
- Coating convergence with antimicrobial polymers:Blade surface treatments combining triclosan alternatives with hydrophobic layers create differentiation in infection-sensitive applications.
- Direct-to-facility distribution:Bypassing traditional medical-surgical distributors allows manufacturers to capture service revenue from blade inventory management.
Industry Challenges
- ISO 13485 certification backlog:Quality management system audits face 6-9 month delays at notified bodies, stalling CE marking for new blade geometries.
- Legacy handle compatibility:Standardized blade-to-handle interfaces constrain innovation in attachment mechanisms without obsoleting hospital inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Scalpel Market |
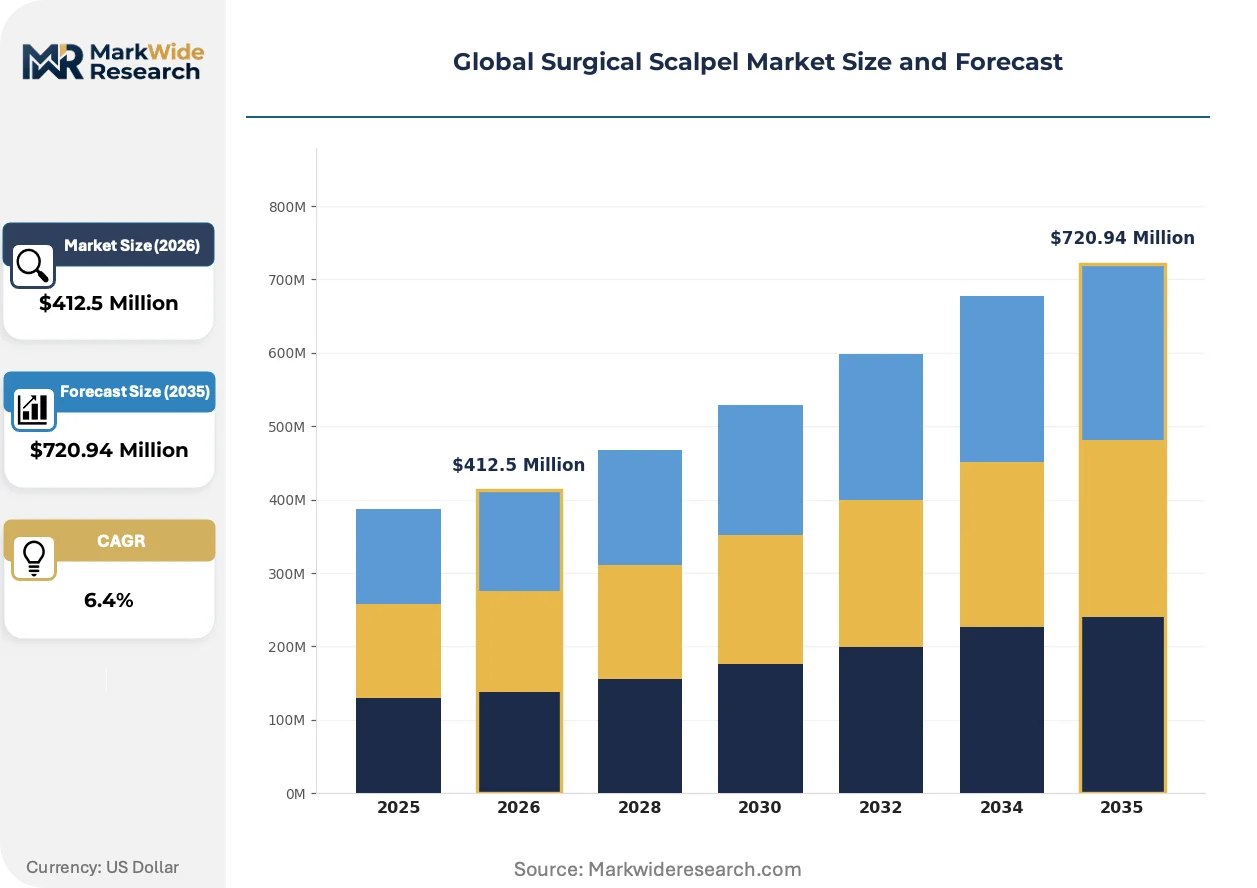
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Scalpel, Reusable Scalpel, Powered Scalpel, Laser Scalpel, Ultrasonic Scalpel Technology: Manual Blade, Electrosurgical, Ultrasonic Cutting, Laser Assisted, Plasma Scalpel Application: General Surgery, Orthopedic Surgery, Neurosurgery, Plastic Surgery, Cardiovascular Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialized Clinics, Research Institutes |
| Companies Covered | Swann-Morton Limited, B. Braun Melsungen AG, Aspen Surgical Products Inc., Hill-Rom Holdings Inc., Feather Safety Razor Co. Ltd., Kai Corp., Becton Dickinson and Co., Medtronic plc, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Scalpel Market Shifts & Advancements
Blade manufacturing is pivoting toward material science advances and regulatory-driven traceability systems that reshape competitive positioning across manual and powered categories.
Ultrasonic scalpel technology is migrating from open hepatic resection into laparoscopic general surgery applications. Academic medical centers in the United States are piloting these platforms for cholecystectomy and appendectomy procedures. The shift is compressing addressable market share for conventional electrosurgical units in mid-tier hospital systems.
EU MDR Unique Device Identification requirements are forcing blade manufacturers to implement laser-etched lot codes and digital traceability databases. The regulation mandates 10-year record retention for implantable-adjacent cutting instruments. German and French hospitals are prioritizing suppliers with pre-integrated serialization systems in 2024 procurement cycles.
Consolidated buying organizations are unbundling blade supply from procedure kit contracts. Integrated delivery networks in Japan and the United States now negotiate standalone blade agreements with volume-tier pricing indexed to ambulatory surgery center case growth. This disintermediation pressures traditional distributor margins while rewarding manufacturers with direct logistics capabilities.
Global Surgical Scalpel Market Segmentation
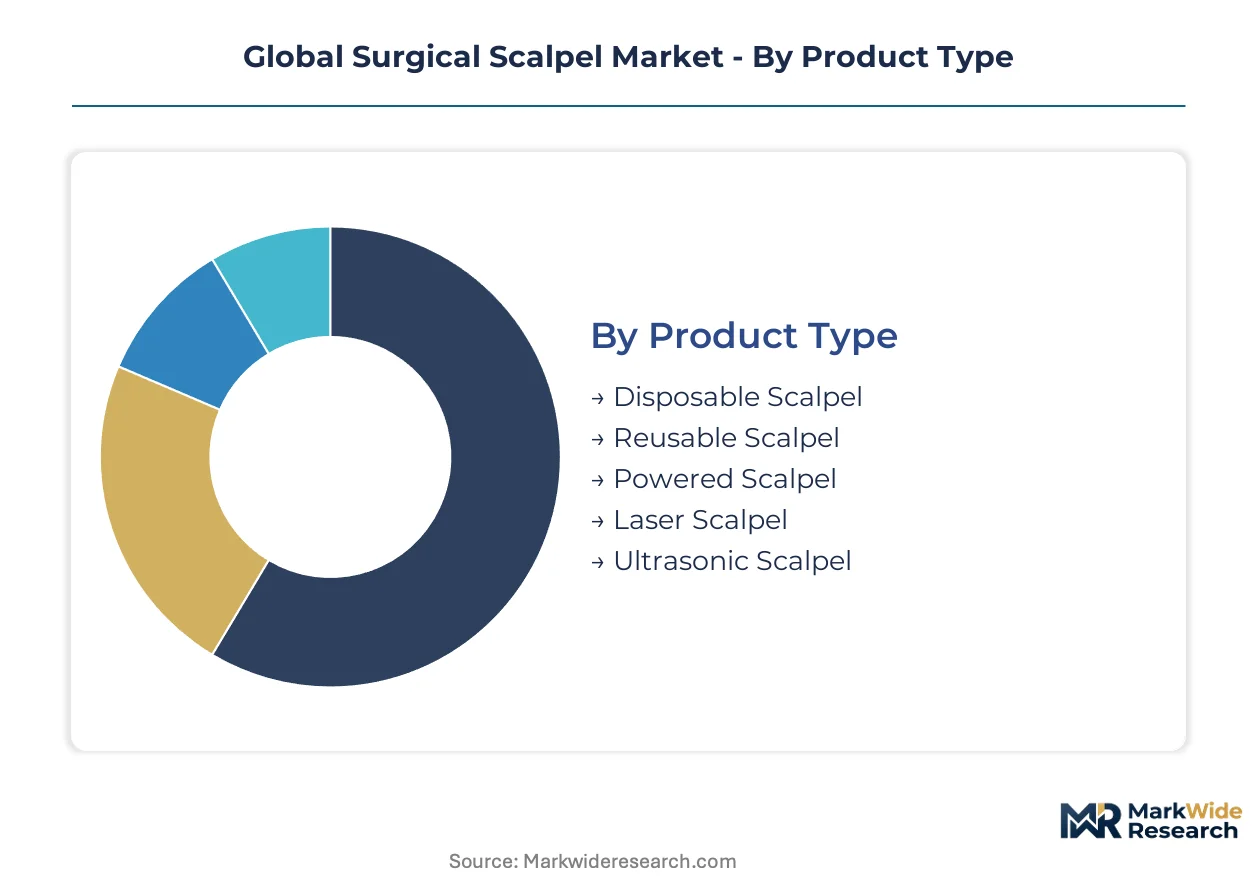
Surgical scalpel segmentation reveals distinct procurement rhythms across product lifecycles, from single-use disposables turning over weekly to capital-intensive powered platforms depreciating over seven years. Technology and application splits expose margin stratification between commodity blade contracts and premium electrosurgical system leases. Understanding these velocity differentials shapes inventory financing, service revenue models, and regulatory compliance investments.
Product Type:
Cycle times range from immediate consumption for sterile disposables to extended amortization schedules for laser and ultrasonic capital equipment, creating divergent working capital demands across supplier portfolios.
- Disposable Scalpel:Single-use carbon steel or stainless steel blades pre-sterilized via gamma irradiation, packaged in peel-pouch configurations for immediate use. Hospital consortiums in Germany and the United States negotiate multi-year disposable supply agreements indexed to ambulatory surgery center case volume expansion.
- Powered Scalpel:Motorized cutting systems integrating battery or line-power handles with disposable blade attachments, commanding premium positioning in cardiac and orthopedic suites. Integrated delivery networks bundle powered platform procurement with preventive maintenance contracts to minimize total cost of ownership.
- Reusable Scalpel:Autoclavable handle systems with detachable blade mounts, requiring central sterilization department processing and traceability documentation under EU MDR lot retention mandates.
- Laser Scalpel:Solid-state or gas laser delivery systems for tissue ablation and precision incision, concentrated in academic medical center dermatology and ophthalmology departments.
- Ultrasonic Scalpel:High-frequency vibration platforms enabling simultaneous cutting and coagulation, migrating from hepatic resection into laparoscopic general surgery applications.
Disposable scalpels dominate installed base. Powered platforms are where expansion concentrates.
Technology:
Cost tiers separate commodity manual blades from capital-intensive energy platforms, with reimbursement differentials driving technology selection across procedure types and facility tiers.
- Manual Blade:Conventional detachable blade systems manufactured to ISO 7740 standardized dimensions, sustaining ubiquity across general surgery and emerging market facilities where capital constraints limit energy platform adoption.
- Electrosurgical:Radiofrequency current delivery through active electrodes enabling cutting with simultaneous hemostasis, leading revenue contribution in cardiovascular procedures where blood loss minimization is critical.
- Ultrasonic Cutting:Mechanical vibration at frequencies exceeding 55 kHz generating frictional heat for tissue transection, gaining share fastest in minimally invasive procedures through reduced thermal spread.
- Laser Assisted:Coherent light energy for precise tissue vaporization, concentrated in plastic surgery and dermatology applications requiring micron-level accuracy.
- Plasma Scalpel:Ionized gas beam technology for contact-free incision with minimal collateral thermal damage, limited to specialized research and military medical applications.
Manual blades anchor volume procurement. Ultrasonic cutting is climbing the fastest through laparoscopic procedure expansion.
Application:
Procedure complexity and reimbursement levels stratify demand, with high-acuity specialties justifying premium technology while high-volume general surgery sustains commodity blade economics.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures generating highest absolute blade consumption volumes across hospital and ambulatory settings.
- Orthopedic Surgery:Joint replacement and trauma procedures requiring powered and ultrasonic platforms for bone and soft tissue management, concentrated in German and Japanese hospital systems.
- Cardiovascular Procedures:Sternotomy and vascular access incisions commanding electrosurgical premium positioning due to hemostasis requirements and reimbursement differentials.
- Neurosurgery:Cranial and spinal access procedures requiring precision blade geometries and minimal tissue trauma, sustaining demand for premium disposable configurations.
- Plastic Surgery:Aesthetic and reconstructive procedures favoring laser assisted and ultrasonic technologies for scar minimization outcomes.
General surgery sustains the broadest supplier base. Cardiovascular procedures generate the steepest margin pools per procedure.
End User:
Customer type determines procurement channel, with consolidated hospital systems leveraging volume leverage while ambulatory centers prioritize turnkey disposable supply.
- Hospitals:Integrated delivery networks operating centralized sterile processing departments, negotiating multi-year blade supply agreements with direct manufacturer relationships.
- Ambulatory Surgical Centers:Outpatient facilities in the United States and Germany expanding disposable safety-engineered blade procurement through group purchasing organizations.
- Specialized Clinics:Dermatology, ophthalmology, and dental surgery centers requiring procedure-specific blade geometries with limited inventory breadth.
- Research Institutes:Academic medical centers and contract research organizations sourcing experimental blade coatings and prototypes for preclinical validation studies.
Hospitals dominate capital platform installed base. Ambulatory surgical centers are where volume procurement is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement consortiums extract steeper volume discounts than Japanese integrated delivery networks, creating a pricing-power asymmetry that reshapes supplier margin structures across developed markets.
United States
Ambulatory surgery center consolidation and Medicare reimbursement shifts toward outpatient settings drive disposable safety-engineered blade procurement. FDA 510(k) clearance pathways govern sterility assurance and biocompatibility documentation for novel coatings. The Cleveland Clinic and Mayo Clinic anchor procurement volume in the Midwest, negotiating direct manufacturer relationships that bypass traditional medical-surgical distributors.
Germany
Hospital system mergers in North Rhine-Westphalia and Bavaria concentrate purchasing power for reusable handle sterilization services. EU MDR Unique Device Identification mandates force laser-etched lot codes and 10-year traceability databases. Tübingen and Heidelberg academic medical centers pilot ultrasonic platforms for laparoscopic general surgery, compressing electrosurgical unit market share in mid-tier systems.
Japan
Aging surgical workforces in Tokyo and Osaka metropolitan areas generate demand for ergonomic powered handles and reduced-force incision technologies. PMDA regulatory frameworks align with MHLW reimbursement policies for minimally invasive procedure expansion. Nagoya and Fukuoka hospital clusters prioritize suppliers with preventive maintenance contracts for powered platform total cost of ownership management.
China
Tier-3 hospital expansion in Sichuan and Shaanxi provinces sustains manual blade volume procurement amid capital constraints on energy platform adoption. NMPA medical device registration requirements stratify market access between multinational manufacturers and domestic suppliers. The Yangtze River Delta medical device cluster in Suzhou and Wuxi concentrates sterile disposable blade contract manufacturing for export markets.
India
Central government health mission procurement and private hospital chain expansion in Maharashtra and Karnataka drive safety-engineered disposable adoption. CDSCO medical device rules and BIS quality certification requirements create compliance barriers for unorganized sector blade manufacturers. The Chennai and Hyderabad medical device corridors host sterilization infrastructure investments serving domestic and Southeast Asian export demand.
Global Surgical Scalpel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blade and handle supply. The market structures around three tiers: multinational conglomerates with sterilization infrastructure, mid-scale disposable safety-engineered specialists, and regional stainless steel fabricators serving price-sensitive procurement. Dominant competitive moves include backward integration into carbon steel supply and direct-to-facility distribution bypassing traditional medical-surgical distributors.
Among German-based platform integrators, B. Braun Melsungen AG exemplifies the sterilization-anchored integrated delivery network model. Medtronic plc occupies a position in the powered and electrosurgical system tier. Aspen Surgical Products Inc. represents the disposable safety-engineered specialist archetype addressing needlestick prevention mandates.
| Leading Market Players |
|---|
| Swann-Morton Limited |
| B. Braun Melsungen AG |
| Aspen Surgical Products Inc. |
| Hill-Rom Holdings Inc. |
| Feather Safety Razor Co. Ltd. |
| Kai Corp. |
| Becton Dickinson and Co. |
| Medtronic plc |
| Integra LifeSciences Corporation |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta medical device manufacturing cluster in Suzhou and Wuxi concentrates sterile disposable blade contract manufacturing capacity, creating asymmetric pricing power for integrated suppliers serving export markets while compressing margins for regional stainless steel fabricators dependent on spot procurement.
Pricing Analysis
Configured-to-order pricing for powered scalpel platforms with preventive maintenance bundling commands substantial premiums over standard disposable blade contracts. Three-tier pricing structure across premium, standard, and economy levels separates electrosurgical systems with FDA 510(k) clearance from CE-marked manual blades and unbranded emerging market alternatives. Pricing pressure stems from hospital procurement consortiums extracting volume-indexed discounts for ambulatory surgery center expansion. Safety-engineered disposable variants show least price sensitivity due to needlestick prevention mandates, while standard manual blades face intense cost compression.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for blade manufacturers with cross-border component flows. Production gravity centers on Germany for sterilization infrastructure, Japan for precision steel processing, and China for gamma-irradiated disposable assembly. Raw material dependencies span Swedish carbon steel, Japanese stainless alloys, and German polymer handle resins. Single-source vulnerability concentrates in third-party sterilization capacity for reusable handle systems. Distribution runs through medical-surgical distributors facing disintermediation pressure from direct-to-facility manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consortium consolidation in Germany and the United States has shifted negotiating leverage decisively toward buyers, fragmenting supplier margins while elevating sterility and traceability requirements as non-negotiable contract terms.
For Market Incumbents: Pre-empt ultrasonic platform displacement of conventional electrosurgical units by accelerating laparoscopic general surgery pilots in academic medical centers. Backward integration into carbon steel supply secures input cost stability against energy-driven volatility. Capture service revenue through direct blade inventory management contracts that bypass traditional distributor networks. For New Entrants and Emerging Players: Pursue ergonomic powered handle development for Japan's aging surgical workforce as the most penetrable white-space target. Target India's tier-2 hospital expansion under central government health mission procurement for volume scaling. Differentiate through antimicrobial polymer coating convergence addressing EU MDR infection control mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization-anchored platform integrators over commodity blade fabricators. Long-term viability rests on captive regulatory compliance infrastructure spanning FDA 510(k) and EU MDR pathways. Acquisition target archetype: disposable safety-engineered specialists with pre-integrated serialization systems. Monitor ambulatory surgery center case growth rates as the signal indicating inflection toward outpatient-dominant procurement patterns.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Serialization Infrastructure | Laser-etched lot codes and 10-year traceability databases satisfy German hospital procurement requirements. |
| Direct-to-Facility Distribution | Bypassing medical-surgical distributors captures blade inventory management service revenue from integrated delivery networks. |
| Ultrasonic Platform Expansion | Migrating from hepatic resection into laparoscopic cholecystectomy compresses electrosurgical unit market share. |
| Antimicrobial Coating Development | Triclosan alternatives with hydrophobic layers differentiate suppliers in infection-sensitive cardiovascular procedures. |
| Preventive Maintenance Bundling | Powered platform procurement with service contracts minimizes total cost of ownership for Japanese hospital clusters. |
Research Methodology
A standing panel of hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and sterilization department supervisors provided ongoing calibration across primary interview cycles. Hospital procurement databases, GPO contract repositories, CMS Medicare reimbursement filings, and FDA 510(k) clearance records supplied secondary validation. Bottom-up demand modeling from ambulatory surgery center case volumes triangulated against top-down manufacturer shipment data.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product lifecycle velocity, technology cost tier, procedure complexity, and facility type procurement channel. CAGRs derived from procedure volume elasticity against reimbursement shifts and technology substitution curves. Industry-specific forecast inputs incorporated EU MDR compliance cost trajectories and powered platform adoption rates in cardiac suites.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese contract manufacturers or accelerated ultrasonic platform launches by mid-scale specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
India Surgical Sutures Market