
 Surgical Drains Market | 2026-2036
Surgical Drains Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Drains Market Outlook
Nursing specialization in postoperative wound management is rotating toward higher-acuity outpatient settings, tightening labor availability for traditional inpatient drain monitoring. Cardinal Health leverages its distribution scale to sustain hospital supply contracts across North America. B. Braun Melsungen AG anchors European manufacturing with vertically controlled silicone extrusion capabilities. Medtronic competes through R&D intensity in active suction technology, while Smith & Nephew differentiates via specialized negative pressure wound therapy integration.
Surgical drains are tubular medical devices, typically constructed from silicone or PVC with radiopaque striping, designed to evacuate fluid or air from wound sites or body cavities through passive capillary action or active negative pressure. Their primary purpose is to prevent hematoma, seroma, or infection accumulation following operative procedures. Closed suction drains command the largest volume share within product type segmentation due to standardized use in cardiac and abdominal procedures, while specialty drains targeting plastic surgery applications capture disproportionate margin pools. Material segmentation shows silicone dominating premium applications for biocompatibility and reduced tissue adherence, with polyurethane gaining traction in micro-lumen designs for minimally invasive techniques.
The FDA regulates surgical drains as class II devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates notified body conformity assessments and clinical evidence documentation for CE marking. Japan's PMDA enforces QMS ministerial ordinances that govern manufacturing site inspections and postmarket surveillance obligations. Stakeholders must monitor evolving sterilization validation standards and anticipate how MDR transition deadlines will reshape competitive access across European markets.
Market Dynamics
Ambulatory surgical center expansion and ERAS protocol adoption are compressing inpatient length of stay, forcing drain manufacturers to redesign products for outpatient monitoring compatibility and patient self-management.
Growth Catalysts
- Enhanced Recovery After Surgery protocols:Hospital systems in Germany and Japan are mandating earlier patient mobilization, creating demand for portable closed suction systems that maintain drainage integrity outside ICU settings.
- Silicone biocompatibility standards:REACH and MDR compliance requirements for reduced tissue adhesion are accelerating material upgrades from PVC to medical-grade silicone across European procurement contracts.
- Cardiac procedure volumes:Sternotomy drainage remains a standardized postoperative requirement, with United States hospital systems maintaining consistent replacement schedules regardless of economic cycles.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production concentrates among a limited set of European and Japanese chemical suppliers, exposing device manufacturers to input cost volatility and allocation constraints.
- Passive drain substitution:Negative pressure wound therapy systems are displacing traditional passive drains in plastic surgery applications, compressing margin pools in historically high-yield segments.
- MDR transition friction:EU Medical Device Regulation conformity assessment backlogs are extending CE marking timelines, freezing competitive access for mid-tier manufacturers lacking legacy certificate grandfathering.
Strategic Opportunities
- Micro-lumen minimally invasive designs:Laparoscopic and robotic surgery expansion in South Korea and the United States is creating demand for smaller-diameter drains compatible with trocar-based extraction.
- Ambulatory surgical center channel development:Same-day discharge mandates are opening direct procurement relationships with ASC networks, bypassing traditional hospital supply chain intermediaries.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for medical devices is attracting contract manufacturing investment, offering cost-competitive export capacity for standard drain configurations.
Industry Challenges
- Postoperative wound care nursing specialization:Labor shortages in inpatient settings are forcing manufacturers to develop simplified drain management protocols that reduce clinical training requirements.
- 510(k) clearance pathway complexity:FDA substantial equivalence determinations for modified drain designs are requiring expanded bench testing and biocompatibility documentation, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Drains Market |
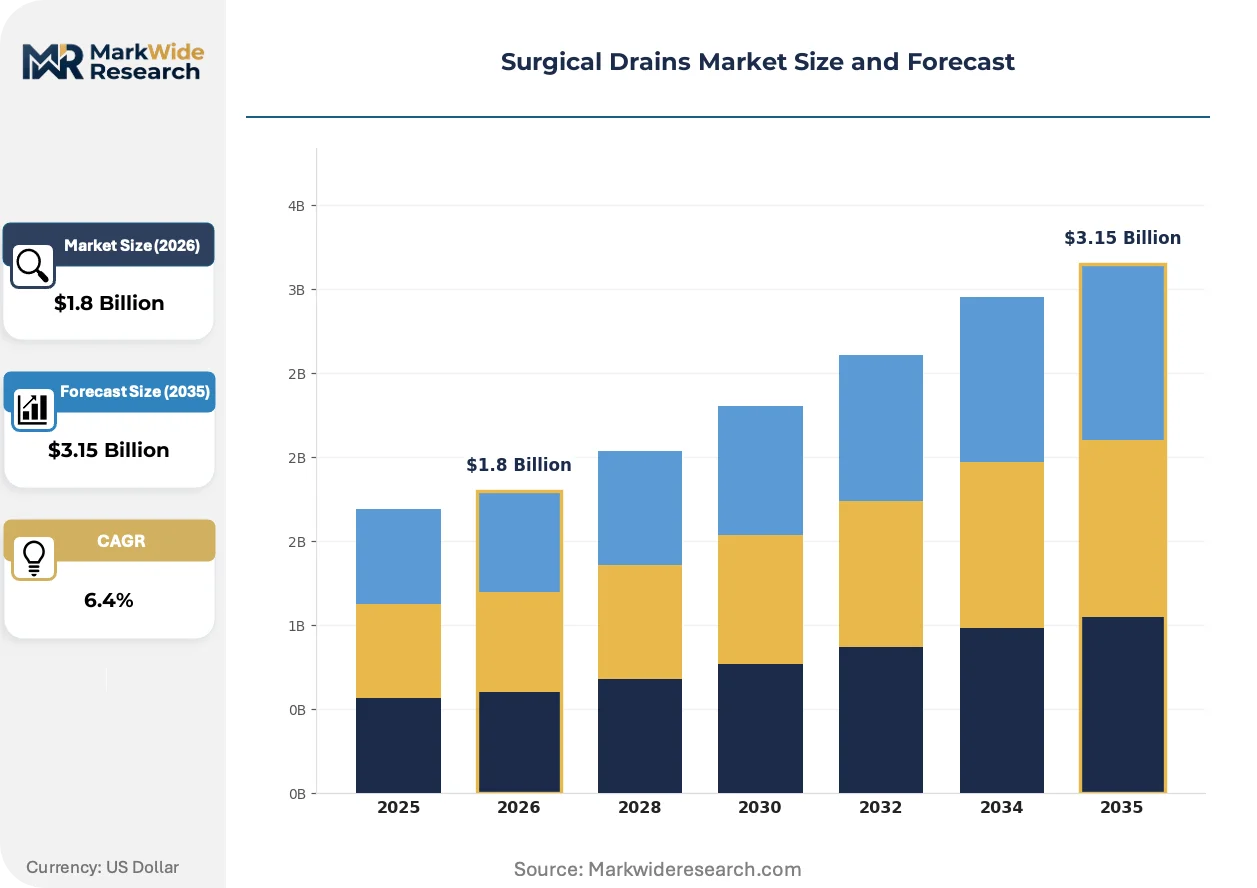
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Suction Drains, Passive Drains, Specialty Drains, Umbilical Drains Material: Silicone, PVC, Latex, Polyurethane End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare, Specialty Clinics Application: Cardiac Surgery, Abdominal Surgery, Orthopedic Surgery, Plastic Surgery |
| Companies Covered | Medtronic, Cardinal Health, B. Braun Melsungen AG, Johnson & Johnson, Cook Medical, Stryker, Teleflex Incorporated, ConvaTec Group, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Drains Market Strategic Shifts
Digital integration and material science advances are redefining drain functionality beyond passive fluid evacuation, with smart monitoring capabilities and antimicrobial surfaces emerging as primary differentiation vectors.
Antimicrobial-coated silicone is fragmenting the premium drain segment by addressing biofilm formation, a leading cause of surgical site infection. Cardiac surgery departments in tertiary United States hospitals are piloting silver-ion and chlorhexidine-impregnated drains despite 40-60% price premiums over standard silicone. This technology is fragmenting procurement decisions by forcing materials committees to weigh infection reduction economics against per-unit cost constraints.
EU Medical Device Regulation clinical evidence requirements are reshaping product development resource allocation across European markets. Manufacturers must now generate postmarket clinical follow-up data for class IIa drain classifications, previously exempt under the Medical Device Directive. Active suction drain portfolios face the heaviest documentation burden, prompting some suppliers to delay CE marking renewals for niche plastic surgery configurations.
Patient-directed drain management education is displacing traditional bedside nursing instruction as same-day discharge protocols expand. United States ASC networks are negotiating bundled contracts that include video-based training platforms and remote monitoring hotlines. This behavioral shift is most visible in metropolitan markets with high penetration of Medicare Advantage plans incentivizing lower-cost site-of-service migration.
Surgical Drains Market Segmentation
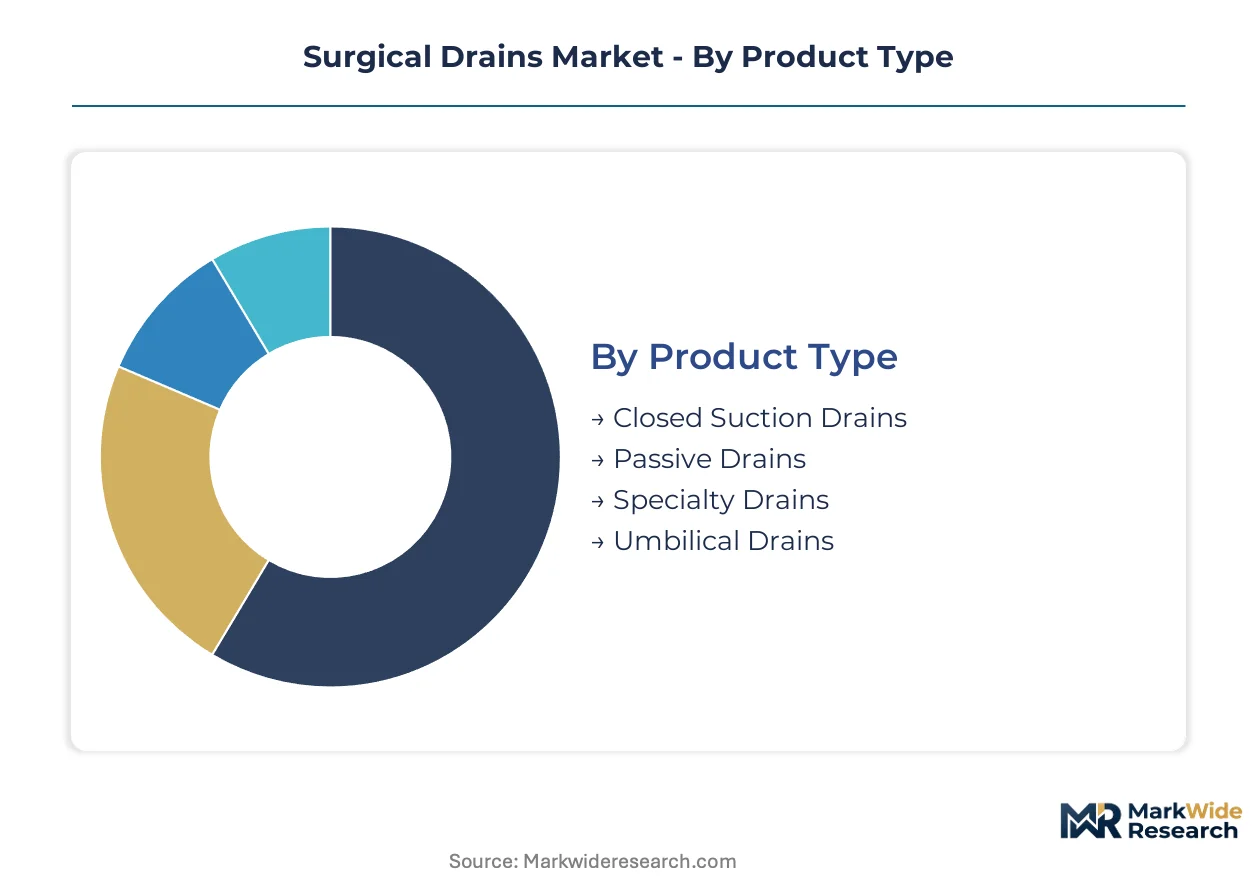
Drain selection hinges on procedure acuity, discharge timeline, and material biocompatibility requirements. Procurement patterns diver sharply between inpatient systems prioritizing reliability and ambulatory networks optimizing for patient self-management.
Product Type:
Domestic hospital procurement concentrates on closed suction systems, while export demand from Germany and Japan drives specialty drain development for plastic surgery applications.
- Closed Suction Drains:These systems employ negative pressure reservoirs connected to radiopaque silicone tubing for active fluid evacuation. United States cardiac surgery departments maintain standardized replacement schedules regardless of economic cycles, creating stable baseline demand.
- Passive Drains:Gravity-dependent capillary systems constructed from PVC or latex permit simpler manufacturing but face displacement from negative pressure wound therapy in high-margin plastic surgery segments.
- Specialty Drains:Custom-configured designs for micro-lumen minimally invasive techniques target South Korean and United States laparoscopic expansion.
- Umbilical Drains:Neonatal-specific configurations address pediatric surgical requirements with reduced-diameter silicone construction.
Closed suction drains hold the largest share; momentum sits with specialty drains.
Material:
Cost tiers separate premium silicone formulations from standard PVC and economy latex alternatives, with polyurethane emerging as a mid-tier option for micro-lumen designs.
- Silicone:Medical-grade elastomer dominates premium applications through superior biocompatibility and reduced tissue adherence. REACH and MDR compliance requirements accelerate material upgrades across European procurement contracts.
- PVC:Lower-cost polymer retains volume share in standard closed suction configurations where extended implantation duration is unnecessary.
- Latex:Budget-sensitive markets sustain residual demand despite allergy risk limitations and declining hospital system adoption.
- Polyurethane:Micro-lumen minimally invasive designs in South Korea and the United States exploit this material's tensile strength for smaller-diameter constructions.
Silicone dominates revenue contribution; polyurethane is expanding most quickly.
End User:
Customer type determines packaging complexity, training support requirements, and procurement channel strategy across institutional versus patient-directed purchasing.
- Hospitals:General hospitals remain the dominant procurement channel for closed suction and passive drain systems, with supply contracts negotiated through distribution intermediaries.
- Ambulatory Surgical Centers:Same-day discharge mandates open direct procurement relationships with ASC networks, bypassing traditional hospital supply chain intermediaries.
- Home Healthcare:Patient-directed drain management education displaces traditional bedside nursing instruction as Medicare Advantage plans incentivize lower-cost site-of-service migration.
- Specialty Clinics:Plastic surgery and cardiac-focused facilities capture disproportionate margin pools through premium antimicrobial-coated configurations.
Hospitals retain the largest share; momentum sits with ambulatory surgical centers.
Application:
Volume concentration in cardiac and abdominal procedures contrasts with margin concentration in plastic surgery, where aesthetic outcomes justify premium pricing.
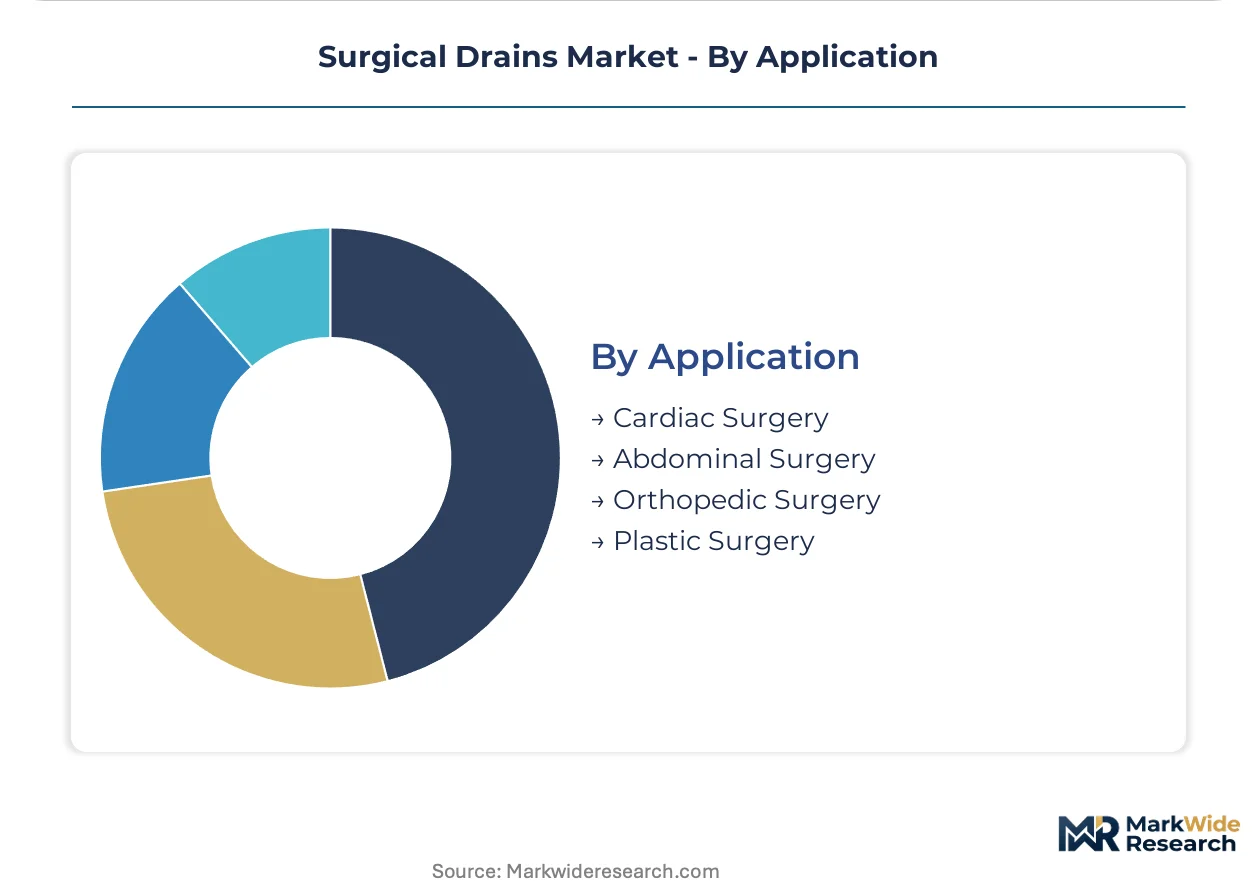
- Cardiac Surgery:Sternotomy drainage remains a standardized postoperative requirement with consistent replacement schedules across United States hospital systems.
- Abdominal Surgery:Laparotomy and colectomy procedures generate high-volume demand for closed suction systems compatible with enhanced recovery after surgery protocols.
- Orthopedic Surgery:Joint replacement and trauma procedures utilize drains for hematoma prevention, with demand concentrating in tertiary United States and German facilities.
- Plastic Surgery:Aesthetic and reconstructive applications capture disproportionate margin pools through specialized negative pressure wound therapy integration and antimicrobial-coated configurations.
Cardiac surgery holds the largest share; plastic surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance timelines anchor procurement decisions in the United States, while EU MDR transition friction and Japan's PMDA QMS ordinances reshape competitive access across their respective markets. Germany's cardiac surgery volume and India's PLI manufacturing incentives concentrate distinct supply chain investments.
United States
Cardiac sternotomy procedures and ASC expansion drive closed suction drain procurement. FDA maintains 510(k) substantial equivalence requirements for class II device modifications. Minneapolis and Cleveland cardiac clusters sustain standardized replacement schedules regardless of reimbursement cycles.
Germany
ERAS protocol mandates accelerate demand for portable suction systems compatible with early mobilization. ECHA REACH compliance pressures silicone material upgrades across hospital procurement contracts. Tuttlingen's medical device manufacturing corridor anchors European silicone extrusion capabilities.
Japan
Ambulatory surgical center capacity expansion concentrates demand for patient self-management compatible drains. PMDA enforces QMS ministerial ordinances governing manufacturing site inspections and postmarket surveillance. Osaka's precision polymer processing district supplies micro-lumen construction for minimally invasive techniques.
India
Government hospital procurement and private ASC networks create bifurcated demand for standard and premium configurations. CDSCO regulates device registration while PLI scheme incentives attract contract manufacturing investment. Gujarat's medical device manufacturing zone develops cost-competitive export capacity for standard drain configurations.
South Korea
Robotic and laparoscopic surgery expansion generates demand for micro-lumen minimally invasive drain designs. MFDS oversees quality management system certification and clinical trial requirements for novel device introductions. Seoul's biomedical cluster concentrates R&D investment in smaller-diameter polyurethane constructions.
Surgical Drains Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the surgical drains landscape. The market structure concentrates around diversified medical device conglomerates with captive distribution networks, mid-tier specialists with material science capabilities, and emerging contract manufacturers leveraging geographic cost advantages. Three archetypes dominate: integrated hospital supply distributors, vertically controlled silicone processors, and active suction technology developers. Competitive moves center on ASC channel direct procurement relationships and antimicrobial surface coating differentiation.
Within the integrated distribution tier, Cardinal Health and Medtronic exemplify contrasting approaches to hospital supply contract retention. B. Braun Melsungen AG occupies a position among European manufacturers with in-house silicone processing capabilities. These three entities represent the dominant competitive anchors across North American and European procurement channels.
| Leading Market Players |
|---|
| Medtronic |
| Cardinal Health |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Cook Medical |
| Stryker |
| Teleflex Incorporated |
| ConvaTec Group |
| Smith & Nephew |
| Others |
Value Chain & Pricing Dynamics
Scale economies in medical-grade silicone extrusion concentrate manufacturing among German and Japanese chemical suppliers, anchoring price floors through input allocation constraints while compressing margins for device assemblers lacking backward integration into polymer production.
Pricing Analysis
United States hospital systems pay 25-35% premiums over Indian procurement for identical closed suction configurations. Three-tier pricing structure across premium antimicrobial-coated, standard silicone, and economy PVC levels separates cardiac surgery departments from ambulatory surgical center buyers. Pricing pressure stems from negative pressure wound therapy substitution in plastic surgery applications. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary cardiac clusters prioritize infection reduction economics over per-unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate United States and German hospital procurement, while Asian contract manufacturers maintain strategic silicone stockpiles against European REACH compliance disruptions. Medical-grade silicone feedstock concentrates in Germany, Japan, and the United States; device assembly clusters in India and Malaysia. Raw material dependencies span silicone elastomer, radiopaque barium sulfate, and antimicrobial silver-ion compounds. Single-source vulnerability concentrates in specialty elastomer production. Distribution runs through group purchasing organizations and direct ASC network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambulatory surgical center consolidation into national networks is shifting procurement leverage toward buyers, compressing margin capture for manufacturers lacking direct channel relationships.
For Market Incumbents: Secure antimicrobial coating differentiation through FDA 510(k) pathway investments before MDR transition deadlines freeze European competitive access. Deepen backward integration into silicone extrusion to insulate against German and Japanese chemical supplier allocation constraints. Channel control through GPO contract retention remains essential as ASC networks bypass traditional intermediaries. For New Entrants and Emerging Players: Anchor in India's PLI scheme manufacturing zone to exploit cost-competitive export capacity for standard drain configurations. Target micro-lumen polyurethane designs for South Korean and United States robotic surgery expansion. Direct procurement relationships with ASC networks offer the most penetrable go-to-market angle against entrenched hospital supply distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated hospital supply distributors with captive GPO contracts and silicone processing capabilities. Long-term viability rests on regulatory navigation capacity across FDA 510(k) and EU MDR pathways. Acquisition targets should demonstrate CE marking grandfathering or active FDA submission pipelines. Watch antimicrobial coating adoption rates in United States cardiac surgery departments as inflection indicator for premium segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Development | Silver-ion and chlorhexidine-impregnated drains command 40-60% price premiums in United States tertiary hospitals. |
| Micro-lumen Design Engineering | Polyurethane constructions for South Korean robotic surgery expansion address trocar-compatible extraction requirements. |
| ASC Direct Channel Establishment | Bypassing hospital supply intermediaries captures same-day discharge procurement relationships in United States metropolitan markets. |
| Silicone Extrusion Backward Integration | In-house polymer processing insulates against German and Japanese chemical supplier allocation volatility. |
| MDR Compliance Pathway Investment | CE marking documentation for class IIa drain classifications secures European market access amid conformity assessment backlogs. |
Study Parameters
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists and secondary validation through FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down macroeconomic healthcare expenditure trends.
Sensitivity analysis across procedure volume assumptions, material cost scenarios, and regulatory timeline variations shapes the analytical framework. Segmentation dimensions span product type, material grade, end-user channel, application acuity, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation validated against historical replacement cycle patterns and ambulatory surgical center capacity expansion trajectories. Cardiac procedure volume stability and ERAS protocol penetration serve as primary forecast inputs.
Underlying assumptions cover silicone supply continuity, MDR transition timeline adherence, and ASC reimbursement stability, with deviation risk concentrated in antimicrobial coating regulatory classification shifts. Revision becomes warranted when negative pressure wound therapy substitution rates in plastic surgery applications cross threshold penetration levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Global Veterinary Surgical Instruments Market