
 Disposable Ophthalmic Surgical Products Market | 2026-2036
Disposable Ophthalmic Surgical Products Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Ophthalmic Surgical Products Market Analytics
Asset-light leasing models for phacoemulsification consoles and bundled disposable kits is tilting competitive economics toward firms with strong capital partnerships. Alcon leverages its integrated surgical platform to lock in recurring consumable revenue across cataract workflows. Johnson & Johnson sustains R&D intensity in presbyopia-correcting IOLs that require specialized disposable instrumentation. Bausch + Lomb competes through geographic dominance in emerging markets where cost-sensitive clinics prefer single-use over reprocessing.
Disposable ophthalmic surgical products encompass sterile single-use instruments, drapes, sponges, specula, and intravitreal injection devices engineered from medical-grade polymers, nonwoven fabrics, and hydrophilic foams, manufactured under ISO 14644 cleanroom standards and sterilized via gamma irradiation or ethylene oxide to eliminate pyrogenic and microbial contamination. These products serve the primary purpose of maintaining aseptic fields during anterior and posterior segment procedures while eliminating reprocessing costs and cross-infection liability. Cataract surgery applications anchor volume demand due to demographic expansion of eligible patients, while glaucoma surgery segments represent faster-growing margin pools as MIGS devices proliferate. Intravitreal injection devices concentrate growth in retina practices managing age-related macular degeneration patient volumes.
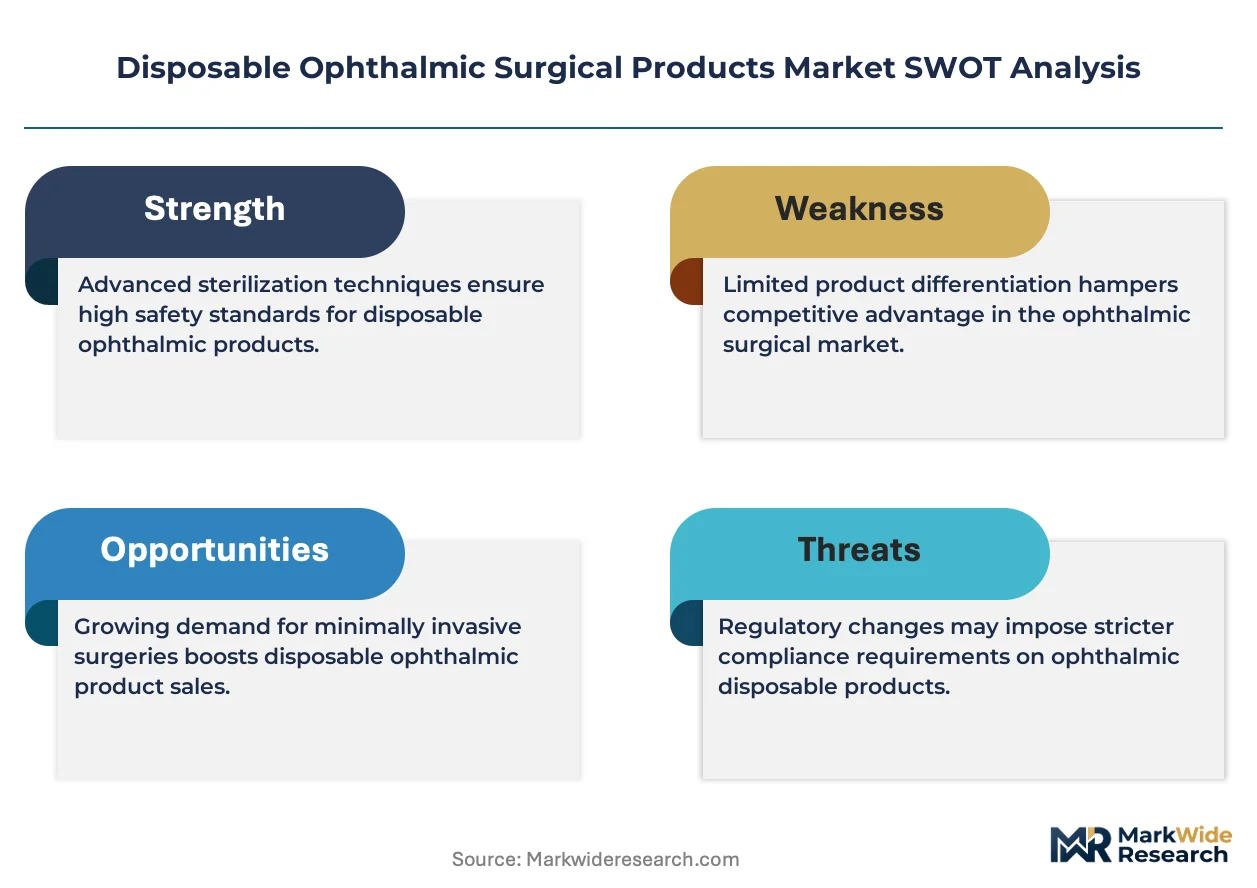
FDA sterilization validation protocols, EU MDR traceability requirements, and ISO 13485 quality management systems collectively elevate compliance costs and favor manufacturers with dedicated regulatory infrastructure. The EPA's emerging restrictions on ethylene oxide emissions are forcing supply chain recalibration toward gamma irradiation and novel low-temperature sterilization modalities. Stakeholders must monitor reimbursement parity between ambulatory surgery centers and hospital outpatient departments as site-of-service differentials reshape procurement concentration.
Market Dynamics
Gamma irradiation sterilization is displacing ethylene oxide across ophthalmic disposable supply chains as EPA emission restrictions tighten, forcing manufacturers to revalidate entire product portfolios under compressed timelines.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Medicare site-of-service payment differentials accelerate ASC volume capture for cataract procedures, concentrating demand for sterile single-use kits.
- EU MDR Traceability Mandates:Unique device identification requirements favor pre-sterilized disposable instruments over reprocessed alternatives with fragmented documentation chains.
- Presbyopia-Correcting IOL Proliferation:Premium lens technologies require specialized disposable instrumentation that commands recurring consumable revenue streams.
Market Restraints
- Ethylene Oxide Supply Concentration:Limited commercial sterilization facilities in the United States create single-point-of-failure risk for manufacturers with legacy validation portfolios.
- Medical-Grade Polymer Cost Volatility:Specialized hydrophilic foam and nonwoven fabric inputs face petrochemical feedstock price swings that compress margin predictability.
- Gamma Irradiation Capacity Constraints:Cobalt-60 sourcing bottlenecks and facility licensing delays extend sterilization queue times beyond production planning horizons.
Strategic Opportunities
- India Cost-Sensitive Clinic Penetration:Single-use preference over capital-intensive reprocessing equipment opens volume pools in tier-2 and tier-3 ophthalmic centers.
- Intravitreal Injection Device Specialization:Age-related macular degeneration patient volumes drive demand for precision-engineered disposable delivery systems.
- ISO 14644 Cleanroom Certification Arbitrage:Manufacturers with established quality infrastructure can capture outsourced production from competitors facing compliance upgrade costs.
Industry Challenges
- Sterilization Validation Timeline Compression:FDA alternative modality approval pathways require extensive bioburden and endotoxin testing that strains regulatory affairs capacity.
- Legacy Reprocessing Infrastructure Stranded Assets:Hospital systems with sunk capital in sterilization departments resist full conversion to disposable workflows despite liability reduction benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Ophthalmic Surgical Products Market |
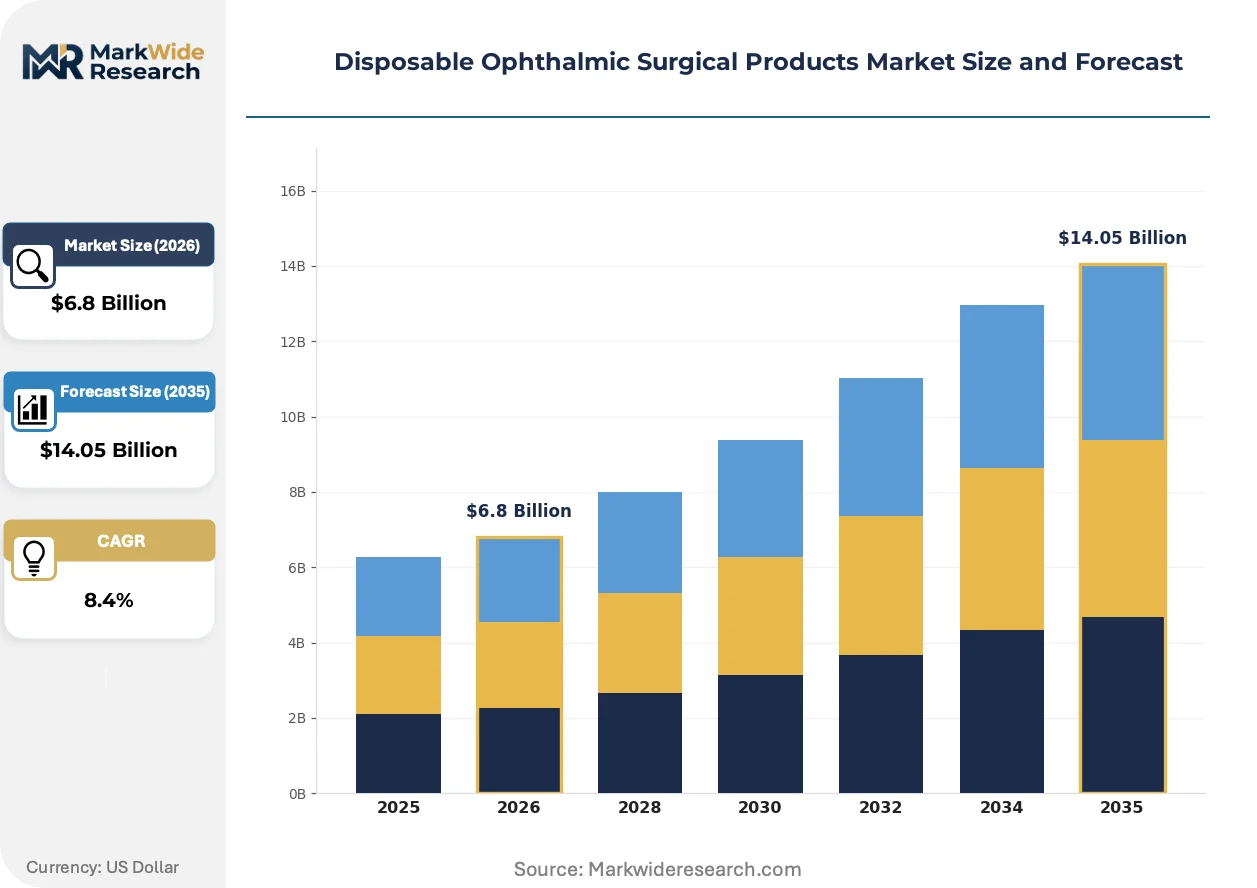
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Drapes, Surgical Sponges, Speculum, Intravitreal Injection Devices End User: Hospitals, Ambulatory Surgery Centers, Eye Clinics, Ophthalmologists Application: Cataract Surgery, Glaucoma Surgery, Corneal Transplant, Retinal Surgery Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Alcon, Johnson & Johnson, Carl Zeiss, Bausch + Lomb, HOYA Corporation, Sterimedix Limited, Glaukos Corporation, NIDEK Co., Ltd., Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Ophthalmic Surgical Products Market Evolving Landscape
Material science advances and regulatory modality shifts are compressing product development cycles while elevating performance specifications for aseptic ophthalmic instrumentation.
Pre-loaded intravitreal injection systems with integrated silicone-tipped plungers are rendering obsolete conventional syringe-and-needle assemblies in retina practices. Academic medical centers in the United States and Germany are standardizing these devices to reduce endophthalmitis risk and procedure time. The shift is compressing commoditized syringe demand while expanding addressable margins for engineered single-use delivery platforms.
EPA ethylene oxide emission restrictions are forcing sterilization modality migrations that favor gamma irradiation and novel low-temperature alternatives. Manufacturers face portfolio-wide revalidation costs and supply chain reconfiguration to access irradiation capacity. Cataract kit producers with concentrated US manufacturing footprints bear disproportionate compliance burden relative to competitors with diversified sterilization partnerships.
Asset-light leasing models for phacoemulsification consoles are unbundling capital equipment from consumable procurement decisions. Ambulatory surgery centers now source disposable kits through bundled subscription arrangements rather than discrete purchase orders. This pattern concentrates most visibly in United States Medicare-reimbursed outpatient settings where cash flow predictability outweighs ownership preferences.
Disposable Ophthalmic Surgical Products Market Segmentation
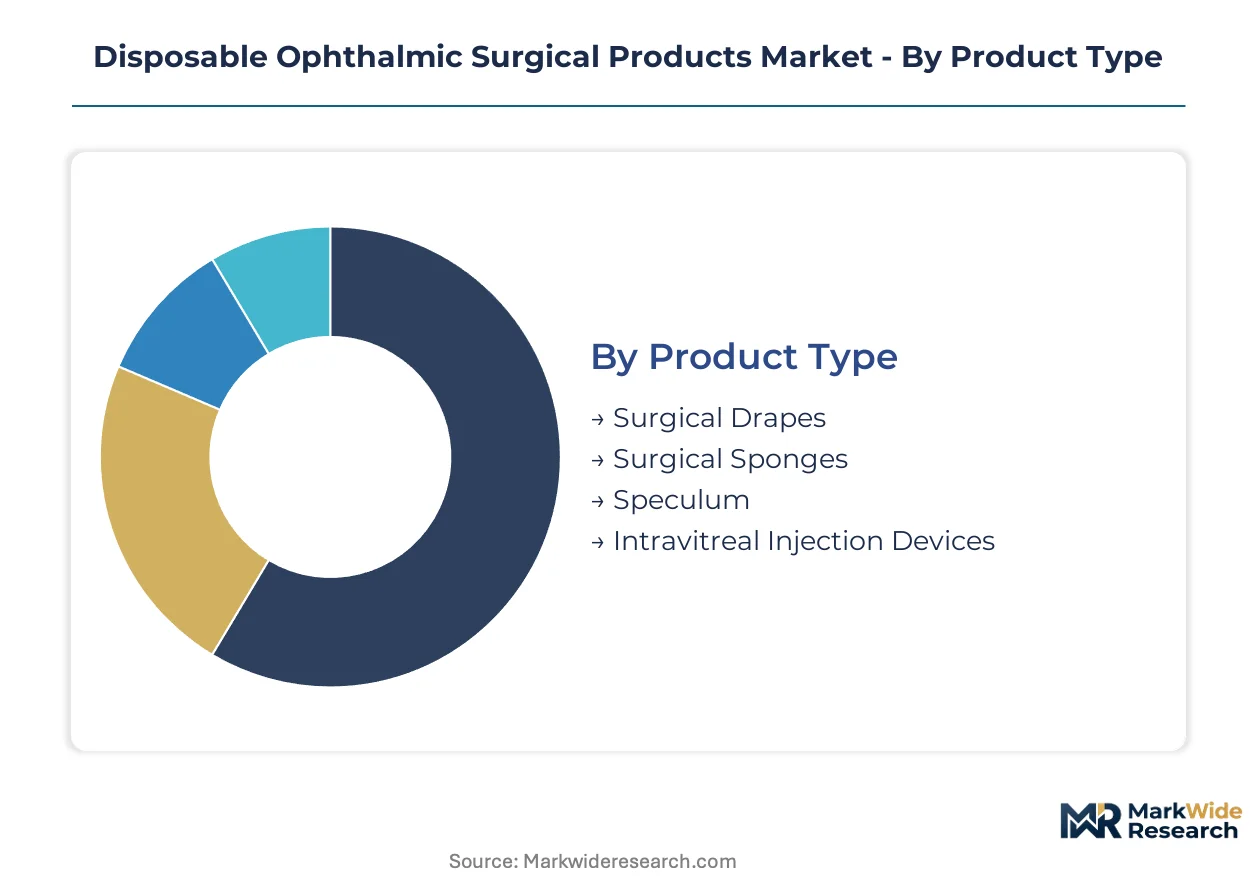
Segmentation in disposable ophthalmic surgical products reveals how sterile supply chains align with procedure complexity, site-of-service economics, and regulatory compliance burdens. Manufacturers configure portfolios across these dimensions to capture recurring consumable revenue while managing sterilization validation costs.
Product Type:
Use-case spectrum spans passive barrier products to precision-engineered delivery systems with divergent margin profiles and sterilization modality requirements.
- Surgical Drapes:Nonwoven polypropylene laminates with adhesive fenestrations establish sterile fields for anterior segment procedures. ASCs in the United States favor pre-sterilized kits bundling drapes with instruments to minimize OR turnover time.
- Intravitreal Injection Devices:Pre-loaded syringes with silicone-tipped plungers and fixed-gauge needles eliminate compounding steps in retina practices. Germany's academic medical centers are standardizing these devices to reduce endophthalmitis risk.
- Surgical Sponges:Hydrophilic PVA foam instruments for fluid management and corneal protection during phacoemulsification.
- Speculum:Wire and blade configurations for eyelid retraction in cataract and glaucoma procedures.
The dominant share belongs to Surgical Drapes, while Intravitreal Injection Devices is closing the gap fastest.
End User:
Customer type determines procurement concentration, with site-of-service payment differentials fragmenting demand across institutional and independent practice settings.
- Ambulatory Surgery Centers:Medicare reimbursement shifts favor outpatient cataract volume capture, driving bundled sterile kit procurement through subscription models. United States ASCs now represent the primary growth vector for single-use platform vendors.
- Hospitals:Hospital outpatient departments retain complex case referrals but face stranded asset pressure from legacy sterilization infrastructure resisting full disposable conversion.
- Eye Clinics:Standalone facilities in tier-2 Indian cities prefer single-use instruments over capital-intensive reprocessing equipment.
- Ophthalmologists:Solo and group practices source precision devices for intravitreal injection procedures in age-related macular degeneration management.
Ambulatory Surgery Centers command the volume lead, though Eye Clinics in emerging markets are expanding most quickly.
Application:
Procedure complexity dictates product specification intensity, with posterior segment interventions requiring higher-grade sterile assurance than anterior workflows.
- Cataract Surgery:Phacoemulsification consumables anchor volume demand as demographic expansion enlarges the eligible patient pool. United States Medicare reimbursement parity between ASCs and hospital outpatient departments concentrates procurement at high-volume sites.
- Retinal Surgery:Vitrectomy and membrane peeling procedures demand specialized drapes, illumination devices, and precision injection systems with ISO 14644 cleanroom certification.
- Glaucoma Surgery:Minimally invasive glaucoma surgery devices create margin pools as MIGS proliferation expands addressable procedure volumes.
- Corneal Transplant:DMEK and DSAEK techniques require trephination systems and donor tissue handling instruments with endotoxin-controlled sterilization.
Cataract Surgery holds the dominant position, while Glaucoma Surgery is gaining share fastest on MIGS device adoption.
Distribution Channel:
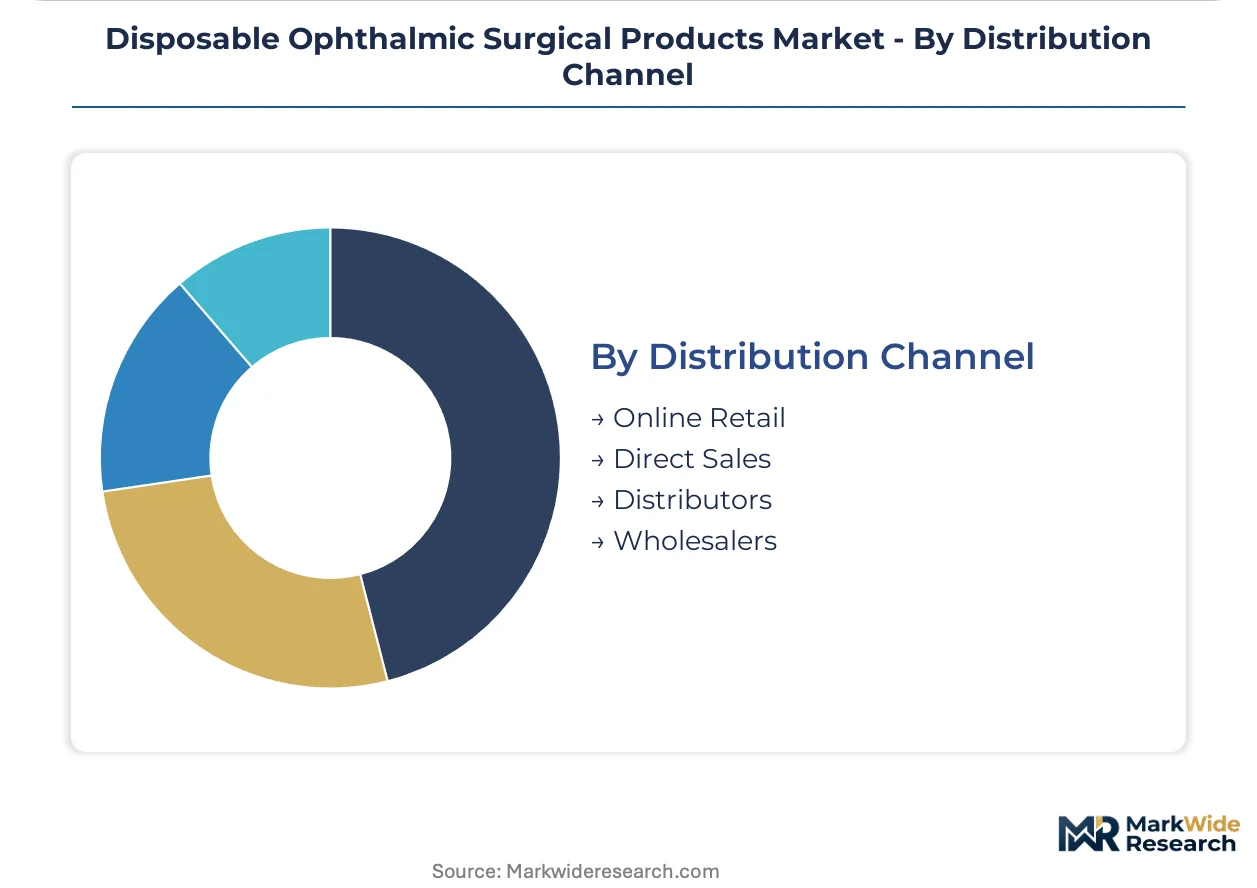
Supply chain configuration reflects customer scale and capital partnership structures, with direct engagement displacing traditional wholesale in high-volume accounts.
- Direct Sales:Manufacturers deploy field specialists to ASC chains and hospital systems for bundled kit contracting. Asset-light leasing models for phacoemulsification consoles tie consumable procurement to equipment subscription arrangements.
- Distributors:Regional medical supply intermediaries serve fragmented eye clinic networks with inventory management and sterilization documentation support.
- Online Retail:E-commerce platforms capture small-practice and international orders for commoditized drapes and sponges with transparent pricing.
- Wholesalers:Broad-line distributors aggregate demand across multiple surgical specialties with limited ophthalmic specialization.
Direct Sales captures the largest share, though Online Retail is climbing the fastest as procurement digitization penetrates smaller practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare site-of-service payment differentials in the United States are accelerating ambulatory surgery center volume capture for cataract procedures. The FDA's updated sterilization validation requirements are pushing manufacturers toward ethylene oxide alternatives and gamma-irradiated packaging. These policy shifts are reshaping procurement concentration across major ophthalmic surgical markets.
United States
ASCs in Florida and Texas are scaling adoption of single-use sterile kits to reduce cross-contamination risk. The FDA's emerging restrictions on ethylene oxide emissions are forcing supply chain recalibration toward gamma irradiation. The Medicare reimbursement parity between ASCs and hospital outpatient departments concentrates procurement at high-volume sites in the Southeast and Southwest.
Germany
Academic medical centers in Berlin and Munich are standardizing pre-loaded intravitreal injection devices to reduce endophthalmitis risk. The EU MDR traceability mandates favor pre-sterilized disposable instruments over reprocessed alternatives with fragmented documentation chains. Manufacturing clusters in Baden-Württemberg host specialized cleanroom facilities serving retina practices across Western Europe.
India
Standalone eye clinics in tier-2 cities prefer single-use instruments over capital-intensive reprocessing equipment. The CDSCO's alignment with ISO 13485 quality management systems elevates compliance costs for imported devices. Manufacturing hubs in Gujarat and Maharashtra are expanding gamma irradiation capacity to serve domestic ophthalmic kit producers.
Japan
Age-related macular degeneration patient volumes in Tokyo and Osaka drive demand for precision-engineered disposable delivery systems. The PMDA's sterilization validation protocols require extensive bioburden and endotoxin testing for alternative modalities. Industrial clusters in the Kansai region specialize in medical-grade polymer processing for hydrophilic foam instruments.
China
Urban hospital systems in Shanghai and Beijing are converting to disposable workflows despite legacy reprocessing infrastructure. The NMPA's updated cleanroom certification requirements favor manufacturers with established ISO 14644 infrastructure. The Yangtze River Delta hosts contract sterilization facilities serving both domestic and export-oriented ophthalmic product manufacturers.
Disposable Ophthalmic Surgical Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement decisions at ambulatory surgery centers and hospital systems. The market structure tilts toward consolidated platforms with integrated surgical equipment leasing and consumable bundling capabilities. Three archetypes dominate: integrated ophthalmic platforms, precision instrument specialists, and regional cost-optimized suppliers. Competitive moves concentrate on asset-light leasing partnerships and sterilization modality diversification to address EPA emission restrictions.
Among integrated platform providers, Alcon and Johnson & Johnson exemplify the channel-control archetype through recurring consumable revenue models. Bausch + Lomb occupies a position within the geographic expansion specialist tier, particularly in emerging markets where cost-sensitive clinics prefer single-use over reprocessing. Carl Zeiss represents the precision-engineering segment, anchoring high-specification product development for posterior segment procedures. These three companies collectively illustrate how competitive positioning stratifies across capital partnership intensity, regulatory infrastructure depth, and geographic coverage breadth.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson |
| Carl Zeiss |
| Bausch + Lomb |
| HOYA Corporation |
| Sterimedix Limited |
| Glaukos Corporation |
| NIDEK Co., Ltd. |
| Topcon Corporation |
| Others |
Value Network & Pricing Analysis
Gamma irradiation capacity underutilization in the United States is forcing sterilization service providers to absorb fixed costs across smaller batch volumes, which compresses per-unit economics for cataract kit manufacturers while simultaneously elevating pricing power for facilities with cobalt-60 sourcing relationships.
Pricing Analysis
Certification level (ISO 14644/FDA-grade) creates the primary spread between premium sterile kits and commodity drapes, with three-tier pricing structure across premium, standard, and economy levels anchoring the market. Subscription-based bundled procurement for ASCs commands price premiums over transactional spot purchases by independent clinics. Cost compression in standard-tier drapes is intensifying because medical-grade polypropylene feedstock volatility feeds through to contract renegotiations. Eye clinics in tier-2 Indian cities exhibit highest price sensitivity, while academic medical centers in Germany prioritize endotoxin-controlled sterilization assurance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for hydrophilic foam instrument producers with Asian polymer sourcing dependencies. Manufacturing concentrates in the United States, Germany, and India, with each hub serving distinct regulatory validation requirements. Raw material inputs draw from medical-grade polymer processors in the Kansai region, nonwoven fabric mills in Gujarat, and cobalt-60 irradiation facilities in Texas. Single-source vulnerability in ethylene oxide sterilization capacity is forcing portfolio diversification toward gamma irradiation partnerships. Distribution runs through direct sales teams for ASC chains and regional distributors for fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across sterilization modality capabilities and geographic regulatory clusters is creating niche entry points for specialists who can arbitrage compliance cost differentials between legacy ethylene oxide portfolios and gamma-irradiated alternatives.
For Market Incumbents: Harden sterilization validation infrastructure against EPA emission restriction enforcement by securing redundant gamma irradiation capacity in multiple regulatory jurisdictions. Consolidate procurement relationships with ASC chains through asset-light phacoemulsification leasing bundles that embed consumable subscription terms. Priority lever rests on backward integration into cobalt-60 sourcing partnerships to escape sterilization queue bottlenecks. For New Entrants and Emerging Players: Tier-3 ophthalmic centers in India represent the most penetrable white-space target, where capital constraints prevent reprocessing equipment acquisition and single-use preference runs strong. CDSCO alignment with ISO 13485 creates compliance arbitrage for manufacturers with established cleanroom infrastructure. Go-to-market angle should emphasize turnkey sterile kit bundling that eliminates procurement complexity for clinic administrators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gamma irradiation facility licensing and cobalt-60 security compliance, favoring asset-light contract manufacturers over integrated sterilization operators. Acquisition target archetype: regional distributors with GPO contracts at ASC chains and established FDA 510(k) submission track records. Signal to watch is Medicare site-of-service reimbursement parity legislation affecting outpatient cataract volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Modality Diversification | EPA emission restrictions are forcing portfolio-wide revalidation toward gamma irradiation and novel low-temperature alternatives. |
| ASC Chain Partnership | Medicare reimbursement parity concentrates procurement at high-volume ambulatory surgery centers through bundled subscription arrangements. |
| ISO 14644 Cleanroom Certification | Established quality infrastructure captures outsourced production from competitors facing compliance upgrade cost burdens. |
| Intravitreal Injection Device Specialization | Age-related macular degeneration patient volumes drive demand for precision-engineered disposable delivery platforms. |
| Geographic Expansion in India | Tier-2 and tier-3 ophthalmic centers prefer single-use instruments over capital-intensive reprocessing equipment investments. |
Research Methodology
The analysis maps sterilization modality segments, product type configurations, and end-user procurement patterns, each validated through operating room managers, ASC procurement directors, and biomedical engineers at academic medical centers. Primary fieldwork with sterilization service providers, GPO contracts managers, and regulatory affairs specialists at ophthalmic device manufacturers combined with secondary validation against FDA 510(k) filings, EPA emission restriction dockets, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up demand modeling from procedure volume projections triangulates against top-down market sizing from manufacturer revenue disclosures.
Assumptions held fixed include current EPA ethylene oxide emission restriction enforcement timelines and Medicare site-of-service payment parity policies, while variables tested include gamma irradiation capacity expansion rates and medical-grade polymer feedstock price trajectories. The analytical framework segments by product type, end user, application, and distribution channel across the analysis window, with CAGRs derived from weighted average procedure growth rates and pricing trajectory assumptions. Forecast inputs incorporate ophthalmologist practice pattern surveys and ambulatory surgery center construction pipeline data.
Practitioners should monitor EPA enforcement action intensity and cobalt-60 sourcing disruption events for early signals of sterilization capacity constraint. Forecasts reflect documented assumptions regarding reimbursement policy stability and regulatory approval pathway timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Surgical Equipment Market