
 Cleft Lip and Palate Repair Surgical Instrument Package Market | 2026-2036
Cleft Lip and Palate Repair Surgical Instrument Package Market Size, Share, and Industry Trends Forecast 2026-2036
Cleft Lip and Palate Repair Surgical Instrument Package Market Analytics
Outpatient clinics are collapsing the historical hospital-centric procurement model for cleft repair instrument packages. Medtronic leverages its integrated surgical workflow platforms to anchor high-volume contracts with ambulatory surgical centers. Stryker competes through specialized pediatric instrument configurations that sustain premium positioning in academic medical centers.
Cleft lip and palate repair surgical instrument packages comprise coordinated sets of precision scissors, forceps, needle holders, and retractors manufactured from stainless steel or titanium alloys to withstand repeated autoclave sterilization cycles while maintaining microsurgical edge integrity. These packages serve the primary commercial purpose of standardizing instrument availability for sequential stages of cheiloplasty and palatoplasty procedures. Forceps and needle holders in titanium compositions command concentrated margin pools due to their superior strength-to-weight ratios and reduced surgeon fatigue during extended neonatal procedures. Minimally invasive technology segments are expanding fastest as fiber-optic retractor systems and micro-laparoscopic adaptations gain protocol adoption in tertiary pediatric centers.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape sterilization validation requirements and biocompatibility testing burdens for instrument manufacturers seeking multi-jurisdiction market access. ISO 13485 quality management standards and WHO surgical safety checklists further constrain product design specifications and traceability documentation. Stakeholders must monitor evolving reimbursement coding for robotic-assisted cleft procedures to anticipate whether capital-intensive technology segments will capture sustainable procedure volumes.
Market Dynamics
Outpatient surgical centers are collapsing the historical hospital-centric procurement model for cleft repair instrument packages, forcing manufacturers to reconfigure distribution networks and service architectures around ambulatory volume contracts.
Growth Catalysts
- India's government-funded cleft surgery missions:State-backed surgical camps and medical tourism infrastructure are scaling instrument procurement volumes through centralized tender processes.
- FDA 510(k) clearance standardization:Streamlined premarket notification pathways for reusable surgical instruments are reducing regulatory friction for manufacturers seeking US market entry.
- Titanium alloy adoption:Pediatric academic centers are specifying titanium forceps and needle holders to reduce surgeon fatigue during extended neonatal procedures.
Market Restraints
- Autoclave degradation cycles:Repeated sterilization protocols under FDA and CE marking requirements shorten functional lifespans of precision microsurgical edges, elevating replacement frequency.
- Supply concentration in German precision forges:Specialty stainless steel and titanium billet sourcing clusters in Baden-Württemberg and North Rhine-Westphalia create geographic vulnerability.
- Fiber-optic retractor cost barriers:Capital-intensive minimally invasive systems face adoption ceilings in resource-constrained public hospital systems.
Strategic Opportunities
- Robotic-assisted cleft procedure coding:Evolving reimbursement classifications for da Vinci and comparable platforms may unlock sustainable capital equipment segments in tertiary pediatric centers.
- ISO 13485 certification arbitrage:Quality management standardization enables qualified manufacturers to bypass jurisdiction-specific validation burdens across multiple markets.
- Direct-to-clinic digital distribution:E-procurement platforms are disintermediating traditional surgical supply distributors in Southeast Asian markets.
Industry Challenges
- Pediatric microsurgical training pipelines:Shortages of fellowship-trained craniofacial surgeons constrain procedure volume expansion regardless of instrument availability.
- Legacy instrument traceability integration:RFID and blockchain-enabled surgical safety checklists require retrofitting documentation systems in established academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleft Lip and Palate Repair Surgical Instrument Package Market |
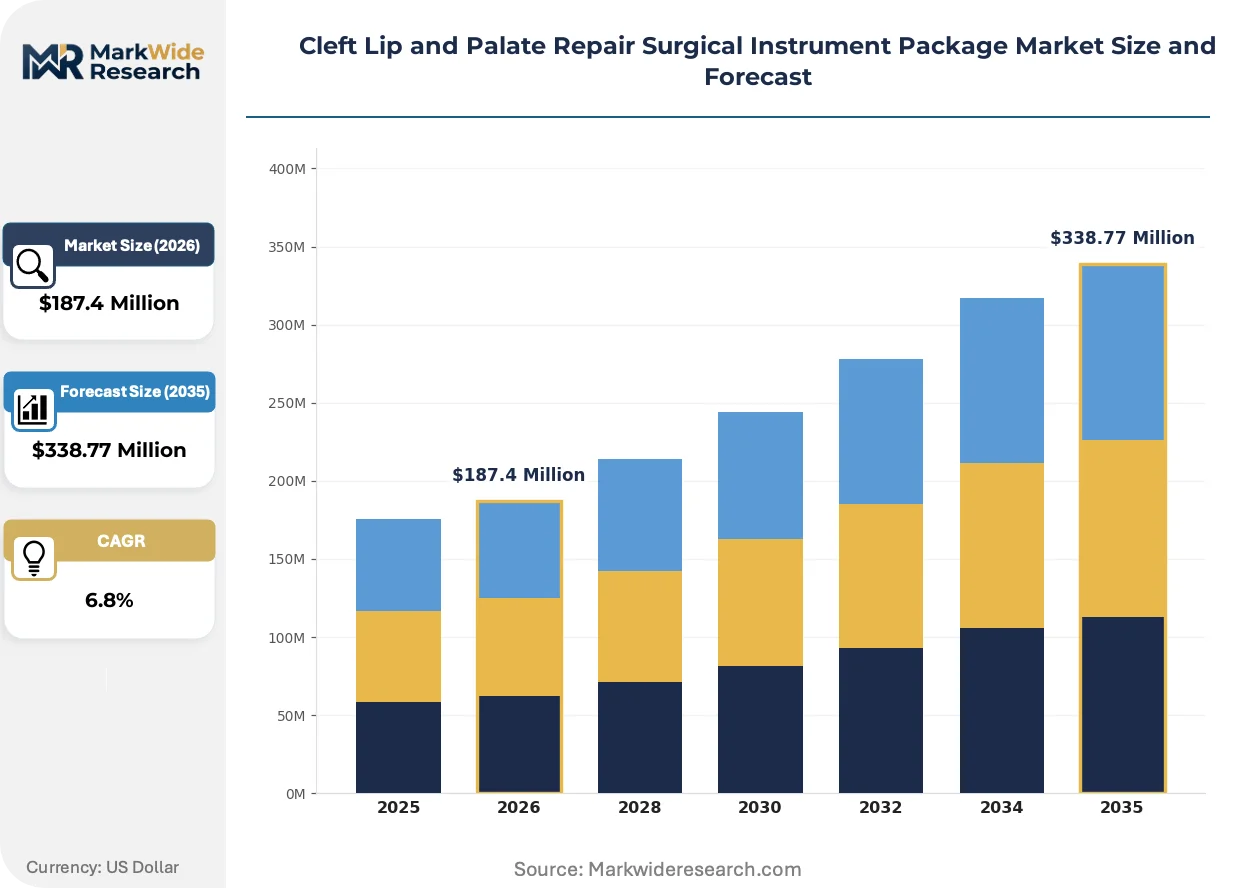
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Forceps, Needle Holders, Retractors Material: Stainless Steel, Titanium, Carbon Steel, Plastic End User: Hospitals, Outpatient Clinics, Academic Institutions, Surgical Centers Technology: Traditional, Minimally Invasive, Robotic-Assisted, Laser |
| Companies Covered | Olympus, Richard WOLF, Medtronic, ConMed, Teleflex, Stryker, Boston Scientific, Cook Medical, KARL STORZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleft Lip and Palate Repair Surgical Instrument Package Market Evolving Landscape
Minimally invasive adaptations are reshaping instrument design specifications while regulatory sterilization protocols tighten material science requirements across manufacturing bases.
Titanium composition is bifurcating instrument procurement tiers as academic medical centers specify premium-grade forceps and needle holders for neonatal procedures while community hospitals retain stainless steel configurations. Pediatric surgical centers in the United States and Western Europe are driving titanium volume through specialized procurement committees. The technology is bifurcating margin structures, compressing commodity stainless steel pricing while concentrating premium pools in aerospace-grade titanium alloys.
EU Medical Device Regulation (MDR) Annex I general safety and performance requirements are elevating biocompatibility testing burdens for reusable surgical instruments seeking CE marking. Manufacturers must now document biological risk management across repeated sterilization cycles to maintain market access. Pediatric instrument specialists are responding by consolidating validation testing in notified body partnerships to accelerate conformity assessment timelines.
Consignment inventory models are displacing traditional capital purchase arrangements in ambulatory surgical centers, transferring working capital burden to manufacturers. Distributors are unbundling after-sales service from instrument packages, forcing producers to build direct field service capabilities. This restructuring is most visible in India's expanding private surgical center networks, where medical tourism operators demand just-in-time instrument availability without ownership overhead.
Cleft Lip and Palate Repair Surgical Instrument Package Market Segmentation
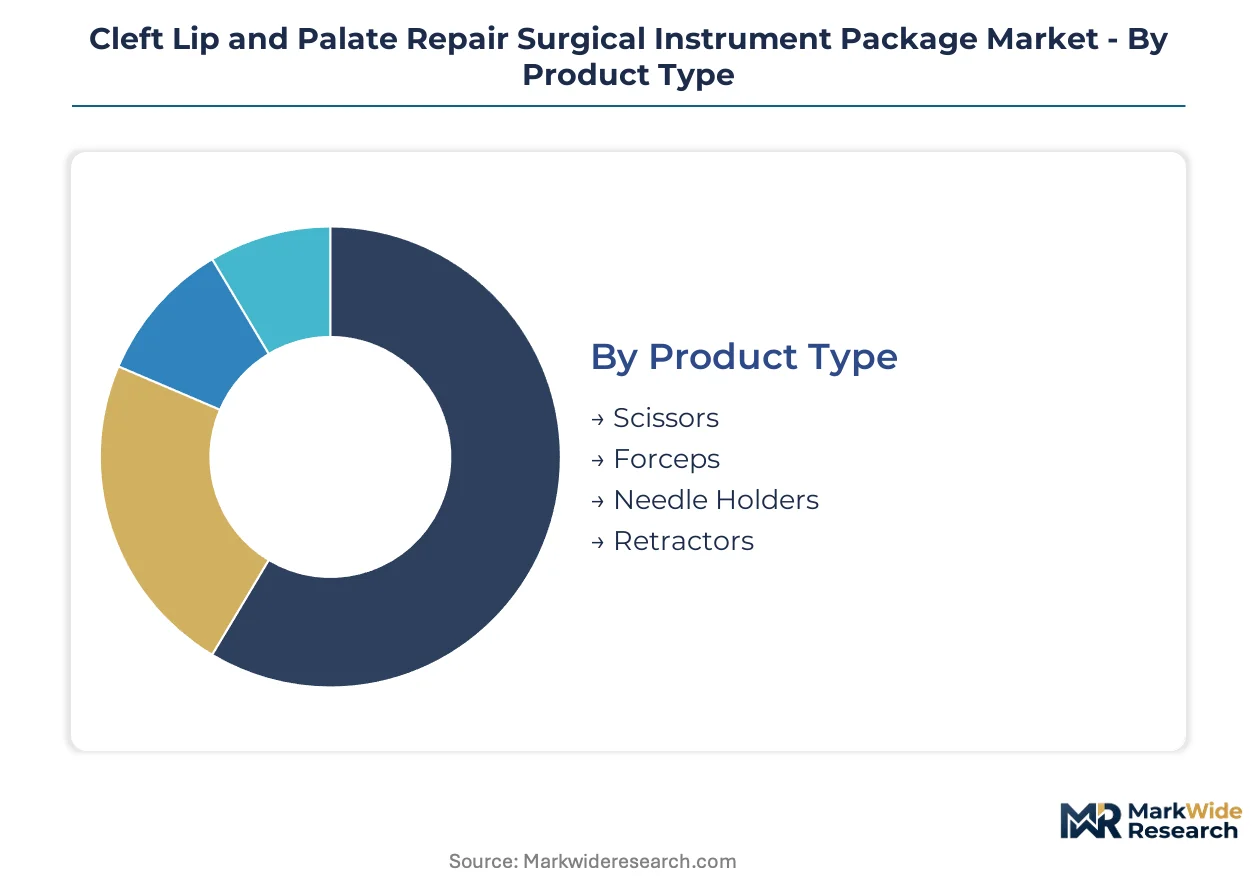
Segmentation in cleft repair instrument packages determines procurement tiering, sterilization protocol requirements, and distribution channel selection across divergent clinical settings. Material composition and technology sophistication create the primary fault lines for margin capture and competitive positioning.
Product Type:
Substitute pressure concentrates in retractor categories, where fiber-optic and single-use alternatives threaten reusable metal instrument economics.
- Scissors:Precision microsurgical scissors with tungsten carbide inserts maintain edge integrity across autoclave cycles. Demand clusters in Indian government-funded cleft surgery missions where standardized sets reduce per-procedure instrument costs.
- Forceps:Adson and Gillies forceps configurations dominate pediatric palatoplasty protocols. Titanium variants specified by US academic medical centers reduce surgeon fatigue during extended neonatal procedures, anchoring premium pricing tiers.
- Needle Holders:Castroviejo and Mathieu designs with ratchet-lock mechanisms serve cheiloplasty suturing sequences.
- Retractors:Dingman and cleft palate retractors face displacement from illuminated fiber-optic systems in tertiary pediatric centers.
Forceps anchors the volume base while retractors gain share at the steepest rate through minimally invasive technology adoption.
Material:
Cost tier stratification separates aerospace-grade titanium procurement committees from commodity stainless steel purchasing in community hospital settings.
- Stainless Steel:400-series martensitic grades dominate high-volume instrument production for developing economy markets. Indian surgical centers specify AISI 420 and 440 compositions for government tender compliance, prioritizing unit cost over extended lifecycle performance.
- Titanium:Ti-6Al-4V ELI alloy specifications command concentrated margin pools through reduced weight and superior biocompatibility profiles. US and Western European pediatric academic centers drive specification authority for neonatal procedure suites.
- Carbon Steel:Hardened carbon compositions serve cost-sensitive institutional procurement in Southeast Asian ambulatory networks.
- Plastic:Single-use polyphenylsulfone and PEEK variants address sterilization capacity constraints in remote surgical camp deployments.
Stainless steel anchors the volume base while titanium expands most quickly through academic center specification authority.
End User:
Customer type determines capital purchase versus consignment inventory terms, with ambulatory settings demanding working capital transfer to manufacturers.
- Hospitals:Tertiary pediatric centers in the United States maintain centralized sterile processing departments with validated autoclave protocols. These institutions specify complete instrument sets with RFID traceability integration for WHO surgical safety checklist compliance.
- Outpatient Clinics:Ambulatory surgical centers in India's private medical tourism corridors are collapsing historical hospital-centric procurement models. Operators demand just-in-time instrument availability through consignment arrangements without ownership overhead.
- Academic Institutions:Fellowship training programs require specialized microsurgical instrument configurations for craniofacial surgery resident education.
- Surgical Centers:Standalone pediatric facilities in Southeast Asian markets leverage e-procurement platforms to disintermediate traditional surgical supply distributors.
Hospitals anchor the volume base while outpatient clinics climb the fastest through ambulatory procedure migration.
Technology:
Maturity gradients separate established open-surgery instrument standards from capital-intensive platform adoption constrained by reimbursement coding uncertainty.
- Traditional:Conventional open-surgery instrument sets with manual retractors and direct visualization remain the default configuration for resource-constrained public hospital systems. These systems face replacement pressure as minimally invasive protocols diffuse from academic centers.
- Minimally Invasive:Fiber-optic retractor systems and micro-laparoscopic adaptations are gaining protocol adoption in US and Western European tertiary pediatric centers. Capital cost barriers limit penetration in developing economy settings despite superior visualization outcomes.
- Robotic-Assisted:da Vinci platform compatibility requirements are driving instrument standardization discussions as reimbursement coding evolves for cleft procedures.
- Laser:Er:YAG and CO2 laser systems for soft tissue incision remain niche applications with limited instrument integration.
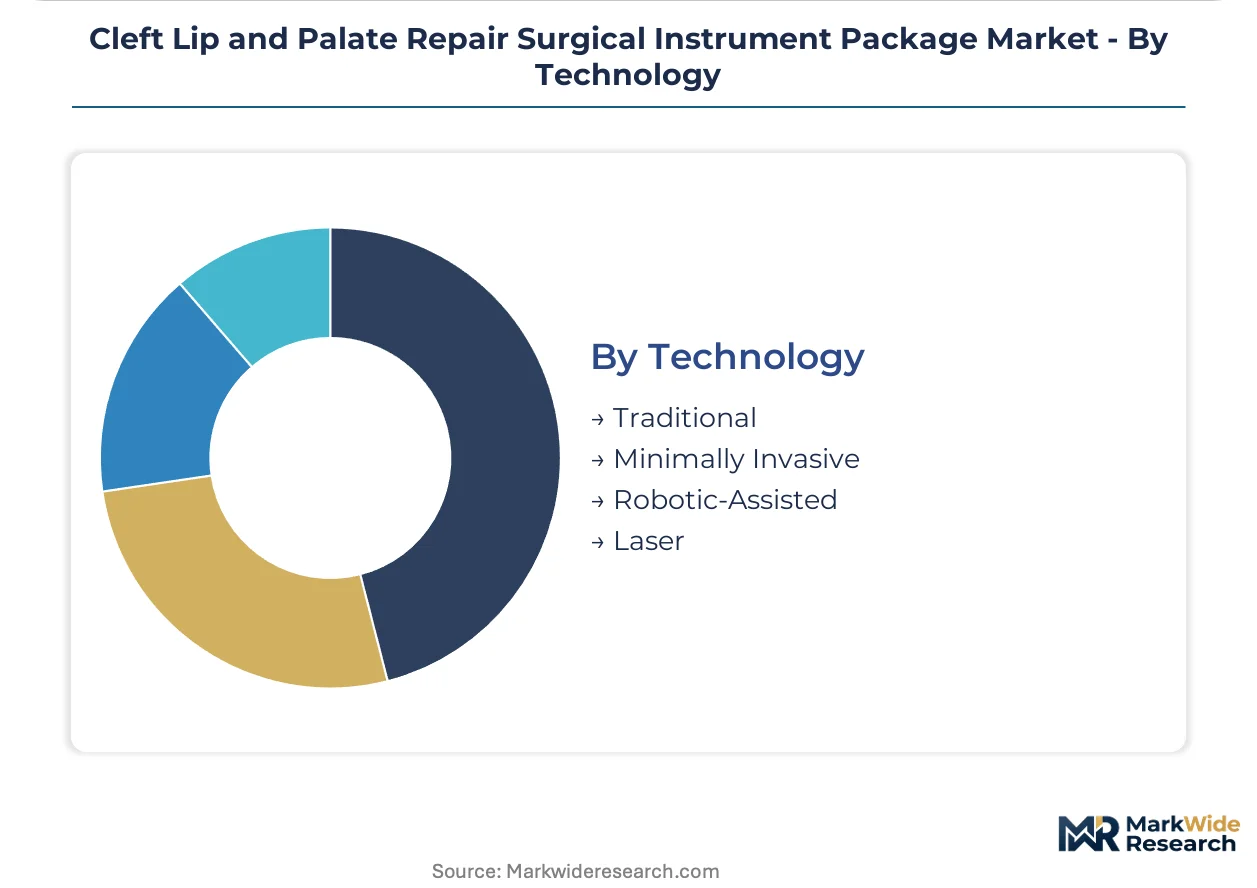
Traditional technology anchors the volume base while minimally invasive systems gain share at the steepest rate through academic center protocol leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision forges in Baden-Württemberg and North Rhine-Westphalia export titanium billets and finished instrument sets to pediatric surgical centers across the United States, India, and Western Europe, anchoring the trade-flow corridor for high-grade cleft repair instrumentation.
United States
Tertiary pediatric academic centers in Boston and Philadelphia drive specification authority for titanium alloy forceps and needle holders. FDA 510(k) clearance pathways under the Center for Devices and Radiological Health streamline premarket notification for reusable surgical instruments. Minneapolis-based Medtronic leverages integrated surgical workflow platforms to anchor high-volume contracts with ambulatory surgical centers.
Germany
Specialty stainless steel and titanium billet sourcing clusters in Tuttlingen and Solingen supply precision-forged instrument blanks to global manufacturers. EU Medical Device Regulation Annex I general safety and performance requirements elevate biocompatibility testing burdens for CE marking. KARL STORZ in Tuttlingen exemplifies the vertically integrated instrument fabricator archetype serving pediatric microsurgical protocols.
India
Government-funded cleft surgery missions and medical tourism infrastructure in Chennai and Hyderabad scale instrument procurement through centralized state tender processes. Central Drugs Standard Control Organization registration requirements under the Ministry of Health and Family Welfare govern import and distribution of reusable surgical instruments. Mumbai-based distributors are disintermediating traditional supply chains through direct-to-clinic e-procurement platforms.
Japan
Fellowship-trained craniofacial surgery programs in Tokyo and Osaka sustain demand for specialized microsurgical instrument configurations. Pharmaceuticals and Medical Devices Agency quality management reviews align with ISO 13485 standards to accelerate market access for foreign manufacturers. Nagoya-area precision metalworking clusters supply tungsten carbide inserts for scissors requiring extended autoclave durability.
United Kingdom
National Health Service procurement frameworks for specialized pediatric services concentrate instrument purchasing in London and Manchester teaching hospitals. Medicines and Healthcare products Regulatory Agency conformity assessment procedures enforce sterilization validation protocols for reusable devices. Oxford and Cambridge academic medical centers specify RFID-traceable instrument sets for WHO surgical safety checklist compliance.
Cleft Lip and Palate Repair Surgical Instrument Package Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with dedicated pediatric surgical divisions. The market exhibits moderate consolidation around integrated workflow platform providers and specialized instrument fabricators. Three archetypes dominate: precision-forge specialists with vertical control over titanium supply chains, diversified conglomerates bundling instruments with capital equipment platforms, and regional distributors building direct field service capabilities. Competitive moves concentrate on consignment inventory arrangements and ISO 13485 certification arbitrage to bypass jurisdiction-specific validation burdens.
Among diversified technology conglomerates, Medtronic and Stryker exemplify contrasting strategic positions. Medtronic anchors high-volume contracts through integrated surgical workflow platforms that bundle instrument packages with capital equipment and digital integration services. Stryker occupies a premium-tier position through specialized pediatric instrument configurations specified by academic medical centers for neonatal procedure suites. Olympus and KARL STORZ represent the precision-forge specialist archetype with concentrated expertise in fiber-optic visualization systems and microsurgical instrument geometries.
| Leading Market Players |
|---|
| Olympus |
| Richard WOLF |
| Medtronic |
| ConMed |
| Teleflex |
| Stryker |
| Boston Scientific |
| Cook Medical |
| KARL STORZ |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways and CE marking under EU MDR simultaneously gate supplier qualification and stratify price tiers, as manufacturers must absorb sterilization validation costs that concentrate margin pools in titanium alloy configurations while compressing commodity stainless steel pricing.
Pricing Analysis
Technology-generation pricing gaps separate traditional open-surgery instrument sets from fiber-optic minimally invasive systems and emerging robotic-compatible configurations. Three-tier pricing structure across premium, standard, and economy levels reflects material grade and certification burden, with titanium forceps commanding premium positioning through academic medical center specifications while AISI 420 stainless steel serves cost-sensitive Indian government tenders. Pricing pressure stems from consignment inventory models transferring working capital burden to manufacturers in India's ambulatory surgical center networks. Community hospitals in Southeast Asia exhibit highest price sensitivity, whereas US tertiary pediatric centers prioritize performance over unit cost.
Supply Chain Analysis
Consignment inventory arrangements are compressing lead times and forcing just-in-time manufacturing coordination between German precision forges and Indian distribution hubs. Specialty titanium and stainless steel billet sourcing clusters in Germany, Japan, and the United States feed precision-forged instrument blanks to global fabricators. Supply chain vulnerability rests on geographic concentration in Baden-Württemberg precision forges and Nagoya-area tungsten carbide insert suppliers. Single-source vulnerability in aerospace-grade Ti-6Al-4V ELI alloy creates exposure to export restriction shocks. Distribution runs through diversified channels: traditional surgical supply distributors in Western Europe, direct-to-clinic e-procurement platforms in Southeast Asia, and centralized state tender processes in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware as field sterilization validation, RFID traceability integration, and direct field service capabilities become recurring-revenue layers that manufacturers must build to secure ambulatory surgical center contracts.
For Market Incumbents: Shield installed base relationships by embedding ISO 13485-certified quality management into consignment inventory arrangements that lock out competitors from Indian medical tourism corridors. Deepen backward integration into titanium billet sourcing to mitigate Baden-Württemberg supply concentration risk. Invest in RFID-enabled surgical safety checklist compliance to defend against fiber-optic retractor substitution in tertiary pediatric centers. For New Entrants and Emerging Players: Differentiate on pediatric microsurgical training program partnerships that address craniofacial surgeon shortage constraints regardless of instrument availability. Target India's government-funded cleft surgery mission tenders with AISI 440 stainless steel configurations that undercut premium titanium pricing. Pursue direct-to-clinic digital distribution in Southeast Asian ambulatory networks to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-forge specialists holding captive titanium supply agreements and notified body partnerships for accelerated CE marking. Long-term viability hinges on manufacturers' ability to pivot from capital sales to service-attach revenue models across the analysis window. Monitor evolving reimbursement coding for robotic-assisted cleft procedures as inflection indicator for capital-intensive technology segment sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex I biocompatibility documentation accelerates multi-jurisdiction market access for qualified manufacturers. |
| Hospital System Partnership | Integrated workflow platform bundling secures high-volume contracts with US ambulatory surgical center networks. |
| Software Companion Development | RFID traceability integration enables WHO surgical safety checklist compliance in NHS procurement frameworks. |
| Reimbursement Strategy | Robotic-assisted procedure coding evolution determines capital equipment segment viability in tertiary pediatric centers. |
| Backward Integration | Captive titanium billet supply mitigates geographic concentration risk in German precision forge clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body conformity assessments, Indian CDSCO import registrations, and hospital procurement contract disclosures. Interviews with pediatric craniofacial surgeons, biomedical engineering directors, GPO contracts managers, and sterile processing department heads informed demand-side validation. Top-down trade flow analysis of German titanium billet exports and bottom-up procedure volume modeling across India's government-funded surgical missions were cross-referenced to anchor volume estimates.
Segmentation dimensions modeled include material composition tier, technology sophistication level, end-user facility type, and geographic regulatory cluster across the projection horizon. CAGRs were derived from procedure volume trajectories, instrument replacement cycle compression under tightened sterilization protocols, and titanium alloy specification diffusion rates through academic medical center procurement committees. Forecast inputs incorporate pediatric microsurgical training pipeline constraints and evolving reimbursement classifications for minimally invasive platforms.
The analysis sits within stated boundaries; outcomes outside sustained government funding for cleft surgery missions, stable titanium alloy supply from German forges, or unchanged FDA 510(k) clearance pathways would require recalibration. Forecasts reflect documented assumptions regarding procedure volume growth and material substitution elasticities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Global Veterinary Surgical Instruments Market