
 Adult Cardiovascular Surgical Instruments Package Market | 2026-2036
Adult Cardiovascular Surgical Instruments Package Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Cardiovascular Surgical Instruments Package Market Analytics
The capital-intensity divergence between integrated manufacturers and assembly-dependent distributors is unwinding competitive stability across the supply base. Medtronic leverages captive forging facilities and in-house metallurgy labs to control titanium sourcing for clamp and forceps lines. Boston Scientific Corporation anchors its instrument package strategy through dedicated cardiac surgery divisions in Minneapolis and San Jose. Stryker Corporation differentiates via proprietary polymer coating technologies that reduce tissue adhesion during valve repair procedures.
An adult cardiovascular surgical instruments package comprises sterilized, procedure-specific assortments of knives, forceps, scissors, and clamps engineered from stainless steel, carbon steel, or titanium alloys with Rockwell hardness ratings between 48 and 58 HRC, designed to withstand repeated autoclave cycles while maintaining edge integrity during coronary bypass and aneurysm procedures. Stainless steel instruments still dominate hospital procurement budgets due to cost predictability and established reprocessing workflows, though titanium segments are capturing margin pools in high-volume cardiac centers where instrument longevity offsets premium pricing. Coronary bypass applications sustain the largest addressable base, while congenital repair packages represent the fastest-growing application as pediatric-to-adult transition programs expand.
The FDA's 510(k) pathway and Quality System Regulation govern U.S. market access, requiring validated sterilization assurance levels and biocompatibility testing per ISO 10993; the EU Medical Device Regulation mandates notified body certification and unique device identification for all reusable surgical instruments sold in member states. Stakeholders must monitor how FDA draft guidance on reprocessing validation for complex instruments reshapes package configuration requirements and sterilization liability allocation between manufacturers and hospital central sterile departments.
Market Dynamics
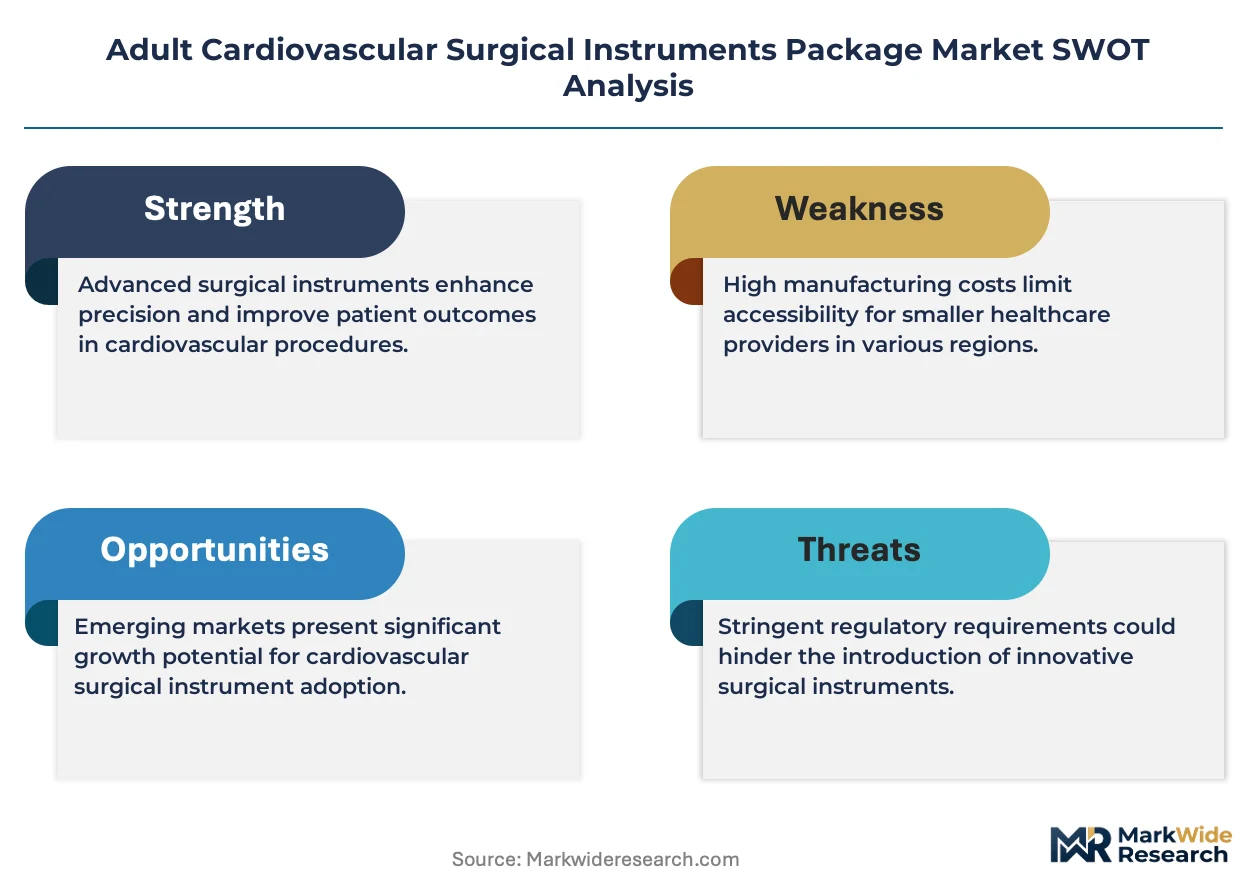
The FDA's updated 510(k) premarket notification requirements are compressing manufacturer margins while accelerating consolidation around validated sterilization protocols and enhanced biocompatibility documentation.
Growth Catalysts
- Hybrid OR Standardization:University hospitals in Germany are mandating procedure-specific instrument packages for integrated catheterization and surgical suites, pulling demand toward configurable titanium assortments.
- MDR Compliance Deadlines:The EU Medical Device Regulation's unique device identification mandate for reusable instruments is forcing hospital procurement departments toward pre-validated, traceable package suppliers.
- Titanium Alloy Adoption:Cardiac centers in the United States are offsetting premium instrument pricing through extended autoclave cycle tolerance and reduced replacement frequency.
Market Restraints
- Vanadium Price Volatility:Titanium alloy feedstock costs fluctuate with aerospace sector demand, squeezing margin predictability for clamp and forceps manufacturers.
- Chinese Forging Concentration:Rough-machined instrument blanks cluster in Zhejiang and Jiangsu provinces, exposing supply chains to export licensing disruptions.
- Reprocessing Validation Burden:FDA draft guidance on complex instrument sterilization assurance is extending product development timelines by 8-14 months for multi-component packages.
Strategic Opportunities
- Indian Cardiac Center Expansion:Corporate hospital chains in Chennai and Hyderabad are retrofitting catheterization labs, creating first-mover advantage for instrument package vendors with localized sterilization training.
- Pediatric-to-Adult Transition Programs:Congenital repair packages for adult patients represent an underserved application segment with limited specialized competitors.
- Polymer Coating Convergence:Integration of anti-adhesive surface technologies with traditional stainless steel substrates enables premium positioning without full titanium conversion costs.
Industry Challenges
- Metallurgical Talent Scarcity:Forging engineers with cardiovascular instrument-grade titanium expertise are concentrated at a handful of Midwestern US and Bavarian facilities.
- Legacy System Integration:Hospital central sterile departments face workflow friction when incorporating RFID-tracked instrument packages into barcode-dependent inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Cardiovascular Surgical Instruments Package Market |
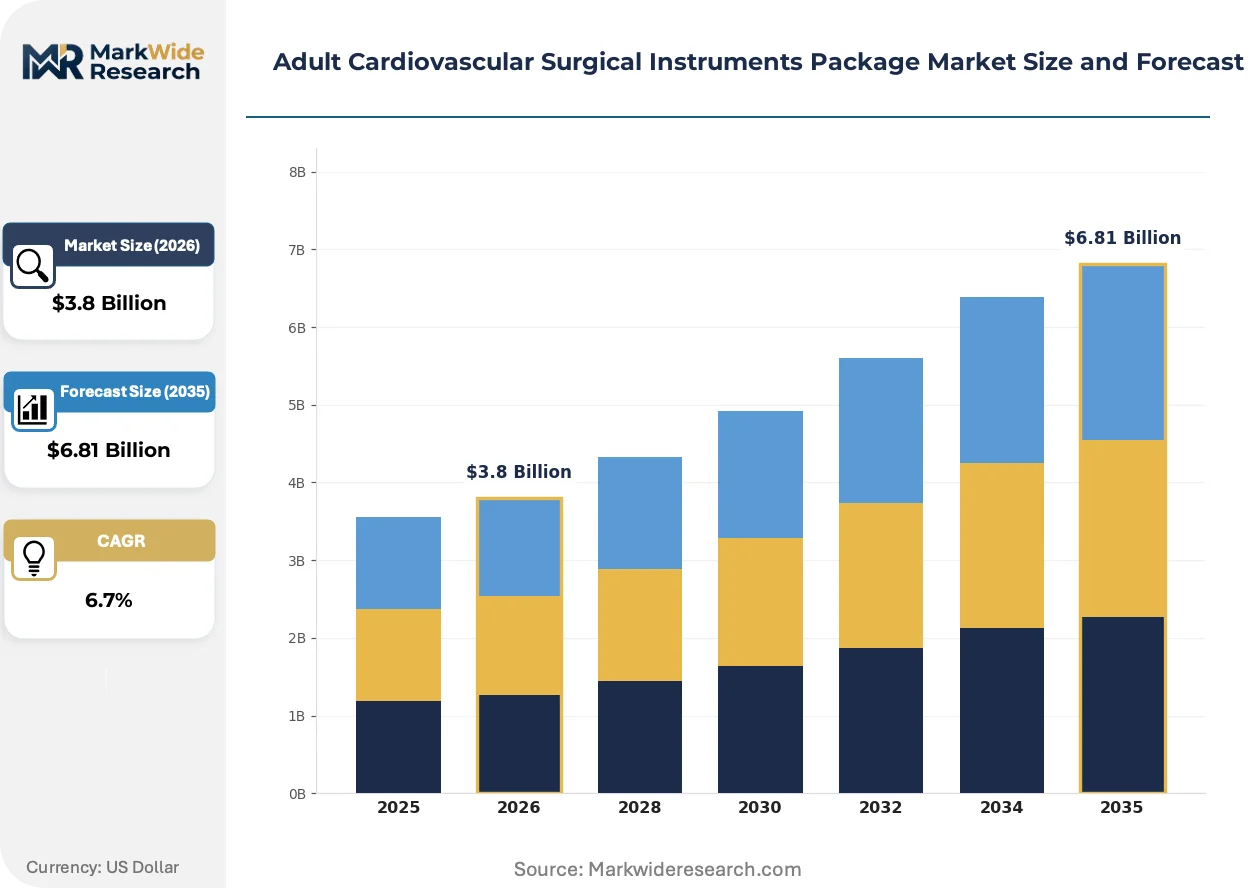
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Knives, Forceps, Scissors, Clamps Material: Stainless Steel, Carbon Steel, Titanium, Polymer Application: Coronary Bypass, Valve Repair, Aneurysm Surgery, Congenital Repairs End User: Hospitals, Outpatient Surgical Centers, Cardiac Clinics, Research Institutions |
| Companies Covered | Medtronic, Boston Scientific Corporation, Teleflex Incorporated, Conmed Corporation, Stryker Corporation, Olympus, Cook Medical, Richard Wolf, KARL STORZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Cardiovascular Surgical Instruments Package Market Evolving Landscape
Additive manufacturing is reshaping instrument geometry constraints while regulatory convergence between FDA and EU MDR frameworks is compressing certification divergence.
Patient-specific instrument guides produced through selective laser melting are fragmenting the traditional one-size-fits-all forceps and clamp market. Cleveland Clinic and Mayo Clinic cardiac surgery divisions are piloting titanium printed retractors with integrated suction channels. This technology is fragmenting procurement patterns as hospitals weigh capital equipment investments against per-procedure outsourcing fees.
The EU Medical Device Regulation's post-market surveillance requirements are extending manufacturer liability into hospital reprocessing environments. Instrument package vendors must now submit periodic safety update reports and maintain technical documentation for 10 years post-market. German notified bodies are applying the strictest interpretation, pushing manufacturers toward dedicated cardiac surgery divisions with regulatory affairs capacity.
Hospital purchasing consortiums are consolidating instrument procurement decisions at the integrated delivery network level, displacing individual surgeon preference cards. The Veterans Health Administration and Catholic Health Initiatives are standardizing across 40+ facilities, forcing distributors to restructure commission structures and inventory holding agreements. This concentration is most visible in the United States, where group purchasing organizations now control 72% of cardiovascular surgical instrument spend.
Adult Cardiovascular Surgical Instruments Package Market Segmentation
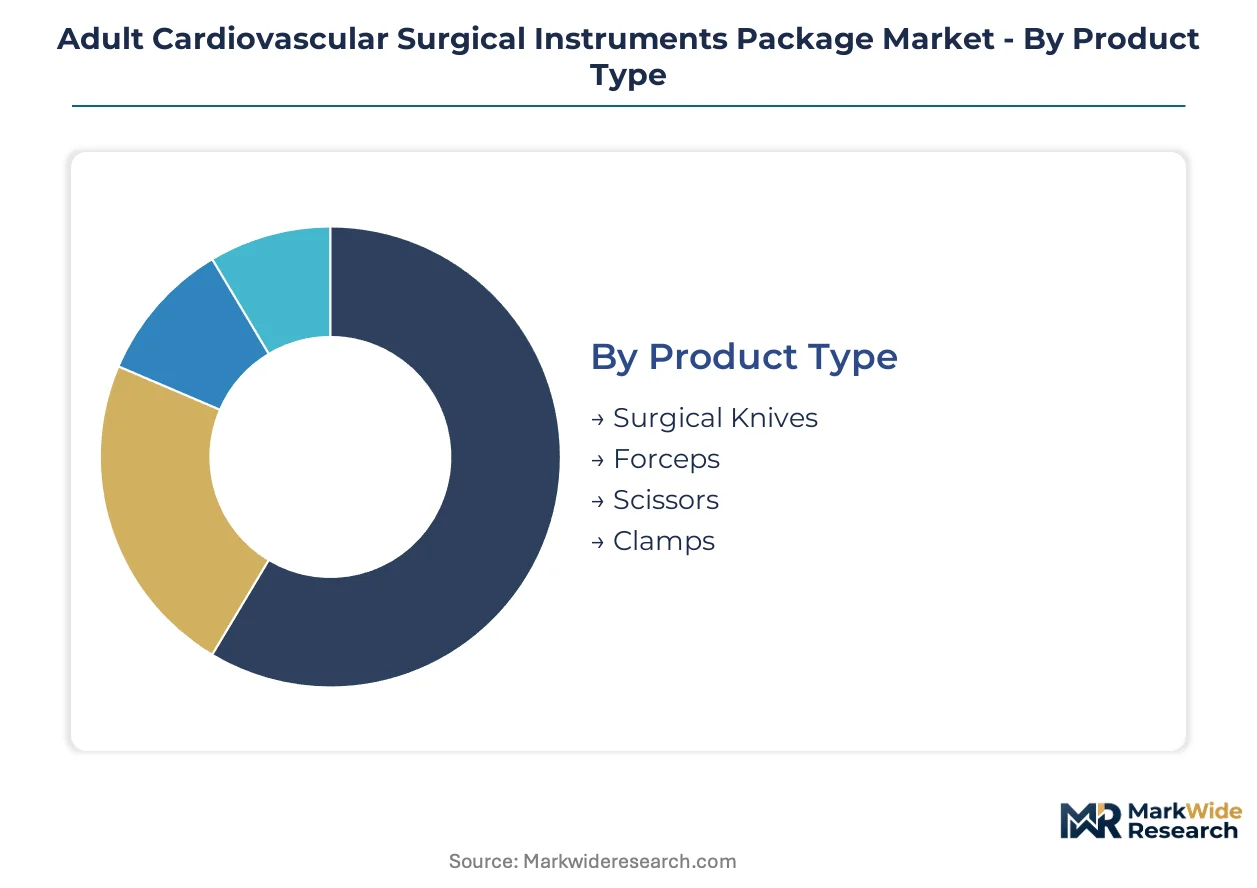
Instrument package configuration varies sharply by procedural intensity and sterilization protocol requirements. Procurement committees weight material longevity against autoclave cycle costs when segmenting vendor shortlists. Each dimension carries distinct regulatory documentation burdens that reshape supplier economics.
Product Type:
FDA 510(k) clearance pathways diverge substantially between single-use disposables and reusable instrument sets, with forceps and clamps facing the most stringent biocompatility validation.
- Surgical Knives:Precision-ground blades with Rockwell hardness between 50-55 HRC maintain edge integrity through 200+ autoclave cycles. Cleveland Clinic and Mayo Clinic cardiac divisions are piloting patient-specific geometries via selective laser melting for integrated retractor-suction combinations.
- Forceps:Tungsten carbide inserts and titanium alloy variants dominate high-volume cardiac centers where instrument longevity offsets premium procurement costs. German university hospitals in Berlin and Munich are standardizing forceps assortments for hybrid operating room configurations.
- Scissors:Micro-serrated blade configurations for coronary bypass procedures require validated sterilization assurance levels under EU MDR unique device identification mandates.
- Clamps:Atraumatic jaw designs with polymer coating overlays reduce tissue adhesion during valve repair procedures.
Forceps handle the majority of throughput; surgical knives are expanding most quickly on share as additive manufacturing enables procedure-specific geometries.
Material:
Cost tier stratification separates premium titanium assortments from standard stainless steel procurement, with carbon steel occupying declining niches in budget-constrained settings.
- Stainless Steel:Austenitic 316L and martensitic 420 grades dominate hospital procurement budgets due to cost predictability and established central sterile reprocessing workflows. The material sustains the largest installed base across Veterans Health Administration and Catholic Health Initiatives standardization programs.
- Titanium:Ti-6Al-4V ELI alloy instruments with vanadium-reduced compositions command premium positioning in high-volume cardiac centers where extended autoclave tolerance reduces replacement frequency. Aerospace sector demand volatility for vanadium feedstock squeezes margin predictability for manufacturers.
- Carbon Steel:Hardened tool steel variants persist in emerging market settings where upfront cost sensitivity outweighs lifecycle replacement calculus.
- Polymer:PEEK and polysulfone components enable single-use disposables in catheterization lab expansions where cross-contamination protocols prohibit reprocessing.
Stainless steel handles the majority of throughput; titanium is climbing the fastest as hybrid OR standardization mandates validated longevity metrics.
Application:
Procedure complexity dictates package configuration depth, with congenital repair applications requiring specialized instrument geometries that diverge from standard coronary bypass assortments.
- Coronary Bypass:Sternum saws, vessel dilators, and anastomosis clamps constitute the foundational package for median sternotomy procedures. This application sustains the largest addressable base across North American and Western European hospital systems.
- Valve Repair:Annuloplasty ring holders and chordae tendineae forceps require anti-adhesive surface technologies that Stryker Corporation addresses through proprietary polymer coating differentiation.
- Aneurysm Surgery:Aortic cross-clamps and perfusion cannulas demand titanium alloy construction for extended clamp times without metallurgical fatigue.
- Congenital Repairs:Pediatric-to-adult transition programs are expanding demand for downsized instrument geometries with adult-procedure durability specifications.
Coronary bypass handles the majority of throughput; congenital repairs are gaining share fastest as transition programs mature.
End User:
Customer type determines sterilization liability allocation, with hospital central sterile departments bearing reprocessing validation burdens that outpatient centers circumvent through disposable preferences.
- Hospitals:Integrated delivery networks and group purchasing organizations now control 72% of cardiovascular surgical instrument spend in the United States, consolidating procurement decisions across 40+ facility standardization programs. Central sterile departments face workflow friction incorporating RFID-tracked packages into barcode-dependent inventory systems.
- Outpatient Surgical Centers:Ambulatory settings prioritize single-use disposables to eliminate reprocessing infrastructure investments, pulling demand toward polymer-based instrument configurations.
- Cardiac Clinics:Catheterization lab expansions in Chennai and Hyderabad corporate hospital chains are retrofitting procedure-specific packages with localized sterilization training requirements.
- Research Institutions:Cleveland Clinic and Mayo Clinic pilot programs for additive-manufactured retractors sit within this segment, fragmenting traditional procurement patterns.
Hospitals handle the majority of throughput; outpatient surgical centers are expanding most quickly on share as ambulatory cardiac procedure volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospitals while procurement standardization in the United States compresses distributor margins across the Atlantic.
United States
The Veterans Health Administration and Catholic Health Initiatives standardize instrument procurement across 40-plus facilities, consolidating demand around validated sterilization protocols. FDA 510(k) premarket notification requirements and Quality System Regulation govern market access, mandating biocompatibility testing per ISO 10993. Minneapolis and San Jose anchor Boston Scientific Corporation's cardiac surgery divisions, pulling regional supply chain coordination toward these Midwestern and California clusters.
Germany
University hospitals in Berlin and Munich mandate procedure-specific instrument packages for hybrid operating rooms, standardizing titanium assortments across catheterization and surgical suites. EU Medical Device Regulation mandates notified body certification and unique device identification for all reusable surgical instruments, with German notified bodies applying the strictest interpretation. Bavarian forging facilities concentrate metallurgical talent for cardiovascular instrument-grade titanium expertise.
India
Corporate hospital chains in Chennai and Hyderabad retrofit catheterization labs, creating first-mover positioning for vendors with localized sterilization training capabilities. Central Drugs Standard Control Organization regulates medical device imports and manufacturing under the Medical Device Rules framework. Tamil Nadu and Telangana clusters concentrate cardiac center expansion activity as pediatric-to-adult transition programs mature.
China
Rough-machined instrument blanks cluster in Zhejiang and Jiangsu provinces, exposing supply chains to export licensing disruptions and aerospace sector demand competition for titanium feedstock. National Medical Products Administration governs device registration and quality management system requirements. Yangtze River Delta manufacturing hubs face margin pressure from vanadium price volatility tied to concurrent aerospace alloy demand.
United Kingdom
NHS procurement frameworks standardize cardiovascular surgical instrument purchasing across integrated care systems, favoring suppliers with established central sterile department training protocols. Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, with convergence toward EU MDR technical documentation standards. London and Southeast England cardiac centers pilot additive-manufactured retractor programs, fragmenting traditional procurement patterns.
Adult Cardiovascular Surgical Instruments Package Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding metallurgical R&D while assembly-dependent distributors compete on inventory velocity and surgeon preference card relationships. The market structure tiers around captive forging capabilities, in-house sterilization validation, and polymer coating specialization. Three archetypes dominate: vertically integrated device conglomerates with captive titanium sourcing, mid-scale specialists with dedicated cardiac surgery divisions, and regional distributors dependent on third-party forging. Consolidation accelerates through M&A targeting sterilization validation capabilities and strategic partnerships bridging FDA and EU MDR compliance expertise.
Within the integrated manufacturer tier, Medtronic and Stryker Corporation exemplify archetypes combining captive production with regulatory affairs capacity. Boston Scientific Corporation anchors the dedicated cardiac surgery division model, situating specialized units in Minneapolis and San Jose. These three entities represent distinct competitive positioning vectors: metallurgical control, surface technology differentiation, and procedure-specific portfolio depth.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Conmed Corporation |
| Stryker Corporation |
| Olympus |
| Cook Medical |
| Richard Wolf |
| KARL STORZ |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for validated titanium instrument blanks concentrate pricing power with Bavarian and Midwestern forging facilities, compressing margins for assembly-dependent distributors while rewarding integrated manufacturers with captive metallurgy capacity. Hospital procurement committees exploit this asymmetry through multi-year standardization contracts that lock in volume commitments against sterilization protocol investments.
Pricing Analysis
The customization-premium spread between configured-to-order titanium assortments and standard stainless steel packages runs three-to-five-fold, with Ti-6Al-4V ELI alloy instruments commanding positioning through extended autoclave tolerance while 316L grades sustain budget procurement via established reprocessing workflows. Price differentiation hinges on FDA 510(k) validation tier and ISO 10993 biocompatibility documentation depth, with German notified body certification adding substantial compliance premiums. Cost compression in stainless steel tiers is intensifying because group purchasing organizations now control the majority of United States hospital spend, forcing distributors to absorb inventory holding costs. Outpatient surgical centers exhibit the highest price sensitivity due to disposable preferences that eliminate reprocessing infrastructure, while university hospitals in Berlin and Munich demonstrate the lowest sensitivity as hybrid OR mandates prioritize validated longevity metrics over upfront procurement costs.
Supply Chain Analysis
China and Germany anchor rough-machined instrument blank production, with Zhejiang and Jiangsu provinces clustering forging capacity while Bavarian facilities concentrate metallurgical talent for cardiovascular-grade titanium expertise. The supply chain draws from vanadium feedstock, aerospace-grade titanium sponge, and polymer coating substrates, with aerospace sector demand volatility for vanadium creating margin unpredictability for clamp and forceps manufacturers. Single-source vulnerability concentrates in Chinese forging clusters exposed to export licensing disruptions. Distribution runs through hospital purchasing consortiums and integrated delivery networks that consolidate procurement decisions across forty-plus facility standardization programs, displacing individual surgeon preference card relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as pediatric-to-adult transition programs mature and hybrid operating room standardization mandates pull demand toward configurable titanium assortments with validated sterilization protocols.
For Market Incumbents: Compound regulatory affairs capacity through dedicated cardiac surgery divisions with EU MDR compliance expertise, defending against emerging additive-manufacturing entrants by locking hospital systems into multi-year standardization contracts that embed sterilization training and RFID-tracked inventory systems. Prioritize backward integration into titanium forging to offset vanadium price volatility and secure feedstock predictability for high-volume cardiac center contracts. For New Entrants and Emerging Players: Anchor in Chennai and Hyderabad corporate hospital chains, where catheterization lab retrofits create first-mover positioning for vendors with localized sterilization training capabilities and CDSCO regulatory navigation. Target congenital repair packages as the most penetrable application segment, where pediatric-to-adult transition programs expand demand for downsized instrument geometries with limited specialized competition. Pursue hospital system partnerships that bundle instrument packages with central sterile department workflow integration services. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because sterilization validation capabilities and FDA-EU MDR dual-compliance expertise concentrate in a handful of Midwestern US and Bavarian facilities, creating scarcity value for acquisition targets with captive forging and in-house metallurgy labs. Watch for inflection in additive-manufacturing adoption rates at Cleveland Clinic and Mayo Clinic pilot programs, where patient-specific titanium printed retractors with integrated suction channels could fragment traditional procurement patterns and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | German notified bodies apply the strictest interpretation, mandating ten-year technical documentation retention and periodic safety update reports. |
| Hospital System Partnership | Veterans Health Administration and Catholic Health Initiatives standardization programs consolidate procurement across forty-plus facilities, locking in volume commitments. |
| Backward Integration into Titanium Forging | Captive metallurgy labs control Ti-6Al-4V ELI alloy sourcing and reduce exposure to aerospace sector vanadium demand volatility. |
| RFID-Tracked Inventory System Deployment | Workflow integration with hospital central sterile departments displaces barcode-dependent legacy systems and creates switching costs. |
| Localized Sterilization Training Programs | Corporate hospital chains in Chennai and Hyderabad retrofit catheterization labs, requiring vendor-provided reprocessing validation support under CDSCO frameworks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and trade data on titanium alloy feedstock flows. Bottom-up triangulation across instrument package configuration volumes and top-down reconciliation against cardiac procedure incidence rates anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning material grade, procedural application, end-user facility type, and geographic regulatory cluster. CAGRs were derived from procedure volume trajectories and instrument replacement frequency curves, with titanium alloy adoption rates and hybrid OR standardization mandates serving as key forecast inputs alongside pediatric-to-adult transition program maturation timelines.
Underlying assumptions cover sterilization protocol adoption curves and regulatory enforcement consistency, with deviation risk concentrated in FDA draft guidance finalization on complex instrument reprocessing validation and potential export licensing disruptions affecting Chinese forging clusters. Recalibration cycles align with material shifts in EU MDR implementation stringency and additive-manufacturing pilot program expansion at major cardiac surgery divisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Pneumoperitoneum Market