
 UAE Bariatric Surgery Market | 2026-2036
UAE Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Bariatric Surgery Market Analytics
Asset-light leasing models for surgical staplers and energy devices are tilting competitive dynamics toward hospitals that avoid capital-heavy equipment purchases. Stryker leverages its broad instruments portfolio to sustain recurring revenue from consumable attachments. Medtronic anchors its position through integrated OR systems that bundle monitoring with stapling platforms. Cleveland Clinic Abu Dhabi competes on clinical outcomes transparency and international accreditation.
UAE bariatric surgery encompasses restrictive and malabsorptive procedures performed laparoscopically to reduce stomach volume or alter nutrient absorption, typically requiring stapling devices calibrated to 3.5 mm or 4.8 mm closed heights depending on tissue thickness. Sleeve gastrectomy dominates procedure volumes due to lower complication profiles and shorter operative times compared to gastric bypass. Inpatient delivery mode still captures the majority of revenue per case, though ambulatory surgical centers are carving share for select low-BMI cohorts. Hospitals retain the deepest margin pools because bundled pricing captures anesthesia, imaging, and multi-day stays.
MOHAP facility licensing rules and Dubai Health Authority clinical governance frameworks mandate minimum annual case volumes and specialized surgeon credentials for bariatric program approval. The UAE's mandatory health insurance reforms under the DHA and MOHAP schemes increasingly cover metabolic surgery for BMI thresholds above 35 with comorbidities. Stakeholders must monitor how prior authorization requirements evolve as insurers scrutinize outcomes data to limit revision surgeries.
Market Dynamics
MOHAP's tightened facility accreditation standards for metabolic surgery are compressing market access to tertiary hospitals with dedicated bariatric units, forcing smaller clinics to exit or affiliate with accredited chains.
Growth Catalysts
- Mandatory health insurance reforms:DHA and MOHAP schemes now cover metabolic surgery for BMI thresholds above 35 with comorbidities, expanding addressable patient pools.
- Laparoscopic technique maturation:Sleeve gastrectomy's lower complication profiles and shorter operative times are pulling volume from open procedures in Dubai and Abu Dhabi facilities.
- Private hospital expansion:Hospital chains across the emirates are building dedicated bariatric service lines to capture bundled pricing for anesthesia, imaging, and multi-day stays.
Market Restraints
- Capital equipment intensity:Surgical staplers and energy devices require substantial upfront investment, limiting program launches to well-capitalized facilities.
- Surgeon credential scarcity:MOHAP mandates specialized surgeon credentials and minimum annual case volumes, creating bottlenecked program approval timelines.
- Prior authorization scrutiny:Insurers are tightening outcomes-data requirements to limit revision surgeries, compressing reimbursement certainty.
Strategic Opportunities
- Ambulatory surgical center carve-out:Low-BMI cohorts are shifting to ASCs for select procedures, opening volume outside traditional inpatient capture.
- Asset-light leasing models:Surgical stapler and energy device leasing is reducing capital barriers for mid-tier hospitals entering metabolic surgery.
- Integrated OR system bundling:Monitoring-stapling platform convergence offers margin expansion through consumable attachment recurring revenue.
Industry Challenges
- Revision surgery complexity:Prior authorization requirements for re-operations demand extensive documentation, stretching administrative bandwidth.
- Multi-disciplinary team assembly:Bariatric program accreditation requires coordinated anesthesia, nutrition, and psychology staffing that strains recruitment pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Bariatric Surgery Market |
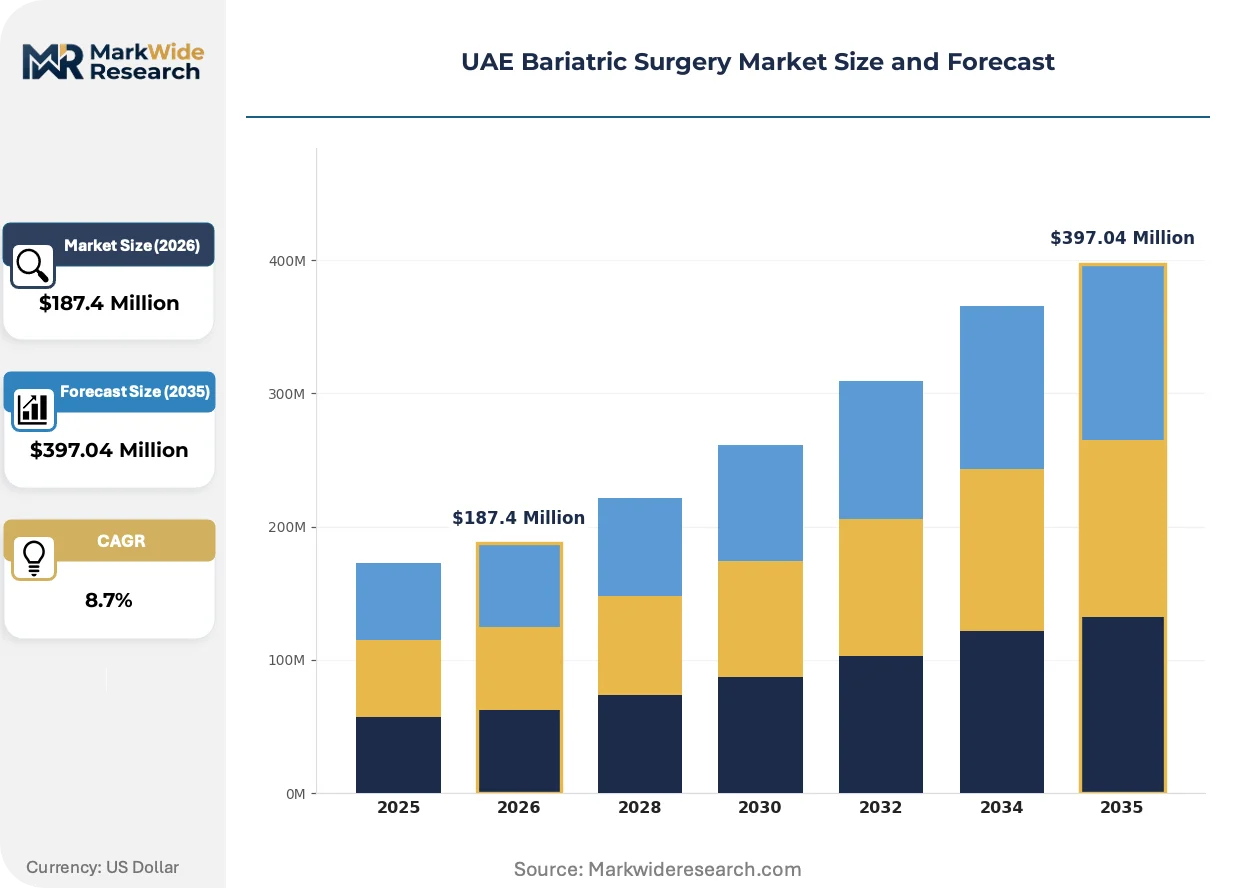
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion Delivery Mode: Inpatient, Outpatient, Telemedicine, Home Care End User: Hospitals, Specialized Clinics, Ambulatory Surgical Centers, Weight Loss Centers Patient Profile: Obese Adults, Adolescents, Elderly Patients, High-Risk Patients |
| Companies Covered | Conmed Corporation, Stryker, Medtronic, Olympus, Becton Dickinson, Johnson & Johnson, B. Braun, Cleveland Clinic Abu Dhabi, Apollo Endosurgery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Bariatric Surgery Market Evolving Landscape
Surgical platform convergence and reimbursement model evolution are restructuring how metabolic services are delivered and monetized across the emirates.
Robotic-assisted stapling platforms are hybridizing laparoscopic precision with automated tissue sensing, enabling consistent staple line integrity across variable gastric wall thickness. Tertiary hospitals in Dubai are adopting these systems to reduce leak rates and justify premium bundled pricing. The technology is hybridizing procedure standardization with surgeon-specific customization, compressing outcome variance between high and low-volume operators.
MOHAP facility licensing rules now mandate minimum annual case volumes and specialized surgeon credentials for bariatric program approval, filtering market participation toward established chains. The regulation is accelerating affiliation strategies among smaller clinics seeking accredited partner status. Dubai Health Authority clinical governance frameworks are tightening parallel to MOHAP standards, affecting program expansion timelines across private hospital groups.
Clinical outcomes transparency is displacing marketing-based patient acquisition in metropolitan Dubai and Abu Dhabi. Cleveland Clinic Abu Dhabi's published complication and readmission data is setting benchmark expectations that competing facilities must match. This shift is most visible among insured patient segments where employer health plans are steering volume toward accredited centers with demonstrable quality metrics.
UAE Bariatric Surgery Market Segmentation
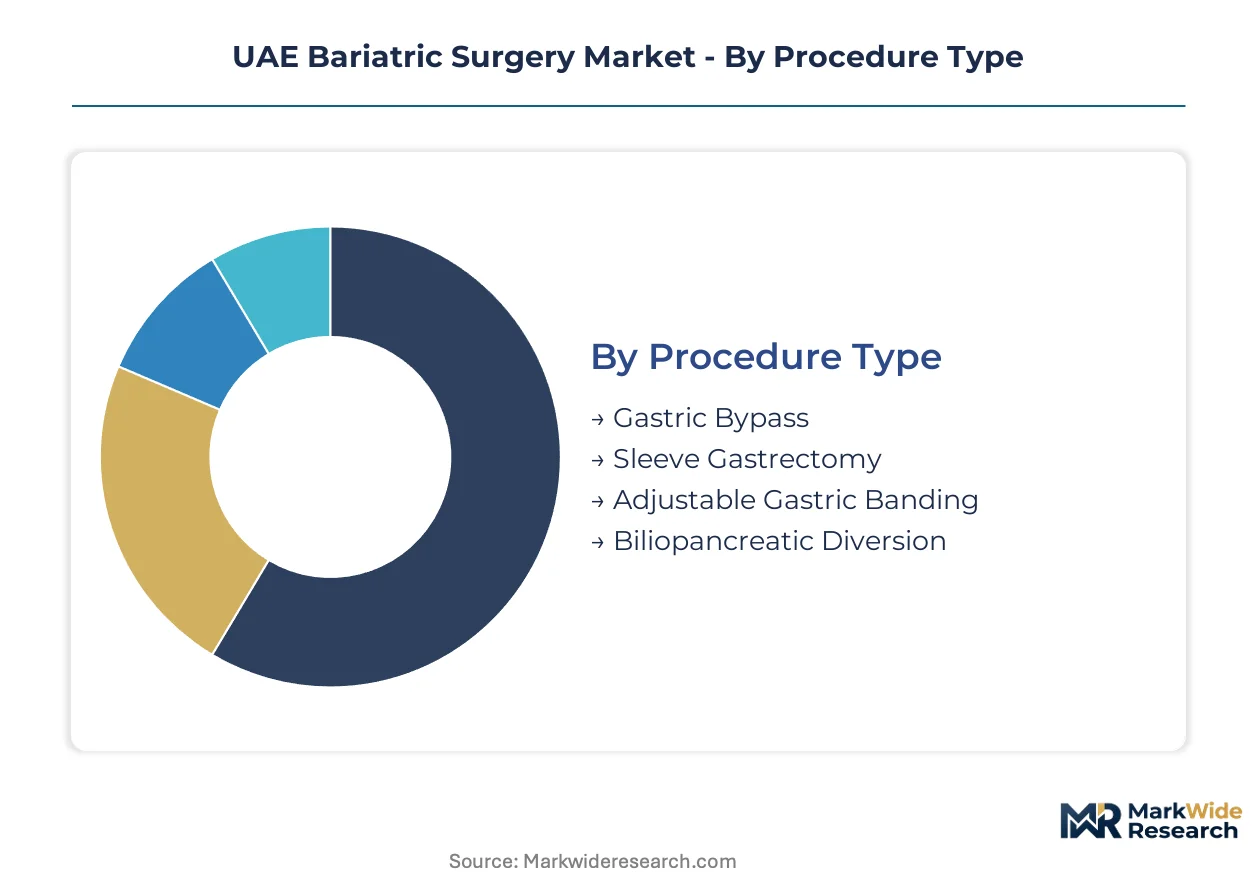
UAE bariatric surgery segmentation reveals how procedure economics, care settings, and patient risk profiles determine where capital deploys and margins concentrate. Understanding these splits exposes which service lines justify dedicated infrastructure investment versus leased capacity models.
Procedure Type:
Use-case spectrum spans restrictive volume reduction through malabsorptive nutrient diversion, with technique selection directly determining stapler specifications and operative complexity.
- Sleeve Gastrectomy:Laparoscopic resection of the gastric fundus creates a tubular stomach remnant calibrated to 150-200ml capacity. Dubai's tertiary hospitals with dedicated bariatric units capture concentrated demand due to shorter operative times and lower leak rates compared to bypass alternatives.
- Gastric Bypass:Roux-en-Y reconstruction partitions the stomach into a 30ml pouch with jejunal limb anastomosis, requiring dual staple lines at 3.5mm and 4.8mm closed heights. Abu Dhabi's Cleveland Clinic and similar accredited centers steer high-BMI diabetic patients toward this modality for superior metabolic remission rates.
- Adjustable Gastric Banding:Laparoscopic placement of a silicone prosthesis with subcutaneous port access enables postoperative restriction adjustment without permanent anatomical alteration.
- Biliopancreatic Diversion:Malabsorptive technique combining distal gastrectomy with ileal switch, reserved for super-obese cohorts with specialized nutritional support infrastructure.
The dominant share belongs to Sleeve Gastrectomy, while Gastric Bypass is closing the gap fastest among diabetic patient segments seeking metabolic disease reversal.
Delivery Mode:
Cost tier stratification separates capital-intensive inpatient infrastructure from leaner outpatient models targeting lower-acuity procedures.
- Inpatient:Multi-day hospitalization bundles anesthesia, imaging, and complication management into single-case pricing. Dubai Health Authority-licensed facilities retain deepest margin pools through this mode, particularly for revision surgeries and high-BMI cohorts requiring intensive care backup.
- Outpatient:Same-day discharge protocols applied to uncomplicated primary sleeve procedures in select low-BMI patients with robust home support systems.
- Telemedicine:Preoperative optimization and postoperative dietary counseling delivered remotely, reducing in-person visits for rural Emirate patients.
- Home Care:Wound management and early mobilization support for stable postoperative patients with family caregiver availability.
Inpatient delivery commands the revenue concentration, though Outpatient is expanding most quickly as ambulatory surgical centers gain MOHAP accreditation for select procedure categories.
End User:
Customer type fragmentation tracks how facility scale and accreditation status determine which institutions can meet tightening MOHAP program standards.
- Hospitals:Tertiary institutions with minimum annual case volume requirements and multi-disciplinary team staffing dominate complex metabolic surgery. Bundled pricing across anesthesia, radiology, and inpatient beds sustains margin depth unavailable to smaller competitors.
- Ambulatory Surgical Centers:Asset-light facilities carving volume from uncomplicated primary procedures, leveraging leased stapler platforms to avoid capital intensity.
- Specialized Clinics:Affiliation-dependent operators seeking accredited hospital partnerships to maintain program legitimacy under tightened licensing rules.
- Weight Loss Centers:Non-surgical facilities providing medical management and referral pipelines to approved surgical programs.
Hospitals retain structural dominance, while Ambulatory Surgical Centers are gaining share fastest among insured low-BMI cohorts meeting strict selection criteria.
Patient Profile:
Volume concentration and risk stratification determine which demographics justify premium bundled pricing versus standardized reimbursement tiers.
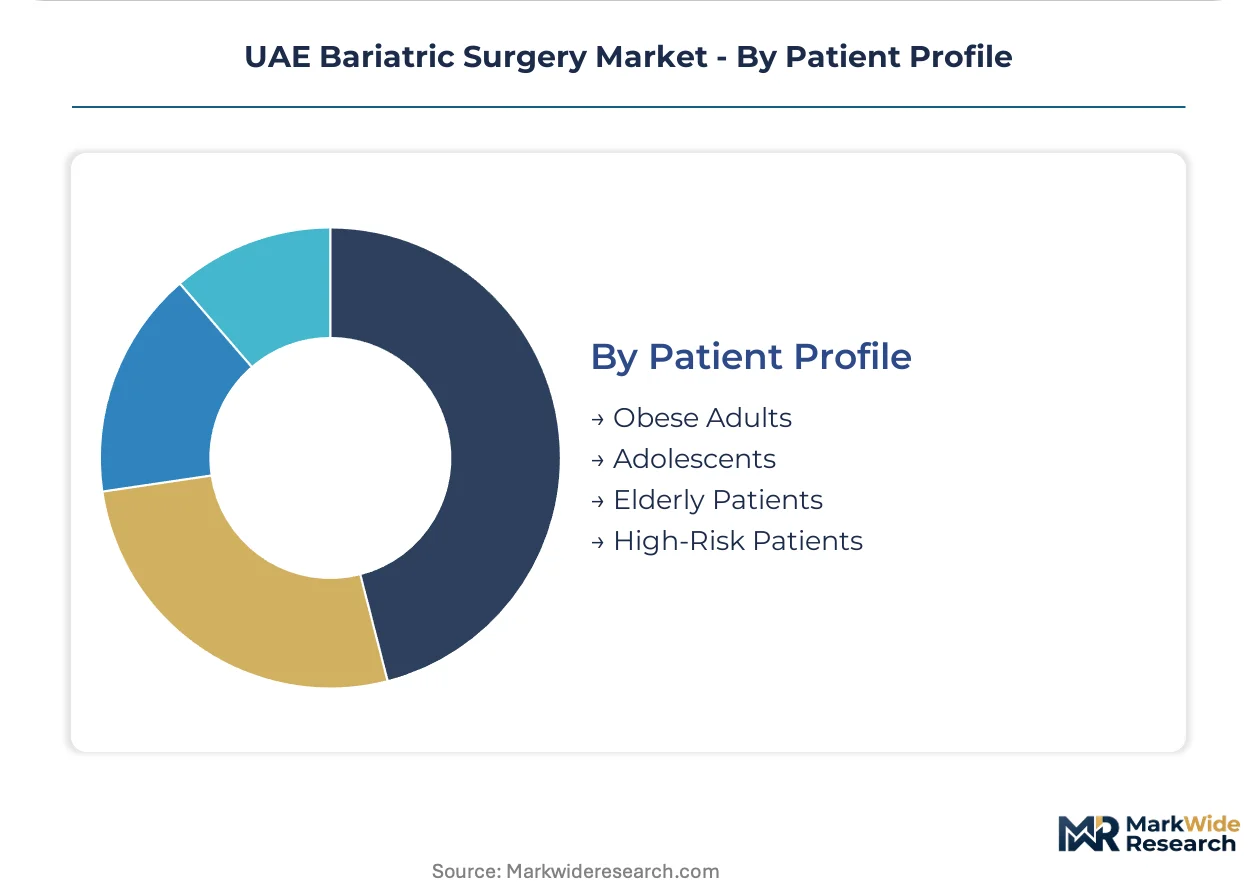
- Obese Adults:BMI 35-50 cohort with metabolic comorbidities constitutes the core addressable population under DHA and MOHAP insurance mandates. Dubai employer health plans steer this volume toward accredited centers with published outcomes transparency.
- High-Risk Patients:BMI above 50 or significant cardiopulmonary disease requiring intensive perioperative management and extended monitoring capabilities.
- Adolescents:Patients under 18 years with severe obesity and failed medical management, restricted to specialized pediatric metabolic programs with psychology and endocrinology integration.
- Elderly Patients:Age-adjusted risk assessment protocols applied to candidates over 65, with frailty scoring determining surgical candidacy.
Obese Adults capture the procedure volume base, while Adolescents represent the steepest expansion trajectory as pediatric metabolic surgery gains insurance recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium bundled pricing for metabolic surgery while Sharjah and Northern Emirates operate on leaner cost structures with leased equipment models.
Dubai
Employer-sponsored health plans and medical tourism flows concentrate demand in Dubai's tertiary hospital corridor. Dubai Health Authority clinical governance frameworks mandate minimum annual case volumes for bariatric program accreditation. Dubai Healthcare City and private hospital clusters along Sheikh Zayed Road anchor the emirate's metabolic surgery infrastructure expansion.
Abu Dhabi
Cleveland Clinic Abu Dhabi and SEHA network facilities attract high-BMI diabetic patients seeking gastric bypass for metabolic remission. Department of Health — Abu Dhabi regulates facility licensing parallel to MOHAP standards with specialized surgeon credential requirements. Al Maryah Island and Al Reem Island medical districts concentrate accredited bariatric units with intensive care backup capabilities.
Sharjah
Mid-tier hospitals leverage asset-light leasing models for surgical staplers to enter metabolic surgery without capital-heavy equipment purchases. Sharjah Health Authority aligns facility accreditation with federal MOHAP standards while maintaining distinct inspection protocols. University Hospital Sharjah and private hospital clusters along Al Dhaid Road are building bariatric service lines through equipment rental partnerships.
Northern Emirates
Ras Al Khaimah and Fujairah facilities serve rural Emirate patients through telemedicine preoperative optimization and referral pipelines to Dubai-Abu Dhabi surgical hubs. Federal MOHAP licensing rules apply uniformly across Ajman, Umm Al Quwain, and Ras Al Khaimah with delegated inspection authority to emirate-level health departments. RAK Medical and Health Sciences University Hospital anchors Northern Emirates metabolic surgery capacity with planned bariatric unit expansion.
UAE Bariatric Surgery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the consumables and instruments layers. The vendor base clusters around three archetypes: integrated operating room system bundlers, surgical stapler and energy device manufacturers, and accredited hospital chains with published outcomes transparency. Competitive moves concentrate on strategic partnerships for equipment leasing access and portfolio diversification into robotic-assisted stapling platforms.
Among US-based medical technology conglomerates, Medtronic and Stryker occupy positions as platform integrators with recurring revenue from consumable attachments. Cleveland Clinic Abu Dhabi exemplifies the accredited hospital chain archetype competing on clinical outcomes transparency and international accreditation status. Conmed Corporation represents component specialists focused on surgical visualization and instrumentation without full system integration.
| Leading Market Players |
|---|
| Conmed Corporation |
| Stryker |
| Medtronic |
| Olympus |
| Becton Dickinson |
| Johnson & Johnson |
| B. Braun |
| Cleveland Clinic Abu Dhabi |
| Apollo Endosurgery |
| Others |
Value Network & Pricing Analysis
Undercapacity in Northern Emirates bariatric surgical capacity is driving equipment leasing premiums and compressing procurement timelines for mid-tier hospitals entering metabolic surgery programs. This utilization gap concentrates pricing power with tertiary Dubai-Abu Dhabi hubs while forcing peripheral facilities toward asset-light supply arrangements.
Pricing Analysis
The customization-premium spread between configured-to-order robotic stapling platforms and standard laparoscopic instrument sets spans three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to integrated OR systems with tissue-sensing automation and consumable attachment bundles, while economy positioning targets leased stapler platforms without monitoring convergence. Price differentiation rests on MOHAP accreditation status and surgeon credential depth, with non-accredited clinics facing 15-20 point procurement disadvantages. Cost compression in standard laparoscopic sets is intensifying because Stryker and Medtronic are pushing recurring revenue from disposable reloads. Employer-sponsored health plans show least price sensitivity for bundled inpatient episodes, while self-pay patients in Sharjah and Northern Emirates drive hardest bargain on device markups.
Supply Chain Analysis
Tariff exposure between US and China dominates surgical instrument sourcing risk for UAE hospital procurement teams. Manufacturing concentration centers on Germany, USA, and China for precision stapling mechanisms, with energy device electronics drawing from South Korean and Japanese component suppliers. Raw material dependencies span surgical-grade stainless steel, titanium alloys for staple formation, and polymer housings for laparoscopic handles. Single-source vulnerability persists for robotic-assisted stapling platforms where Intuitive Surgical and Medtronic control proprietary cartridge interfaces. Distribution runs through Dubai Healthcare City logistics hubs serving Northern Emirates through consolidated freight arrangements with 72-hour fulfillment windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is hitting a platform-economics inflection as integrated OR system bundling displaces standalone instrument purchasing, with interoperability between monitoring and stapling platforms determining vendor lock-in depth.
For Market Incumbents: Pre-empt ambulatory surgical center leasing channel capture by embedding consumable attachment minimums into stapler rental contracts. Consolidate position through backward integration into surgical visualization modules that bundle with core stapling platforms. The emerging threat is asset-light entrants undercutting capital-heavy system sales with pure rental economics. For New Entrants and Emerging Players: Build out telemedicine-enabled preoperative optimization services for rural Northern Emirates patients bypassing Dubai-Abu Dhabi travel burdens. The most penetrable white space sits in Sharjah mid-tier hospitals seeking accredited partnership status without full capital commitment. Target go-to-market angle: equipment-as-a-service partnerships that transfer MOHAP compliance risk to platform vendors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ambulatory surgical center segments as leasing models displace ownership economics. Long-term viability favors platform integrators with recurring consumable revenue over pure instrument manufacturers. Acquisition target archetype: specialized bariatric clinics with MOHAP accreditation but underutilized surgical capacity. Signal to watch: prior authorization approval velocity as insurer scrutiny tightens revision surgery reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated OR System Partnership | Bundles Medtronic monitoring with stapling platforms to lock hospital procurement committees into single-vendor contracts. |
| Asset-Light Leasing Expansion | Enables Sharjah mid-tier hospitals to launch metabolic surgery programs without Cleveland Clinic-level capital deployment. |
| Telemedicine Preoperative Optimization | Extends Cleveland Clinic Abu Dhabi clinical protocols to Northern Emirates patients through remote dietary counseling. |
| Robotic-Assisted Platform Adoption | Reduces leak rate variance between high and low-volume operators across Dubai tertiary hospital networks. |
| Reimbursement Strategy Development | Aligns DHA and MOHAP insurance mandates with outcomes documentation to secure prior authorization for revision cases. |
Research Methodology
Operator-level perspectives from bariatric surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against hospital procurement databases, GPO contract filings, and MOHAP facility licensing records. Bottom-up procedure volume estimates triangulated with top-down equipment shipment data from surgical stapler and energy device distributors.
Scenario-bracketing around insurance coverage expansion and robotic platform adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include procedure type, delivery mode, end user facility scale, and patient risk profile. CAGRs derived from equipment replacement cycles, surgeon training pipeline throughput, and MOHAP accreditation timeline assumptions. Industry-specific inputs incorporated DHA and MOHAP regulatory filing trajectories alongside Cleveland Clinic Abu Dhabi outcomes transparency benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ambulatory surgical center chains or robotic platform disruptors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market