
 Laparoscopic Sutures Market | 2026-2036
Laparoscopic Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Sutures Market Outlook
Hospital procurement is rotating toward ambulatory surgery centers as the dominant buyer archetype for laparoscopic sutures. Ethicon Inc. leverages its absorbable polymer portfolio to anchor North American distribution channels. Medtronic plc sustains R&D intensity across braided and monofilament platforms. B. Braun Melsungen AG dominates European hospital contracts through manufacturing scale in Melsungen.
Laparoscopic sutures are sterile, needle-attached threads engineered from synthetic polymers or natural fibers, designed to pass through trocar ports and maintain tensile strength in insufflated abdominal cavities during minimally invasive closure. Absorbable polyglactin variants degrade through hydrolysis within 56 to 70 days, eliminating foreign body retention in gastrointestinal and gynecological applications. Absorbable sutures command the largest volume share as gastrointestinal surgery adoption rises, while monofilament constructions represent the fastest-growing material architecture due to reduced tissue drag and infection risk. Braided polyester segments retain premium positioning in bariatric procedures where knot security is paramount.
FDA 510(k) pathways and EU MDR technical documentation requirements shape product registration timelines and clinical evidence burdens for manufacturers entering the United States and European markets. ISO 10993 biocompatibility testing and ASTM tensile standards further constrain material selection and batch release protocols. Stakeholders must monitor evolving FDA guidance on absorbable synthetic sutures and EU notified body capacity constraints to calibrate regulatory investment against market access timelines.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around absorbable polymer portfolios capable of satisfying both FDA 510(k) and EU MDR sterility documentation requirements within compressed tender cycles.
Growth Catalysts
- EU MDR compliance mandates:Stricter biocompatibility testing under ISO 10993 is filtering out marginal suppliers and concentrating procurement among manufacturers with dedicated notified body relationships.
- Ambulatory surgery center expansion:Outpatient migration of cholecystectomy and hernia repair procedures is generating recurring suture volume outside traditional hospital supply agreements.
- Polyglactin hydrolysis chemistry:Predictable 56-70 day absorption profiles eliminate foreign body retrieval costs in gastrointestinal applications, accelerating conversion from non-absorbable alternatives.
Market Restraints
- Polymer feedstock concentration:Glycolide and lactide monomer supply chains cluster in Chinese petrochemical corridors, exposing manufacturers to input cost volatility.
- Notified body bottlenecks:EU MDR technical documentation backlogs extend product registration timelines to 18-24 months for absorbable synthetic suture classifications.
- Monofilament knot security limitations:Reduced tissue drag advantages in infection-prone procedures trade off against slippage risks in high-tension bariatric closures.
Strategic Opportunities
- Indian outpatient surgical infrastructure:Government-funded health centers in Maharashtra and Tamil Nadu lack established suture supply contracts, creating first-mover positioning for compliant manufacturers.
- Antimicrobial coating convergence:Integration of triclosan or chlorhexidine into absorbable braids addresses surgical site infection protocols without separate pharmaceutical registration.
- Japan PMDA fast-track pathway:Priority review designation for sutures demonstrating reduced adhesion formation opens accelerated access to the world's third-largest laparoscopic surgery volume.
Industry Challenges
- Needle attachment automation:Precision swaging of curved needles to 3-0 and 4-0 suture diameters requires capital-intensive robotic workstations with 24-month depreciation cycles.
- Batch sterility validation:Ethylene oxide residual testing and endotoxin screening for each production lot extends release timelines, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Sutures Market |
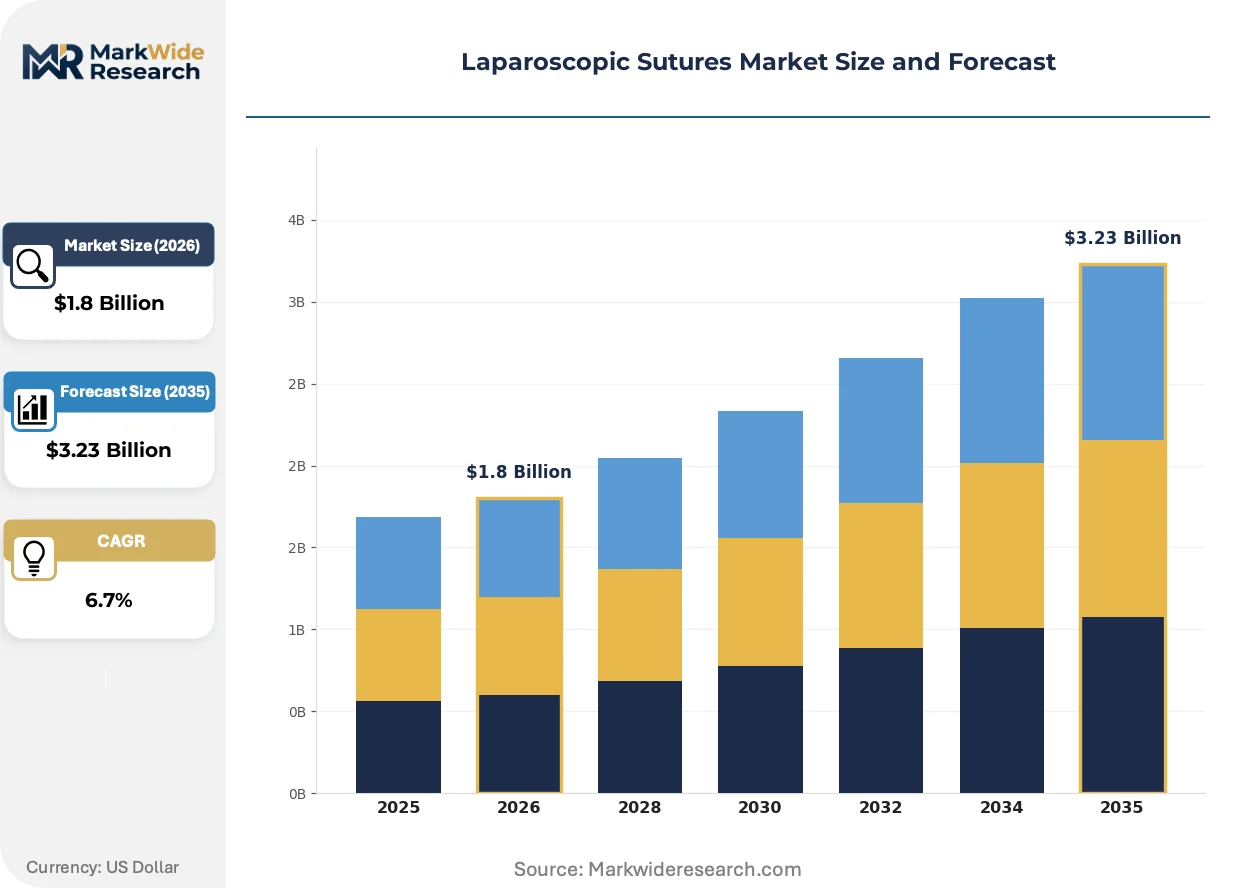
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Non-Absorbable Sutures, Monofilament Sutures, Braided Sutures Material: Polyester, Polypropylene, Polyglactin, Silk Application: Gastrointestinal Surgery, Gynecological Surgery, Bariatric Surgery, Urological Surgery End User: Hospitals, Ambulatory Surgery Centers, Clinics, Specialized Surgical Facilities |
| Companies Covered | Ethicon Inc., Medtronic plc, B. Braun Melsungen AG, Smith & Nephew plc, Boston Scientific Corporation, CONMED Corporation, Teleflex Incorporated, Surgical Specialties Corporation, Advanced Medical Solutions Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Sutures Market Strategic Shifts
Material science advances and regulatory documentation burdens are simultaneously fragmenting product architectures and consolidating viable supplier bases across minimally invasive closure categories.
Barbed monofilament sutures are bifurcating the laparoscopic closure landscape between knotless continuous running techniques and traditional interrupted suturing methods. Bariatric surgery units in German university hospitals are adopting barbed configurations for gastric sleeve reinforcement, displacing manual knot-tying time in procedures where insufflation pressure limits operative windows. The technology is bifurcating training protocols and instrument compatibility requirements across European teaching institutions.
EU MDR Annex I general safety and performance requirements now mandate clinical evaluation reports with post-market surveillance data for all absorbable suture classifications. Manufacturers must demonstrate equivalence to predicate devices through biocompatibility testing under ISO 10993-5 and ISO 10993-10 cytotoxicity protocols, extending documentation preparation to 14-18 months. Smaller European manufacturers without dedicated regulatory affairs departments are outsourcing technical file compilation to specialized consultancies in Switzerland and Ireland.
Hospital supply chain directors are unbundling suture procurement from broad orthopedic and cardiovascular contracts into standalone laparoscopic category management. Ambulatory surgery centers in Texas and Florida are negotiating direct manufacturer agreements for polyglactin and polydioxanone SKUs, bypassing distributor markups on high-velocity consumables. This reconfiguration is most visible in United States markets where group purchasing organization exclusions for outpatient facilities have loosened since 2022.
Laparoscopic Sutures Market Segmentation
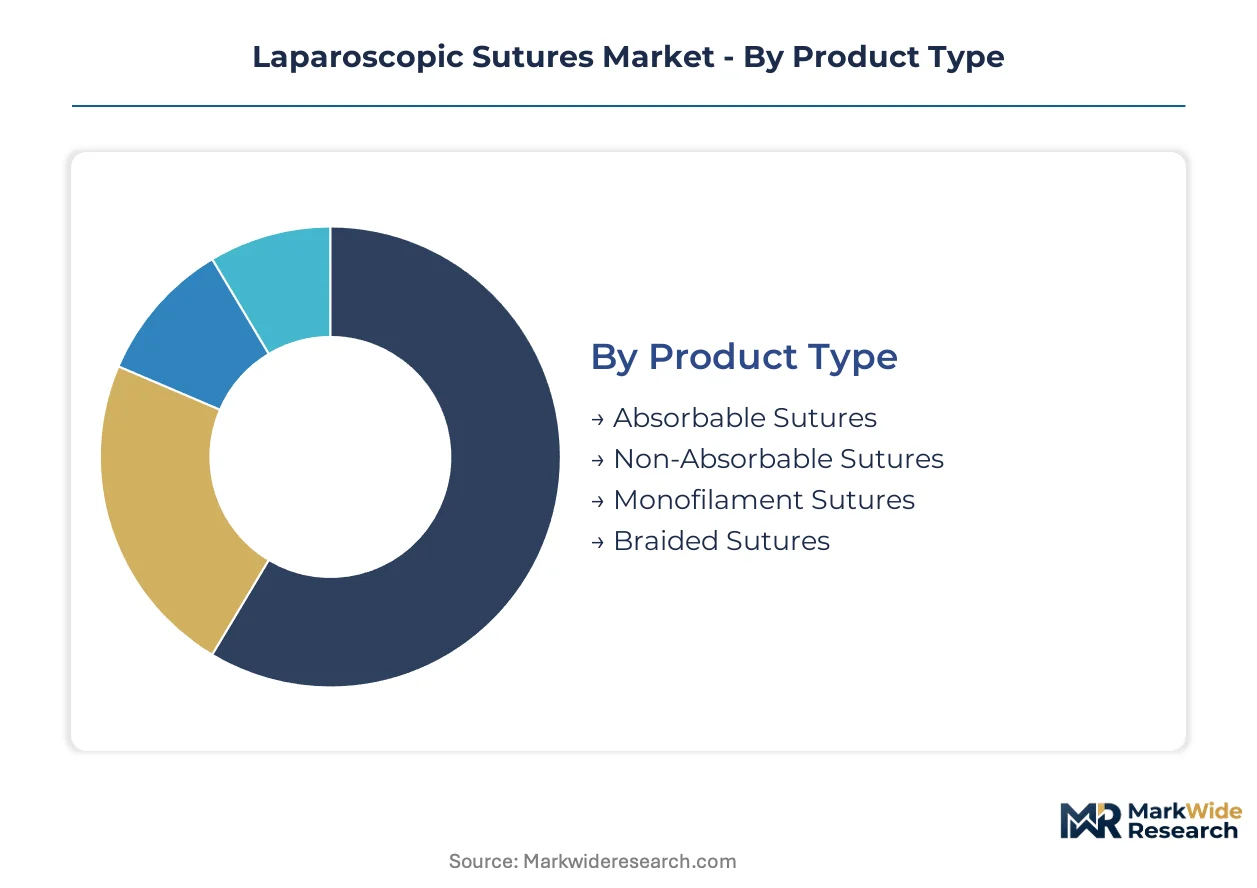
Laparoscopic suture procurement channels fragment sharply across product architectures, with absorbable polymers flowing through consolidated hospital contracts while monofilament variants penetrate ambulatory networks through direct manufacturer agreements. Material selection and application specificity determine margin profiles and regulatory documentation burdens for each segment.
Product Type:
Channel mix diverges between absorbable portfolios anchored in multi-year hospital tenders and non-absorbable lines serving specialized surgical facilities through distributor relationships.
- Absorbable Sutures:Polyglactin and polydioxanone formulations hydrolyze predictably within 56-70 days, eliminating foreign body retrieval costs. Demand concentrates in United States gastrointestinal units where Medicare reimbursement favors same-day discharge protocols.
- Monofilament Sutures:Single-strand polypropylene constructions reduce tissue drag and bacterial colonization risk in infection-prone procedures. German bariatric centers are converting fastest due to insufflation pressure constraints that limit operative windows.
- Non-Absorbable Sutures:Permanent polyester and polypropylene threads retain tensile strength indefinitely, serving hernia mesh fixation and vascular anastomosis where long-term structural integrity is mandatory.
- Braided Sutures:Multi-filament constructions deliver superior knot security in high-tension closures, commanding premium positioning in Japanese university hospitals performing complex gastric sleeve procedures.
By volume, Absorbable Sutures leads. By growth pace, Monofilament Sutures is expanding most quickly.
Material:
Cost tiers stratify around polymer feedstock concentration and biocompatibility certification depth, with synthetic absorbables occupying mid-premium positioning against natural fiber alternatives.
- Polyglactin:Copolymer of glycolide and lactide delivers predictable hydrolysis kinetics with minimal tissue reaction. United States ambulatory surgery centers in Texas and Florida are negotiating direct supply agreements to bypass distributor markups on this high-velocity SKU.
- Polypropylene:Isotactic polymer maintains tensile strength beyond two years, serving permanent closure applications where foreign body tolerance is established. Japanese PMDA fast-track eligibility for adhesion-reducing variants is accelerating regulatory investment.
- Polyester:Braided polyethylene terephthalate constructions anchor bariatric procedures where knot security outweighs absorption convenience, with European hospital contracts concentrated in German manufacturing clusters.
- Silk:Natural protein fiber retains niche positioning in ligature applications requiring handling pliability, though demand is contracting amid synthetic substitution and allergen concerns.
Polyglactin commands the largest procurement volumes. Polypropylene is gaining share fastest in permanent closure categories.
Application:
Customer type alignment varies by procedure complexity, with high-acuity gastrointestinal and bariatric cases remaining hospital-centered while gynecological migration to outpatient settings accelerates.
- Gastrointestinal Surgery:Cholecystectomy and colorectal resection closures demand absorbable polymers with documented hydrolysis profiles. FDA 510(k) predicate device requirements shape material selection for United States manufacturers.
- Bariatric Surgery:Gastric sleeve and bypass procedures require maximum knot security under insufflation pressure. German university hospitals are adopting barbed monofilament configurations to reduce manual tying time.
- Gynecological Surgery:Hysterectomy and myomectomy closures are migrating to ambulatory surgery centers in Maharashtra and Tamil Nadu, creating first-mover supply contract opportunities.
- Urological Surgery:Prostatectomy and nephrectomy applications favor fine-gauge monofilaments where tissue trauma minimization is prioritized over absorption predictability.
Gastrointestinal Surgery generates the highest absolute suture consumption. Gynecological Surgery is shifting to outpatient channels fastest.
End User:
Procurement authority is decentralizing from hospital supply chain directors toward ambulatory facility administrators with distinct volume-scale and documentation requirements.
- Hospitals:Consolidated vendor relationships around absorbable polymer portfolios capable of satisfying both FDA 510(k) and EU MDR sterility documentation dominate procurement. United States group purchasing organization contracts remain the primary volume channel.
- Ambulatory Surgery Centers:Outpatient migration of cholecystectomy and hernia repair is generating recurring suture volume outside traditional supply agreements, with direct manufacturer negotiations bypassing distributor markups.
- Clinics:Lower-acuity procedures favor economy-tier non-absorbable configurations where procedure volume does not justify specialized inventory investment.
- Specialized Surgical Facilities:Bariatric and oncological centers require premium braided constructions with batch-specific sterility validation and extended technical documentation.
Hospitals retain the largest procurement volumes. Ambulatory Surgery Centers are expanding their share fastest as minimally invasive procedures shift to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in European laparoscopic suture distribution, while the Port of Long Beach anchors United States import logistics for polymer feedstocks. Japan's Chubu Centrair International Airport facilitates just-in-time delivery to Nagoya's precision instrument manufacturing cluster.
United States
Medicare same-day discharge protocols and ambulatory surgery center expansion in Texas and Florida drive polyglactin consumption. FDA 510(k) predicate device requirements shape material selection timelines for domestic manufacturers. The Dallas-Fort Worth metroplex hosts concentrated distribution operations serving Southwestern outpatient facilities.
Germany
University hospital bariatric units in Berlin and Munich convert fastest to barbed monofilament configurations. EU MDR technical documentation mandates filter supplier bases toward notified body-certified manufacturers. The Melsungen manufacturing cluster dominates European hospital contract fulfillment through integrated polymer processing.
Japan
PMDA fast-track eligibility for adhesion-reducing suture variants accelerates regulatory investment from domestic and foreign applicants. Aging demographics expand laparoscopic cholecystectomy volumes in Kansai region facilities. The Nagoya precision instrument corridor supplies automated needle-attachment workstations to regional manufacturers.
India
Government-funded health centers in Maharashtra and Tamil Nadu lack established suture supply contracts, creating first-mover opportunities. CDSCO medical device registration requirements are tightening sterility documentation for imported absorbable polymers. The Chennai medical device cluster is expanding polymer conversion capacity for gastrointestinal surgery applications.
United Kingdom
NHS procurement consolidation around multi-year absorbable polymer tenders concentrates volume among notified body-certified suppliers. MHRA post-Brexit regulatory alignment with EU MDR extends documentation requirements for market access. The Cambridge medical technology corridor hosts specialized consultancies supporting technical file compilation for smaller manufacturers.
Laparoscopic Sutures Market Competitive Environment
Concentration sits with diversified medical device conglomerates possessing dedicated regulatory affairs departments and established notified body relationships. The supplier base fragments across three tiers: integrated polymer manufacturers with captive feedstock supply, specialized suture assemblers purchasing monomer inputs, and regional distributors handling import logistics for emerging markets. Strategic archetypes include scale-driven contract manufacturers, technology licensors of barbed configurations, and compliance-focused EU MDR specialists. Competitive moves center on backward integration into glycolide-lactide polymerization and geographic expansion into Indian outpatient infrastructure.
Among diversified medical technology conglomerates, Ethicon Inc., Medtronic plc, and B. Braun Melsungen AG occupy positions representing distinct strategic emphases. Ethicon exemplifies the absorbable polymer portfolio archetype anchored in North American distribution density. Medtronic sits within the multi-platform R&D intensity tier sustaining investment across braided and monofilament constructions. B. Braun represents the European manufacturing scale archetype dominating hospital contracts through integrated production in German industrial clusters. These three entities collectively illustrate how regulatory compliance depth and polymer chemistry control separate viable competitors from marginal suppliers in laparoscopic closure markets.
| Leading Market Players |
|---|
| Ethicon Inc. |
| Medtronic plc |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| Boston Scientific Corporation |
| CONMED Corporation |
| Teleflex Incorporated |
| Surgical Specialties Corporation |
| Advanced Medical Solutions Group plc |
| Others |
Value Chain & Pricing Dynamics
Polyglactin substitution for silk and catgut sutures is redrawing procurement geography toward Chinese glycolide-lactide corridors while compressing margin structures for European manufacturers dependent on imported monomer feedstocks.
Pricing Analysis
Volume-discount tiering structures separate multi-year hospital GPO contracts from spot purchases by ambulatory surgery centers, with FDA 510(k) certification grade and batch sterility documentation serving as the primary price differentiation drivers. Cost compression in standard absorbable tiers is intensifying as Texas and Florida outpatient facilities negotiate direct manufacturer agreements, bypassing traditional distributor markups. Hospital procurement committees demonstrate lowest price sensitivity due to bundled reimbursement protocols, while Indian government health centers exhibit highest sensitivity amid constrained public health budgets.
Supply Chain Analysis
Inventory lead times for ethylene oxide sterilization cycles extend working capital cycles, with finished goods distribution running through German Melsungen manufacturing clusters and United States Dallas-Fort Worth distribution hubs. Glycolide and lactide monomer production concentrates in Chinese petrochemical corridors, exposing manufacturers to tariff exposure on polymer feedstock imports. Braided and monofilament constructions draw from Japanese Nagoya precision instrument corridors for automated needle-attachment workstations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laparoscopic sutures market is recovering from cyclical sterilization capacity constraints, with ethylene oxide processing backlogs normalizing as alternative sterilization modalities gain regulatory acceptance.
For Market Incumbents: Compound notified body relationship depth to defend EU MDR certification moats against emerging polymer converters in India. Backward integration into glycolide-lactide polymerization secures input cost predictability against Chinese petrochemical volatility. Prioritize batch sterility validation automation to compress release timelines and improve working capital velocity. For New Entrants and Emerging Players: Anchor in Maharashtra and Tamil Nadu government health center procurement white space, where CDSCO registration requirements have filtered established suppliers. Target gynecological surgery migration to outpatient settings as the most penetrable application segment. Pursue direct manufacturer agreements with ambulatory surgery centers to circumvent entrenched GPO contract structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European suture assemblers lacking captive polymer supply. Five-to-ten year viability hinges on EU MDR technical file completion timelines and notified body capacity expansion. Monitor PMDA fast-track designation grants for adhesion-reducing variants as the signal indicating Japanese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Completion | Notified body certification unlocks German hospital contract participation against non-compliant suppliers. |
| Backward Integration into Polymerization | Captive glycolide-lactide production insulates margin structures from Chinese feedstock volatility. |
| Antimicrobial Coating Development | Triclosan integration addresses surgical site infection protocols without separate pharmaceutical registration. |
| Barbed Monofilament Platform Launch | Knotless configurations reduce operative time constraints in German bariatric insufflation environments. |
| Indian Distribution Partnership | Maharashtra government health center contracts establish first-mover positioning in outpatient infrastructure expansion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and hospital GPO contract disclosures. Interviews with biomedical engineers, hospital purchasing committee directors, regulatory affairs specialists at notified bodies, and ambulatory surgery center administrators inform demand-side validation. Bottom-up SKU-level volume analysis triangulates against top-down procedure frequency estimates from Medicare and NHS reimbursement datasets.
Segmentation dimensions modeled include absorbable versus non-absorbable material architectures, monofilament versus braided constructions, gastrointestinal versus bariatric versus gynecological applications, and hospital versus ambulatory surgery center procurement channels. CAGRs derive from procedure volume elasticity analysis against suture consumption intensity ratios across the projection horizon. Polymer hydrolysis kinetics and EU MDR registration timelines serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable ethylene oxide sterilization capacity and unchanged EU notified body throughput; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market