
 Surgical Retainers Market | 2026-2036
Surgical Retainers Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Retainers Market Analytics
Germany is reshaping European supply dynamics through precision manufacturing investments in surgical retainer components. Medtronic leverages its cardiovascular device heritage to sustain polymer science capabilities transferable to dental retention systems. Johnson & Johnson Services, Inc. anchors North American distribution through its Ethicon surgical channel infrastructure. B. Braun Melsungen AG dominates Central European hospital procurement with integrated sterile packaging workflows.
Surgical retainers are mechanical or bonded devices fabricated from stainless steel, cobalt-chromium alloys, or fiber-reinforced polymers designed to stabilize dental arches following orthodontic intervention or maxillofacial reconstruction. Fixed retainers, typically multi-strand wire bonded lingually, maintain anterior alignment with minimal patient compliance burden. Removable variants command premium pricing due to thermoplastic vacuum-forming precision and patient-specific digital workflows. Metal compositions retain volume leadership in hospital settings where durability thresholds override aesthetic considerations.
FDA 510(k) clearance pathways and EU MDR Class IIa designation govern biocompatibility testing and clinical validation requirements for permanent implantable retainers. ISO 13485 quality management standards shape subcontractor qualification across polymer sourcing and wire drawing operations. Stakeholders must monitor evolving FDA guidance on patient-matched device exemptions as chairside 3D printing disrupts traditional laboratory outsourcing models.
Market Dynamics
The Surgical Retainers Market is undergoing structural recalibration as orthodontic retention protocols extend treatment timelines and chairside digital manufacturing compresses traditional laboratory outsourcing. FDA 510(k) clearance requirements and EU MDR Class IIa biocompatibility mandates are tightening material specifications while specialist networks concentrate procurement power.
Growth Catalysts
- Extended Retention Protocols:Orthodontic associations now recommend indefinite or multi-decade retention phases, expanding the installed base of replacement and maintenance procedures across dental clinics.
- EU MDR Compliance:Stricter biocompatibility documentation requirements for permanent implantable devices are filtering out non-compliant suppliers and consolidating demand toward certified manufacturers.
- Fiber-Reinforced Polymers:Advancements in glass-fiber and PEEK-based composites are displacing metal retainers in aesthetic-sensitive patient segments, opening premium pricing tiers.
Market Restraints
- Cobalt-Chromium Volatility:Mining concentration in the Democratic Republic of Congo and processing bottlenecks in China create input cost instability for alloy-based fixed retainers.
- Specialist Labor Scarcity:The limited pipeline of orthodontists trained in multi-strand wire bonding techniques constrains fixed retainer deployment velocity in community dental settings.
- Removable Aligner Substitution:Clear aligner systems with integrated retention phases are capturing post-treatment patients who would otherwise transition to dedicated retainer protocols.
Strategic Opportunities
- India's Underserved Tier-2 Cities:Rising disposable incomes and orthodontic awareness in secondary urban centers create first-mover potential for standardized removable retainer distribution.
- Chairside 3D Printing Convergence:Integration of intraoral scanning with direct-print photopolymer workflows enables same-day retainer delivery, collapsing laboratory turnaround from weeks to hours.
- US Tax-Advantaged HSAs:Expanded health savings account eligibility for orthodontic retention devices is lowering effective patient costs and stimulating elective procedure volume.
Industry Challenges
- ISO 13485 Certification Timelines:The 12-18 month quality management system validation process delays market entry for polymer sourcing subcontractors and wire drawing specialists.
- Legacy Practice Management Integration:Digital workflow adoption requires costly upgrades to patient record systems and laboratory communication platforms in established orthodontic practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Retainers Market |
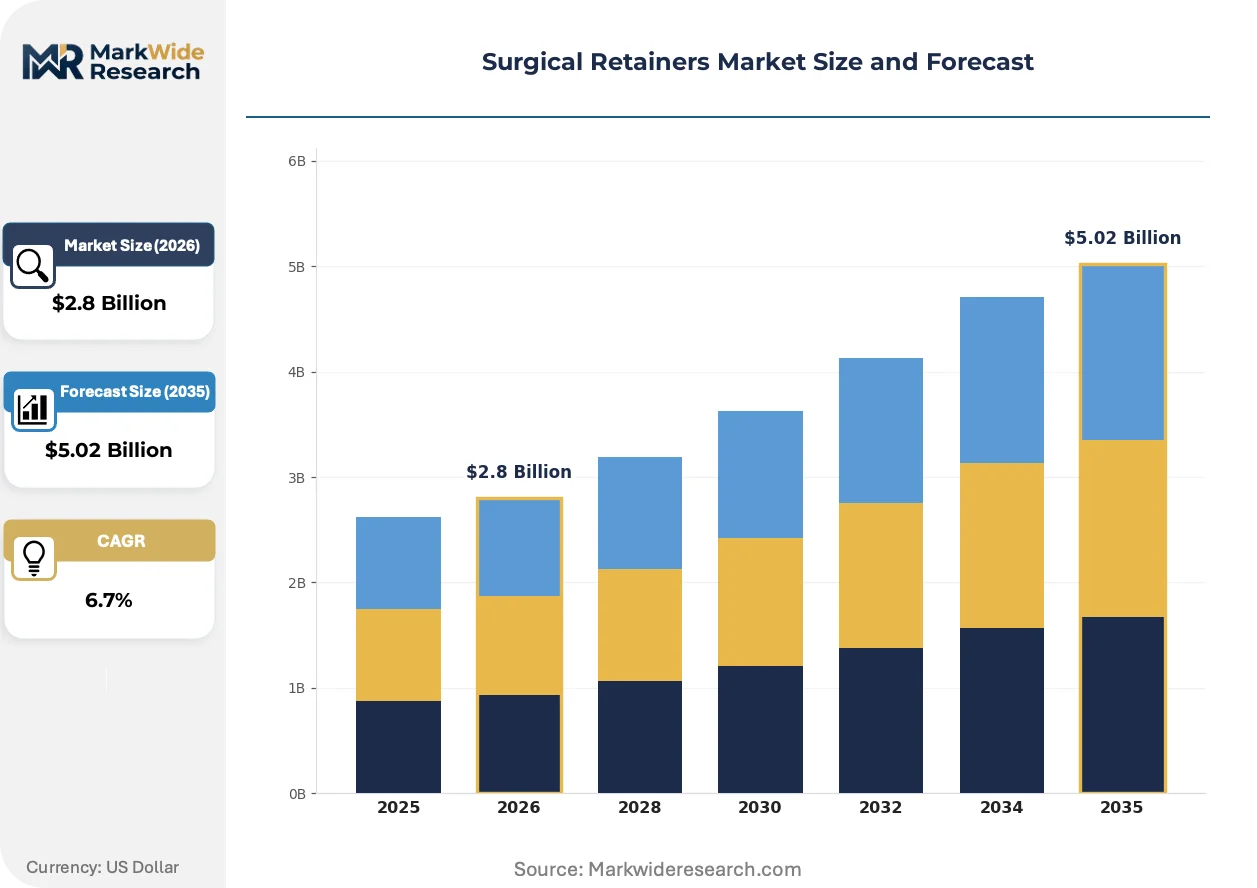
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Retainers, Removable Retainers, Adjustable Retainers, Lingual Retainers Material: Plastic, Metal, Composite, Acrylic End User: Orthodontists, Hospitals, Dental Clinics, Rehabilitation Centers Application: Post-Surgical Care, Orthodontic Treatment, Dental Restoration, Preventive Care |
| Companies Covered | Medtronic, Johnson & Johnson Services, Inc., B. Braun Melsungen AG, Becton, Dickinson and Company, Integra LifeSciences, Teleflex Incorporated, Stryker Corporation, Cook Group, Applied Medical Resources Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Retainers Market Evolving Landscape
Digital fabrication technologies and regulatory harmonization efforts are compressing product development cycles while reshaping how retainers reach end-users. Material science breakthroughs and procurement model evolution are creating divergent competitive paths.
Intraoral scanning combined with cloud-based design automation is virtualizing the traditional dental laboratory relationship. Specialist orthodontic networks in the United States are deploying chairside milling and printing systems that eliminate physical impression shipping and reduce turnaround from two weeks to under 48 hours. This virtualization is compressing regional laboratory ecosystems and forcing independent labs to specialize in complex reconstruction work or exit the retainer segment entirely.
EU MDR technical documentation requirements for permanent implantable devices are elevating clinical validation burdens across stainless steel and cobalt-chromium retainer categories. Manufacturers must now submit biocompatibility testing data and post-market surveillance plans that previously applied only to cardiovascular implants. German and Swiss suppliers with existing notified body relationships are capturing volume as smaller competitors defer re-certification investments.
Direct-to-patient subscription models for removable retainer replacement are disrupting traditional dental channel economics. Tele-dentistry platforms in North America are bundling remote monitoring with scheduled retainer shipments, bypassing chairside dispensing margins. This behavioral shift is most visible among young adult patients who completed orthodontic treatment via aligner systems and expect comparable convenience in retention maintenance.
Surgical Retainers Market Segmentation
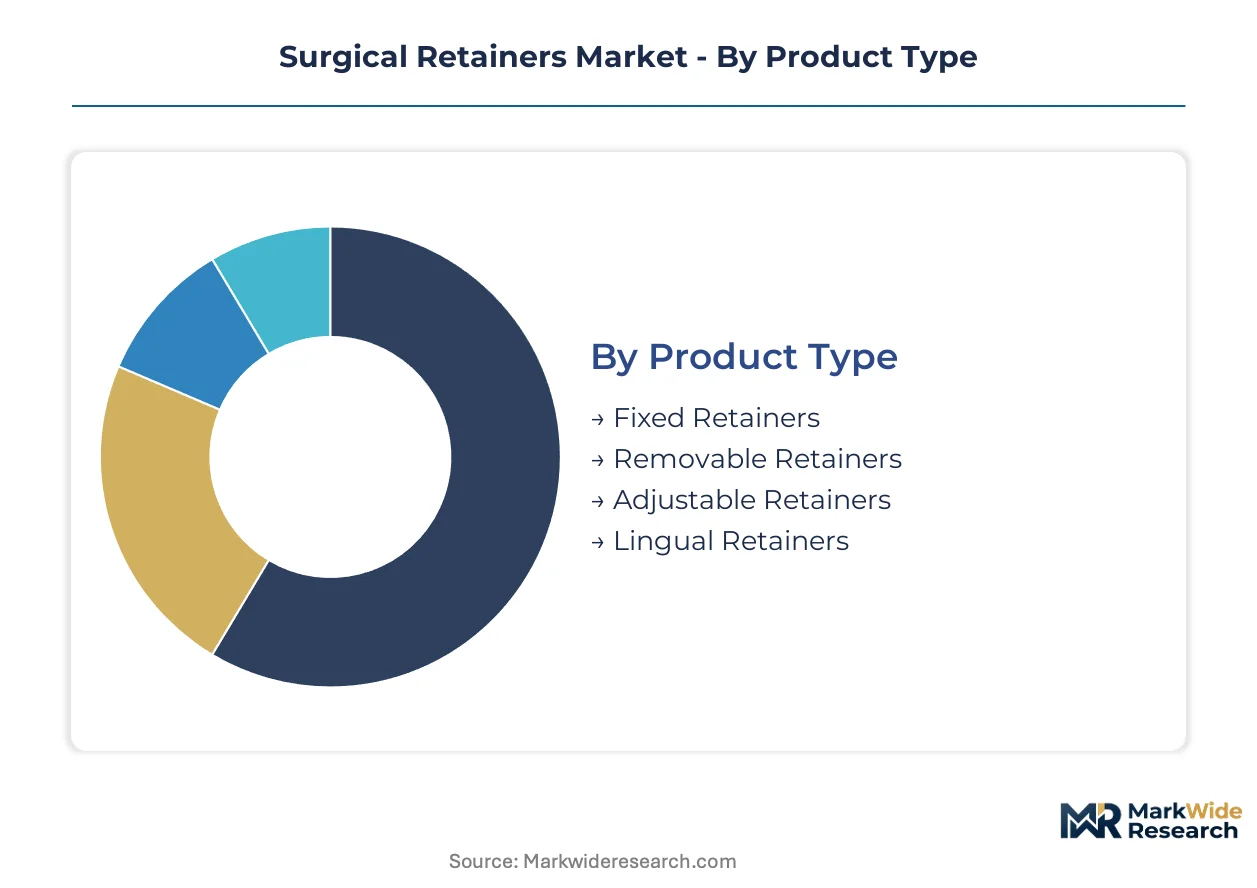
Segmentation in the surgical retainers market exposes divergent service models across product categories. Fixed and removable variants demand fundamentally different replacement cycles, chairside labor intensity, and patient compliance monitoring protocols.
Product Type:
After-sales service intensity varies dramatically across retainer categories, with bonded fixed devices requiring emergency repair protocols and removable systems demanding scheduled replacement programs.
- Fixed Retainers:Multi-strand stainless steel or cobalt-chromium wire bonded lingually to anterior teeth. Demand concentrates in United States specialist orthodontic networks where indefinite retention protocols drive replacement and maintenance volume. These devices generate recurring revenue through debonding emergencies and wire fatigue failures.
- Removable Retainers:Thermoplastic vacuum-formed appliances produced via digital workflows from intraoral scans. Adoption accelerates in Germany and Switzerland where chairside 3D printing enables same-day delivery. Premium pricing reflects patient-specific fit precision and aesthetic transparency requirements.
- Adjustable Retainers:Mechanisms permitting active arch modification post-treatment. Limited deployment in complex maxillofacial reconstruction cases.
- Lingual Retainers:Bonded fixed devices positioned on tooth palatal surfaces. Niche adoption among aesthetic-sensitive adult patients in private dental clinics.
Fixed Retainers holds the largest share; momentum sits with Removable Retainers.
Material:
Cost tier differentiation separates premium fiber-reinforced composites from commodity metal alternatives, with biocompatibility certification costs filtering supplier participation.
- Metal:Stainless steel and cobalt-chromium alloys dominate hospital procurement where durability thresholds override unit economics. EU MDR Class IIa documentation requirements favor established German and Swiss suppliers with notified body relationships.
- Plastic:Thermoplastic polymers for vacuum-formed removable devices. Volume leadership in dental clinics serving aligner-completed patients expecting comparable convenience.
- Composite:Glass-fiber and PEEK-based materials displacing metal in aesthetic segments. Steepest expansion trajectory among adult retention patients.
- Acrylic:Traditional material for Hawley-style removable retainers. Declining share as digital thermoplastic workflows capture preference.
Metal commands volume leadership; Composite gains share fastest.
End User:
Customer type determines procurement authority, with hospitals centralizing purchasing through sterile supply committees and dental clinics exercising chairside discretion.
- Dental Clinics:Primary volume channel for removable retainers with direct patient relationships. United States distribution runs through specialist orthodontic networks and general practice aligner partnerships.
- Orthodontists:Fixed retainer specification authority in complex cases. Labor scarcity in multi-strand bonding techniques constrains deployment velocity.
- Hospitals:Centralized procurement of metal retainers for post-surgical stabilization. B. Braun Melsungen AG captures volume through integrated sterile packaging workflows in Central Europe.
- Rehabilitation Centers:Niche demand following maxillofacial trauma reconstruction. Limited penetration outside tertiary care networks.
Dental Clinics generate highest procedure volume; Orthodontists retain specification control.
Application:
Maturity stage separates established orthodontic protocols from emerging preventive deployment models.
- Orthodontic Treatment:Core application following fixed appliance or aligner therapy. Extended retention recommendations from professional associations expand installed base maintenance.
- Post-Surgical Care:Maxillofacial reconstruction stabilization requiring hospital-grade durability. Metal compositions retain dominance.
- Dental Restoration:Adjunct to prosthetic rehabilitation. Limited standardization across protocols.
- Preventive Care:Emerging application for occlusal stabilization in bruxism management. Early adoption in Swiss and German preventive dentistry models.
Orthodontic Treatment anchors revenue; Preventive Care offers expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters and United States specialist orthodontic networks concentrate supply capacity for surgical retainer components, while regulatory divergence between FDA and EU MDR frameworks fragments certification pathways across major demand centers.
United States
Specialist orthodontic networks in Texas and California drive premium fixed retainer procurement through indefinite retention protocols. FDA 510(k) clearance requirements for biocompatible materials filter supplier participation toward established polymer science and wire drawing operations. The Minneapolis medical device corridor anchors polymer sourcing capabilities transferable to dental retention systems.
Germany
Precision manufacturing investments in Baden-Württemberg and Bavaria reshape European supply dynamics for cobalt-chromium alloy components. EU MDR Class IIa designation mandates biocompatibility documentation that favors notified body relationships held by established suppliers. The Stuttgart precision engineering cluster concentrates wire drawing and sterile packaging workflows for hospital-grade retainers.
Switzerland
Aesthetic-sensitive patient segments in Zurich and Geneva accelerate fiber-reinforced polymer adoption displacing traditional metal retainers. Swissmedic regulatory frameworks align with EU MDR technical documentation requirements for permanent implantable devices. The Basel pharmaceutical-medical device nexus supports advanced composite material validation for premium retention applications.
India
Rising disposable incomes in Mumbai, Bangalore, and Delhi-NCR secondary urban centers create first-mover potential for standardized removable retainer distribution. CDSCO medical device regulations are converging toward international standards for biocompatibility testing. The Gujarat pharmaceutical manufacturing belt expands into polymer sourcing for dental device subcontracting.
China
Domestic orthodontic clinic chains in Shanghai and Beijing compress laboratory turnaround through chairside digital manufacturing adoption. NMPA medical device registration requirements for imported retainers create localization incentives for alloy processing and thermoplastic forming. The Yangtze River Delta medical device manufacturing corridor scales vacuum-forming precision for removable appliance production.
Surgical Retainers Market Competitive Landscape
Diversified medical device conglomerates and specialized dental suppliers split the market between hospital procurement channels and dental clinic direct relationships. Tiered competitive positioning separates scale-driven polymer science capabilities from precision wire bonding specialists. Two dominant archetypes emerge: cardiovascular device heritage players leveraging transferable materials expertise, and sterile packaging integrators capturing hospital centralized purchasing. Competitive moves concentrate on regulatory certification consolidation and chairside digital workflow partnerships.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson Services, Inc. occupy positions representing polymer science and distribution infrastructure archetypes respectively. B. Braun Melsungen AG exemplifies the sterile packaging integrator model within Central European hospital procurement networks. These three anchors illustrate how cardiovascular device heritage, surgical channel infrastructure, and integrated sterile workflows translate into dental retention market positioning without vertical integration into raw material production.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson Services, Inc. |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Integra LifeSciences |
| Teleflex Incorporated |
| Stryker Corporation |
| Cook Group |
| Applied Medical Resources Corporation |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's cost dynamics amplify both supply concentration effects and downstream price stratification across surgical retainer markets. German precision manufacturing clusters leverage this logistics advantage to command premium positioning, while Asian thermoplastic suppliers compete on volume economics through alternative routing.
Pricing Analysis
EU MDR Class IIa designation dictates the pricing tier structure across the surgical retainers landscape. Three-tier pricing separates fiber-reinforced composite premium offerings from standard stainless steel configurations and economy-grade acrylic alternatives. Price differentiation rests on certification grade and after-sales service bundling, with FDA 510(k) clearance adding substantial documentation costs to US-bound shipments. Cost compression in the economy tier is intensifying because aligner-integrated retention protocols capture price-sensitive post-treatment patients. Dental clinics serving aesthetic-conscious adults exhibit lowest price sensitivity; community general practices show highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for alloy-based fixed retainers. Manufacturing gravity centers on Germany, Switzerland, and China, with Baden-Württemberg precision clusters and Yangtze River Delta thermoplastic forming operations anchoring respective metal and polymer supply. Raw material dependencies span cobalt-chromium alloys from Central African mining operations, medical-grade PEEK resins from European chemical producers, and stainless steel wire from Chinese drawing facilities. Single-source vulnerability concentrates in cobalt processing nodes. Distribution runs through specialist orthodontic networks in North America and hospital procurement committees in Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical retainers market is entering a cyclical recovery phase as extended retention protocols expand replacement procedure volume. Orthodontic association guidelines recommending indefinite retention create predictable demand recurrence across patient cohorts.
For Market Incumbents: Build regulatory certification moats by accelerating EU MDR technical documentation investments before smaller competitors complete re-certification. Consolidate polymer science capabilities through captive supply of medical-grade PEEK resins to offset cobalt-chromium volatility. Channel control through chairside digital workflow partnerships defends against tele-dentistry subscription models eroding traditional dispensing margins.
For New Entrants and Emerging Players: India's tier-2 cities with rising orthodontic awareness and limited specialist penetration represent the most penetrable entry point for standardized removable retainer distribution. Direct-to-patient subscription bundling with remote monitoring software offers a go-to-market angle that bypasses established dental channel gatekeepers. Fiber-reinforced composite segments in Swiss and German aesthetic markets provide secondary white-space targeting.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking portfolio rationalization of dental-adjacent divisions with transferable polymer capabilities. The five-to-ten year viability window favors platforms with notified body relationships and chairside manufacturing integration. Acquisition target archetypes include precision wire drawing specialists with ISO 13485 certification and digital workflow software providers. The signal to watch is CDSCO regulatory convergence accelerating multinational localization investments in Indian manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Biocompatibility documentation investments filter supplier participation toward certified manufacturers with polymer science capabilities. |
| EU MDR Class IIa Certification | Notified body relationships held by German and Swiss suppliers capture volume as competitors defer re-certification investments. |
| Chairside 3D Printing Integration | Same-day delivery workflows collapse laboratory turnaround from weeks to hours, compressing regional lab ecosystems. |
| Hospital System Partnership | Centralized procurement through sterile supply committees favors integrated packaging workflows in Central European markets. |
| Direct-to-Patient Subscription Model | Tele-dentistry platforms bundling remote monitoring bypass chairside dispensing margins among aligner-completed patients. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with orthodontic practice owners, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and orthodontic association clinical guidelines. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across product categories.
Forecast inputs span product type segmentation across fixed, removable, and adjustable retainers; material tiers from commodity metal to fiber-reinforced composites; end-user channels distinguishing dental clinics from hospital procurement; and application categories from orthodontic treatment to preventive care. CAGRs were derived through regression analysis of historical procedure volumes against demographic and regulatory drivers across the projection horizon. Industry-specific inputs include orthodontic specialist pipeline constraints and chairside digital adoption curves.
Stress conditions across cobalt supply disruption, EU MDR implementation delays, and aligner substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding retention protocol adherence and regulatory harmonization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Drains Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Endoluminal Suturing Devices Market