
 Global Cath Lab Services Market | 2026-2036
Global Cath Lab Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cath Lab Services Market Foresight
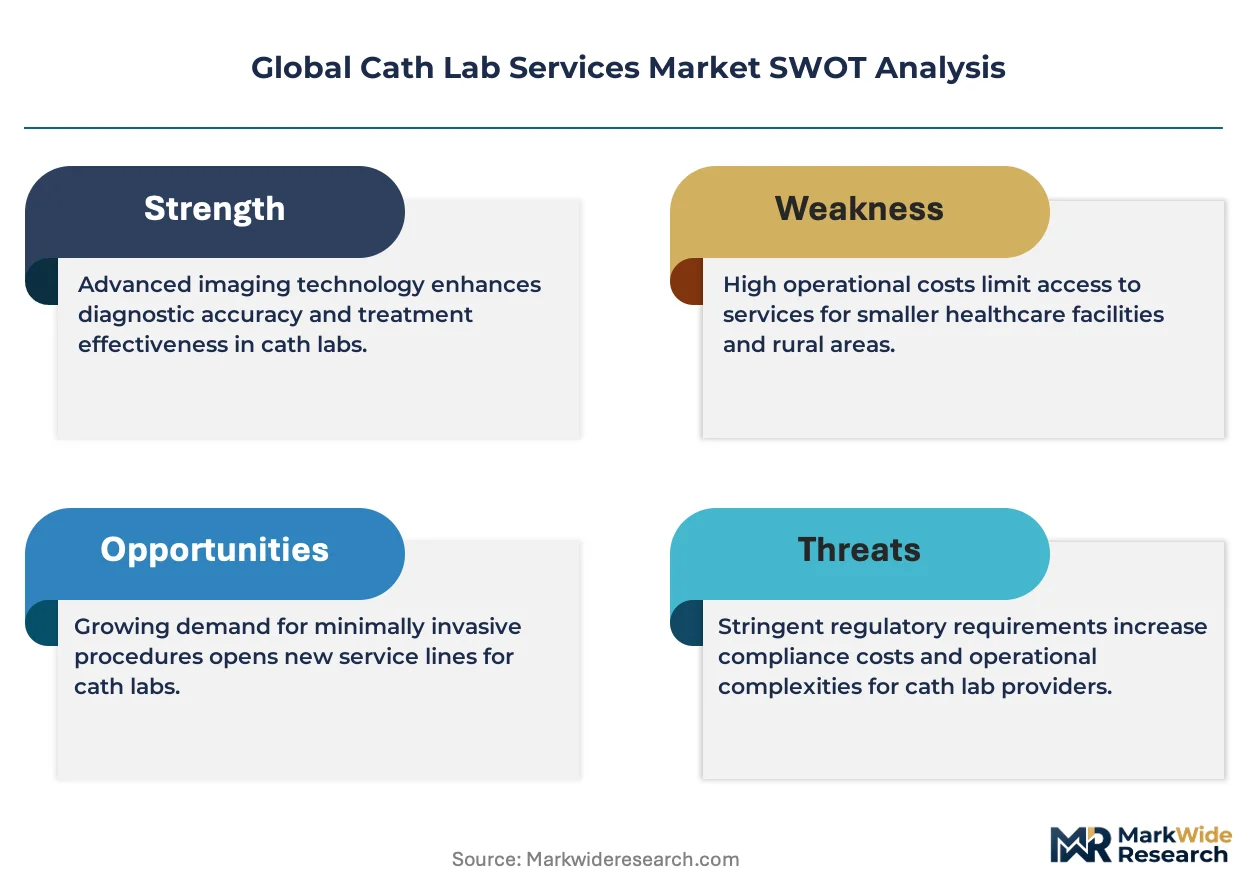
Flat-panel detector technology is pivoting away from legacy image intensifier systems across cath lab installations, cutting radiation exposure and improving fluoroscopic resolution. Siemens Healthineers leverages in-house detector manufacturing to control hardware cost curves. Philips Healthcare sustains installed-base loyalty through integrated informatics platforms. GE Healthcare competes on remote service architectures that reduce equipment downtime.
Cath lab services encompass diagnostic and interventional cardiovascular procedures performed in specialized suites equipped with X-ray imaging, hemodynamic monitoring, and catheter-based instrumentation. Primary systems operate at 15-30 frames per second fluoroscopy with digital subtraction angiography capability for real-time vascular visualization. Therapeutic interventions command the largest revenue share among service types due to stenting and angioplasty volume. Outpatient centers represent the fastest-expanding delivery model as payors shift reimbursement toward lower-acuity settings. Diagnostic procedures remain a mature, high-frequency entry point that feeds downstream therapeutic conversion.
FDA 510(k) clearance requirements shape device selection and service line configuration for US-based operators. EMA medical device regulation and ISO 13485 quality standards govern equipment procurement and maintenance protocols across European installations. Stakeholders must monitor reimbursement parity between inpatient and outpatient settings as site-of-service policies determine capital allocation for new cath lab construction.
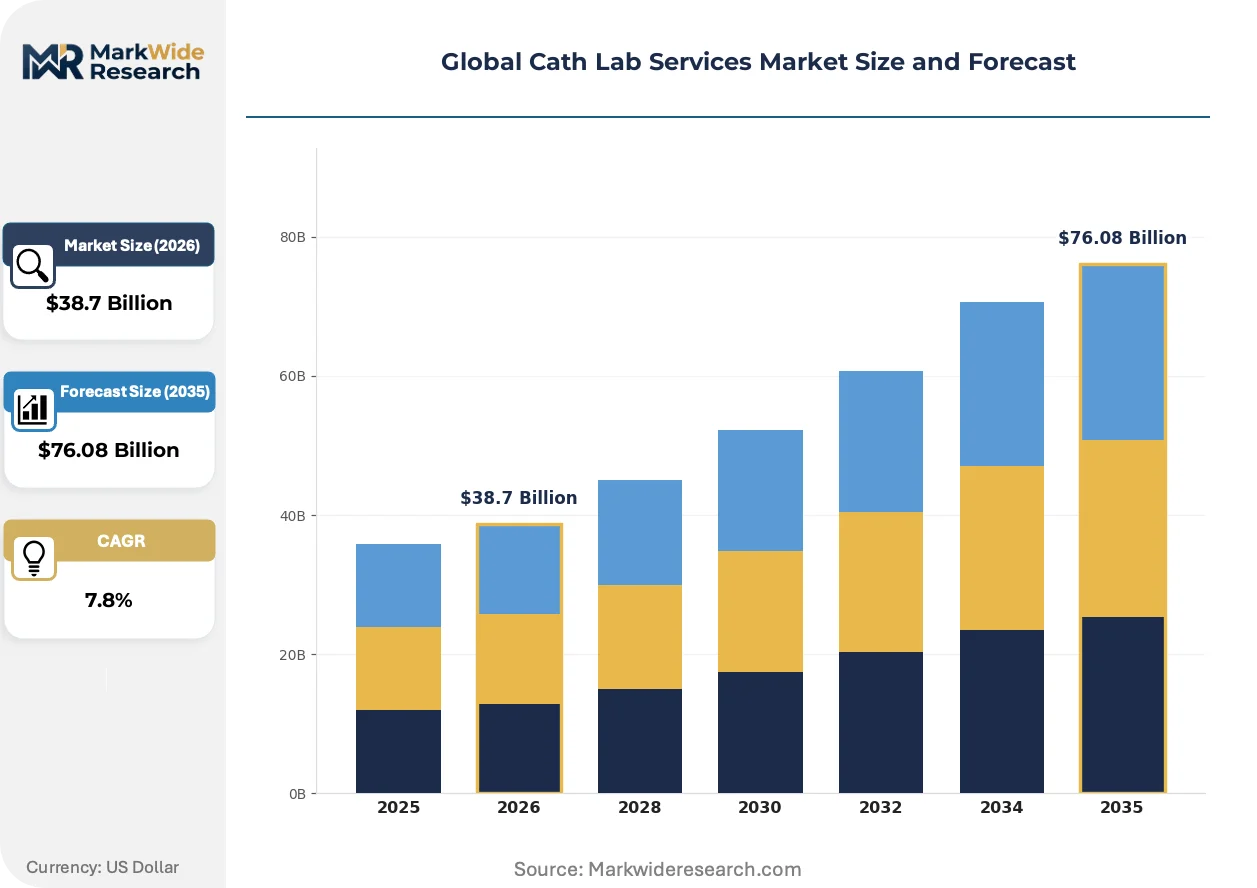
Market Dynamics
Flat-panel detector adoption is compressing equipment replacement cycles while outpatient reimbursement parity is redirecting capital toward ambulatory surgical centers. Siemens Healthineers and Philips Healthcare are restructuring service contracts around detector refresh timelines rather than full-suite replacement.
Growth Catalysts
- CMS site-of-service payment differentials:US Medicare reimbursement rates for outpatient cardiac catheterization now approach inpatient parity, accelerating freestanding facility development in Texas and Florida.
- AI-enabled image reconstruction:Deep learning algorithms reduce fluoroscopy dose by 40-60% without diagnostic quality loss, expanding eligible patient populations at high-volume centers.
- German cardiology consolidation:Rhineland-Palatinate and Bavaria clinic chains are centralizing cath lab operations under unified quality management systems to capture scale efficiencies.
Market Restraints
- Flat-panel detector supply concentration:Two Japanese sensor foundries control 70% of amorphous silicon deposition capacity, creating procurement bottlenecks during demand surges.
- EMA MDR transition friction:Extended conformity assessment timelines for interventional devices delay service line upgrades at European facilities awaiting CE mark renewals.
- Interventional radiologist training pipelines:US fellowship positions in interventional cardiology have plateaued since 2019, constraining procedure volume expansion regardless of installed capacity.
Strategic Opportunities
- Brazil ANVISA accelerated pathway:Priority review designation for stent and catheter innovations enables first-mover positioning in Latin America's largest private insurance market.
- Hybrid operating room convergence:Integration of surgical robotics with angiography systems creates premium service tiers for structural heart procedures at academic medical centers.
- Direct-to-employer contracting:Self-insured corporations in North Carolina and Tennessee are negotiating bundled cath lab rates bypassing traditional payer intermediaries.
Industry Challenges
- ISO 13485 maintenance burden:Multi-site cath lab operators face audit complexity when coordinating quality management across hospital and outpatient facility portfolios.
- Legacy PACS integration:DICOM routing between new flat-panel systems and decade-old archive infrastructure requires custom middleware development at mid-tier health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cath Lab Services Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Procedures, Therapeutic Interventions, Electrophysiology, Imaging Services Application: Cardiovascular Diseases, Peripheral Vascular Disease, Neurovascular Conditions, Structural Heart Disease Delivery Model: Inpatient Settings, Outpatient Centers, Ambulatory Surgical Centers, Mobile Units End User: Cardiology Clinics, Specialty Hospitals, Multispecialty Hospitals, Diagnostic Laboratories |
| Companies Covered | Philips Healthcare, Siemens Healthineers, GE Healthcare, Medtronic, Abbott Laboratories, Boston Scientific, Cardinal Health, Terumo Corporation, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cath Lab Services Market Shifts & Advancements
Detector hardware commoditization is separating imaging performance from informatics value, forcing equipment vendors to compete on software integration rather than raw specification sheets. This decoupling is redistributing margin capture across the cath lab value chain.
Photon-counting detector technology is modularizing service line architecture. The technology replaces energy-integrating sensors with cadmium telluride layers that discriminate tissue density at the photon level. Academic medical centers in Switzerland and the Netherlands are piloting these systems for complex coronary interventions. This hardware shift is modularizing cath lab construction, enabling phased detector upgrades without full-suite replacement and compressing capital deployment timelines for facility expansions.
EU MDR Article 117 imposes notified body involvement for all class III device modifications, including software updates affecting diagnostic algorithms. The regulation extends recertification timelines by 12-18 months for angiography system manufacturers. German and Italian cath lab operators are delaying planned informatics upgrades pending clarity on qualification boundaries, creating temporary competitive advantage for vendors with pre-certified integrated platforms.
After-sales service unbundling is disrupting traditional equipment financing. Hospital procurement departments in Australia and South Korea are separating detector warranty, software subscription, and field engineering into distinct contract vehicles. This disaggregation enables competitive benchmarking of service components and shifts vendor relationships from bundled lock-in toward modular vendor selection. The practice is most advanced at multi-hospital systems with centralized biomedical engineering functions.
Global Cath Lab Services Market Segmentation
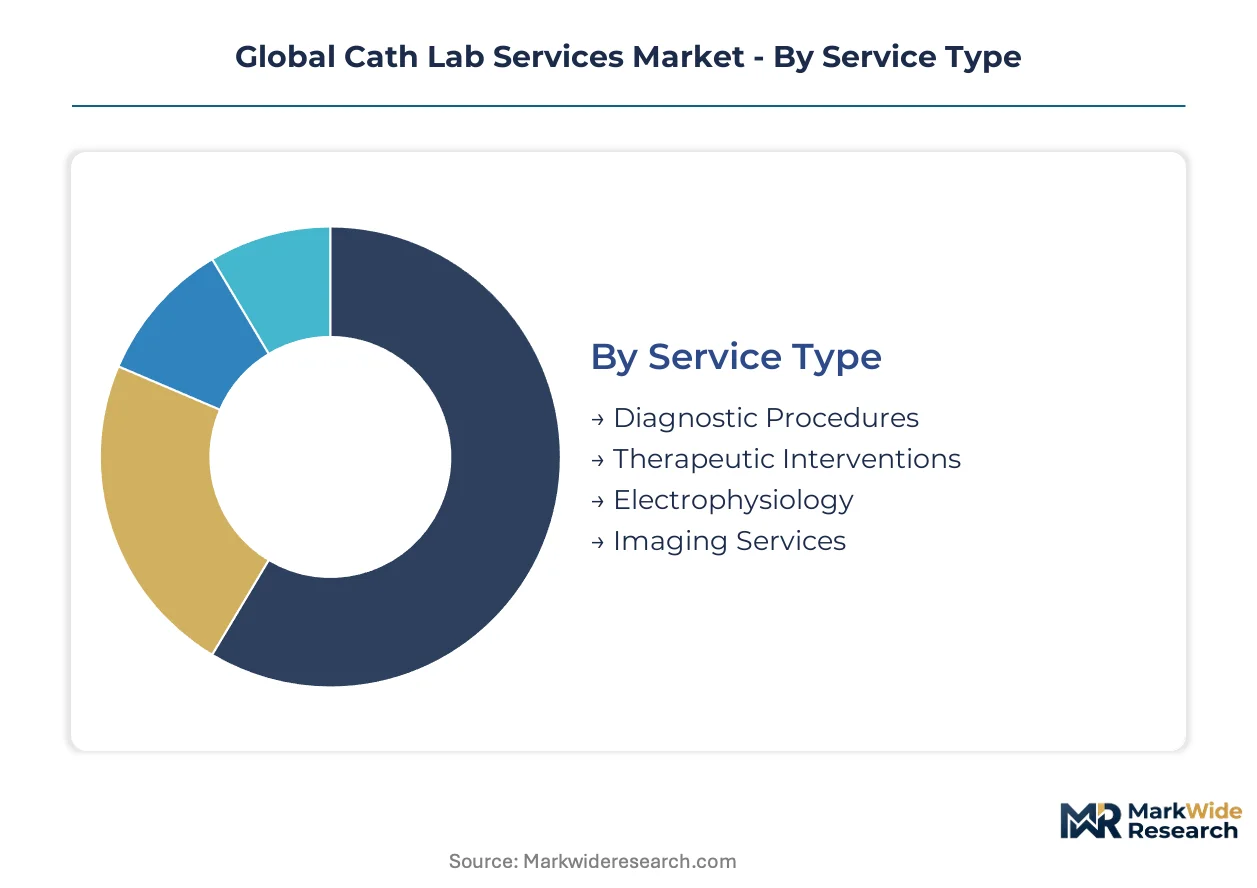
Cath lab service segmentation reveals how procedure economics, patient acuity, and capital deployment patterns diverge across clinical settings. Understanding these splits enables targeted capacity planning and reimbursement optimization.
Service Type:
Therapeutic volume dominates revenue capture while diagnostic frequency drives patient funnel economics.
- Diagnostic Procedures:Coronary angiography and fractional flow reserve measurements establish disease burden using contrast injection and hemodynamic monitoring. Demand concentrates at outpatient centers in Texas and Florida where CMS reimbursement parity reduces patient cost barriers. These procedures feed downstream therapeutic conversion at a 40-60% rate depending on lesion severity.
- Therapeutic Interventions:Percutaneous coronary intervention, stent deployment, and balloon angioplasty command premium reimbursement due to device costs and procedural complexity. German cardiology clinic chains in Rhineland-Palatinate and Bavaria centralize these services under unified quality management to capture scale efficiencies. The segment absorbs the majority of flat-panel detector capital investment.
- Electrophysiology:Catheter ablation and device implantation for arrhythmia management.
- Imaging Services:Intravascular ultrasound and optical coherence tomography guidance.
Mature deployment sits with Diagnostic Procedures. Newer deployment is concentrated in Electrophysiology.
Application:
Cardiovascular dominance reflects coronary disease prevalence while structural heart applications attract academic medical center investment.
- Cardiovascular Diseases:Coronary artery disease interventions including chronic total occlusion recanalization and bifurcation stenting. Swiss and Dutch academic centers pilot photon-counting detector systems specifically for these complex coronary cases. The application justifies hybrid operating room convergence with surgical robotics.
- Structural Heart Disease:Transcatheter aortic valve replacement and mitral clip procedures requiring advanced imaging and multidisciplinary teams. Demand clusters at US academic medical centers in North Carolina and Tennessee where direct-to-employer bundled contracts bypass traditional payer intermediaries. Premium pricing supports dedicated structural heart program investment.
- Peripheral Vascular Disease:Lower extremity and renal artery interventions.
- Neurovascular Conditions:Stroke intervention and aneurysm coiling procedures.
Volume concentration remains with Cardiovascular Diseases. Steepest expansion trajectory belongs to Structural Heart Disease.
Delivery Model:
Site-of-service economics are compressing inpatient share while ambulatory capacity expands fastest.
- Outpatient Centers:Freestanding catheterization laboratories performing diagnostic and low-risk interventional procedures. Growth accelerates in Texas and Florida where Medicare reimbursement approaches inpatient parity. These facilities operate at 30-40% lower per-procedure cost than hospital-based labs.
- Ambulatory Surgical Centers:Multi-specialty facilities integrating cardiac catheterization with other same-day surgical services. Australian and South Korean hospital systems separate detector warranty, software subscription, and field engineering into distinct contract vehicles for these settings. Procurement flexibility enables competitive service benchmarking.
- Inpatient Settings:Hospital-based labs attached to emergency departments and cardiac surgery programs.
- Mobile Units:Transportable catheterization systems for rural and underserved market access.
Capital deployment still favors Inpatient Settings. Gaining share fastest are Outpatient Centers.
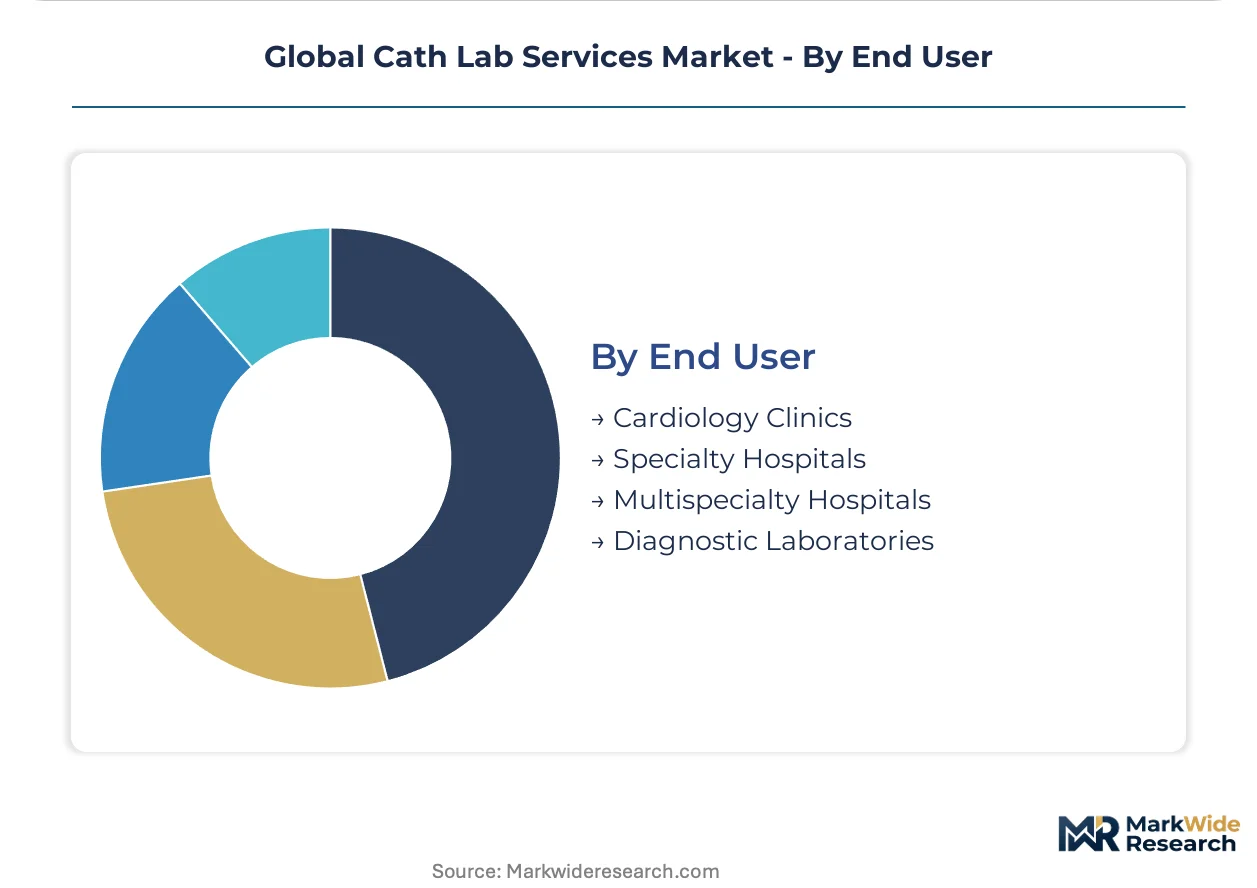
End User:
Specialty depth versus scale economies defines competitive positioning across provider types.
- Cardiology Clinics:Single-specialty practices with dedicated catheterization capacity and procedure volume concentration. German clinic chains in Rhineland-Palatinate consolidate cath lab operations under centralized management to reduce per-procedure costs. These operators lead flat-panel detector refresh cycles.
- Multispecialty Hospitals:Integrated health systems spreading cath lab capital across cardiovascular, neurovascular, and peripheral service lines. US hospital networks expand outpatient catheterization capacity to capture CMS site-of-service payment differentials. Cross-subsidization enables technology upgrade investment.
- Specialty Hospitals:Cardiovascular-focused acute care facilities.
- Diagnostic Laboratories:Imaging-focused providers without interventional capability.
Equipment refresh leadership sits with Cardiology Clinics. Capacity expansion concentrates in Multispecialty Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cath lab services concentrates in the United States, Germany, and Japan where aging demographics and established reimbursement frameworks sustain procedure volume. Cardiology clinic chains and hospital networks in these markets drive capital deployment patterns for flat-panel detector systems and outpatient facility construction.
United States
Hospital networks in Texas and Florida are expanding outpatient catheterization capacity to capture CMS site-of-service payment differentials that now approach inpatient parity. FDA 510(k) clearance requirements shape device selection and service line configuration for operators building new ambulatory capacity. The Southeast corridor from Houston to Miami represents the fastest-growing cluster of freestanding cath lab development.
Germany
Cardiology clinic chains in Rhineland-Palatinate and Bavaria are consolidating cath lab operations under centralized quality management systems to reduce per-procedure costs. EMA medical device regulation and ISO 13485 quality standards govern equipment procurement protocols across these installations. The Rhine-Main and Munich metropolitan areas concentrate the majority of detector refresh cycles and hybrid operating room investments.
Japan
Academic medical centers in Tokyo and Osaka are piloting photon-counting detector systems for complex coronary interventions requiring advanced tissue density discrimination. METI industrial policy supports domestic manufacturing of cadmium telluride sensor layers for next-generation angiography platforms. The Kanto and Kansai regions anchor procurement decisions for the Asia-Pacific installed base.
Switzerland
Swissmedic regulation enables accelerated evaluation of AI-enabled image reconstruction algorithms that reduce fluoroscopy dose by 40-60% without diagnostic quality loss. University hospitals in Zurich and Geneva lead European adoption of deep learning guidance systems for structural heart procedures. The Swiss-German border corridor functions as a testbed for EU MDR Article 117 compliance strategies.
Brazil
Private insurance markets in São Paulo and Rio de Janeiro are expanding cath lab access through ANVISA accelerated pathway designations for stent and catheter innovations. Priority review timelines enable first-mover positioning for foreign equipment vendors targeting Latin America's largest healthcare economy. The Southeast region concentrates both diagnostic volume and interventional capacity expansion.
Global Cath Lab Services Market Competitive Landscape
Service contract restructuring dominates the current landscape as vendors pivot from full-suite replacement to detector refresh timelines. Equipment manufacturers compete across three tiers: integrated imaging-informatics platforms, hardware-focused system suppliers, and modular component providers. Two strategic archetypes define positioning: vendors controlling in-house detector manufacturing versus those relying on external sensor foundries. M&A activity concentrates on software integration capabilities, while geographic expansion targets outpatient center development in Texas and Florida.
Among diversified health technology conglomerates, Philips Healthcare and Siemens Healthineers exemplify contrasting approaches to installed-base retention. Philips sustains customer loyalty through integrated informatics platforms that bridge imaging and electronic health record systems. Siemens leverages captive flat-panel detector manufacturing to control hardware cost curves and refresh timelines. GE Healthcare occupies a distinct position emphasizing remote service architectures that minimize equipment downtime across distributed facility networks. These three entities collectively represent the premium-tier competitive vector where software differentiation now supersedes raw imaging specifications.
| Leading Market Players |
|---|
| Philips Healthcare |
| Siemens Healthineers |
| GE Healthcare |
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| Cardinal Health |
| Terumo Corporation |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Amorphous silicon wafer pricing indices from Japanese foundries cascade directly into three-tier equipment procurement structures, where detector refresh timelines separate premium academic medical centers from standard hospital networks and economy-tier outpatient facilities.
Pricing Analysis
Volume concentration in diagnostic procedures compresses margins at outpatient centers, while therapeutic interventions at German cardiology clinics sustain premium pricing through device bundling and after-sales service unbundling. Price differentiation hinges on ISO 13485 certification tier and flat-panel detector resolution specifications, with FDA 510(k) clearance status commanding additional brand premium. Cost compression in the economy tier intensifies as Australian and South Korean hospital systems benchmark detector warranties against software subscriptions separately. Price sensitivity peaks at multispecialty hospitals spreading capital across service lines, while academic medical centers in Switzerland demonstrate lowest sensitivity due to research funding offsets.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from US hospital networks, while specialized distributors serve mid-tier European clinic chains with fragmented procurement authority. Manufacturing concentrates in Japan for amorphous silicon deposition, Germany for system integration, and the United States for software development. Raw material dependencies include cadmium telluride for photon-counting layers, rare earth phosphors for scintillation, and high-purity silicon substrates. Single-source vulnerability at two Japanese sensor foundries creates procurement bottlenecks during demand surges. Distribution runs through regional service hubs co-located with major metropolitan healthcare clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR Article 117 recertification timelines create a twelve-to-eighteen-month barrier-to-entry moat for vendors with pre-certified integrated platforms.
For Market Incumbents: Anchor installed-base retention through captive detector manufacturing and modular service contract restructuring. Siemens Healthineers leverages in-house amorphous silicon production to control refresh timelines against Philips Healthcare's informatics platform stickiness. Defensive consolidation should prioritize software integration acquisitions over hardware scale, as detector commoditization accelerates.
For New Entrants and Emerging Players: Capture white-space opportunity in Brazil's ANVISA accelerated pathway for stent and catheter innovations, where priority review designations enable first-mover positioning ahead of established European vendors. The Southeast region from São Paulo to Rio de Janeiro offers the most penetrable geography due to private insurance market expansion. Go-to-market execution should emphasize direct-to-employer bundled contracting in North Carolina and Tennessee.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale cardiology clinic chains in Rhineland-Palatinate and Bavaria facing EMA MDR transition friction. Long-term viability over the next decade hinges on photon-counting detector upgrade trajectories and hybrid operating room convergence capabilities. Watch Swissmedic AI algorithm approvals as the inflection signal for deep learning guidance system adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 pre-certification accelerates German clinic chain upgrade cycles. |
| Hospital System Partnership | Texas and Florida networks expand outpatient capacity to capture CMS payment parity. |
| Software Companion Development | AI-enabled image reconstruction reduces fluoroscopy dose at Swiss academic centers. |
| Reimbursement Strategy | Direct-to-employer bundled contracts bypass traditional payer intermediaries in Tennessee. |
| FDA Submission | 510(k) clearance pathways shape device selection for US ambulatory surgical center buildouts. |
Research Methodology
Document review covered FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement schedules, and ISO 13485 audit records, complemented by interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from hospital procurement databases, cath lab equipment service contract registries, and regulatory submission tracking systems. Bottom-up procedure volume estimates triangulated against top-down capital expenditure flows from health system financial disclosures.
Historical installation data cross-referenced against expert panel input on detector refresh timelines and outpatient migration patterns across the analysis window. Segmentation modeling incorporated service type, delivery model, application, and end-user archetype dimensions. CAGRs were derived from weighted regression across procedure volume projections and capital deployment schedules, with specific inputs including AI algorithm adoption curves and hybrid operating room construction pipelines.
The model holds under stable reimbursement parity conditions; deviation in CMS site-of-service policy or EMA MDR enforcement intensity would shift capital allocation timelines. Forecasts reflect documented assumptions regarding fellowship training pipeline constraints and amorphous silicon foundry capacity expansion. Periodic stress-testing of base assumptions against ANVISA pathway velocity and photon-counting detector pilot outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Hospice Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
India Senior Living Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Spa Services Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Healthcare Transportation Services Market