
 Global Mobile Clinics Market | 2026-2036
Global Mobile Clinics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Clinics Market Foresight
Rural healthcare delivery is pivoting toward mobile infrastructure as governments seek alternatives to fixed-facility investment. ADI Mobile Health leverages extensive van-based manufacturing capacity across North American operations. Matthews Specialty Vehicles anchors its position through specialty chassis integration for diagnostic imaging. Odulair LLC differentiates via modular interior configurations that adapt between dental and primary care deployments.
Mobile clinics are self-contained medical units built on modified vehicle platforms, typically incorporating electrical systems supporting diagnostic equipment, climate control, and water sterilization capabilities. Their primary purpose extends clinical reach to populations beyond permanent healthcare infrastructure. Van-based deployment modes dominate current procurement volumes due to maneuverability advantages in urban and semi-urban corridors. Diagnostic services within the service type category command premium configuration requirements, elevating unit economics relative to basic primary care setups. Trailer-based alternatives occupy niche positions where stationary deployment duration exceeds typical mobile rotation cycles.
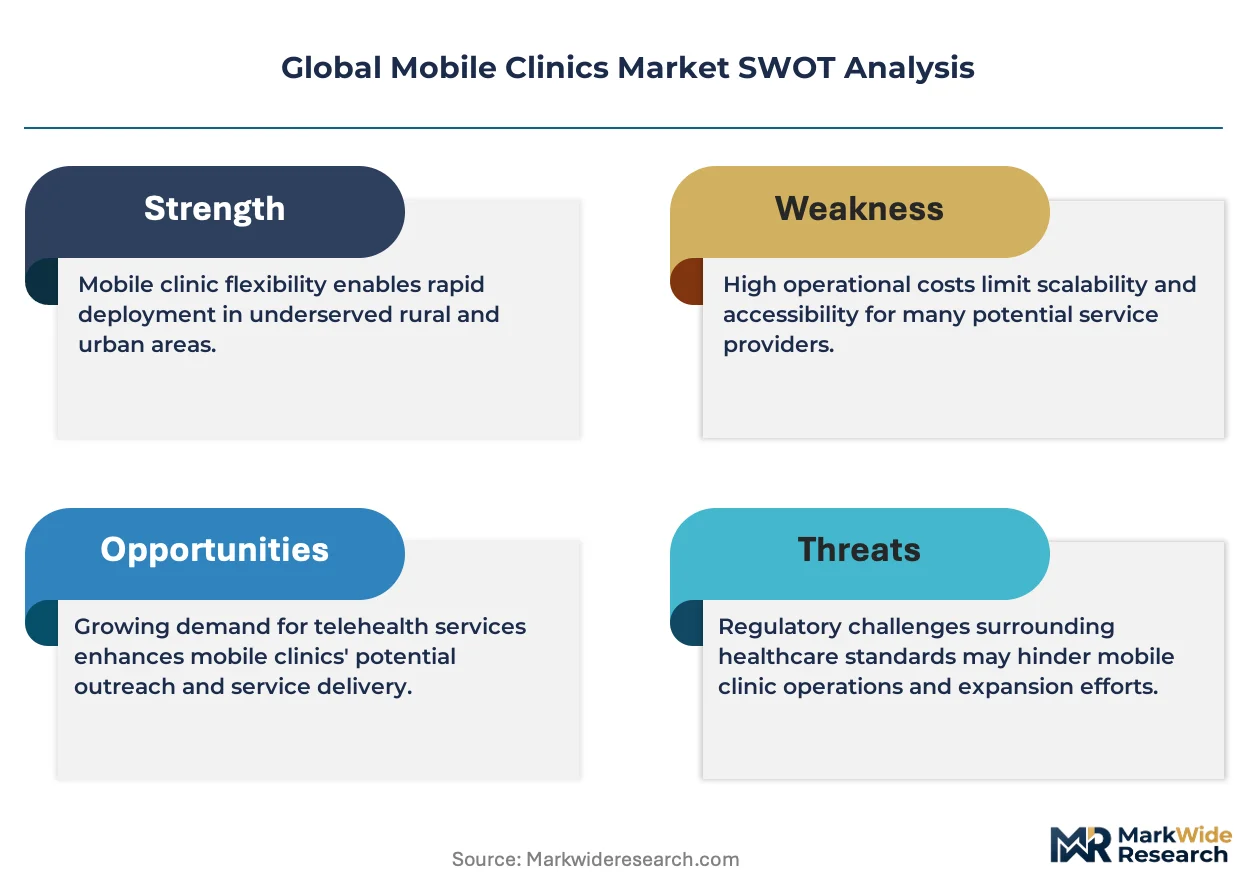
FDA standards for mobile medical device operation, WHO prequalification protocols for field diagnostics, and EU MDR requirements for temporary care sites collectively shape product certification pathways and market access conditions. Health Canada and Australia's TGA impose additional electromagnetic compatibility standards for onboard imaging equipment. Stakeholders must monitor evolving reimbursement frameworks for telehealth-integrated mobile services as regulatory clarity determines sustainable operating models across jurisdictions.
Market Dynamics
WHO prequalification protocols for point-of-care diagnostics are compressing certification timelines while national health missions in India and procurement programs across sub-Saharan Africa are accelerating fleet deployment velocity beyond traditional fixed-facility construction cycles.
Growth Catalysts
- India's National Health Mission:Federal procurement mandates for maternal and child health mobile units in underserved districts are creating predictable demand pipelines for van-based configurations.
- WHO Modular Vehicle Standards:Platform interoperability guidelines are reducing integration friction between chassis suppliers and medical equipment manufacturers.
- Point-of-Care Diagnostics:HIV and tuberculosis screening protocols are expanding rural fleet deployment in sub-Saharan African health systems.
Market Restraints
- Specialty Chassis Concentration:North American and European chassis suppliers control premium platform availability, creating procurement bottlenecks for African and South Asian operators.
- Electromagnetic Compatibility Certification:Health Canada and Australia's TGA impose divergent testing protocols for onboard imaging equipment, fragmenting product development roadmaps.
- Fixed-Facility Substitution:Telehealth infrastructure investments in urban corridors are diverting capital from mobile clinic procurement in some OECD markets.
Strategic Opportunities
- Telehealth-Integrated Reimbursement:Evolving frameworks for remote diagnostic services in the US and Germany are creating sustainable operating models for hybrid mobile-virtual care delivery.
- Modular Interior Convergence:Dental-primary care reconfiguration capabilities are opening multi-service deployment contracts with municipal health departments.
- Brazil's SUS Expansion:Universal health system fleet procurement for Amazon basin communities represents underpenetrated demand for trailer-based stationary deployment.
Industry Challenges
- Electrical Systems Integration:Climate control and water sterilization capabilities require specialized technician training that outpaces vocational program output in target deployment regions.
- FDA Mobile Medical Device Timelines:Field operation certification pathways for diagnostic equipment extend product launch cycles beyond typical municipal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Clinics Market |
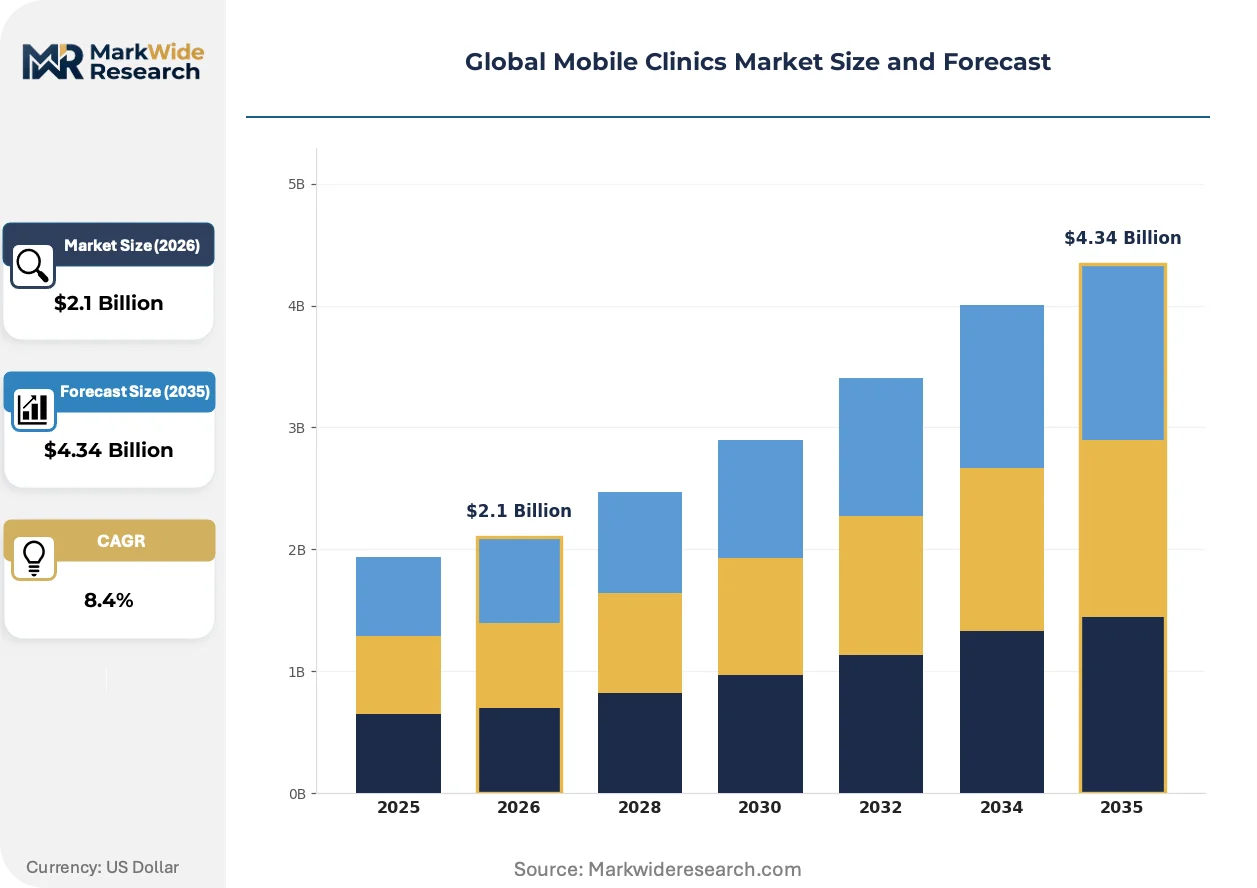
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Care, Diagnostic Services, Dental Care, Vaccination Programs, Maternal Health, Chronic Disease Management Deployment Mode: Van-Based Clinics, Trailer-Based Clinics, Ship-Based Clinics, Bicycle Clinics, Portable Tent Clinics, Bus-Based Clinics Application: Disaster Relief, Remote Area Healthcare, Corporate Wellness, School Health Programs, Community Outreach, Prison Healthcare End User: Government Agencies, Non-Governmental Organizations, Private Corporations, Educational Institutions, Correctional Facilities, Military Units |
| Companies Covered | ADI Mobile Health, Medical Coaches, Matthews Specialty Vehicles, Odulair LLC, LifeLine Mobile, Farber Specialty Vehicles, La Boit Specialty Vehicles, Indicom Buildings, Phoenix Modular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Clinics Market Shifts & Advancements
Telehealth-integrated diagnostics are compressing the care delivery chain while modular vehicle architectures are enabling rapid service reconfiguration. Regulatory harmonization efforts across WHO, FDA, and EU MDR frameworks are reshaping certification economics.
Containerized point-of-care laboratories are decentralizing diagnostic access to populations beyond permanent healthcare infrastructure. National health missions in India and procurement authorities in Kenya are adopting these configurations for tuberculosis and HIV screening programs. The technology is decentralizing clinical reach from urban hospital networks to rural catchment areas previously served only by outreach campaigns.
EU MDR requirements for temporary care sites are elevating documentation burdens for mobile medical device operation. Manufacturers must now maintain technical files spanning multiple jurisdictions with divergent electromagnetic compatibility standards. Diagnostic imaging configurations face the steepest compliance costs, compressing margins for premium van-based units relative to basic primary care setups.
Subscription-based fleet management is replacing outright purchase contracts among municipal health departments and NGO operators. Service bundling that includes maintenance, equipment refresh, and regulatory compliance support is capturing preference in Brazil and South Africa. This shift is most visible in sub-Saharan Africa, where foreign aid-dependent health systems prioritize operational expenditure over capital commitment.
Global Mobile Clinics Market Segmentation
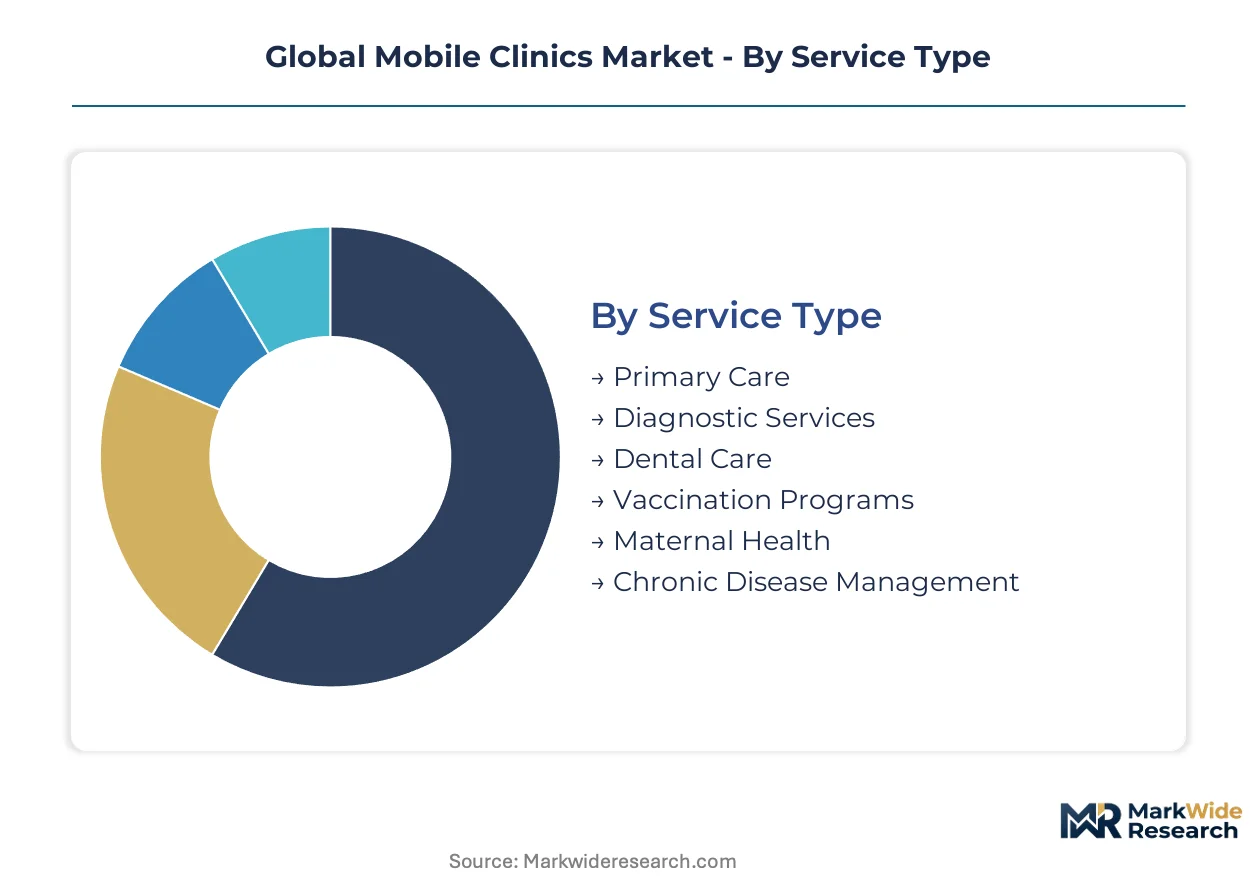
Mobile clinic procurement patterns diverge sharply across service configurations, chassis platforms, and institutional buyers. Upgrade cycles and replacement timelines vary from 5-7 years for van-based primary care units to 12-15 years for trailer-based diagnostic laboratories, creating distinct revenue windows for equipment suppliers and fleet operators.
Service Type:
Replacement cycles drive equipment refresh priorities, with diagnostic configurations demanding shorter upgrade intervals due to imaging technology obsolescence.
- Diagnostic Services:Mobile units integrate radiography, ultrasound, and point-of-care laboratory equipment requiring climate-controlled environments and stabilized electrical systems. India's National Health Mission procures these configurations for district-level tuberculosis screening, while sub-Saharan African health systems prioritize HIV viral load monitoring capabilities. Equipment refresh cycles compress to 5-6 years as imaging modality standards advance.
- Primary Care:Examination rooms with basic diagnostic instruments and pharmaceutical storage dominate municipal health department fleets. Brazilian SUS operators in Amazon basin communities favor these lower-cost configurations for routine consultations. Extended 8-10 year replacement timelines reflect slower equipment obsolescence.
- Dental Care:Compressor-driven operatories with suction systems and sterilization equipment serve school health programs.
- Vaccination Programs:Cold-chain configurations with vaccine refrigeration units deploy for outbreak response and routine immunization.
- Maternal Health:Obstetric examination capabilities with emergency delivery equipment target underserved rural districts.
- Chronic Disease Management:Diabetes and hypertension monitoring stations with telehealth connectivity serve aging populations.
Volume placements concentrate in Primary Care; the faster expansion belongs to Diagnostic Services.
Deployment Mode:
Chassis selection hinges on maneuverability requirements against stationary deployment duration, with cost tiers separating premium specialty platforms from standard commercial van conversions.
- Van-Based Clinics:Modified commercial chassis with reinforced suspensions support diagnostic imaging and surgical equipment loads. Maneuverability advantages dominate urban and semi-urban procurement in India and South Africa. Premium configurations from North American and European chassis suppliers command 40-60% cost premiums over standard conversions.
- Trailer-Based Clinics:Detachable platforms enable stationary deployment exceeding typical mobile rotation cycles. Brazilian Amazon basin communities and Kenyan rural health systems adopt these for semi-permanent clinic establishment. Lower per-unit costs offset transportation infrastructure requirements.
- Bus-Based Clinics:High-capacity platforms serve mass screening campaigns and corporate wellness programs.
- Ship-Based Clinics:Riverine configurations access flood-affected regions and archipelago communities.
- Bicycle Clinics:Ultra-lightweight setups penetrate areas with non-motorized access constraints.
- Portable Tent Clinics:Rapid deployment configurations serve disaster relief and temporary outreach.
Procurement volumes favor Van-Based Clinics; Trailer-Based Clinics are climbing the fastest in emerging market health system expansion.
Application:
Customer workflow requirements determine equipment specifications, with disaster response demanding rapid deployment capabilities versus corporate wellness prioritizing appointment scheduling integration.
- Remote Area Healthcare:Self-contained electrical generation and water purification systems enable operation beyond grid infrastructure. Sub-Saharan African national health systems and India's rural mission programs constitute core demand. WHO modular vehicle standards guide platform interoperability for these deployments.
- Disaster Relief:Rapid-deployment configurations with satellite communications and emergency surgical capabilities serve humanitarian response agencies. Equipment standardization across NGO fleets accelerates interoperability during multi-actor responses.
- Corporate Wellness:Employer-sponsored health screening programs in the US and Germany drive occupational health configurations.
- School Health Programs:Pediatric-optimized examination spaces with vaccination cold storage serve municipal education departments.
- Community Outreach:Religious and civic organization sponsorship supports preventive care access in underserved neighborhoods.
- Prison Healthcare:Security-enhanced configurations with controlled access systems serve correctional health systems.
Contract values peak in Remote Area Healthcare; Disaster Relief applications are gaining share fastest among international development funders.
End User:
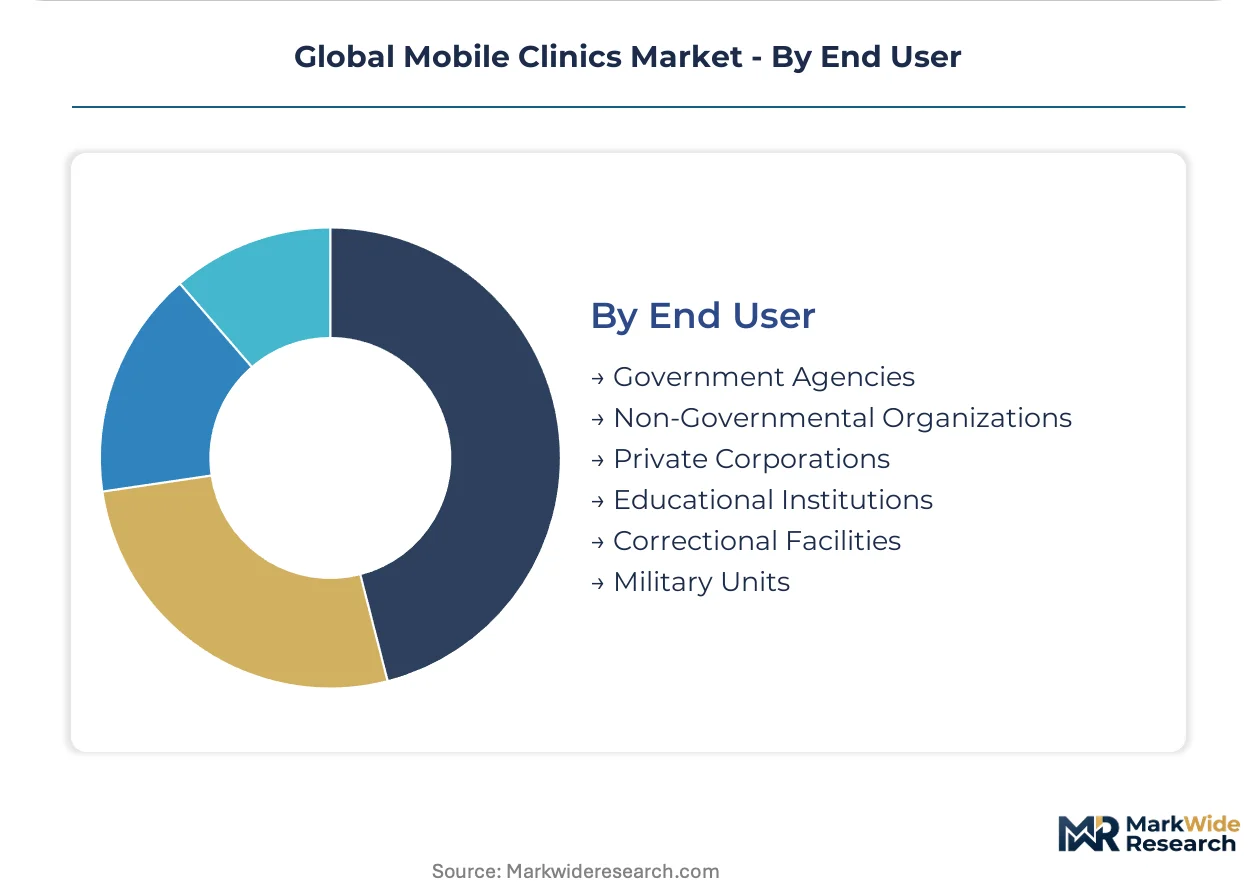
Institutional procurement authority shapes specification requirements, with government tenders emphasizing standardization and NGO buyers prioritizing reconfiguration flexibility.
- Government Agencies:National health missions and municipal health departments drive standardized fleet specifications enabling multi-vendor maintenance. India's federal procurement mandates and Brazil's SUS regional authorities constitute anchor demand. Budget predictability supports 3-5 year fleet expansion planning.
- Non-Governmental Organizations:International development agencies and faith-based health networks prioritize modular interior configurations for service-line flexibility. Subscription-based fleet management models capture preference among foreign aid-dependent operators in sub-Saharan Africa.
- Private Corporations:Occupational health and executive wellness programs drive premium fit-out specifications.
- Educational Institutions:University health systems and school districts procure for student and faculty populations.
- Correctional Facilities:State and federal prison systems require security-compliant access controls.
- Military Units:Field medical configurations with trauma stabilization capabilities serve defense health services.
Procurement scale concentrates in Government Agencies; NGO fleet modernization is expanding most quickly through development finance mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Health Mission procurement corridors and Brazil's SUS expansion zones are concentrating mobile clinic deployment through federal health system mandates rather than private capital flows.
United States
FDA mobile medical device certification timelines shape deployment economics for diagnostic imaging configurations. The IRA's rural health investment provisions accelerate fleet procurement for underserved Appalachian and Southwestern communities. Texas and Arizona municipal health departments anchor van-based contract volumes through telehealth-integrated operating models.
India
Federal procurement mandates for maternal and child health mobile units create predictable demand pipelines across underserved districts. CDSCO point-of-care diagnostic approvals compress equipment integration cycles for tuberculosis and HIV screening programs. Karnataka and Tamil Nadu state health missions drive van-based fleet expansion through national mission funding allocations.
Brazil
SUS regional authorities prioritize trailer-based stationary deployment for Amazon basin communities beyond road infrastructure networks. ANVISA temporary care site regulations govern modular platform specifications for semi-permanent clinic establishment. Pará and Amazonas state procurement offices anchor demand for detachable platforms with extended deployment cycles.
Germany
EU MDR requirements for temporary care sites elevate documentation burdens for onboard diagnostic equipment. KBA specialty vehicle certification protocols govern chassis modifications supporting medical imaging loads. Bavaria and North Rhine-Westphalia municipal health departments pilot subscription-based fleet management for occupational health screening programs.
Kenya
National health system procurement programs accelerate rural fleet deployment for HIV viral load monitoring beyond fixed-facility catchment areas. WHO prequalification protocols for point-of-care diagnostics reduce integration friction between chassis suppliers and equipment manufacturers. Nairobi and Mombasa-based NGO operators anchor containerized laboratory adoption through development finance mechanisms.
Global Mobile Clinics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium diagnostic configurations concentrating around chassis-integrated platforms while primary care units fragment across regional conversion shops. Three archetypes dominate: van-based manufacturing specialists with North American production footprints, modular interior configuration providers serving multi-service deployment contracts, and specialty chassis integrators focusing on imaging equipment stabilization. Capacity expansion and strategic partnerships represent the dominant competitive vectors as operators seek to compress certification timelines across FDA, EU MDR, and WHO prequalification pathways.
Within the specialty chassis integration tier, Matthews Specialty Vehicles occupies a position exemplifying premium platform manufacturing for diagnostic imaging configurations, while Odulair LLC represents modular interior reconfiguration capabilities spanning dental and primary care service lines. ADI Mobile Health anchors the van-based manufacturing archetype through extensive North American operational footprints. These three entities collectively illustrate the segmentation between chassis-centric, interior-modular, and volume-manufacturing competitive positions.
| Leading Market Players |
|---|
| ADI Mobile Health |
| Medical Coaches |
| Matthews Specialty Vehicles |
| Odulair LLC |
| LifeLine Mobile |
| Farber Specialty Vehicles |
| La Boit Specialty Vehicles |
| Indicom Buildings |
| Phoenix Modular |
| Others |
Supply & Pricing Matrix
WHO modular vehicle standards for point-of-care diagnostics are gating qualified chassis supply and premium-tier pricing access for imaging-integrated configurations. Municipal health departments in India and NGO operators in sub-Saharan Africa face extended procurement cycles when sourcing FDA-cleared or EU MDR-compliant platforms.
Pricing Analysis
Short lead-time premiums of 15-25% apply to van-based diagnostic configurations from North American chassis suppliers, while spot inventory of standard primary care conversions trades at negotiated discounts. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified imaging platforms from CDSCO-registered units and unmodified commercial van conversions. Price differentiation rests on electromagnetic compatibility certification grade and after-sales service bundling. Cost compression in economy-tier primary care units is intensifying because Brazilian SUS and Indian state health missions are consolidating purchase volumes. Government tenders exhibit highest price sensitivity; private occupational health operators in Germany and the US demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from Kenya's national health system and India's National Health Mission are mandating multi-supplier qualification for chassis platforms and point-of-care diagnostic modules. Geographic supply concentration centers on the United States for specialty chassis integration, Germany for KBA-certified vehicle modifications, and China for electrical system components and climate control units. Raw material dependencies include medical-grade aluminum alloys for radiation shielding, lithium-ion battery systems for off-grid operation, and composite paneling for interior fit-out. Single-source vulnerability in FDA-cleared imaging equipment creates procurement bottlenecks for diagnostic service configurations. Distribution runs through direct contracts with national health missions, municipal procurement offices, and NGO fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated diagnostics are displacing legacy outreach-based service delivery in OECD markets, compressing replacement cycles for non-connected mobile units.
For Market Incumbents: Deepen backward integration into chassis modification capabilities to reduce dependency on North American and European specialty suppliers facing allocation constraints. Accelerate WHO prequalification pathway investments to defend position against emerging modular platform competitors from Asia-Pacific manufacturing bases. Certification timeline compression represents the critical defensive lever as national health missions in India and Brazil consolidate vendor lists. For New Entrants and Emerging Players: The price-point gap between premium diagnostic configurations and economy primary care units creates entry space for mid-tier telehealth-integrated offerings. Target trailer-based stationary deployment contracts in Brazil's Amazon basin and Kenyan rural health systems, where infrastructure constraints favor detachable platforms over van-based maneuverability. Pursue subscription-based fleet management partnerships with foreign aid-dependent NGO operators as the preferred go-to-market mechanism. For Investors and Strategic Acquirers: FDA mobile medical device certification timeline compression is the leading indicator that regulatory capability is becoming the scarce resource in this market. Long-term viability favors vertically integrated manufacturers with in-house chassis modification, equipment integration, and multi-jurisdiction compliance expertise. Monitor WHO prequalification protocol expansion beyond HIV and tuberculosis screening into maternal health and non-communicable disease categories as the primary inflection signal for platform demand diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | WHO vehicle interoperability guidelines reduce integration friction between chassis suppliers and diagnostic equipment manufacturers. |
| Telehealth Integration Partnership | Reimbursement framework clarity in Germany and the US enables sustainable hybrid mobile-virtual care operating models. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EU MDR, and CDSCO pathways accelerate market access for diagnostic imaging configurations. |
| Subscription Fleet Management Launch | Operational expenditure preference among sub-Saharan African health systems shifts procurement from capital purchase to service contracts. |
| Specialty Chassis Capacity Expansion | Domestic production in India and Brazil reduces lead times and import duty exposure for national health mission tenders. |
Research Methodology
Independent corroboration across chassis manufacturer production data, national health mission procurement disclosures, and point-of-care diagnostic equipment regulatory filings underwrites the qualitative findings in this study. Primary interviews with mobile clinic fleet operators, biomedical equipment engineers, municipal health department procurement officers, and WHO prequalification program administrators were combined with secondary validation from FDA 510(k) databases, EU MDR technical documentation, CDSCO approval registers, and hospital procurement contract repositories. Bottom-up unit deployment estimates and top-down health system expenditure analysis were triangulated to establish market sizing boundaries.
Comparable historical reference periods spanning pre-pandemic baseline, emergency deployment surge, and normalized procurement recovery anchored the forecast window calibration. Segmentation modeling across service type, deployment mode, application, and end user dimensions was executed throughout the projection horizon, with additional granularity applied to chassis platform specifications and diagnostic equipment integration complexity. CAGRs were derived from fitted trend analysis of national health mission budget allocations and fleet replacement cycle patterns. Key forecast inputs included WHO guideline revision timelines, electromagnetic compatibility certification pathway changes, and telehealth reimbursement framework evolution.
Inputs from chassis manufacturers, health system procurement authorities, and diagnostic equipment suppliers were available through the study window; gaps in real-time fleet utilization data and subscription contract pricing introduce uncertainty bands around deployment velocity assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization progress and national health mission funding continuity. Deviation in WHO prequalification protocol expansion scope or major trade restriction imposition on medical-grade vehicle components would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Patient Transportation Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Acute Care Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Global Ambulatory Services Market